
 Manual Bottle Opener Market | 2026-2036
Manual Bottle Opener Market Size, Share, and Industry Trends Forecast 2026-2036
Manual Bottle Opener Market Insights
Artisan metalworking skills in traditional European forging centers is unwinding production bottlenecks for premium manual bottle opener variants. OXO International leverages ergonomic design expertise to sustain brand loyalty across North American hospitality channels. Joseph Joseph anchors its competitive stance through multifunctional product architectures that merge bottle opening with integrated cap-collection features. Boker dominates the pocket-sized segment through German blade-making heritage translated into compact, high-durability tools.
A manual bottle opener is a hand-actuated lever device, typically fabricated from stainless steel, aluminum, or zinc alloy, employing a fulcrum lip to pry crown caps from glass beverage containers with a force-displacement ratio optimized for single-handed operation. Its primary commercial purpose spans hospitality service, retail beverage sales, and consumer home use where electrical power is unavailable or undesired. Pocket-sized and wall-mounted variants command the largest volume pools, while multifunctional and magnetic designs capture expanding margin contributions from gift-shop and e-commerce channels. Stainless steel and brass material grades concentrate in premium positioning, whereas plastic and aluminum serve high-turnover food service chain procurement.
Food-grade material compliance under FDA regulations in the United States and REACH chemical safety frameworks in the European Union shape product standards and market access requirements for imported manual bottle openers. ISO 8442 cutlery and flatware standards additionally govern surface finish and corrosion resistance specifications for stainless steel variants. Stakeholders must monitor evolving state-level extended producer responsibility laws and shifting e-commerce platform certification requirements to anticipate compliance cost trajectories.
Market Dynamics
REACH compliance in the European Union is redirecting material sourcing toward food-grade certified stainless steel, while artisan metalworking clusters in Sheffield and Solingen unwind production bottlenecks for premium variants. This dual pressure of regulatory stringency and craft capacity expansion defines current market restructuring.
Growth Catalysts
- Food-grade certification mandates:FDA regulations in the United States and REACH frameworks in the European Union compel hospitality chains to replace non-compliant zinc-alloy openers with certified stainless steel alternatives.
- Japan's izakaya densification:Pocket-sized and multifunctional designs see concentrated demand from Japan's izakaya and home-bar segments seeking compact, durable service tools.
- Artisan metalworking revival:Traditional forging centers in Sheffield and Solingen restore premium production capacity through heritage craft skills applied to small-batch stainless steel manufacturing.
Market Restraints
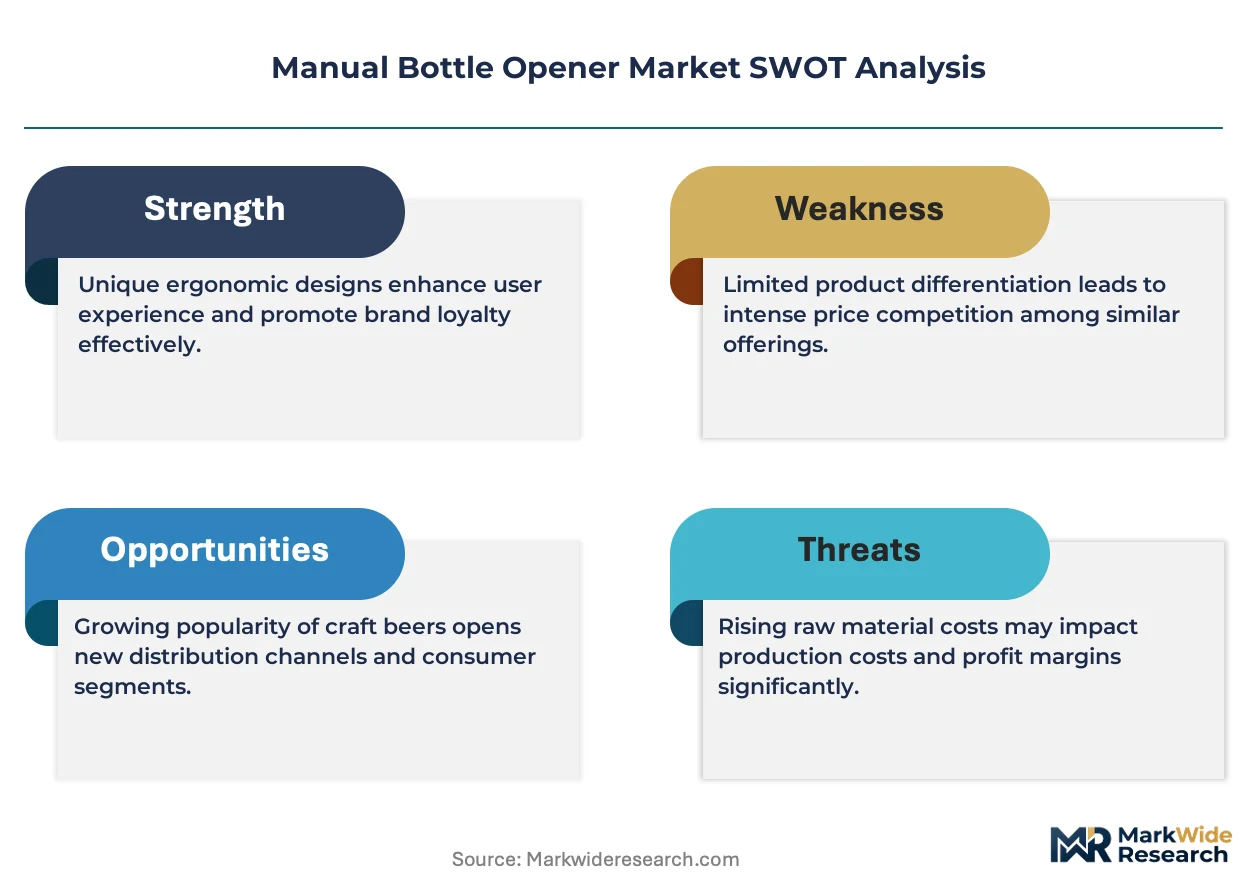
- Nickel price volatility:Stainless steel input costs fluctuate with nickel market swings, compressing margins for mid-tier manufacturers without long-term supply agreements.
- Single-source forging dependency:Premium heat-treatment capabilities concentrate in Solingen and Sheffield, creating geographic supply concentration risk for high-durability variants.
- Electrified alternative substitution:Battery-powered automatic openers threaten wall-mounted and high-volume food service segments where labor cost reduction outweighs manual durability preferences.
Strategic Opportunities
- India's hospitality expansion:Underpenetrated premium barware demand in India's tier-two cities offers white space for food-grade certified manual openers as international hotel chains expand.
- E-commerce platform certification:Amazon and Alibaba marketplace food-contact material verification creates barrier-to-entry advantages for pre-certified suppliers against uncertified competitors.
- Multifunctional convergence:Integration of bottle opening with cap collection, magnetic mounting, and corkscrew functions captures gift-shop margin premiums through utility stacking.
Industry Challenges
- Artisan skill succession gaps:Heat-treatment and precision-forging expertise concentrates among aging craftspeople in Solingen without structured apprenticeship pipelines.
- Extended certification timelines:FDA food-contact notification and EU REACH compliance documentation require 12-18 month lead times, delaying product launches for new market entrants.
- Legacy zinc-alloy inventory stranding:Food service distributors face write-downs on non-compliant stockpiles as chain procurement shifts to certified materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manual Bottle Opener Market |
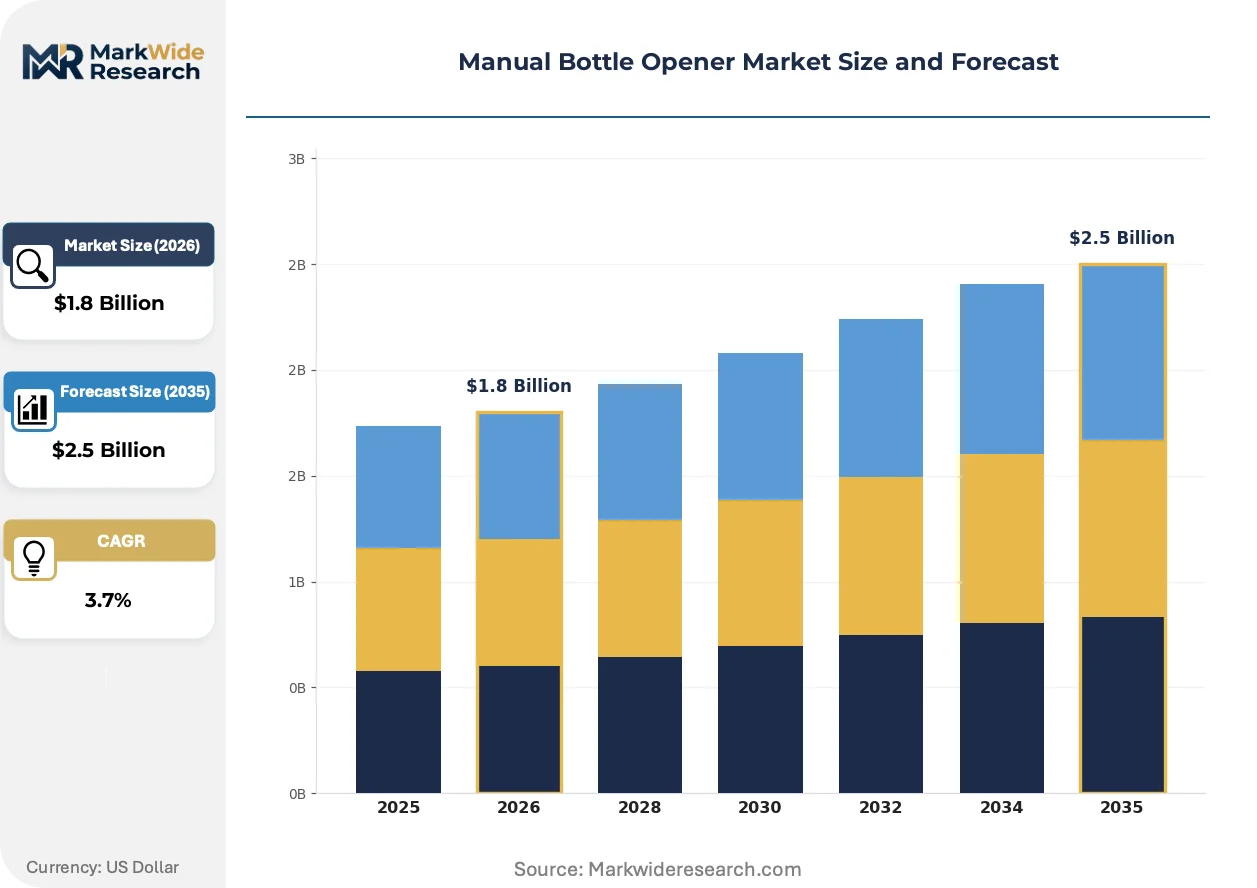
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Mounted, Pocket Sized, Countertop, Multifunctional, Magnetic, Novelty Material: Stainless Steel, Plastic, Aluminum, Wood, Zinc Alloy, Brass Application: Hospitality, Beverage Retailers, Food Service Chains, Catering, Event Management, Home Use Distribution Channel: E-commerce Platforms, Specialty Stores, Supermarkets, Wholesale Suppliers, Direct Sales, Gift Shops |
| Companies Covered | OXO International, Joseph Joseph, Le Creuset, Kohler, BarCraft, Boker, Corkcicle, Godinger, True Fabrications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manual Bottle Opener Market Trends and Innovations
Material science advances and regulatory harmonization are compressing product lifecycles while expanding certified supplier bases. Three distinct vectors reshape competitive positioning: metallurgical substitution, compliance framework evolution, and procurement channel restructuring.
Precision investment casting of 316L marine-grade stainless steel is displacing stamped 304-grade variants in premium positioning. Japanese hospitality buyers and North American craft breweries adopt cast-body openers for corrosion resistance in high-humidity environments. This metallurgical upgrade compresses the viable supplier base to foundries with vacuum casting capability.
REACH Annex XVII restrictions on nickel release rates tighten surface-finish specifications for EU market access. German and French metal finishers invest in electropolishing lines to meet migration limits, raising fixed-cost barriers for uncertified competitors. Wall-mounted variants for commercial kitchens face the steepest compliance cost escalation.
Direct-to-brewery procurement via specialized barware distributors is fragmenting traditional hospitality supply house channels. Craft breweries in the United States and United Kingdom bypass broadline distributors to source custom-branded openers with shorter lead times. This channel shift concentrates volume with vertically integrated metalworkers offering in-house laser engraving and packaging.
Manual Bottle Opener Market Segmentation
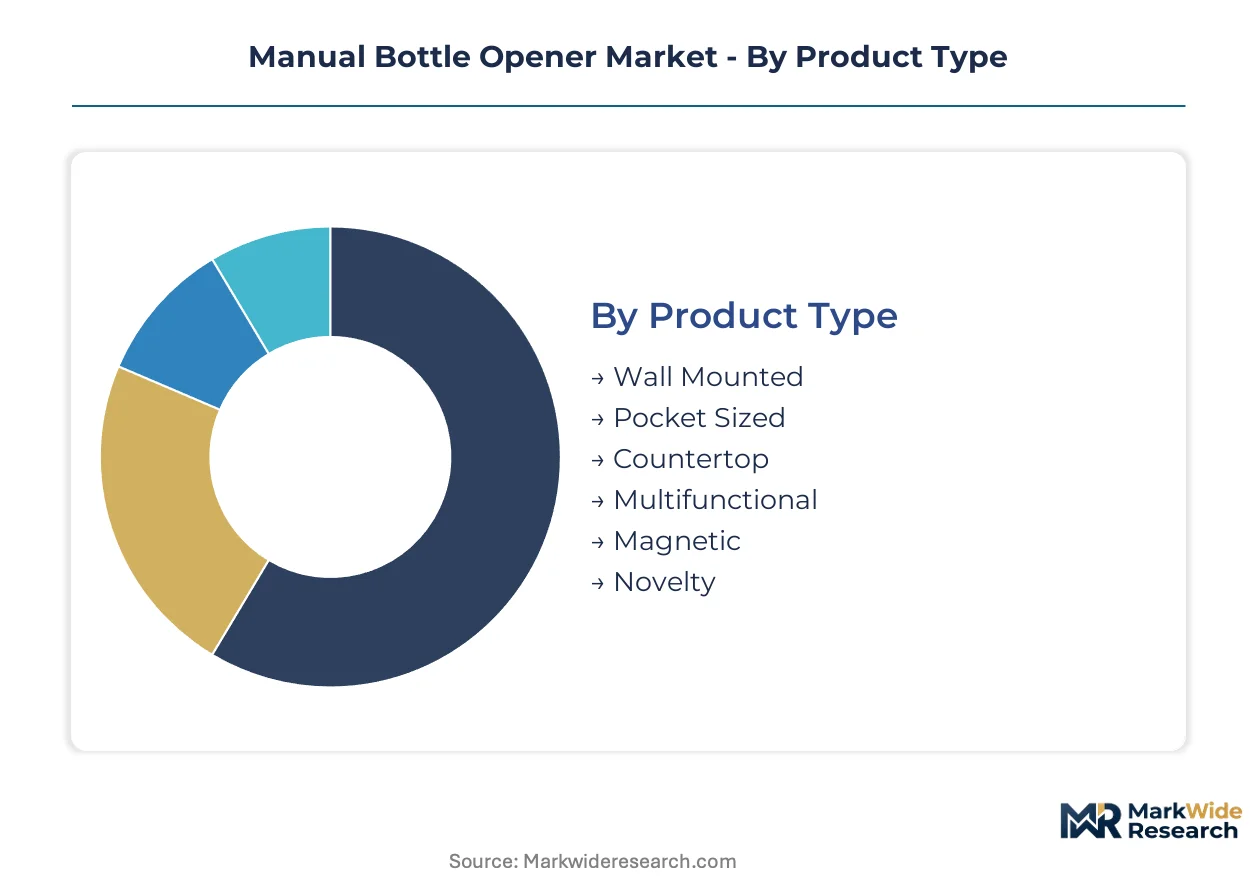
Manual bottle opener procurement patterns diverge sharply between hospitality bulk buyers and individual consumers, with material certification requirements and distribution channel accessibility determining segment viability across regulatory environments.
Product Type:
Wall-mounted and pocket-sized variants dominate export flows to North American hospitality chains, while multifunctional and magnetic designs serve Japan's izakaya densification and European home-bar segments.
- Wall Mounted:Heavy-gauge stainless steel construction with permanent mounting hardware satisfies commercial kitchen durability mandates. North American food service chains specify these for back-of-house standardization under NSF certification requirements.
- Pocket Sized:Compact lever mechanisms under 10cm length target mobile service applications. Japan's izakaya operators and craft brewery taproom staff prioritize these for on-floor portability where electrical outlets remain scarce.
- Countertop:Freestanding weighted bases with integrated cap catch bins suit beverage retail display environments.
- Multifunctional:Corkscrew, foil cutter, and cap-lifter combinations capture gift-shop premiums through utility consolidation.
- Magnetic:Rare-earth magnet integration enables refrigerator mounting and cap adhesion for residential kitchen organization.
- Novelty:Themed shapes and custom-molded designs serve event marketing and promotional merchandise channels.
Wall-mounted variants command the established base. The steepest expansion runs through multifunctional configurations.
Material:
Cost-tier stratification separates food-grade certified stainless steel at premium positioning from aluminum and plastic serving high-turnover procurement in developing hospitality markets.
- Stainless Steel:304 and 316L grades dominate FDA-compliant and REACH-certified procurement for professional kitchens. Sheffield and Solingen forging clusters supply vacuum-cast marine-grade variants to Japanese hospitality buyers seeking corrosion resistance.
- Plastic:ABS and polycarbonate formulations serve single-use event management and budget catering segments where loss rates exceed durability concerns.
- Aluminum:Stamped aircraft-grade alloys balance weight reduction with moderate durability for mid-tier beverage retailers.
- Wood:Hardwood handles with metal inserts target gift-shop and craft brewery direct sales emphasizing tactile aesthetics.
- Zinc Alloy:Die-cast Zamak variants face regulatory phase-out as nickel release rates tighten under EU chemical safety frameworks.
- Brass:Solid and plated variants occupy heritage positioning in UK pub restoration and North American craft cocktail establishments.
Stainless steel anchors the certified premium tier. Zinc alloy faces accelerated displacement from compliance-driven procurement shifts.
Application:
Volume concentration in hospitality and food service chains contrasts with margin-rich fragmentation across catering and event management where customization commands pricing power.
- Hospitality:Hotels, bars, and restaurants specify NSF-listed stainless steel for front-of-house and back-of-house standardization. Procurement runs through broadline distributors with compliance documentation requirements.
- Beverage Retailers:Supermarkets and specialty alcohol retailers utilize countertop and magnetic variants for customer convenience and impulse placement near checkout.
- Food Service Chains:Quick-service and fast-casual operators prioritize aluminum and plastic for cost-controlled replacement cycles.
- Catering:Mobile service applications favor pocket-sized and multifunctional tools for equipment minimization.
- Event Management:Disposable and novelty configurations serve festivals, weddings, and corporate activations with high loss tolerance.
- Home Use:Residential purchasers through e-commerce platforms drive magnetic and multifunctional adoption for kitchen organization.
Hospitality absorbs the highest certified-material volumes. Home use generates the most rapid channel shift toward direct e-commerce procurement.
Distribution Channel:
Platform certification requirements are restructuring access, with Amazon and Alibaba food-contact verification creating barrier-to-entry advantages for pre-certified suppliers against uncertified competitors.
- E-commerce Platforms:Amazon, Alibaba, and specialized barware marketplaces require REACH and FDA documentation for food-contact listings. This filters supplier bases toward vertically integrated metalworkers with in-house compliance teams.
- Specialty Stores:Kitchenware and barware boutiques emphasize tactile evaluation and brand storytelling for premium stainless steel and brass variants.
- Supermarkets:Mass retail placement favors aluminum and plastic at impulse price points near beverage sections.
- Wholesale Suppliers:Broadline hospitality distributors bundle openers with flatware and glassware for contract standardization.
- Direct Sales:Craft breweries and heritage metalworkers bypass intermediaries via brewery taproom and forge-direct channels with custom laser engraving.
- Gift Shops:Museum stores, airport retail, and tourist destinations stock novelty and multifunctional designs for souvenir and travel-gift occasions.
Wholesale suppliers retain the hospitality volume core. E-commerce platforms are gaining share fastest through certification-gated marketplace expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food-contact notification procedures in the United States establish the baseline compliance threshold that shapes procurement standards across multiple geographies. The report maps demand concentration across five countries where hospitality investment, regulatory stringency, and metalworking heritage intersect.
United States
Craft brewery taproom expansion drives demand for wall-mounted and pocket-sized variants with custom laser engraving capabilities. FDA food-contact material verification filters supplier bases toward vertically integrated metalworkers with in-house compliance documentation. Sheffield-forged stainless steel imports serve premium positioning in coastal metropolitan markets.
Germany
REACH Annex XVII nickel release restrictions tighten surface-finish specifications for professional kitchen procurement. Solingen's heat-treatment and precision-forging clusters supply vacuum-cast marine-grade variants to domestic and export hospitality buyers. ECHA compliance documentation requirements extend certification timelines for new market entrants.
Japan
Izakaya densification and home-bar segment growth concentrate demand for pocket-sized and multifunctional designs under 10cm length. METI industrial standards govern surface finish specifications for food-contact metalware. Osaka-based hospitality equipment distributors bypass broadline channels to source corrosion-resistant tools for high-humidity service environments.
United Kingdom
Heritage pub restoration and craft cocktail establishment expansion sustain brass and stainless steel demand in premium positioning. REACH frameworks apply post-Brexit through retained EU law, maintaining chemical safety documentation requirements. Sheffield's artisan metalworking revival restores small-batch production capacity for forged 316L variants.
India
International hotel chain expansion into tier-two cities creates underpenetrated demand for food-grade certified manual openers. FSSAI food-contact material standards are tightening import documentation requirements for hospitality procurement. Maharashtra and Karnataka hospitality clusters drive initial specification trials for NSF-listed stainless steel variants.
Manual Bottle Opener Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the manual bottle opener market. Premium positioning concentrates with heritage metalworkers possessing vacuum casting and precision-forging capabilities, while scale manufacturing clusters in stamped aluminum and plastic serving high-turnover food service procurement. Three archetypes dominate: vertically integrated forge-direct specialists, ergonomic design-focused kitchenware brands, and private-label contract manufacturers. Competitive moves center on backward integration into heat-treatment capacity and geographic expansion through e-commerce platform certification.
Within the heritage-forging tier, Boker anchors German blade-making heritage translated into compact durability tools. OXO International and Joseph Joseph occupy positions on the design-led vector, with the former leveraging ergonomic expertise and the latter anchoring multifunctional product architectures. These three exemplify divergent strategic positions: craft authenticity, user-interface innovation, and utility consolidation respectively.
| Leading Market Players |
|---|
| OXO International |
| Joseph Joseph |
| Le Creuset |
| Kohler |
| BarCraft |
| Boker |
| Corkcicle |
| Godinger |
| True Fabrications |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between North American hospitality chains and Sheffield-based forging houses lock in multi-year supply access while fixing stainless steel input costs against nickel market swings. This contract-structure pattern insulates premium-tier procurement from spot-price volatility while concentrating pricing power with heritage metalworkers possessing vacuum-casting capability.
Pricing Analysis
Geographic price spreads separate EU-certified marine-grade 316L variants from stamped aluminum serving developing-market food service chains. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under FDA and REACH frameworks. Cost compression in mid-tier stamped variants is intensifying because nickel price volatility erodes contract-margin predictability. Food service chains exhibit highest price sensitivity, whereas Japanese izakaya operators prioritize corrosion resistance over unit cost.
Supply Chain Analysis
Sheffield and Solingen anchor premium stainless steel forging capacity, while Chinese stamping clusters supply aluminum and zinc-alloy variants for high-turnover procurement. Raw material flows draw from Indonesian nickel smelters, German cold-rolling mills, and Japanese precision-grinding equipment suppliers. Single-source vulnerability concentrates in Solingen's heat-treatment capacity for marine-grade durability certification. Distribution runs through broadline hospitality suppliers for volume accounts and direct-to-brewery channels for custom-branded configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated North American hospitality chains and fragmented craft brewery networks, fragmenting traditional distributor intermediation. This consolidation dynamic rewards suppliers with direct-channel capability and compliance documentation infrastructure.
For Market Incumbents: Shield premium positioning by securing captive heat-treatment capacity in Solingen or Sheffield before artisan skill succession gaps widen. Deepen backward integration into vacuum-casting operations to defend margin position against nickel price volatility. Accelerate FDA and REACH certification investment to exploit e-commerce platform verification barriers.
For New Entrants and Emerging Players: Lead with India's tier-two city hospitality expansion as the most penetrable white-space geography, where international hotel chains lack established barware suppliers. Target multifunctional product architectures combining cap collection and magnetic mounting to capture gift-shop margin premiums. Deploy direct-to-brewery go-to-market positioning with in-house laser engraving capability.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated metalworkers with in-house compliance teams and forge-direct distribution reach. Long-term viability across the projection horizon hinges on regulatory certification moats rather than scale manufacturing. Monitor ECHA nickel-release restriction enforcement as the critical inflection signal for premium-tier supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment Capacity | Captive Solingen forging expertise defends premium-tier positioning against artisan skill gaps. |
| REACH and FDA Certification Investment | Pre-certified documentation creates Amazon and Alibaba marketplace barrier-to-entry advantages. |
| Direct-to-Brewery Channel Expansion | Bypassing broadline distributors captures craft brewery custom-engraving and shorter-lead-time demand. |
| Multifunctional Product Architecture Development | Utility stacking with cap collection and magnetic mounting captures gift-shop margin premiums. |
| India Tier-Two City Distribution Buildout | International hotel chain expansion in Maharashtra and Karnataka creates underpenetrated certified-material demand. |
Research Methodology
Cross-validation between primary interviews with hospitality procurement directors and secondary customs trade data anchors the qualitative findings. Conversations with Sheffield forging house operators, Solingen heat-treatment specialists, Japanese izakaya equipment buyers, and Indian FSSAI compliance officers generated operational insight. Secondary validation drew from FDA food-contact notification databases, ECHA REACH Annex XVII filings, METI industrial standards documentation, and hospitality distributor SEC disclosures. Bottom-up volume triangulation against top-down macroeconomic elasticity checks ensured forecast robustness.
Sensitivity analysis across nickel price scenarios, certification timeline delays, and e-commerce platform policy shifts tested forecast resilience. Segmentation modeling spanned product type, material grade, application end-use, and distribution channel dimensions across the projection horizon. CAGRs were derived from elasticity-adjusted volume projections and price-level assumptions. Forecast inputs incorporated REACH nickel-release migration limits and FSSAI import documentation tightening trajectories.
The analysis sits within stated boundaries; outcomes outside sustained artisan metalworking skill transmission or abrupt REACH enforcement acceleration would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and nickel market volatility patterns. Recalibration cycles align with material shifts in regulatory enforcement intensity and e-commerce platform verification protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Commercial Locker Market
Household Items
Washing Capsules Market
Household Items
North America Water Purifier Market
Household Items
Facial Tissue Market
Household Items
United States Smart Shower Market
Household Items
Brush Cover Market
Household Items
Domestic Sauna Heaters Market
Household Items
Plastic Carafe Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Mason Jars and Canning Supplies Market
Household Items
Drinkware Accessories Market
Household Items
UK Digital Showers Market
Household Items
Air Mattress Market
Household Items
India Cookware Market
Household Items
Washing Machine Cleaner Market