
 United States Smart Shower Market | 2026-2036
United States Smart Shower Market Size, Share, and Industry Trends Forecast 2026-2036
United States Smart Shower Market Insights
Multi-source component procurement is rebalancing toward vertically integrated domestic manufacturing as tariff exposure on Asian electronics escalates. Kohler Co. anchors Midwest production capacity with captive thermostatic valve machining and ceramic disc manufacturing. Moen Incorporated leverages its Great Lakes distribution network to control contractor channel access. TOTO LTD competes through R&D intensity in sensor-activated flow systems, while LIXIL Corporation sustains design-led positioning through its American Standard portfolio.
United States Smart Shower systems integrate digital valve controllers, connected thermostatic mixing, and user-preference memory to deliver precise temperature management and consumption tracking for residential and commercial wet spaces. These assemblies typically incorporate ceramic disc cartridges rated for 500,000 cycles, pressure-balancing spools, and IP65-rated electronic enclosures to survive sustained humidity exposure. Digital Showers lead product type revenue given their higher average selling prices and integration complexity, while Voice Control technology grows fastest as Matter protocol standardization reduces interoperability friction. Residential Customers dominate end user volume, though Hospitality Industry deployments command superior margins through bulk specification and brand-standard compliance requirements.
EPA WaterSense labeling shapes product development priorities by certifying flow rates below 2.0 gallons per minute, while DOE appliance efficiency standards mandate minimum performance thresholds that exclude low-cost imports. California Title 20 and 24 building codes enforce the nation's strictest water-fixture specifications, effectively pre-qualifying products for other state adoptions. Stakeholders must monitor CPSC electrical safety rulings on bathroom-connected IoT devices and state-level net-metering changes that affect heat-pump water heater pairing economics.
Market Dynamics
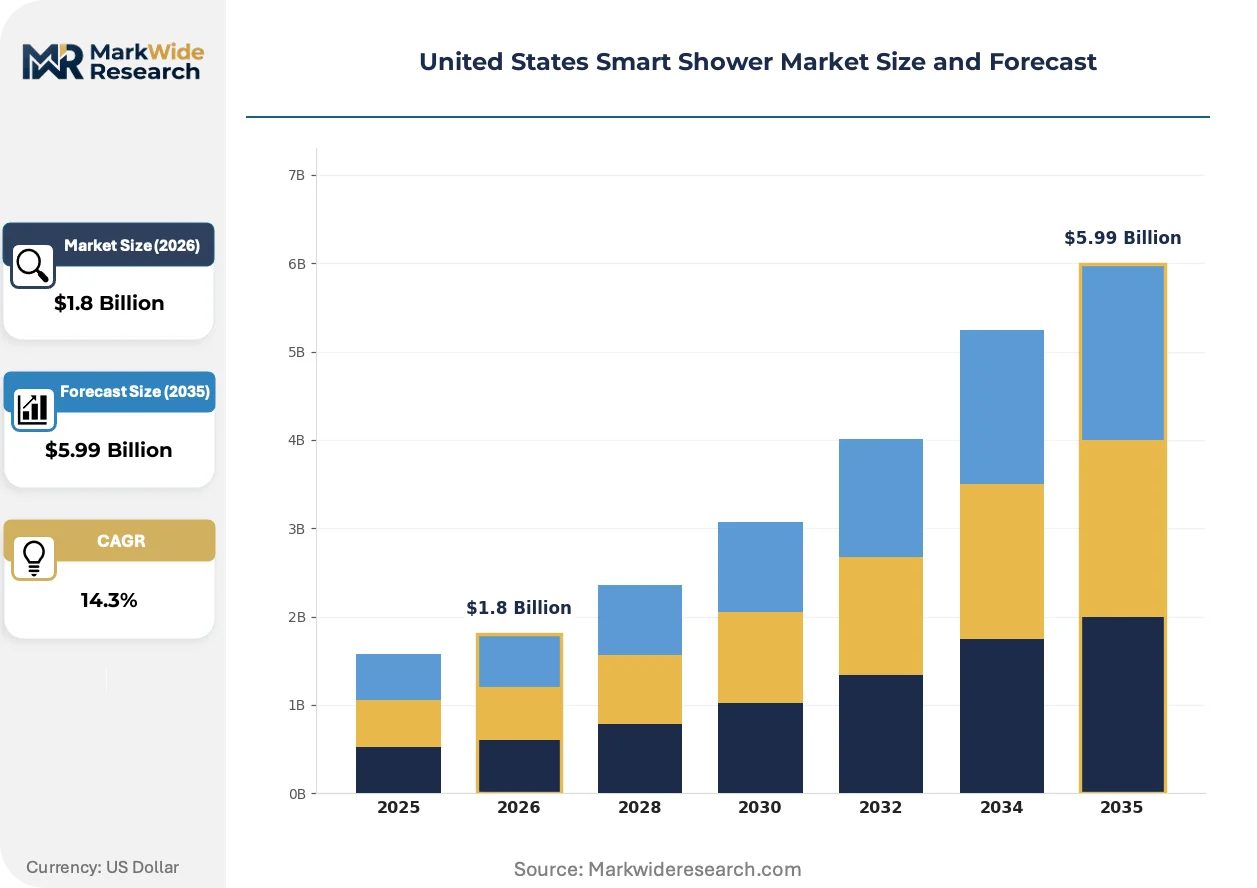
Water conservation mandates and connected-home specifications are converging to compress replacement cycles in residential construction. EPA WaterSense certification and state-level building codes now function as gatekeepers for market access, while tariff exposure on Asian electronics accelerates domestic manufacturing investment.
Growth Catalysts
- EPA WaterSense Certification:Flow-rate requirements below 2.0 gallons per minute create product differentiation that favors engineered systems over commodity fixtures.
- California Title 20 and 24:These building codes enforce the strictest water-fixture specifications in the nation, effectively pre-qualifying compliant products for adoption in other drought-prone states.
- Utility Rebate Programs:Municipal water authorities in Texas and Florida subsidize upgrade costs, accelerating residential retrofit decisions in concentrated upgrade corridors.
Market Restraints
- Semiconductor Supply Concentration:Dependence on Asian-sourced microcontrollers for digital valve controllers exposes manufacturers to tariff volatility and logistics disruption.
- Installation Skill Requirements:Connected thermostatic systems demand electrical and plumbing competency that standard contractor networks often lack.
- Heat-Pump Water Heater Pairing Economics:State-level net-metering changes alter the total cost of ownership calculation for integrated hot-water systems.
Strategic Opportunities
- Hospitality Industry Specifications:Bulk procurement for brand-standard compliance offers superior margins compared to fragmented residential sales.
- Matter Protocol Standardization:Interoperability friction reduction enables voice-control integration that expands addressable market beyond early adopters.
- Florida Coastal Markets:Hurricane-resistant construction codes and salt-air corrosion concerns create demand for IP65-rated electronic enclosures in high-value replacement cycles.
Industry Challenges
- CPSC Electrical Safety Rulings:Evolving standards for bathroom-connected IoT devices require continuous design iteration and testing investment.
- Certification Timeline Compression:Multiple overlapping state and federal efficiency programs demand parallel compliance tracks that strain product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Smart Shower Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.99 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Showers, Smart Controls, Thermostatic Showers, Eco-Friendly Showers Technology: Wi-Fi Enabled, Bluetooth Connectivity, Mobile App Integration, Voice Control End User: Residential Customers, Hospitality Industry, Healthcare Facilities, Commercial Spaces Feature: Water Usage Monitoring, Temperature Regulation, Pre-Set Preferences, Remote Access |
| Companies Covered | LIXIL Corporation, WaterHawk (LTE Water Products), Roca Sanitario, S.A., Aqualisa, Dornbracht AG & Co. KG, TOTO LTD, Kohler Co., Jaquar, Moen Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Smart Shower Market Trends and Innovations
Digital infrastructure is penetrating wet-space environments through sensor-activated flow systems and user-preference memory. Three developments are restructuring how temperature management and consumption tracking deliver value to residential and commercial buyers.
Sensor-activated flow systems are integrating ceramic disc cartridges rated for 500,000 cycles with pressure-balancing spools to deliver precise temperature management. Luxury residential builders specify these assemblies as standard in new construction, compressing the addressable market for basic thermostatic alternatives. The technology is integrating digital valve controllers with connected-home platforms, enabling remote monitoring that shifts maintenance from reactive to predictive.
California Title 20 and 24 building codes are mandating flow-rate performance thresholds that exclude low-cost imports from the state's supply base. This regulatory architecture creates a compliance moat that domestic manufacturers exploit to defend margin position. Products certified under these codes gain automatic qualification for utility rebate programs in Texas and Florida, amplifying their competitive advantage.
Builder procurement preferences are consolidating around connected-home specifications that bundle smart shower systems with whole-house automation. Standard tract-home developers lag this shift, creating a bifurcation between premium new construction and retrofit replacement demand. The divergence is most visible in California's luxury residential corridors, where specification compliance has become a non-negotiable bidding requirement.
United States Smart Shower Market Segmentation
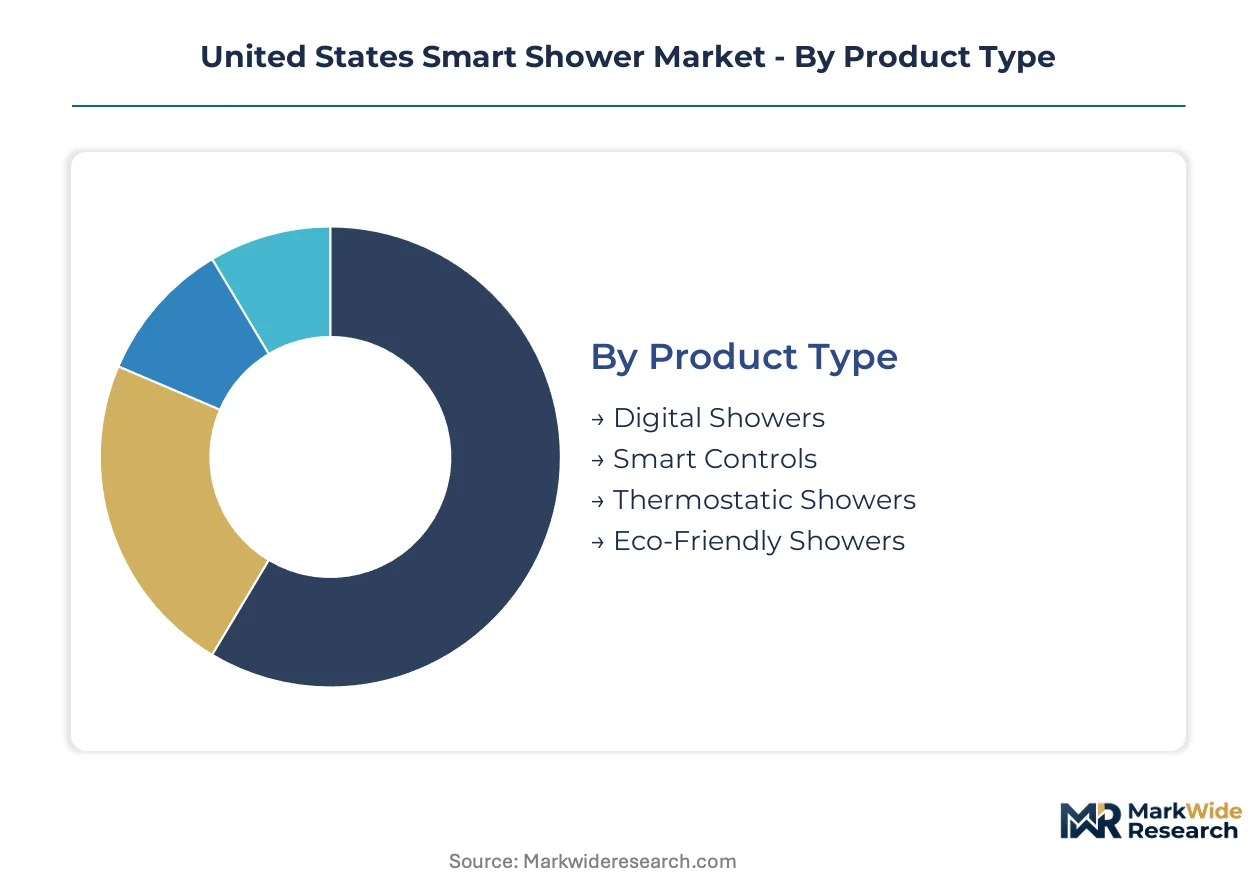
Smart shower procurement patterns diverge sharply across installation contexts, with capital requirements and regulatory exposure determining which configurations dominate specific channels. Understanding these segment boundaries clarifies where technology investment translates into sustainable margin capture versus commodity price competition.
Product Type:
Capital intensity varies dramatically across these four configurations, with electronic integration depth driving upfront engineering investment and certification burden.
- Digital Showers:These systems incorporate ceramic disc cartridges rated for 500,000 cycles alongside IP65-rated electronic enclosures that survive sustained humidity exposure. Demand concentrates in California luxury residential corridors where Title 24 compliance functions as a non-negotiable bidding requirement for new construction.
- Smart Controls:Modular retrofit units that upgrade existing thermostatic hardware through add-on valve controllers and connected interfaces. Texas and Florida utility rebate programs accelerate residential retrofit decisions in concentrated upgrade corridors where full system replacement proves cost-prohibitive.
- Thermostatic Showers:Pressure-balancing spool assemblies with mechanical temperature regulation that predate electronic integration. Builder-grade tract housing in drought-prone jurisdictions specifies these for baseline WaterSense compliance without connectivity premiums.
- Eco-Friendly Showers:Flow-restricted hardware engineered explicitly for sub-2.0 gallons-per-minute certification thresholds. Municipal water authority procurement in Arizona and Nevada favors these for public facility retrofits facing conservation mandates.
Digital Showers absorb the bulk of installed capacity; Smart Controls is expanding most quickly as retrofit economics improve.
Technology:
Connectivity protocol choices determine interoperability scope and installation complexity, with standardization efforts reshaping competitive moats across the vendor base.
- Wi-Fi Enabled:Full cloud-connected architectures supporting remote monitoring and predictive maintenance alerts. Hospitality Industry bulk specifications in Florida coastal markets demand these for brand-standard compliance across property portfolios.
- Bluetooth Connectivity:Local-device pairing without internet dependency, reducing cybersecurity exposure and installation support burden. Healthcare Facilities specify these for patient-room deployments where network isolation protocols restrict external connectivity.
- Mobile App Integration:Smartphone-based preference memory and usage analytics that shift maintenance from reactive to predictive. Residential Customers in tech-forward urban clusters adopt these as entry points to whole-home automation ecosystems.
- Voice Control:Matter protocol standardization reduces interoperability friction, expanding addressable market beyond early adopters into mainstream residential replacement cycles.
Wi-Fi Enabled commands the dominant share of commercial specification; Voice Control is climbing the fastest as protocol fragmentation resolves.
End User:
Customer-type economics govern margin structure, with fragmented residential volume trading off against concentrated hospitality purchasing power.
- Residential Customers:Fragmented upgrade decisions driven by utility rebate timing and replacement cycle compression. California, Texas, and Florida concentrate demand where building code stringency and subsidy programs align.
- Hospitality Industry:Bulk procurement for brand-standard compliance offers superior margins compared to fragmented residential sales. National hotel chains specify connected thermostatic systems as standard in new construction and renovation cycles.
- Healthcare Facilities:Infection-control protocols and patient-safety regulations drive specification toward sensor-activated flow systems with minimal touch surfaces. Long-term care operators in water-stressed states face dual pressure from conservation mandates and clinical compliance.
- Commercial Spaces:Corporate wellness amenities and gym operators deploy consumption-tracking hardware to align with sustainability reporting requirements and tenant experience benchmarks.
Residential Customers generate the volume base; Hospitality Industry captures the steepest expansion trajectory through specification consolidation.
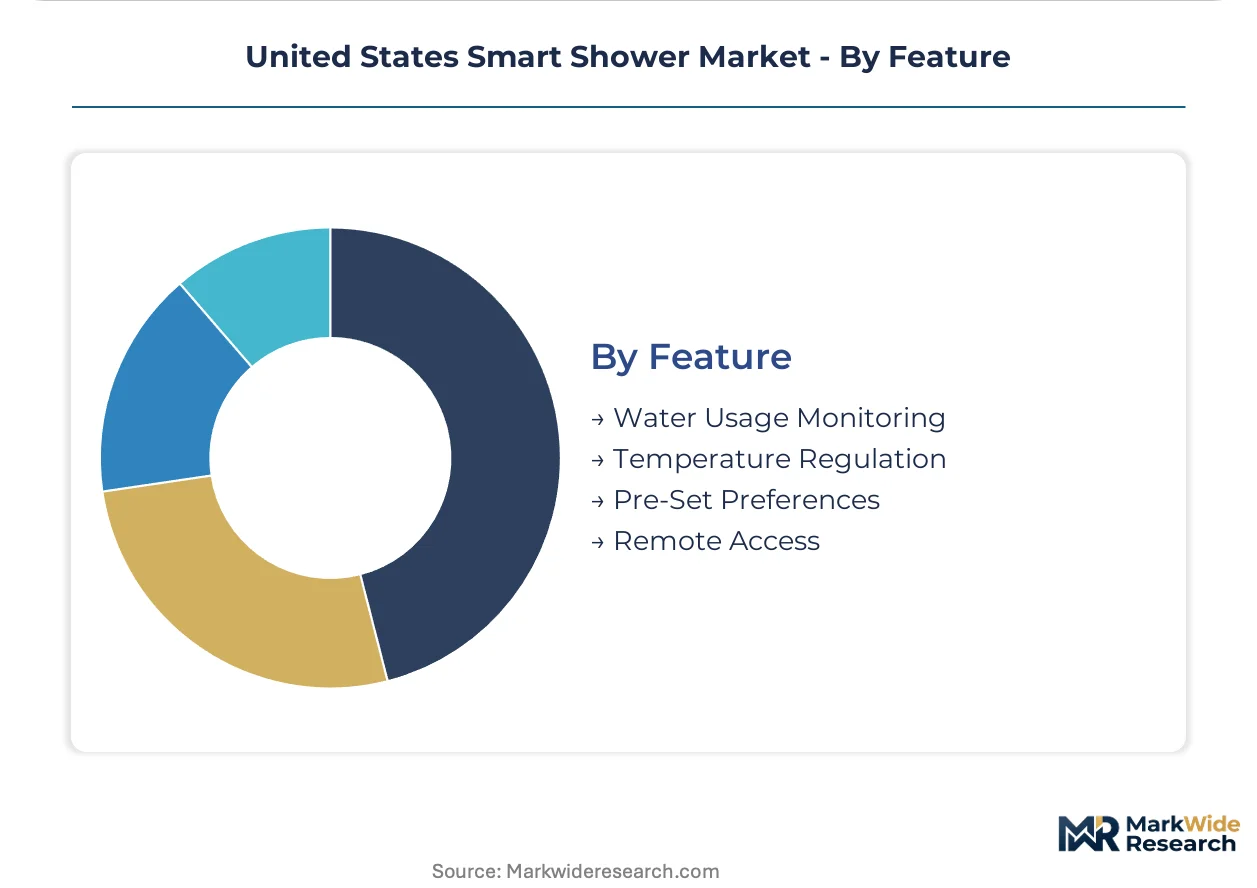
Feature:
Functional differentiation tracks regulatory pressure and user-control preferences, with monitoring capabilities increasingly table stakes for market access.
- Water Usage Monitoring:Real-time flow measurement and historical consumption analytics that satisfy EPA WaterSense certification requirements. Drought-prone jurisdictions mandate these capabilities for rebate eligibility.
- Temperature Regulation:Precise thermostatic mixing with scald-prevention thresholds that address CPSC electrical safety rulings on bathroom-connected IoT devices. Healthcare and hospitality specifications treat this as non-negotiable liability protection.
- Pre-Set Preferences:User-profile memory storing individual temperature and flow combinations for multi-occupant households. Luxury residential builders bundle these with whole-house automation platforms.
- Remote Access:Cloud-based valve control enabling pre-heating and vacation-mode shutdown that pairs with heat-pump water heater economics in net-metering jurisdictions.
Water Usage Monitoring anchors regulatory compliance; Remote Access is gaining share fastest as heat-pump pairing economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ceramic disc cartridge manufacturing clusters in the Midwest anchor domestic production capacity for thermostatic valve components. Water-stressed coastal and Sun Belt states concentrate retrofit demand where conservation mandates intersect with utility rebate programs.
California
Luxury residential builders in Los Angeles and San Francisco corridors specify connected thermostatic systems as standard for new construction. Title 20 and Title 24 building codes enforce flow-rate thresholds below 2.0 gallons per minute that exclude low-cost imports. Silicon Valley tech-forward households drive mobile app integration adoption as entry points to whole-home automation ecosystems.
Texas
Municipal water authorities in Dallas-Fort Worth and Houston subsidize smart shower upgrades through concentrated rebate corridors. State-level plumbing codes incorporate EPA WaterSense certification as a baseline for residential permit approval. Gulf Coast hurricane-resistant construction standards in Houston metro create demand for IP65-rated electronic enclosures.
Florida
Hospitality industry bulk specifications in Miami and Orlando command superior margins through brand-standard compliance requirements. Salt-air corrosion concerns in coastal markets accelerate replacement cycles for humidity-resistant valve assemblies. State building codes align with California Title 24 pre-qualification, enabling cross-certified products to capture utility incentives.
Illinois
Midwest distribution networks centered on Chicago control contractor channel access for thermostatic hardware procurement. Great Lakes manufacturing heritage supports captive ceramic disc machining and pressure-balancing spool production. Cold-climate heat-pump water heater pairing economics shift total cost calculations for integrated hot-water systems.
Arizona
Municipal water authority procurement in Phoenix and Tucson favors eco-friendly showers for public facility retrofits facing severe conservation mandates. Colorado River shortage declarations compress replacement cycles for flow-restricted fixtures in multi-family housing. Desert climate conditions stress-test electronic enclosure durability, favoring domestic suppliers with regional service infrastructure.
United States Smart Shower Market Competitive Landscape
Capacity expansion dominates the current landscape as tariff exposure on Asian-sourced microcontrollers accelerates domestic manufacturing investment. The vendor base organizes around three strategic archetypes: vertically integrated fixture manufacturers with captive valve machining, specialty electronics suppliers focused on sensor-activated flow systems, and global sanitation conglomerates leveraging design-led portfolio positioning. M&A activity and strategic partnerships concentrate on securing thermostatic cartridge supply chains and Matter protocol certification capabilities.
Within the vertically integrated tier, Kohler Co. and Moen Incorporated anchor Midwest production capacity through captive thermostatic valve operations. TOTO LTD exemplifies R&D-intensive positioning in sensor-activated flow systems. These three manufacturers represent distinct competitive vectors: Great Lakes distribution control, ceramic disc manufacturing depth, and digital infrastructure integration respectively.
| Leading Market Players |
|---|
| LIXIL Corporation |
| WaterHawk (LTE Water Products) |
| Roca Sanitario, S.A. |
| Aqualisa |
| Dornbracht AG & Co. KG |
| TOTO LTD |
| Kohler Co. |
| Jaquar |
| Moen Incorporated |
| Others |
Pricing and Supply Chain Analysis
Ceramic disc cartridge costs cascade through three distinct pricing tiers as captive Midwest machining capacity anchors premium positioning while Asian-sourced microcontroller exposure compresses margins at the entry level. EPA WaterSense certification functions as a quality gate that separates bundled installation-and-warranty packages from unbundled commodity hardware.
Pricing Analysis
Warranty and service bundling separates premium digital shower systems from stripped-down thermostatic alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and installation complexity, with California Title 24 compliance commanding substantial premiums. Pricing pressure stems from semiconductor cost volatility in Asian supply chains. Residential retrofit buyers exhibit highest price sensitivity; hospitality bulk procurement shows lowest.
Supply Chain Analysis
Dual-sourcing requirements for thermostatic valve components mandate domestic and Asian supplier qualification to mitigate tariff exposure. Manufacturing draws from United States, China, and Taiwan for ceramic discs, pressure-balancing spools, and microcontroller assemblies. Single-source vulnerability concentrates in sensor-activated flow system electronics. Distribution runs through Great Lakes contractor networks and direct hospitality channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EPA WaterSense certification timelines and state-level code compliance strain development resources, forcing sub-scale players toward exit or acquisition.
For Market Incumbents: Deploy captive thermostatic valve machining to defend margin position against tariff-exposed electronics suppliers. Accelerate Matter protocol certification investment to capture voice-control specification share. Counter emerging specialty electronics entrants through backward integration into sensor-activated flow system R&D. For New Entrants and Emerging Players: Enter via Texas and Florida utility rebate corridors where concentrated upgrade demand outpaces incumbent service capacity. Target healthcare facility sensor-activated specifications where infection-control protocols create procurement urgency. Pursue direct-to-contractor distribution bypassing established Great Lakes channel control. For Investors and Strategic Acquirers: Matter protocol certification announcements from mid-tier manufacturers are the leading indicator that interoperability friction reduction is unlocking mainstream residential replacement demand. Five-to-ten year viability favors vertically integrated fixture manufacturers with captive ceramic disc capacity over pure-play electronics suppliers. Monitor CPSC electrical safety ruling timelines as inflection signals for compliance investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| EPA WaterSense Certification Investment | Qualifies products for California Title 20 and Texas utility rebate programs simultaneously. |
| Captive Thermostatic Valve Machining | Insulates margin structure from tariff exposure on Asian-sourced electronic controllers. |
| Matter Protocol Integration | Enables voice-control specification capture in hospitality brand-standard compliance cycles. |
| Healthcare Channel Partnership Development | Opens sensor-activated flow system procurement governed by infection-control protocols. |
| Great Lakes Distribution Network Expansion | Controls contractor channel access for new construction specification decisions. |
Research Methodology
Multi-period observation of EPA certification timelines, state building code adoptions, and utility rebate program expansions anchored the trend analysis, supplemented by interviews with plumbing contractors, hospitality procurement directors, ceramic disc manufacturing engineers, and municipal water authority officials. Secondary validation drew from DOE appliance efficiency standard filings, California Energy Commission Title 24 documentation, EPA WaterSense product databases, and customs import records. Bottom-up channel volume estimates triangulated against top-down construction permit data.
Segment-weighting applied product type, technology protocol, end-user category, and feature set as primary dimensions across the projection horizon. CAGRs derived from installed base replacement cycle compression and new construction specification penetration curves. Forecast inputs incorporated heat-pump water heater pairing economics and state-level net-metering policy trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or accelerated CPSC electrical safety rulings. Deviation in California Title 24 amendment timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Porcelain Tableware Market
Household Items
Smart Toilet Market
Household Items
Middle East and Africa Air Purifier Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Coffin and Cremation Urn Market
Household Items
Brazil Cookware Market
Household Items
Global Aluminum Cookware Market
Household Items
Germany Digital Showers Market
Household Items
Luxury Massage Chair Market
Household Items
Smart Memory Foam Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
Trash Can Market
Household Items
Hands-Free Faucet Market
Household Items
Silicone Soap Mold Market
Household Items
Gas Hobs Market
Household Items
Party Balloon Market