
 Drinkware Accessories Market | 2026-2036
Drinkware Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Drinkware Accessories Market Foresight
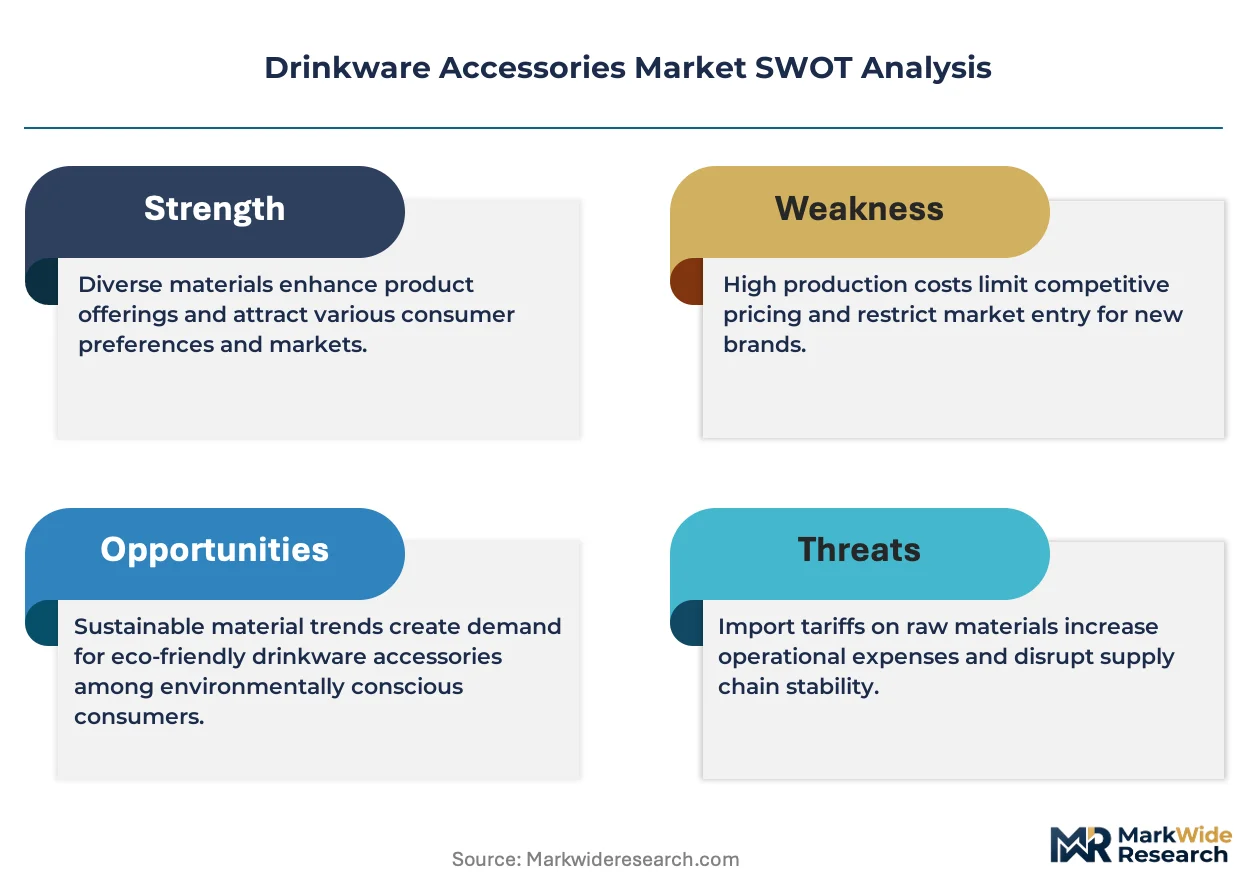
Asset-light leasing models for injection-molding equipment is narrowing the capital barrier for new entrants in drinkware accessories manufacturing. Stanley leverages its vertical integration to control stainless steel lid quality from raw material through finishing. Hydro Flask anchors its position through R&D intensity in vacuum-insulated sleeve technology. Yeti Holdings Inc. competes by dominating the premium replacement lid segment across North American specialty retail channels.
Drinkware accessories encompass supplementary components—straws, lids, sleeves, and cleaning brushes—designed to enhance, protect, or maintain portable beverage containers, typically fabricated from silicone, stainless steel, bamboo, or food-grade plastic through injection molding, thermoforming, or CNC machining processes. These items serve commercial and consumer functions including thermal insulation, spill prevention, hygiene maintenance, and brand customization. Stainless steel lids and silicone straws capture the dominant margin pools due to durability premiums and repeat purchase frequency. Bamboo cleaning brushes represent the fastest-expanding material segment as sustainability preferences intensify among home users and outdoor enthusiasts. Plastic sleeves retain volume leadership in supermarket channels despite regulatory pressure on petroleum-based polymers.
The EU Single-Use Plastics Directive and REACH chemical standards constrain plastic straw and lid formulations across European markets, redirecting procurement toward certified silicone and bamboo alternatives. The FDA's food-contact substance regulations in the United States govern migration limits for lid gaskets and straw coatings, elevating compliance costs for cross-border suppliers. China's GB standards for food-contact materials shape export qualification requirements for Asian manufacturers serving Western buyers. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification timelines to secure shelf placement in regulated channels.
Market Dynamics
Material substitution mandates under the EU Single-Use Plastics Directive are compressing petroleum-based polymer demand while accelerating silicone and bamboo certification pipelines across European supply chains.
Growth Catalysts
- REACH chemical standards:Migration testing protocols for food-contact silicone are creating certified supplier scarcity that locks in premium pricing for compliant lid gasket manufacturers.
- Outdoor recreation equipment buyers:Camping and hiking enthusiasts are expanding replacement straw purchases toward multi-pack stainless steel sets with custom carrying cases.
- Injection-molding equipment leasing:Asset-light production models are lowering entry barriers for regional specialists serving supermarket private-label sleeve contracts.
Market Restraints
- Stainless steel feedstock volatility:Nickel and chromium price swings from Indonesian and South African supply concentration compress lid margin buffers for mid-tier fabricators.
- GB standards compliance costs:China's food-contact material export certifications impose 12-18 month qualification timelines that freeze out unqualified Asian contract manufacturers from Western retail procurement.
- Bamboo fiber substitution ceiling:Natural material moisture absorption limits prevent brush filament applications beyond narrow-neck bottle cleaning, capping segment expansion.
Strategic Opportunities
- Extended Producer Responsibility frameworks:France's AGEC law and Germany's VerpackG are mandating take-back infrastructure that rewards accessory producers with closed-loop material recovery systems.
- Vacuum-insulated sleeve convergence:Integration of aerogel layers with traditional neoprene is opening premium thermal performance tiers for specialty coffee retail channels.
- Direct-to-consumer brush subscriptions:Replenishment models for biodegradable cleaning heads are capturing recurring revenue from sustainability-focused household segments.
Industry Challenges
- Multi-jurisdiction certification parallelism:Simultaneous FDA, EFSA, and GB standard compliance requires redundant testing protocols that strain SME quality assurance staffing.
- Legacy ERP integration with traceability systems:Batch-level material origin tracking for EUDR deforestation compliance demands middleware investments that delay digital transformation roadmaps.
- Silicone formulation IP fragmentation:Patent thickets around platinum-cured versus peroxide-cured elastomers are licensing complexity that slows new entrant product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drinkware Accessories Market |
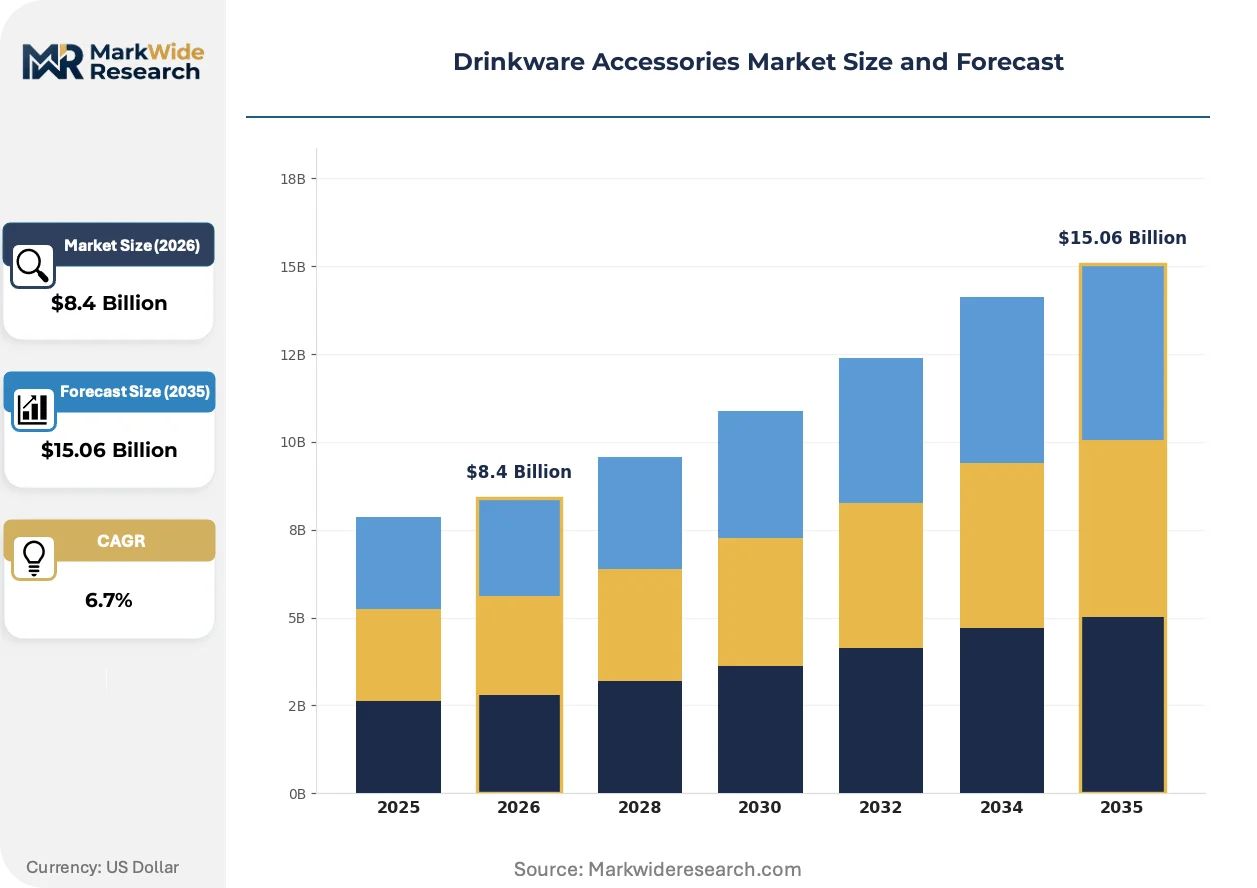
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straw, Lid, Sleeve, Cleaning Brush Material: Silicone, Stainless Steel, Bamboo, Plastic End User: Home Users, Outdoor Enthusiasts, Athletes, Event Planners Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Stanley, CamelBak, Contigo, Newell Brands Inc., Klean Kanteen, Hydro Flask, Thermos LLC, Libbey Inc., Yeti Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drinkware Accessories Market Shifts & Advancements
Active material science development and regulatory chemistry restrictions are compressing traditional petroleum-based formulations while elevating bio-based and performance-engineered alternatives across accessory categories.
Silicone formulations for straw and lid gasket applications are migrating from standard platinum-cured systems toward medical-grade liquid silicone rubber with enhanced tear strength. Specialty outdoor retailers and institutional foodservice buyers are specifying these upgraded materials for multi-year replacement cycles. This migration is compressing commodity silicone suppliers into undifferentiated supermarket channels while rewarding compounders with FDA master file registrations.
The EU Single-Use Plastics Directive's implementation timeline is forcing immediate reformulation of polypropylene straws and polystyrene lid liners across member state markets. Manufacturers serving German and French retail chains are accelerating FSC-certified bamboo and Cradle-to-Cradle silicone certifications to maintain shelf placement. Small-format hospitality operators in Southern Europe are responding fastest due to stricter national transposition deadlines and coastal tourism sensitivity to plastic pollution visibility.
Buyer concentration among specialty outdoor retailers is compressing traditional distributor margins and forcing direct manufacturer investment in brand-owned digital channels. REI and Dick's Sporting Goods are consolidating accessory assortment decisions toward exclusive co-development partnerships with proven thermal performance credentials. This channel consolidation is most visible in Pacific Northwest and Rocky Mountain regional markets where outdoor recreation participation rates sustain premium price acceptance for vacuum-insulated sleeve bundles.
Drinkware Accessories Market Segmentation
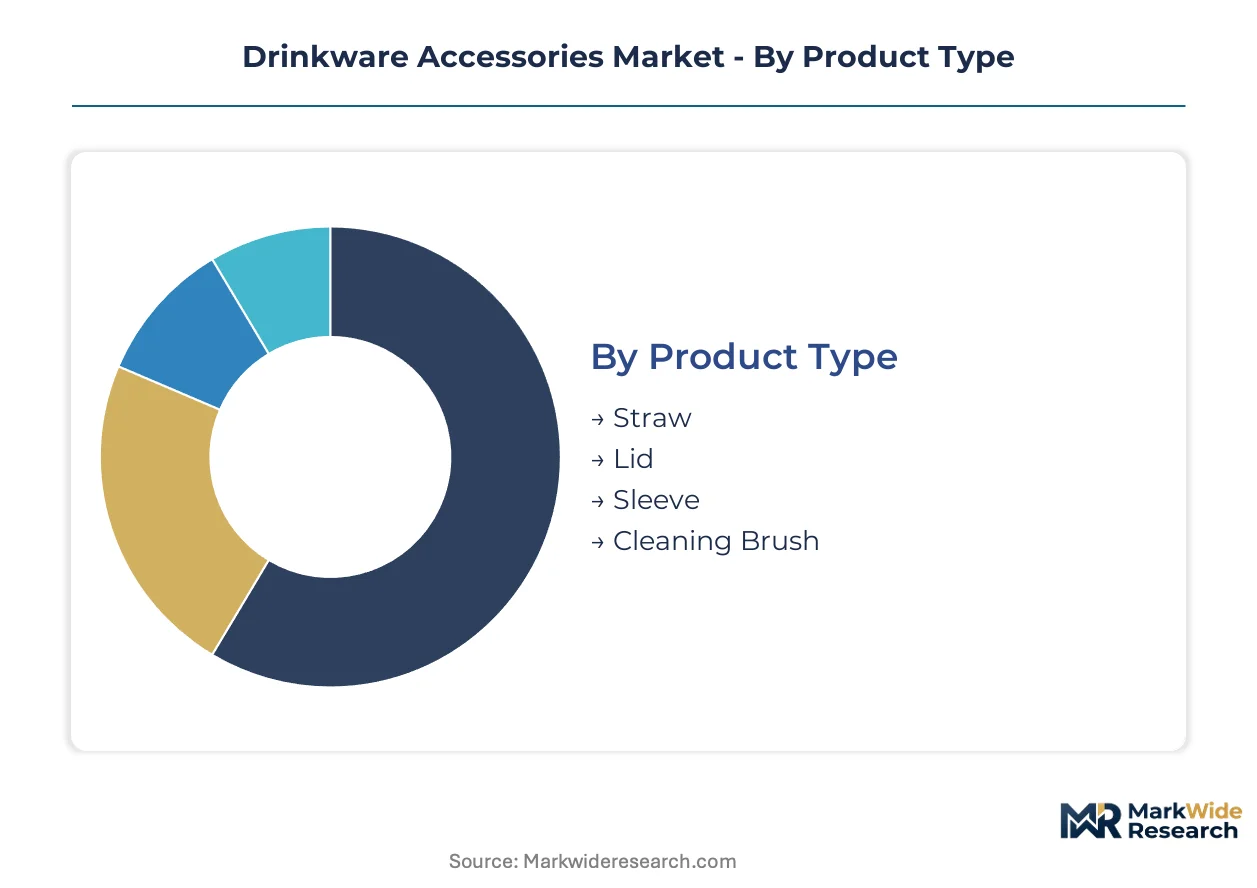
Segmentation in drinkware accessories reveals divergent margin profiles and replacement cadences. After-sales intensity varies sharply by product type and end user, with outdoor enthusiasts generating 3-4x higher accessory attachment rates than casual home users.
Product Type:
After-sales-service intensity peaks with cleaning brushes and replacement straws, where repeat purchase cycles and consumable wear create recurring revenue streams that lid and sleeve manufacturers cannot replicate.
- Straw:Fabricated from medical-grade silicone or 18/8 stainless steel tubing with precision-bored diameters for flow consistency. Demand concentrates among outdoor enthusiasts in Germany and France, where EU Single-Use Plastics Directive enforcement has eliminated polypropylene alternatives from hospitality procurement.
- Lid:Vacuum-formed or CNC-machined sealing assemblies incorporating silicone gaskets and polypropylene threading. German sustainability-driven consumers favor premium stainless steel lids with replaceable gasket systems, locking in multi-year replacement part revenue for certified suppliers.
- Sleeve:Neoprene, silicone, or aerogel-composite insulation layers thermoformed to vessel contours. REI and Dick's Sporting Goods buyers specify these for bundled thermal performance in Pacific Northwest markets.
- Cleaning Brush:Bamboo filament or nylon-bristle implements with twisted-wire cores and ergonomic handles. Moisture absorption limits cap bamboo brush applications to narrow-neck bottle cleaning, constraining filament diameter specifications.
By volume, Sleeve leads. By growth pace, Cleaning Brush is ahead.
Material:
Cost tier stratification separates certified medical-grade compounds from commodity feedstocks, with platinum-cured silicone commanding 4-5x pricing premiums over peroxide-cured alternatives in specialty channels.
- Silicone:Platinum-cured liquid silicone rubber with FDA master file registrations dominates straw and gasket applications. Migration testing protocols under REACH standards have created certified supplier scarcity in European supply chains.
- Stainless Steel:18/8 or 18/10 austenitic grades with electropolished finishes for food-contact surfaces. Nickel and chromium price volatility from Indonesian and South African supply concentration compresses margin buffers for mid-tier lid fabricators.
- Bamboo:FSC-certified fiber composites and solid laminates for brush handles and straw bodies. France's AGEC law and Germany's VerpackG mandate take-back infrastructure that rewards producers with closed-loop recovery systems.
- Plastic:Polypropylene and polystyrene formulations facing compression from EU Single-Use Plastics Directive implementation timelines. Supermarket channels retain volume leadership despite regulatory pressure on petroleum-based polymers.
By revenue contribution, Silicone leads. By certification velocity, Bamboo is climbing the fastest.
End User:
Application context determines performance specifications and price elasticity, with institutional buyers prioritizing durability metrics while household segments respond to sustainability signaling.
- Home Users:Residential consumers purchasing replacement straws and cleaning brushes through supermarket and online channels. Direct-to-consumer brush subscriptions are capturing recurring revenue from sustainability-focused household segments.
- Outdoor Enthusiasts:Camping and hiking equipment buyers demanding multi-pack stainless steel straw sets with custom carrying cases. This segment generates the highest accessory attachment rates and premium price acceptance.
- Athletes:Hydration-focused consumers requiring spill-proof lid systems and thermal sleeves for training environments. Vacuum-insulated sleeve convergence with aerogel layers opens premium performance tiers.
- Event Planners:Hospitality and corporate procurement specialists sourcing branded accessories in volume. Small-format operators in Southern Europe respond fastest to single-use plastic restrictions due to coastal tourism sensitivity.
By absolute volume, Home Users lead. By margin expansion, Outdoor Enthusiasts are gaining share fastest.
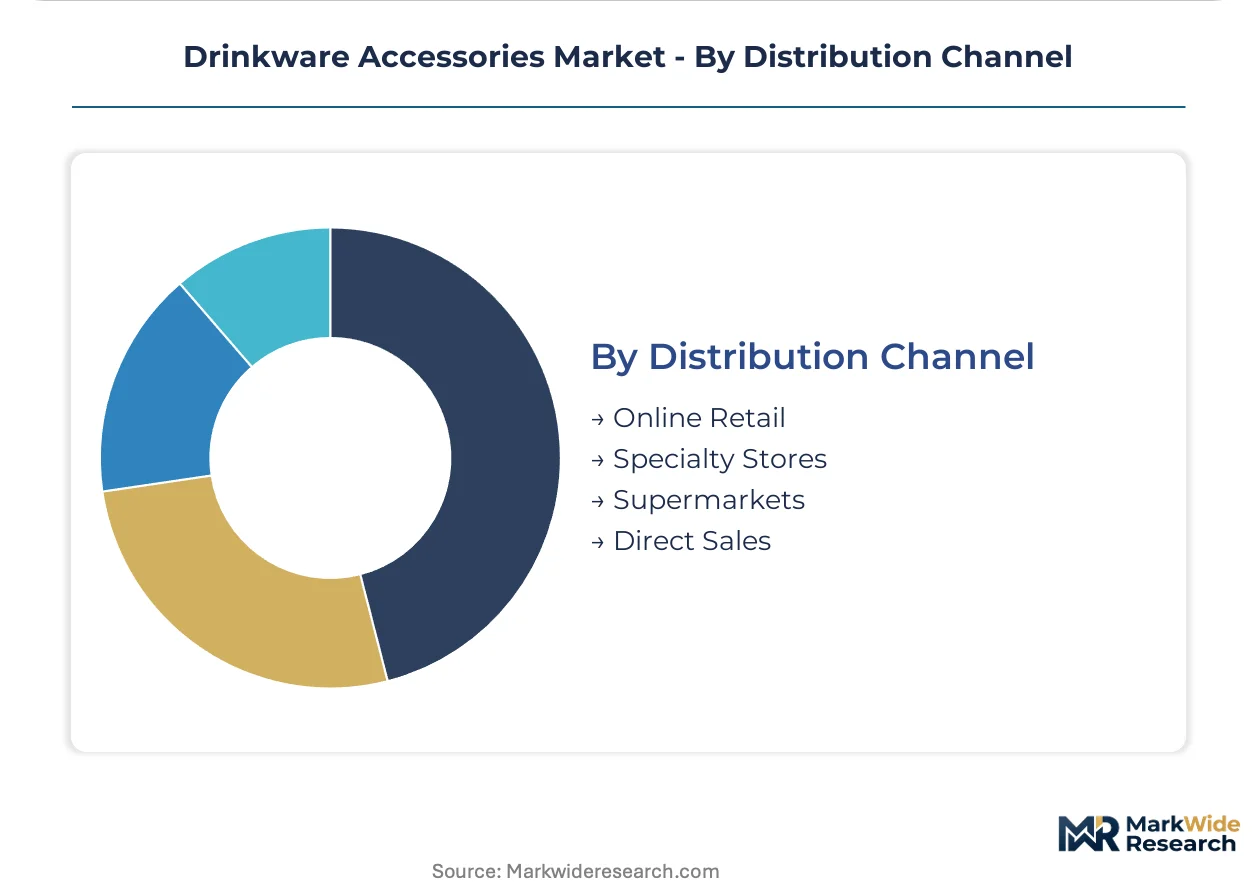
Distribution Channel:
Customer type and purchase urgency shape channel selection, with emergency replacements favoring online immediacy while planned upgrades flow through tactile retail experiences.
- Online Retail:Digital-native purchasing platforms capturing replacement part demand and subscription replenishment models. Brand-owned direct channels are compressing traditional distributor margins.
- Specialty Stores:REI and Dick's Sporting Goods consolidating assortment decisions toward exclusive co-development partnerships with proven thermal performance credentials.
- Supermarkets:Mass-market retail channels retaining plastic sleeve volume leadership despite regulatory pressure. Private-label sleeve contracts attract regional specialists through asset-light injection-molding leasing.
- Direct Sales:Manufacturer-owned channels and institutional procurement relationships. Extended Producer Responsibility frameworks reward producers with closed-loop material recovery infrastructure.
By transaction frequency, Online Retail leads. By partnership value, Specialty Stores show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's AGEC law and Germany's VerpackG are mandating take-back infrastructure that rewards accessory producers with closed-loop material recovery systems. These extended producer responsibility frameworks are redirecting procurement toward certified silicone and bamboo alternatives. Outdoor recreation participation in the Pacific Northwest and Rocky Mountain regions sustains premium price acceptance for vacuum-insulated sleeve bundles.
United States
Camping and hiking enthusiasts in the Pacific Northwest and Rocky Mountain states are expanding replacement straw purchases toward multi-pack stainless steel sets with custom carrying cases. FDA food-contact substance regulations govern migration limits for lid gaskets and straw coatings, elevating compliance costs for cross-border suppliers. Seattle and Portland anchor specialty retail consolidation, with REI and Dick's Sporting Goods consolidating assortment decisions toward exclusive co-development partnerships.
Germany
Sustainability-driven consumers in Bavaria and North Rhine-Westphalia favor premium stainless steel lids with replaceable gasket systems, locking in multi-year replacement part revenue. The VerpackG packaging law mandates take-back infrastructure that rewards producers with closed-loop material recovery systems. Munich and Hamburg concentrate certified silicone compounders with FDA master file registrations serving European supply chains.
China
Export-oriented manufacturers in Guangdong and Zhejiang provinces face 12-18 month qualification timelines under GB standards for food-contact materials that freeze out unqualified contract manufacturers from Western retail procurement. The Ministry of Ecology and Environment enforces dual carbon goals that constrain petroleum-based polymer capacity expansions. Shenzhen and Dongguan cluster injection-molding specialists serving supermarket private-label sleeve contracts through asset-light equipment leasing.
France
Small-format hospitality operators in Provence-Alpes-Côte d'Azur and coastal tourism zones respond fastest to single-use plastic restrictions due to pollution visibility sensitivity. The AGEC anti-waste law accelerates FSC-certified bamboo and Cradle-to-Cradle silicone certifications to maintain shelf placement in regulated channels. Lyon and Marseille concentrate regional specialists pivoting from polypropylene straws toward medical-grade liquid silicone rubber formulations.
Japan
Hydration-focused consumers in the Kanto and Kansai regions require spill-proof lid systems and thermal sleeves for training environments. METI standards for food-contact materials shape domestic certification requirements that filter import procurement. Osaka and Nagoya cluster precision machining fabricators supplying CNC-machined sealing assemblies with electropolished stainless steel finishes.
Drinkware Accessories Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated specialists and brand-owned direct channels that compress traditional distributor margins. The vendor base stratifies across three archetypes: legacy outdoor equipment brands with thermal performance credentials, stainless steel fabricators with captive raw material sourcing, and regional injection-molding specialists serving private-label contracts. Dominant competitive moves include exclusive co-development partnerships with specialty retailers and backward integration into medical-grade silicone compounding.
Among legacy outdoor equipment brands, Stanley, Hydro Flask, and Yeti Holdings Inc. exemplify the premium-tier archetype through vertical control over manufacturing quality and direct-to-consumer channel investment. These companies anchor positioning in North American specialty retail through proven thermal performance credentials. Stainless steel lid and vacuum-insulated sleeve technology concentration sits with fabricators that have secured FDA master file registrations and REACH-compliant silicone supply agreements.
| Leading Market Players |
|---|
| Stanley |
| CamelBak |
| Contigo |
| Newell Brands Inc. |
| Klean Kanteen |
| Hydro Flask |
| Thermos LLC |
| Libbey Inc. |
| Yeti Holdings Inc. |
| Others |
Supply & Pricing Matrix
Shanghai-Ningbo freight corridor cost dynamics compress margin buffers for European-bound silicone compounders while amplifying price spreads between certified medical-grade and commodity peroxide-cured alternatives. Supply concentration in Guangdong injection-molding clusters feeds downstream differentiation across German specialty retail and North American outdoor channels.
Pricing Analysis
Certification level creates the primary spread across drinkware accessories, with FDA master file-registered silicone commanding premium positioning over REACH-compliant but non-registered alternatives. Three-tier pricing structure across premium medical-grade, standard food-grade, and economy peroxide-cured tiers stratifies the market. Pricing pressure stems from nickel and chromium feedstock volatility originating in Indonesian and South African supply concentration. Home users through supermarket channels exhibit highest price sensitivity, while outdoor enthusiasts through REI and Dick's Sporting Goods demonstrate lowest elasticity for thermal performance bundles.
Supply Chain Analysis
Contract manufacturing concentrates in Shenzhen and Dongguan injection-molding specialists, with secondary clusters in Zhejiang thermoforming operations and Osaka precision machining fabricators. Raw material flows draw from Malaysian silicone feedstock, Indonesian nickel for stainless steel, and FSC-certified bamboo from Anhui province. Single-source vulnerability sits with platinum-cured silicone compounders holding FDA master file registrations. Distribution runs through brand-owned direct channels compressing traditional distributor margins, with supermarket private-label contracts anchored in asset-light equipment leasing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drinkware accessories sit in early-cycle expansion as EU Single-Use Plastics Directive enforcement accelerates material substitution timelines and opens certified supplier scarcity premiums. Sustainability-driven procurement mandates across Germany and France extend replacement part revenue visibility.
For Market Incumbents: Entrench positioning through backward integration into medical-grade silicone compounding and captive stainless steel lid finishing. Lock in multi-year exclusive co-development partnerships with REI and Dick's Sporting Goods before channel consolidation completes. Defend against emerging regional injection-molding specialists by accelerating REACH and FDA dual-certification pipelines that freeze out unqualified competitors.
For New Entrants and Emerging Players: Pursue direct-to-consumer brush subscription models capturing recurring revenue from sustainability-focused household segments. Target white-space in FSC-certified bamboo brush handles for narrow-neck bottle applications where moisture absorption limits have capped incumbent expansion. Establish go-to-market through specialty outdoor retail partnerships in Pacific Northwest markets where premium price acceptance sustains vacuum-insulated sleeve bundles.
For Investors and Strategic Acquirers: Regional injection-molding specialists with asset-light equipment leasing capabilities and supermarket private-label relationships offer consolidation targets. Long-term viability hinges on closed-loop material recovery infrastructure compliance with France's AGEC law and Germany's VerpackG extended producer responsibility frameworks. Watch for inflection in EUDR deforestation compliance batch-tracking investments as a signal of operational readiness for regulated European shelf placement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Silicone Compounding | FDA master file registrations lock in premium pricing and freeze out commodity competitors from specialty channels. |
| Exclusive Co-Development Partnerships with Specialty Retailers | REI and Dick's Sporting Goods consolidation rewards proven thermal performance credentials with shelf placement security. |
| Direct-to-Consumer Subscription Models for Cleaning Brushes | Biodegradable head replenishment captures recurring revenue from sustainability-focused household segments in Germany and France. |
| Closed-Loop Material Recovery Infrastructure Investment | AGEC and VerpackG take-back mandates reward producers with certified silicone and bamboo recycling capabilities. |
| Aerogel-Composite Sleeve Technology Convergence | Integration with traditional neoprene opens premium thermal performance tiers for specialty coffee retail channels. |
Research Methodology
A spread of perspectives from silicone compounders, injection-molding specialists, specialty retail buyers, and sustainability certification auditors converged on the working assumptions. Primary interviews with procurement leads at REI and Dick's Sporting Goods, plant managers in Guangdong and Zhejiang, and regulatory affairs specialists at ECHA-registered testing laboratories combined with secondary validation through FDA master file databases, REACH registration dossiers, and customs trade flow records. Bottom-up capacity assessments and top-down demand sizing triangulated volume and value estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material certification tier, end-user application context, and distribution channel structure. CAGRs derived from replacement cycle analysis, regulatory implementation timelines, and channel penetration curves. Industry-specific inputs incorporated EU Single-Use Plastics Directive enforcement schedules and extended producer responsibility framework adoption rates.
Macroeconomic conditions sit as an overlay; deviation in nickel and chromium feedstock pricing, freight corridor cost structures, or euro-dollar exchange rates would shift the trajectory. Forecasts reflect assumptions about regulatory compliance timelines and certification pipeline velocities. Quarterly review of REACH registration updates, FDA master file submission trends, and specialty retail partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Europe Ice/Cooler Box Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
South Africa Cookware Market
Household Items
Electric Brooms Market
Household Items
Europe Handheld Fans Market
Household Items
MENA POU Water Purifiers Market
Household Items
Cutlery Steel Market
Household Items
Portable Car Vacuum Market
Household Items
Global Humidifier Market
Household Items
Asia-Pacific Air Purifier Market
Household Items
Commercial Lawnmower Market
Household Items
Indoor Humidifier Market
Household Items
Car Air Freshener Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Porcelain Tableware Market
Household Items
Stick Vacuum Cleaner Market