
 Washing Capsules Market | 2026-2036
Washing Capsules Market Size, Share, and Industry Trends Forecast 2026-2036
Washing Capsules Market Analysis
ISO 9001 quality management certification is unwinding as a baseline gating standard for manufacturers seeking retail shelf placement in developed markets. Procter & Gamble leverages its R&D intensity to sustain patent-protected film technologies that dissolve across temperature ranges. Henkel anchors European market presence through backward integration into surfactant production and captive supply of biodegradable polymers. Unilever competes on brand strength in emerging markets where single-use pouch formats dominate rural distribution channels.
Washing capsules are pre-measured, water-soluble pods containing concentrated laundry detergent encased in polyvinyl alcohol film that dissolves upon contact with water, designed to eliminate dosing guesswork and reduce chemical spillage in both domestic and commercial settings. Multi-chamber capsules lead product type margins by combining detergent, fabric softener, and stain remover in segmented compartments that release sequentially during wash cycles. Online retail channels represent the fastest-growing distribution pathway as direct-to-consumer subscription models capture recurring household purchases and bypass traditional wholesale markups.
REACH registration requirements in Europe govern surfactant chemistry and biodegradability thresholds, while EPA Safer Choice labeling in the United States shapes consumer-facing product differentiation and retailer procurement criteria. BIS certification for household chemicals in India creates market access barriers for imported formulations that lack local stability testing documentation. Stakeholders must monitor evolving packaging waste directives across multiple geographies as extended producer responsibility schemes begin assigning end-of-life collection costs directly to capsule manufacturers rather than municipal waste systems.
Market Dynamics
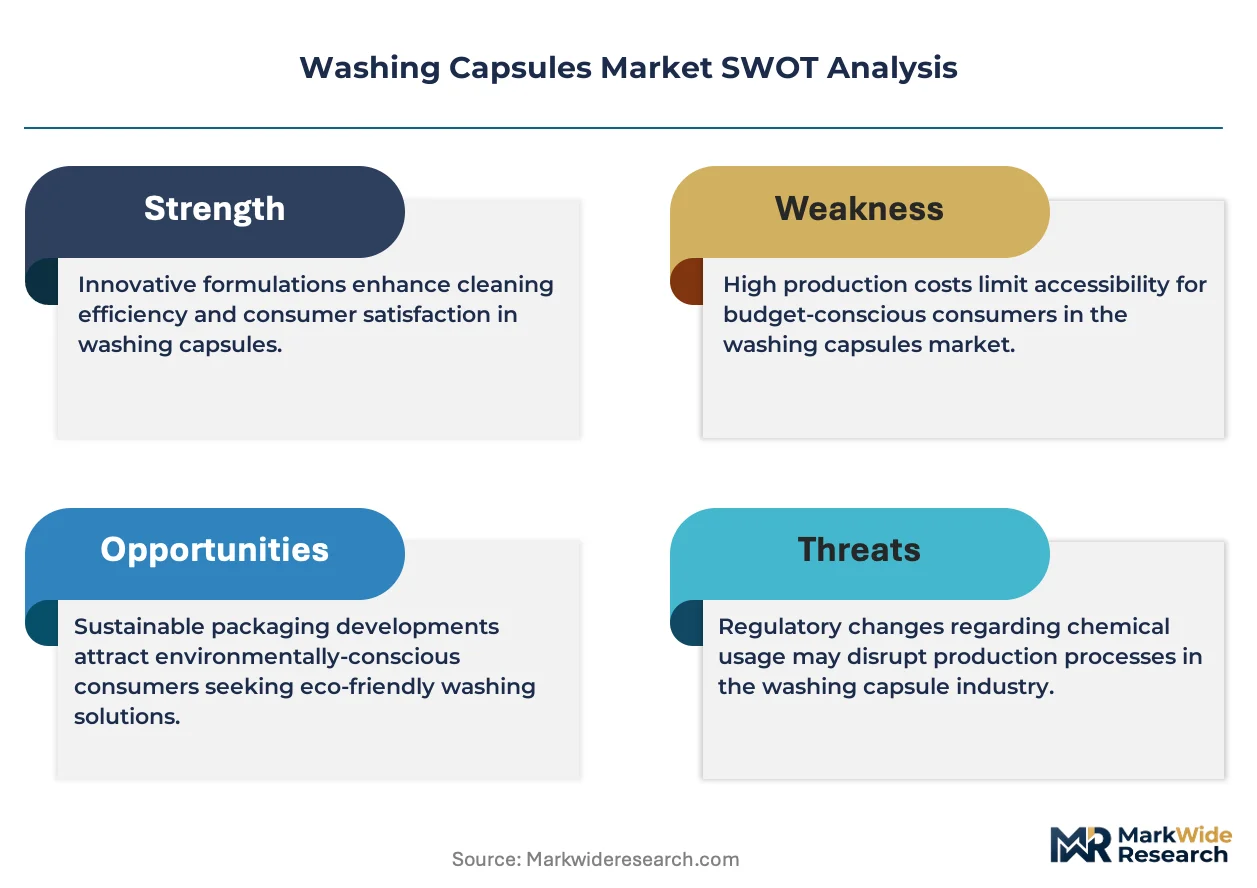
Pre-measured dosing formats are compressing the competitive landscape as commercial laundries in hospitality and healthcare sectors abandon bulk detergent systems. REACH compliance in Europe and EPA Safer Choice labeling in the United States are raising chemistry disclosure bars that favor concentrated, biodegradable formulations over legacy liquid detergents.
Growth Catalysts
- REACH registration thresholds:ECHA mandates for surfactant biodegradability are filtering out non-compliant suppliers and concentrating shelf space among certified multi-chamber capsule producers in Germany and France.
- Commercial laundry automation:Hospitality chains in the United States are retrofitting on-premise facilities with capsule-compatible dispensing systems to eliminate dosing variance and reduce chemical handling labor.
- Polyvinyl alcohol film chemistry:Advances in cold-water dissolution polymers are extending capsule viability into markets with lower-temperature washing norms, particularly Japan and South Korea.
Market Restraints
- Petrochemical feedstock volatility:Surfactant precursors derived from ethylene oxide supply chains expose margin compression risks when naphtha crack spreads widen.
- Single-source film supply concentration:Polyvinyl alcohol resin production clusters in East Asia create geographic concentration risk for European and North American capsule assemblers.
- Child-resistant packaging mandates:CPSC requirements for opaque, double-lock containers add per-unit cost burdens that erode price competitiveness against liquid detergents in economy segments.
Strategic Opportunities
- Rural India distribution gaps:Single-use pouch formats distributed through kirana stores and mobile commerce platforms remain underpenetrated relative to urban organized retail.
- EU Green Deal packaging waste directives:Extended producer responsibility schemes assign end-of-life collection costs to manufacturers, creating first-mover advantages for firms with closed-loop film recovery partnerships.
- Healthcare sanitation protocols:Infection control standards in German and Japanese hospital laundries are opening demand for capsules with integrated antimicrobial chambers beyond standard detergent-softener combinations.
Industry Challenges
- ISO 9001 certification timelines:Retail procurement departments in developed markets now require quality management documentation as a baseline gating condition, extending supplier onboarding cycles by 6-12 months.
- Legacy dispensing system incompatibility:Commercial laundries with capital equipment depreciation schedules resist retrofitting capsule-compatible hardware until end-of-life replacement cycles trigger.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Washing Capsules Market |
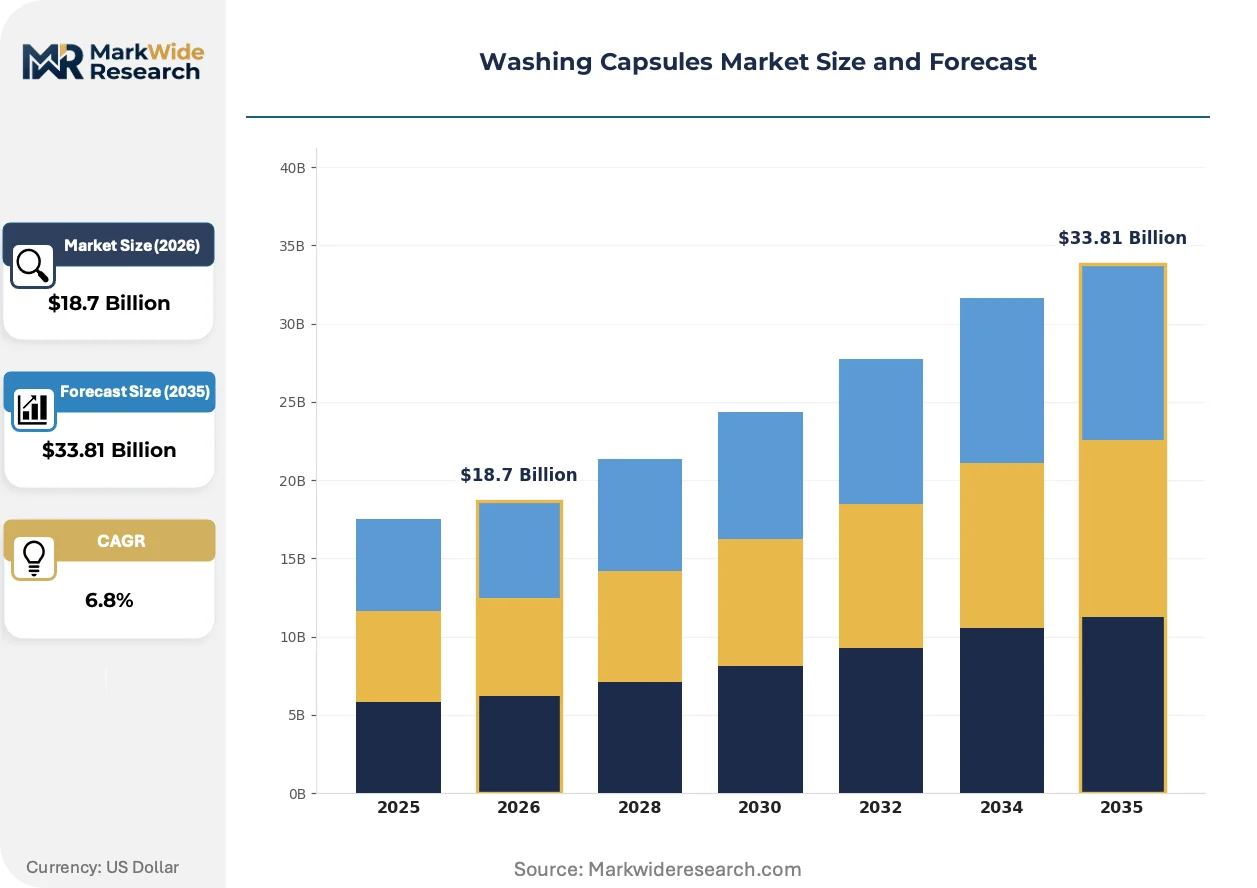
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Capsules, Powder Capsules, Eco-friendly Capsules, Multi-chamber Capsules End User: Households, Commercial Laundries, Hotels, Institutions Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale Packaging Type: Single-use Pouches, Bulk Containers, Eco-friendly Packaging, Gift Packs |
| Companies Covered | The Clorox Company, Kao Corporation, Procter & Gamble, Reckitt Benckiser, Church & Dwight, Henkel, Colgate-Palmolive, Lion Corporation, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Washing Capsules Market Emerging Trajectories
Multi-chamber architecture is fragmenting product development roadmaps as manufacturers race to integrate sequential-release chemistry. The competitive frontier is shifting from detergent concentration metrics toward film dissolution kinetics and chamber-separation integrity.
Water-soluble polyvinyl alcohol film technology is bifurcating the market into temperature-optimized grades. Cold-water formulations are capturing share in Japanese and Nordic residential segments where energy-efficient wash cycles dominate. Hot-water variants retain dominance in commercial hospitality applications where thermal sanitation is non-negotiable. This technical segmentation is compressing the addressable market for universal-temperature films.
EPA Safer Choice labeling requirements are reshaping surfactant procurement criteria in the United States. Retailers including Walmart and Target have integrated Safer Choice status into vendor scorecards, redirecting R&D expenditure toward biodegradable polymer development. Household product categories bearing the label now command preferential shelf positioning in mass-market channels.
Direct-to-consumer subscription models are disintermediating wholesale distribution in developed markets. Amazon Subscribe & Save and specialized laundry services in Germany and the United Kingdom are capturing recurring household purchases. This channel shift is most visible in premium multi-chamber segments where brand loyalty and convenience premiums offset per-unit shipping costs.
Washing Capsules Market Segmentation
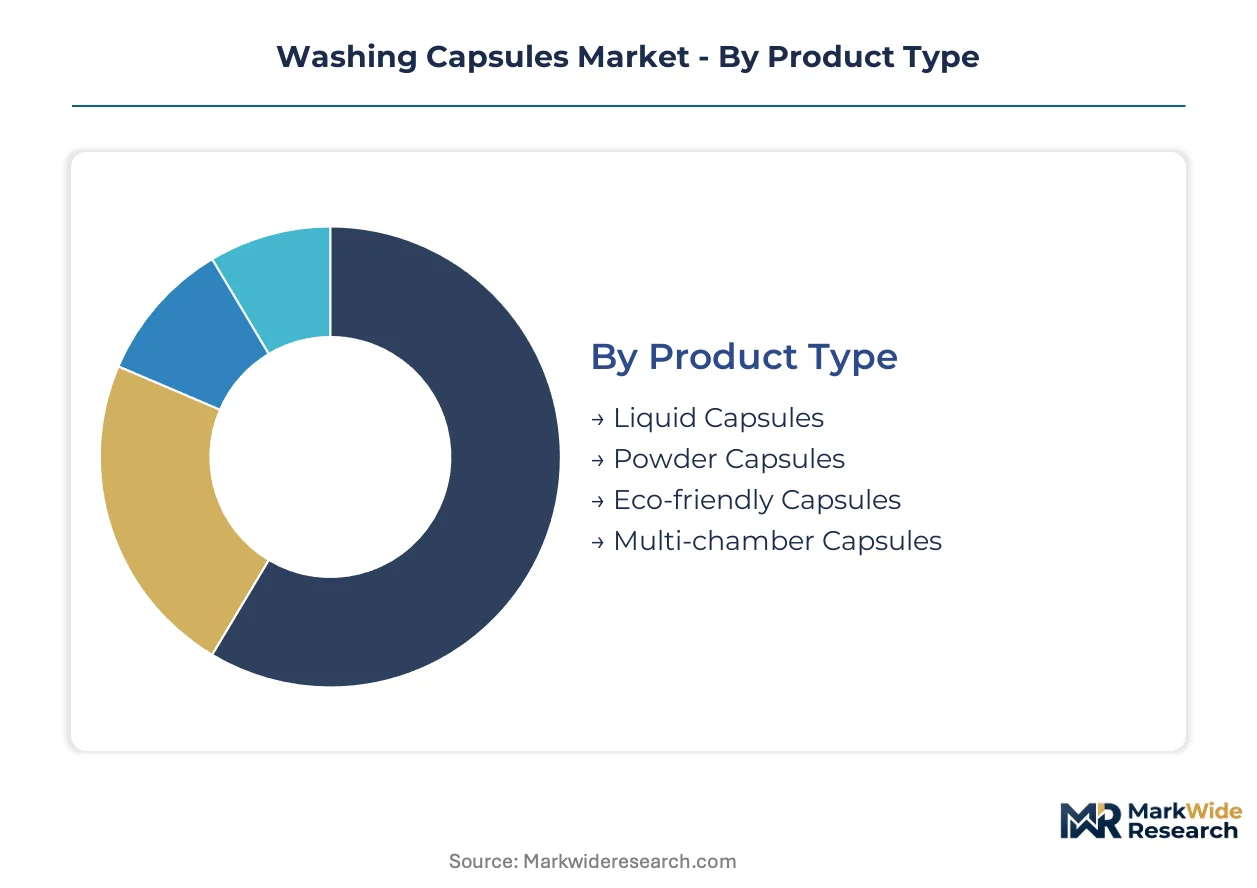
Washing capsules fragment across four dimensions that determine margin capture and channel access. Product chemistry and packaging format choices dictate regulatory compliance burdens, while end-user concentration shapes volume contracting terms and distribution economics.
Product Type:
Substitution pressure from concentrated liquid detergents and sheet formats intensifies most acutely in single-chamber segments, forcing multi-chamber and eco-friendly variants to defend premium positioning through performance differentiation.
- Liquid Capsules:Single-chamber polyvinyl alcohol film pods containing concentrated surfactant solutions dominate mass-market shelf space in Germany and the United States. Hospitality procurement departments favor these for compatibility with existing commercial dispensing systems, though margin compression from private-label competition is accelerating.
- Multi-chamber Capsules:Segmented compartments release detergent, fabric softener, and stain remover sequentially during wash cycles. Japanese and South Korean households with cold-water washing norms drive demand for advanced film dissolution kinetics that maintain chamber-separation integrity.
- Powder Capsules:Compressed detergent granules in water-soluble film address markets with high-mineral water hardness.
- Eco-friendly Capsules:Plant-derived surfactants and biodegradable polymers carry EPA Safer Choice or EU Ecolabel certifications.
Liquid capsules retain volume leadership; multi-chamber formats hold the steepest expansion curve.
End User:
Cost tier stratification separates premium multi-chamber adoption in contract hospitality from economy single-chamber penetration in price-sensitive institutional procurement.
- Households:Direct-to-consumer subscription models through Amazon Subscribe & Save and German specialized laundry services capture recurring purchases. Convenience premiums offset per-unit shipping costs in premium multi-chamber segments.
- Commercial Laundries:On-premise facilities in United States hospitality chains retrofit with capsule-compatible dispensing systems to eliminate dosing variance and reduce chemical handling labor. Capital equipment depreciation schedules delay adoption until replacement cycles trigger.
- Hotels:Brand-standard requirements for linen quality drive specification of multi-chamber formats with integrated fabric care.
- Institutions:German and Japanese hospital laundries adopt capsules with antimicrobial chambers beyond standard detergent-softener combinations to meet infection control protocols.
Commercial laundries command the largest contract values; healthcare institutions are climbing fastest on sanitation protocol upgrades.
Distribution Channel:
Volume concentration in organized retail creates supply chain leverage that online channels are disrupting through subscription economics and bypassed wholesale markups.
- Online Retail:Direct-to-consumer platforms represent the fastest-growing pathway as subscription models capture recurring household purchases. Walmart and Target vendor scorecards now integrate EPA Safer Choice status, redirecting procurement toward certified suppliers.
- Supermarkets:Mass-market shelf positioning in Germany, the United States, and Japan concentrates among ISO 9001-certified manufacturers with REACH-compliant surfactant chemistry.
- Convenience Stores:Single-use pouch formats distributed through kirana stores in rural India remain underpenetrated relative to urban organized retail.
- Wholesale:Bulk contracting for commercial laundries and hospitality chains operates on annual volume commitments with formula pricing adjustments.
Supermarkets retain transaction volume leadership; online retail is expanding most quickly on subscription conversion.
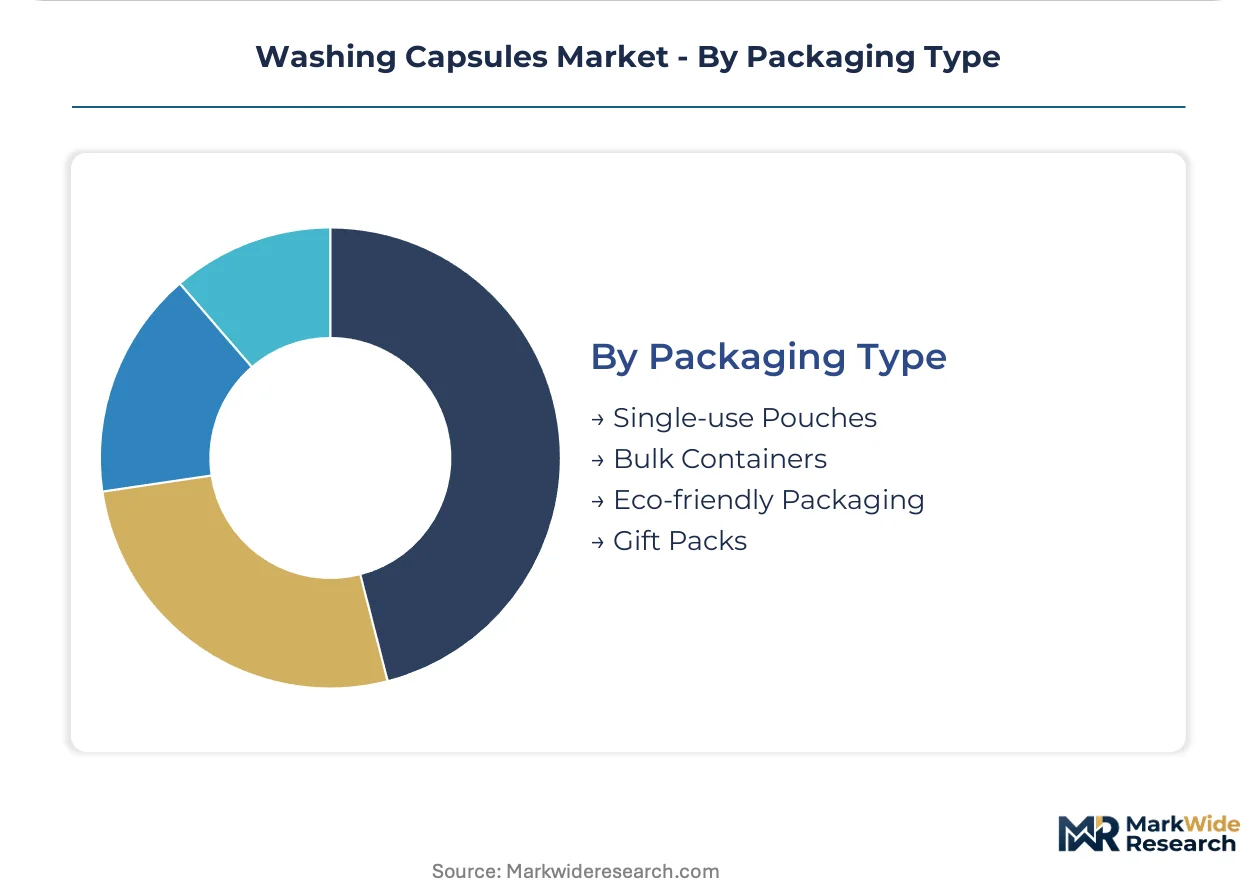
Packaging Type:
Supply concentration in East Asian polyvinyl alcohol resin production shapes format economics, with extended producer responsibility schemes in Europe beginning to assign end-of-life collection costs directly to manufacturers.
- Single-use Pouches:Individual water-soluble pods in child-resistant, opaque, double-lock containers address CPSC mandates. Per-unit cost burdens from compliance erode price competitiveness against liquid detergents in economy segments.
- Bulk Containers:Commercial laundries in hospitality and healthcare sectors accelerate adoption of pre-measured dosing formats to abandon bulk detergent systems, though legacy dispensing incompatibility delays retrofitting.
- Eco-friendly Packaging:Closed-loop film recovery partnerships create first-mover advantages under EU Green Deal packaging waste directives.
- Gift Packs:Premium multi-chamber assortments target seasonal household gifting in Japanese and South Korean markets.
Single-use pouches dominate unit volume; eco-friendly packaging is gaining share fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial laundry buyers in hospitality and healthcare sectors concentrate procurement volume in Germany, the United States, and Japan, where premium multi-chamber formats command established shelf positions and regulatory compliance infrastructure.
Germany
REACH registration mandates from ECHA filter non-compliant surfactant suppliers and concentrate retail shelf space among certified multi-chamber capsule producers. The country's national chemical regulator enforces strict biodegradability thresholds that favor concentrated, biodegradable formulations. Industrial laundries in the Rhine-Ruhr metropolitan region retrofit facilities with capsule-compatible dispensing systems to eliminate dosing variance.
United States
EPA Safer Choice labeling requirements reshape surfactant procurement criteria as retailers integrate certification status into vendor scorecards. Hospitality chains across the Sun Belt retrofit on-premise facilities with capsule-compatible dispensing systems to reduce chemical handling labor. Manufacturing clusters in the Midwest produce child-resistant, opaque, double-lock containers that comply with CPSC mandates.
Japan
Cold-water washing norms drive demand for advanced film dissolution kinetics that maintain chamber-separation integrity in energy-efficient wash cycles. METI standards govern household chemical stability testing and packaging safety requirements. Industrial laundries in the Kansai region around Osaka adopt capsules with integrated antimicrobial chambers to meet hospital infection control protocols.
India
BIS certification for household chemicals creates market access barriers for imported formulations lacking local stability testing documentation. Single-use pouch formats distributed through kirana stores in rural Maharashtra and Gujarat remain underpenetrated relative to urban organized retail. Mobile commerce platforms capture recurring household purchases in Tier-2 and Tier-3 cities.
South Korea
Energy-efficient residential washing machine penetration drives adoption of cold-water dissolution polymers. The country's national standards body enforces packaging safety and chemical disclosure requirements for household detergents. Manufacturing facilities in the Seoul Capital Area supply polyvinyl alcohol resin to domestic capsule assemblers and export markets.
Washing Capsules Market Vendor Landscape
Player mix skews toward multinational consumer goods conglomerates with integrated surfactant supply chains and captive film technology partnerships. Three to five holding companies control the majority of premium multi-chamber shelf space in developed markets, while regional specialists defend positions in single-use pouch segments. Strategic archetypes include R&D-intensive patent holders, backward-integrated surfactant producers, and brand-loyalty-driven emerging market distributors. Dominant competitive moves encompass capacity expansion in biodegradable polymer production and technology licensing agreements for cold-water dissolution films.
Within the multinational conglomerate tier, Procter & Gamble, Henkel, and Unilever occupy positions that exemplify distinct strategic vectors. Procter & Gamble anchors North American market presence through patent-protected film technologies. Henkel represents European backward integration into surfactant production and captive biodegradable polymer supply. Unilever sits within the emerging market distribution archetype where single-use pouch formats dominate rural channels.
| Leading Market Players |
|---|
| The Clorox Company |
| Kao Corporation |
| Procter & Gamble |
| Reckitt Benckiser |
| Church & Dwight |
| Henkel |
| Colgate-Palmolive |
| Lion Corporation |
| Unilever |
| Others |
Supply Flow & Price Mechanics
Polyvinyl alcohol resin substitution for conventional detergent packaging simultaneously redraws supply geography toward East Asian manufacturing clusters and compresses pricing economics through petrochemical feedstock indexation. REACH-compliant surfactant chemistry in Europe and EPA Safer Choice certification in the United States bifurcate procurement criteria, forcing buyers to absorb premium differentials or accept non-certified alternatives.
Pricing Analysis
Cost-plus contracts with ethylene oxide feedstock indexation dominate commercial laundry procurement in the United States hospitality sector. Three-tier pricing structure across premium multi-chamber, standard single-chamber, and economy powder formats separates ISO 9001-certified manufacturers from private-label competitors. Pricing pressure stems from naphtha crack spread volatility that squeezes surfactant precursor margins. Institutional buyers in German healthcare exhibit lowest price sensitivity due to infection-control protocol mandates, while rural Indian kirana stores face acute cost compression from liquid detergent alternatives.
Supply Chain Analysis
Strait of Malacca transit underwrites polyvinyl alcohol resin flows from South Korea, Japan, and China toward European and North American capsule assemblers. Manufacturing draws from ethylene oxide derivatives, biodegradable polymer additives, and cold-water dissolution film grades. Single-source concentration in East Asian resin production creates tariff exposure risk as trade policy shifts. Distribution runs through wholesale bulk contracting for commercial laundries and direct-to-consumer subscription platforms for household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Washing capsules constitute a defensive-moat market where regulatory entrenchment through REACH and EPA Safer Choice certification creates switching costs that lock in procurement relationships across hospitality and healthcare verticals.
For Market Incumbents: Compound backward integration into surfactant production to defend margin position against private-label encroachment in single-chamber segments. Prioritize captive supply of biodegradable polymers to capture EU Green Deal extended producer responsibility advantages before compliance deadlines tighten. Capacity addition in German Rhine-Ruhr manufacturing clusters reinforces proximity to ECHA-regulated buyers. For New Entrants and Emerging Players: EPA Safer Choice fast-track certification unlocks Walmart and Target vendor scorecard eligibility that incumbent suppliers currently monopolize. White-space concentration sits in rural India kirana store distribution for single-use pouch formats, where mobile commerce platforms enable direct-to-consumer bypass of organized retail markups. Cold-water dissolution film technology licensing from Japanese polymer specialists accelerates market entry. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated surfactant producers with captive biodegradable polymer supply. Long-term viability hinges on extended producer responsibility scheme adaptation across European markets. Acquisition target archetype: regional specialists with established BIS certification in India and underexploited kirana store distribution networks. Monitor ECHA biodegradability threshold tightening as inflection signal for chemistry compliance investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Production | Henkel's captive supply of biodegradable polymers insulates margin from ethylene oxide price volatility. |
| Cold-Water Dissolution Film Licensing | Japanese polymer technology transfers unlock South Korean and Nordic residential market penetration. |
| Direct-to-Consumer Subscription Launch | Amazon Subscribe & Save bypasses wholesale markups and captures recurring household purchase loyalty. |
| EPA Safer Choice Certification Investment | Walmart vendor scorecard integration redirects procurement toward certified multi-chamber suppliers. |
| Closed-Loop Film Recovery Partnership | EU Green Deal extended producer responsibility schemes assign collection cost advantages to first movers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA REACH registration databases, EPA Safer Choice certified product listings, and Nielsen retail audit records. Interviews with procurement directors at United States hospitality chains, German hospital laundry facility managers, and South Korean polymer R&D heads inform demand-side validation. Technical discussions with surfactant plant engineers and polyvinyl alcohol resin distribution channel partners anchor supply-side assessment. Bottom-up volume modeling triangulates against top-down value projections across product type, end user, and distribution channel dimensions.
Segmentation dimensions modeled encompass liquid, multi-chamber, powder, and eco-friendly product types; household, commercial laundry, hotel, and institutional end users; online retail, supermarket, convenience store, and wholesale distribution channels; and single-use pouch, bulk container, eco-friendly packaging, and gift pack formats. CAGRs derive from regression analysis of historical volume trajectories and elasticity-adjusted price evolution across the projection horizon. Forecast inputs incorporate REACH biodegradability threshold enforcement schedules and EPA Safer Choice label adoption curves.
Decision-makers should treat outputs as directional under sustained petrochemical feedstock availability and stable regulatory enforcement intensity; material deviation in naphtha crack spreads or ECHA threshold tightening would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Sleeping Pods Market
Household Items
Europe Hand Dryers Market
Household Items
Hydration Containers Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Electric Hedge Trimmer Market
Household Items
Robotic Vacuum Cleaner Market
Household Items
Dry and Wet Wipes Market
Household Items
UV Sanitizer Travel Wand Market
Household Items
Commercial Lawnmower Market
Household Items
North America Robotic Pool Cleaner Market
Household Items
Washing Machine Cleaner Market
Household Items
Scouring Pads Market
Household Items
Car Air Freshener Market
Household Items
Facial Tissue Paper Market
Household Items
Laundry Detergent Sheets Market
Household Items
Lunch Box Market