
 UK Digital Showers Market | 2026-2036
UK Digital Showers Market Size, Share, and Industry Trends Forecast 2026-2036
UK Digital Showers Market Insights
WRAS approval is collapsing as the baseline gate for market participation, with manufacturers now needing KIWA or BSI certification to secure specification in premium developments. Mira Showers leverages its British manufacturing heritage to sustain trade channel loyalty across merchant networks. Aqualisa competes through app-controlled thermostatic systems that anchor its position in the smart home integration segment. Triton Showers dominates the replacement market with value-engineered digital mixer units.
UK digital showers combine electronically controlled thermostatic mixing valves with digital user interfaces to deliver precise temperature and flow management through solenoid-actuated water paths. These systems serve residential and commercial wet environments where scald protection and water efficiency compliance are mandatory. Thermostatic digital products lead the product type hierarchy due to their integration with Building Regulations Part G temperature control requirements. Wi-Fi enabled and app controlled technologies are capturing the fastest expansion as homeowners retrofit connected ecosystems. Wet room installation and hotel suites represent the most concentrated margin pools within the use case dimension.
WRAS, BSI, and the UK's Building Regulations Part G framework collectively shape product design standards and installation compliance pathways for digital shower systems. The Environment Agency's water efficiency targets further pressure manufacturers to optimize flow rates below statutory limits. Stakeholders must monitor how Ofwat's future consumption reduction mandates will recalibrate minimum performance thresholds for connected bathroom fixtures.
Market Dynamics
WRAS approval erosion is compressing competitive access as KIWA and BSI certifications become mandatory specification filters in premium UK residential developments. This regulatory recalibration is redistributing market power toward manufacturers with established British testing infrastructure.
Growth Catalysts
- Building Regulations Part G temperature mandates:Thermostatic digital mixing valves now satisfy mandatory scald protection requirements in all new UK residential wet rooms, eliminating traditional mixer alternatives from compliant specifications.
- Southeast England housing corridors:Concentrated new-build activity across Kent, Surrey, and Essex is absorbing volume shipments of connected shower systems as standard fixtures in developer packages.
- Wi-Fi module cost curves:Falling semiconductor pricing for wireless connectivity chipsets is enabling app-controlled functionality at mid-market price points previously restricted to luxury tiers.
Market Restraints
- Brass and copper input volatility:Thermostatic valve bodies rely on non-ferrous metal castings subject to London Metal Exchange price swings that compress gross margins during commodity spikes.
- Solenoid actuator supply concentration:Precision water-path control components source predominantly from German and Italian specialist manufacturers, creating single-source vulnerability for UK assemblers.
- Gas boiler phase-out timeline uncertainty:Ambiguity around UK heat pump transition deadlines is delaying renovation decisions among homeowners weighing complementary bathroom upgrades.
Strategic Opportunities
- Social housing decarbonization:Ofwat consumption reduction mandates create specification pathways for flow-optimized digital showers in council-owned retrofit programs across Northern England.
- Voice assistant integration:Amazon Alexa and Google Home protocol convergence with shower control APIs opens smart home ecosystem positioning beyond standalone app functionality.
- Wet room specification in boutique hotels:Edinburgh and Manchester hospitality developments are specifying thermostatic digital systems as guest experience differentiators in premium room categories.
Industry Challenges
- Multi-skilled installation technician scarcity:Digital shower deployment demands plumbers with electrical competency and smart home commissioning skills that trade apprenticeship pipelines undersupply.
- KIWA certification timeline compression:Extended laboratory testing queues for thermostatic performance validation are delaying product launches and freezing inventory capital for 12-18 month cycles.
- Legacy gravity-fed system incompatibility:Victorian-era housing stock with low-pressure hot water cylinders requires pump-assisted digital units that complicate retrofit economics and installation logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Digital Showers Market |
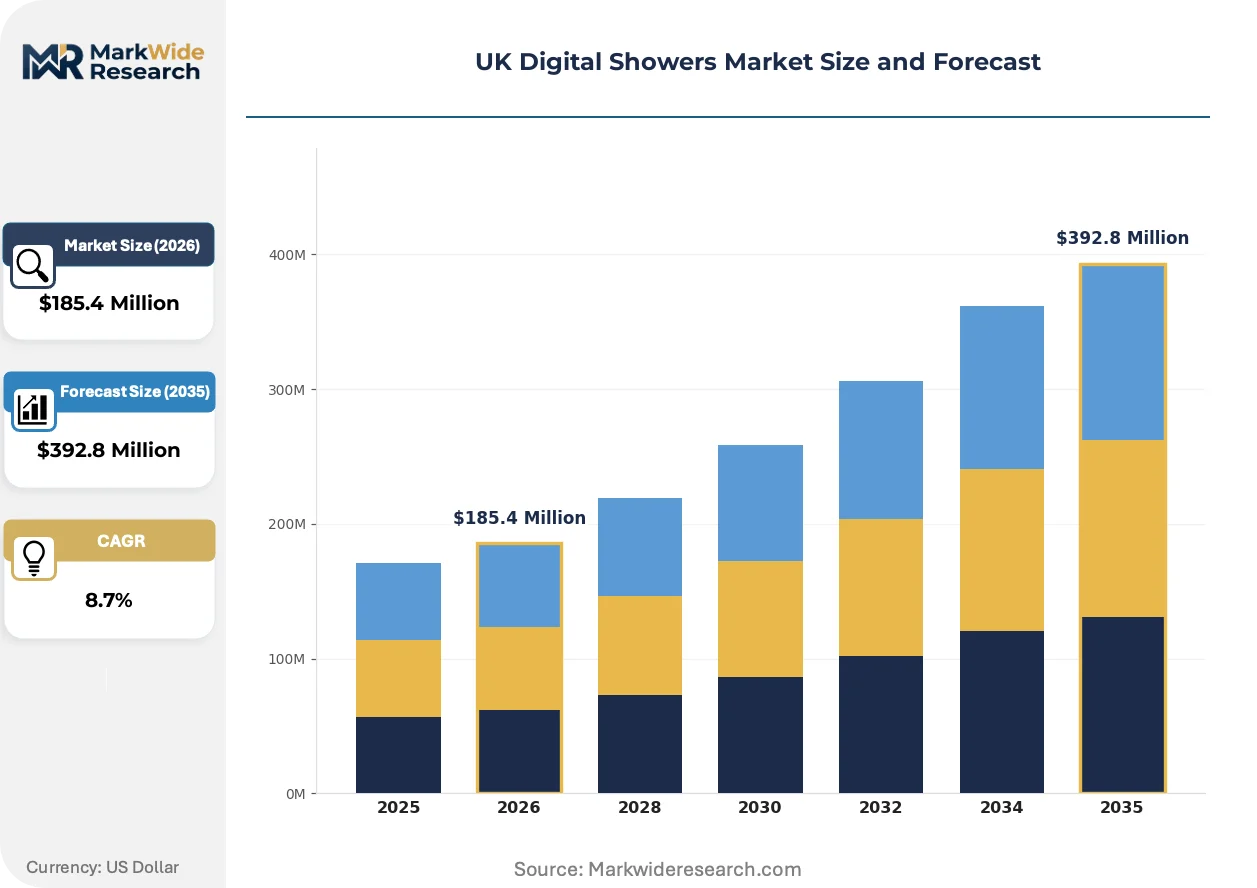
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $392.8 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermostatic Digital, Thermostatic Mixer, Manual Digital, Power Shower, High-Pressure Mixer Technology: Wi-Fi Enabled, Bluetooth Compatible, Voice Control, Touch Screen Interface, App Controlled Use Case: Residential Renovation, Wet Room Installation, Hotel Suites, Fitness Centers, Senior Living Facilities Distribution Channel: Specialty Retailers, Online Marketplaces, Plumbing Suppliers, Home Improvement Stores, Trade Wholesalers |
| Companies Covered | Roca UK Bathrooms, Dornbracht, Mira Showers, Lixil Corporation, Kohler, Aqualisa, Roman Limited, Toto Ltd, Triton Showers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Digital Showers Market Trends and Innovations
Connected bathroom ecosystems are redefining user interaction paradigms as thermostatic precision becomes a baseline expectation rather than a premium feature. Manufacturers are racing to embed intelligence deeper into water delivery infrastructure.
Digital valve control electronics is miniaturizing as silicon integration replaces discrete component architectures in thermostatic mixing modules. High-volume residential developers in London's Zone 2-4 new-build zones are specifying these compact units for space-constrained service voids. The technology is miniaturizing installation footprints to sub-100mm depths, enabling concealed valve positioning behind thinner wall constructions that maximize usable bathroom volumes.
UK Building Regulations Part G water efficiency amendments are tightening maximum flow rate thresholds for domestic showers to 10 litres per minute. Manufacturers are recalibrating solenoid aperture geometries and pressure-compensating algorithms to maintain thermal stability at restricted volumes. Thermostatic digital products with sub-8 litre certified performance are capturing specification preference in Southeast England's Part L-compliant housing developments.
Merchant channel consolidation is compressing distributor margins as national plumbing chains centralize procurement decisions at headquarters level. Independent regional merchants in Yorkshire and the Midlands are losing specification influence to consolidated national accounts teams. Scotland's developer market exhibits strongest resistance to this concentration, with local merchant networks retaining project-level relationships through technical specification support services.
UK Digital Showers Market Segmentation
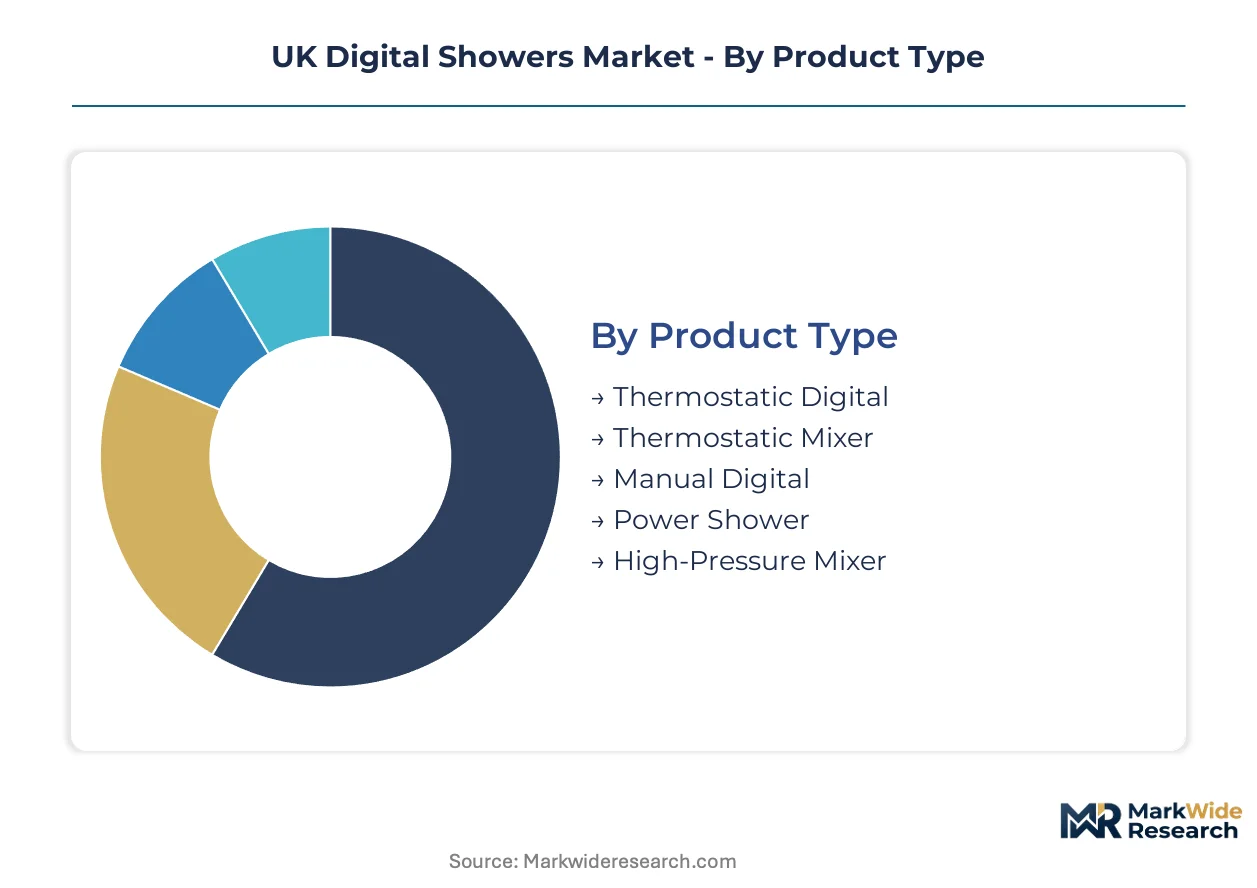
UK digital shower segmentation reveals how Building Regulations Part G compliance requirements and smart home integration priorities reshape specification patterns across residential and commercial wet environments. Distinct technology tiers and distribution pathways create divergent margin profiles that manufacturers must navigate strategically.
Product Type:
Domestic production concentrates thermostatic digital and thermostatic mixer variants for UK specification, while power shower and high-pressure mixer units increasingly serve export markets in Ireland and the Channel Islands.
- Thermostatic Digital:Electronically controlled mixing valves with digital interfaces deliver precise temperature management through solenoid-actuated water paths. Demand clusters in London's Zone 2-4 luxury residential developments where Building Regulations Part G scald protection mandates eliminate traditional alternatives.
- Thermostatic Mixer:Mechanical thermostatic cartridges with manual override controls bridge compliance requirements and cost sensitivity. Southeast England's new-build housing corridors absorb volume shipments as developer-standard fixtures in Part L-compliant developments.
- Manual Digital:Basic electronic temperature displays without automated mixing functionality serve budget-conscious renovation segments in Northern England's Victorian housing stock.
- Power Shower:Pump-assisted systems overcome low-pressure gravity-fed hot water cylinders common in pre-1960s UK housing.
- High-Pressure Mixer:Unpumped units for combi boiler and unvented cylinder installations dominate replacement demand in post-1990 housing.
Thermostatic digital holds the largest share; momentum sits with thermostatic mixer variants in volume housing.
Technology:
Cost tier stratification separates premium voice and app-controlled systems from mid-market Bluetooth units and entry-level touch screen interfaces.
- Wi-Fi Enabled:Wireless connectivity modules enable remote pre-heating and usage analytics through cloud-connected platforms. Edinburgh and Manchester boutique hotel developments specify these for guest experience differentiation in premium room categories.
- App Controlled:Smartphone integration with programmable profiles and water consumption tracking anchors smart home ecosystem positioning. Wi-Fi module cost curves enable this functionality at mid-market price points previously restricted to luxury tiers.
- Voice Control:Amazon Alexa and Google Home protocol convergence opens hands-free operation for accessibility-focused installations in senior living facilities.
- Bluetooth Compatible:Local wireless pairing without internet dependency serves privacy-conscious residential segments.
- Touch Screen Interface:On-device controls without connectivity reduce cost for basic digital temperature management.
App controlled systems command premium positioning; Wi-Fi enabled variants are climbing the fastest in new-build specifications.
Use Case:
Volume concentrates in residential applications while margin pools concentrate in commercial wet environments with specification durability requirements.
- Residential Renovation:Retrofit installations in owner-occupied housing drive replacement demand as homeowners modernize bathrooms ahead of heat pump transitions. Gas boiler phase-out timeline uncertainty delays some upgrade decisions.
- Wet Room Installation:Level-access showering environments with concealed drainage systems require thermostatic precision for scald protection in multi-generational households.
- Hotel Suites:Edinburgh and Manchester hospitality developments specify digital systems as guest experience differentiators with water efficiency compliance.
- Fitness Centers:High-frequency commercial use demands durable valve components with rapid recovery times between users.
- Senior Living Facilities:Care home operators prioritize thermostatic lockout features and grab-bar compatibility for accessibility compliance.
Residential renovation holds the largest share; hotel suites represent the steepest expansion trajectory in commercial segments.
Distribution Channel:
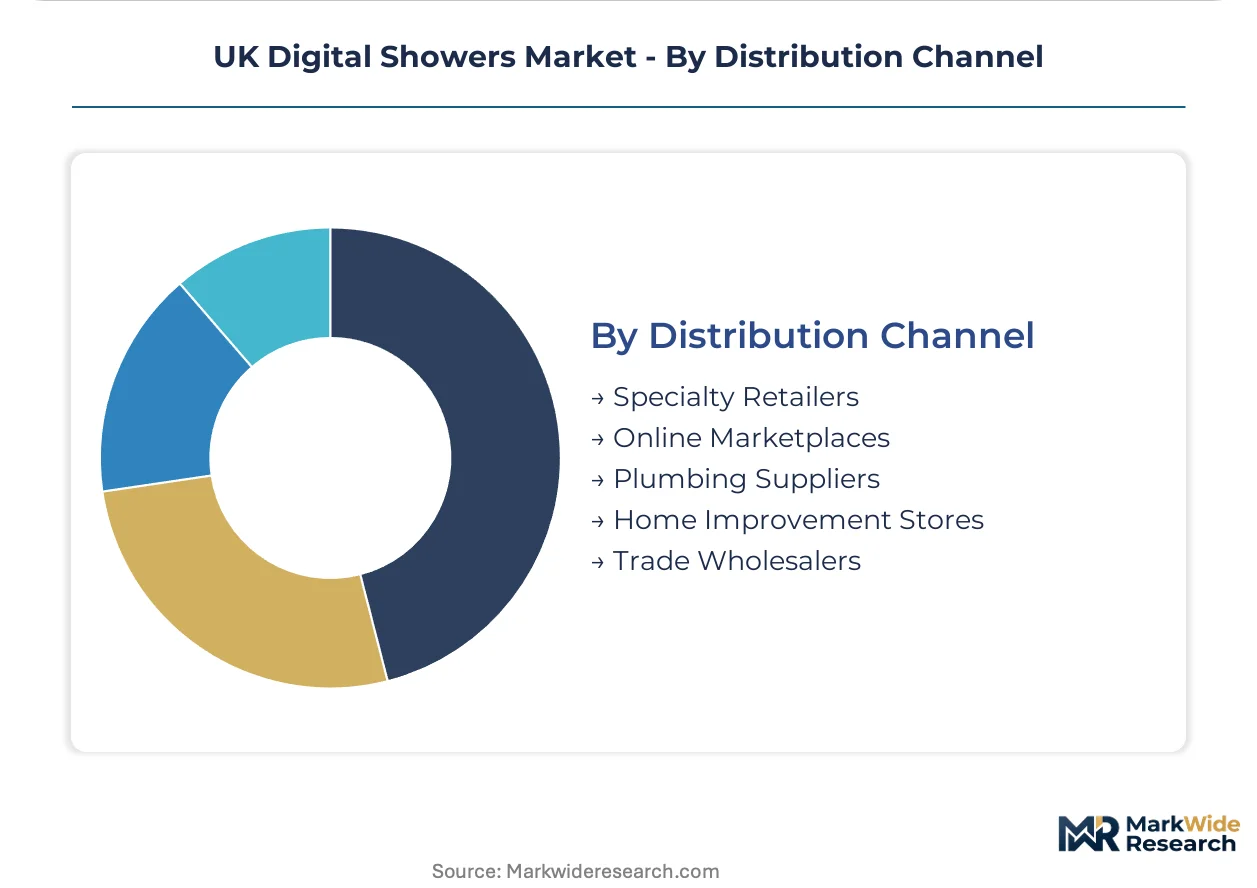
Merchant channel consolidation compresses regional distributor influence while national accounts teams capture specification authority in volume developments.
- Plumbing Suppliers:Trade-focused merchants with technical specification support retain project-level relationships in Scotland's developer market. Mira Showers leverages British manufacturing heritage to sustain loyalty across these networks.
- Trade Wholesalers:National merchant chains with centralized procurement dominate volume shipments to Southeast England housing developers.
- Specialty Retailers:Bathroom showrooms with design consultation services capture premium residential renovation spend in London and the Home Counties.
- Online Marketplaces:Direct-to-consumer platforms serve informed buyers researching WRAS and KIWA certification details independently.
- Home Improvement Stores:Mass-market retailers with limited technical support serve basic replacement demand in value segments.
Plumbing suppliers hold the largest share; online marketplaces are gaining share fastest among digitally confident renovation customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Luxury residential developers and social housing retrofit programs concentrate demand across distinct UK geographies, with regulatory compliance requirements varying by local authority interpretation of national standards.
London and Southeast England
Zone 2-4 luxury residential developments and Kent-Surrey-Essex new-build corridors absorb the highest volume shipments of thermostatic digital systems. Building Regulations Part G temperature mandates eliminate traditional mixer alternatives from all compliant wet room specifications. Merchant channel consolidation concentrates procurement decisions through national accounts teams serving volume developers.
Midlands
Independent regional merchants retain specification influence through technical support services in Birmingham and Leicester renovation markets. Victorian-era housing stock with gravity-fed systems creates demand for pump-assisted digital units. KIWA certification delays freeze inventory capital for manufacturers serving this replacement-heavy segment.
North England
Ofwat consumption reduction mandates open specification pathways for flow-optimized digital showers in Manchester and Leeds council-owned retrofit programs. Social housing decarbonization drives volume demand for sub-8 litre certified performance units. Local authority sustainability targets accelerate connected bathroom fixture adoption in multi-unit residential blocks.
Scotland
Edinburgh boutique hotel developments specify Wi-Fi enabled thermostatic systems as guest experience differentiators in premium room categories. Local merchant networks retain project-level relationships through specification support services that national chains cannot replicate. Scottish Building Standards Section 4 water efficiency requirements exceed England-Wales baselines.
Wales and Northern Ireland
Rural housing stock with combi boiler installations favors unpumped high-pressure mixer units in Cardiff and Belfast replacement markets. Devolved building control authorities interpret Part G amendments with varying enforcement timelines. Smaller developer markets limit volume concentration but sustain margin pools in premium one-off residential projects.
UK Digital Showers Market Competitive Landscape
Player mix skews toward British heritage manufacturers and Japanese-German precision engineering specialists competing through certification depth and smart home integration capabilities. Three strategic archetypes dominate: domestic manufacturers leveraging WRAS-KIWA infrastructure proximity, international specialists with thermostatic valve heritage, and scale-driven volume suppliers serving replacement markets. Competitive moves concentrate on certification timeline acceleration and voice-assistant ecosystem partnerships.
Among British-heritage manufacturers, Mira Showers, Aqualisa, and Triton Showers occupy distinct positioning vectors. Mira Showers exemplifies the trade-channel-loyalty archetype through sustained merchant network relationships. Aqualisa represents the smart-home-integration specialist tier with app-controlled thermostatic positioning. Triton Showers anchors the value-engineered replacement market segment. International specialists including Roca UK Bathrooms and Kohler compete through design-forward premium positioning in London luxury developments.
| Leading Market Players |
|---|
| Roca UK Bathrooms |
| Dornbracht |
| Mira Showers |
| Lixil Corporation |
| Kohler |
| Aqualisa |
| Roman Limited |
| Toto Ltd |
| Triton Showers |
| Others |
Pricing and Supply Chain Analysis
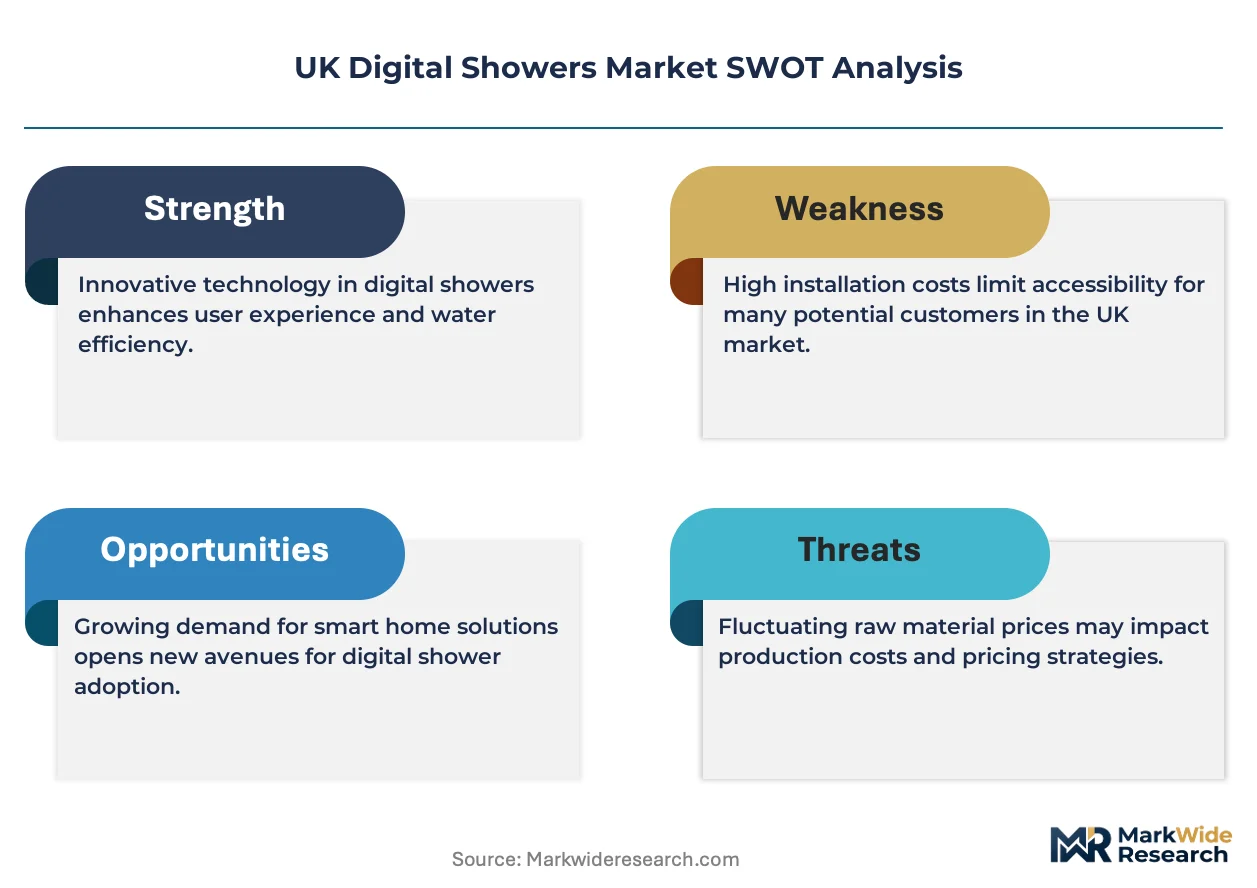
Long-term offtake agreements between UK merchant chains and British manufacturers lock in both thermostatic valve supply access and price visibility across 18-24 month procurement cycles. These arrangements insulate volume developers from London Metal Exchange copper volatility while compressing margin flexibility for mid-tier assemblers without equivalent scale.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate procurement between UK assemblers and brass foundry suppliers. Three-tier pricing structure across KIWA-certified premium, WRAS-baseline standard, and uncertified economy levels separates specification tiers. Pricing pressure stems from semiconductor cost deflation enabling app functionality at mid-market points. Social housing retrofit programs exhibit highest price sensitivity; London Zone 2-4 luxury developers show lowest.
Supply Chain Analysis
Solenoid actuator supply from German and Italian specialist manufacturers creates a chokepoint for UK digital shower assemblers. Component sourcing draws from China for Wi-Fi modules, Germany for precision valves, and Italy for electronic controllers. Single-source vulnerability concentrates in thermostatic cartridge supply. Distribution runs through national merchant chains with centralized procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat story. KIWA certification entrenchment creates switching costs that freeze out unqualified competitors for 12-18 month laboratory cycles.
For Market Incumbents: Secure KIWA testing queue priority through advance capacity reservation at British laboratories. Deepen backward integration into brass casting to offset London Metal Exchange volatility. Channel control through merchant network technical support teams defends against emerging smart-home specialists. For New Entrants and Emerging Players: Lead with voice-assistant integration protocols as the wedge into senior living facility specifications. Northern England social housing retrofit programs represent the most penetrable geography. Direct-to-installer digital training platforms bypass merchant channel consolidation. For Investors and Strategic Acquirers: British-heritage manufacturers with dormant KIWA infrastructure and underutilized foundry capacity present the strongest acquisition profile. Long-term viability hinges on heat pump transition timeline clarity. Watch Ofwat consumption mandate enforcement intensity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| KIWA Certification Acceleration | Compresses 18-month laboratory queues to secure specification in premium developments. |
| Voice Assistant Protocol Integration | Opens Amazon Alexa and Google Home ecosystem positioning beyond standalone apps. |
| Backward Integration into Brass Casting | Captures margin from London Metal Exchange copper price volatility exposure. |
| Social Housing Retrofit Partnership | Locks volume offtake through Ofwat-mandated council programs across Northern England. |
| Installer Digital Training Platform | Bypasses merchant channel consolidation with direct competency development. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with product development directors at British manufacturers, merchant category managers, and KIWA laboratory technical assessors; and secondary validation against Building Regulations Part G amendment records, WRAS approval databases, and Ofwat consumption reduction policy filings. Bottom-up shipment data from merchant networks triangulated with top-down housing completion statistics across Southeast England corridors.
Across the analysis window, forecasts model product type segmentation by thermostatic digital, thermostatic mixer, and manual digital tiers; technology stratification across Wi-Fi enabled, app controlled, and voice control categories; and use case dimensions spanning residential renovation, wet room installation, and hotel suite specifications. CAGRs derive from regression analysis against housing starts, regulatory amendment timelines, and semiconductor cost curve trajectories. Heat pump transition uncertainty and social housing decarbonization program scale represent key forecast sensitivity inputs.
Forecasts assume regulatory continuity in UK Building Regulations Part G and Scottish Building Standards Section 4 regimes; material policy shifts around water efficiency thresholds or heat pump transition deadlines would require re-modeling. Practitioners should keep alternative scenarios live as Ofwat mandate enforcement intensity and merchant channel consolidation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Powered Lawn Mowers Market
Household Items
Steam Cleaners Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Replacement Sheets Market
Household Items
Insulated Water Bottles Market
Household Items
Middle East and Africa Air Purifier Market
Household Items
Folded Tissues Market
Household Items
Brush Cover Market
Household Items
Chest Freezers Market
Household Items
Fine Mist Sprayer Market
Household Items
Drain Cleaners Market
Household Items
Aquarium Hydrometers Market
Household Items
Insulated Tumblers Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
Home Use Air Purifiers Market
Household Items
Russia Residential Water Heaters Market