
 Can Opener Market | 2026-2036
Can Opener Market Size, Share, and Industry Trends Forecast 2026-2036
Can Opener Market Outlook
ISO 8442 kitchen utensil certification for blade corrosion resistance is collapsing the supplier base to manufacturers with metallurgical testing capabilities. Edlund Company, LLC leverages its Wisconsin-based foundry operations to control stainless steel quality from melt to finished blade. Hamilton Beach Brands, Inc. anchors the electric segment through direct retail partnerships with mass-market chains. OXO differentiates via ergonomic design patents that command premium placement in specialty housewares channels.
A can opener is a mechanical cutting device employing a rotating wheel and serrated blade to puncture and sever metal container lids, with blade hardness typically rated at 52-58 HRC for repeatable performance. Its primary commercial purpose is safe, efficient access to shelf-stable food contents in high-throughput foodservice environments. Electric can openers lead the value pool due to motor and gear assembly complexity, while ergonomic designs represent the fastest-growing type segment as aging populations and accessibility standards reshape household purchasing. Stainless steel dominates material selection for professional kitchens where NSF/ANSI sanitation protocols require non-porous, dishwasher-safe surfaces.
FDA food-contact substance regulations govern blade coatings and handle polymers, while NSF/ANSI standards 2 and 8 certify equipment for commercial food zones. The EU RoHS directive restricts cadmium and lead in electrical components, affecting export-bound electric models. California Proposition 65 labeling requirements create compliance friction for silicone-grip imports. Stakeholders must monitor evolving state-level chemical disclosure rules and decide whether to standardize formulations globally or maintain regional SKUs.
Market Dynamics
ISO 8442 kitchen utensil certification for blade corrosion resistance is collapsing the supplier base to manufacturers with metallurgical testing capabilities, reshaping competitive positioning across the value chain.
Growth Catalysts
- FDA food-contact material rules:Stainless steel sourcing requirements from the US regulator are accelerating replacement cycles in commercial kitchens seeking compliant equipment upgrades.
- NSF/ANSI sanitation protocols:Non-porous, dishwasher-safe surface mandates in professional foodservice environments are concentrating demand toward certified stainless steel construction.
- Ergonomic design patents:Accessibility standards and aging demographics are pulling premium household purchases toward specialized handle geometries and reduced-effort mechanisms.
Market Restraints
- Stainless steel input volatility:Nickel and chromium price swings squeeze margin structures for blade manufacturers without captive melt-to-finish operations.
- Supplier base concentration:Metallurgical testing capabilities required for ISO 8442 compliance have reduced qualified vendors to a handful of foundry-integrated producers.
- Manual-to-electric substitution:Battery-powered and rechargeable alternatives are compressing addressable volume for traditional countertop electric units in residential segments.
Strategic Opportunities
- Underpenetrated foodservice automation:European commercial kitchens lag North American replacement rates, creating white space for NSF/ANSI-certified equipment exporters.
- EU RoHS directive tailwinds:Cadmium and lead restrictions in electrical components are forcing redesigns that favor compliant manufacturers with established supply chain controls.
- Specialty housewares channel expansion:Direct-to-retailer partnerships with premium kitchen boutiques are bypassing mass-market margin compression for design-differentiated products.
Industry Challenges
- Certification timeline compression:ISO 8442 and NSF/ANSI parallel testing requirements extend product development cycles by 8-14 months for new blade formulations.
- Metallurgical talent scarcity:Hardened steel expertise for 52-58 HRC blade production concentrates with aging specialists, constraining quality control scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Can Opener Market |
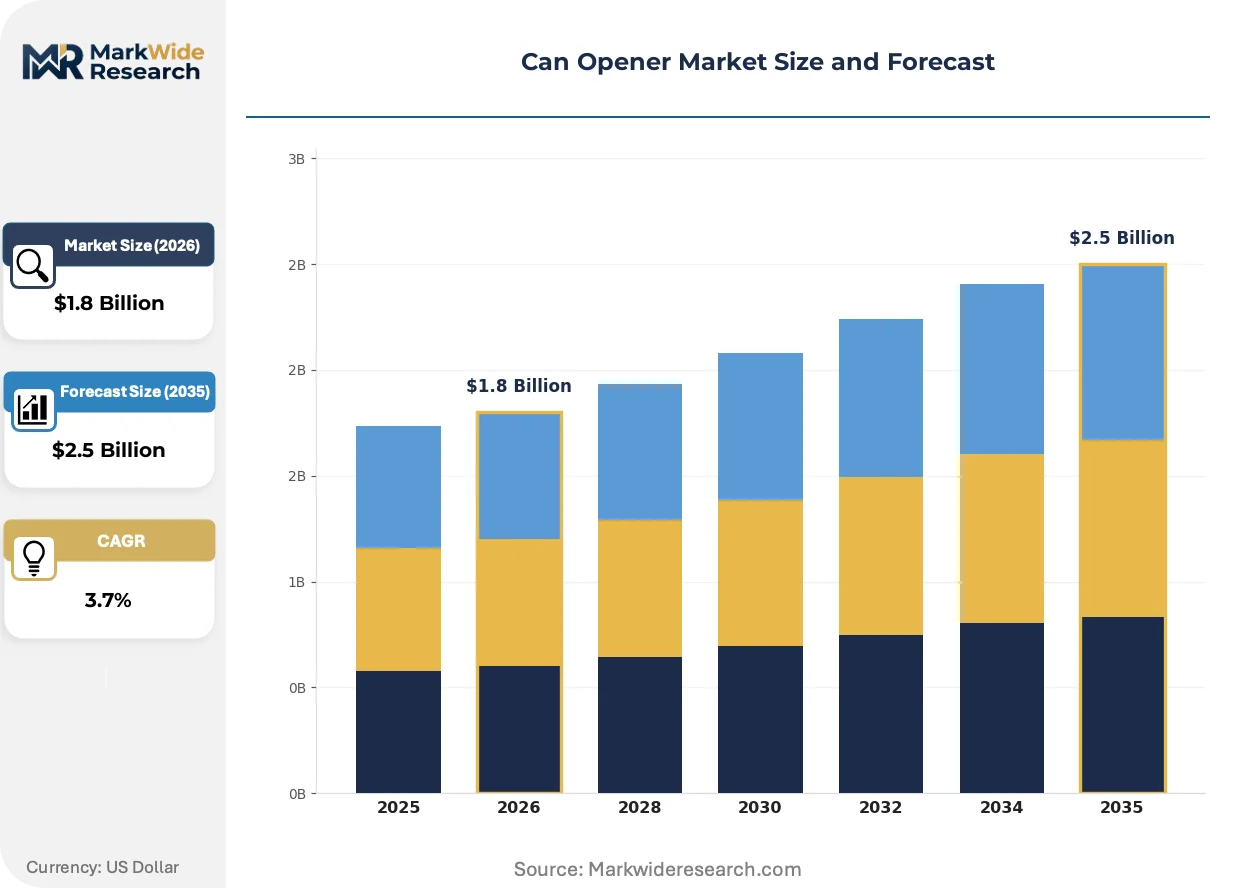
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Manual, Electric, Ergonomic, Standard Material: Stainless Steel, Plastic, Aluminum, Silicone Design: Traditional, Compact, Multi-Functional, Specialty End User: Households, Restaurants, Canteens, Catering Services |
| Companies Covered | Cuisinart, KitchenAid, OXO, Proctor Silex, Kuhn Rikon, BLACK+DECKER, Zyliss, Edlund Company, LLC, Hamilton Beach Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Can Opener Market Strategic Shifts
Ergonomic and automation technologies are fragmenting traditional product categories while regulatory harmonization pressures force simultaneous multi-jurisdiction compliance investments.
Magnetic lid-lift mechanisms are fragmenting the safety-feature landscape in electric can openers. High-volume foodservice operators in the United States are specifying hands-free lid removal at accelerating rates. This capability is fragmenting procurement specifications across hospital cafeterias, school nutrition programs, and chain restaurant commissaries previously tolerant of manual lid handling.
REACH substance restrictions from ECHA are reshaping polymer selection for handle grips and electrical housings in export-bound equipment. Manufacturers serving EU markets must reformulate silicone and ABS compounds to eliminate SVHC candidates. Electric models with integrated knife sharpeners and bottle openers face the steepest reformulation burdens due to multi-material complexity.
Certification-driven preference shifts are compressing supplier qualification timelines. Foodservice distributors now require ISO 8442 documentation prior to SKU authorization, displacing informal vendor relationships. This behavioral change is most visible in United States group purchasing organization contracts, where metallurgical certificates have become mandatory bid attachments.
Can Opener Market Segmentation
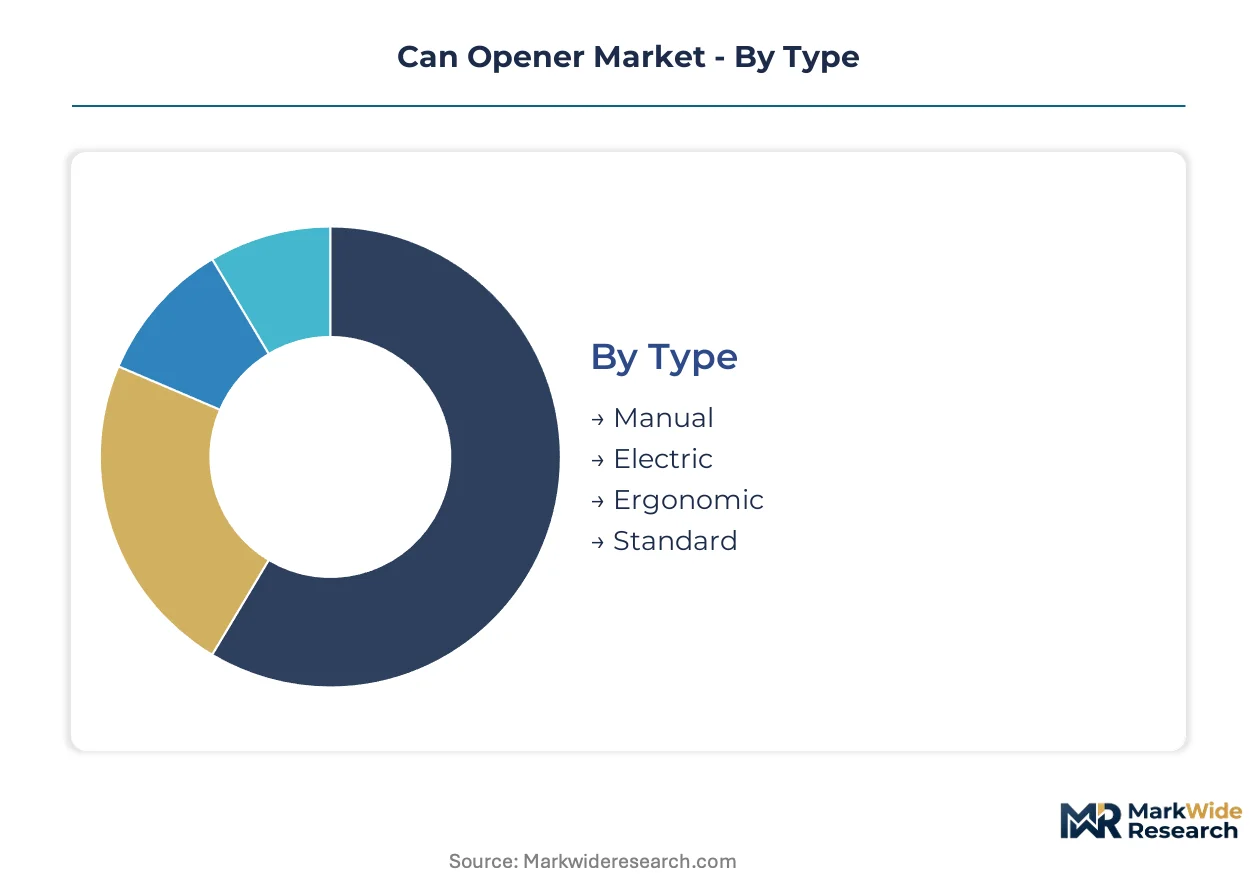
Regulatory certification requirements fragment procurement specifications across the can opener market, concentrating volume in segments that satisfy ISO 8442 metallurgical standards and NSF/ANSI sanitation protocols. Segmentation choices directly determine compliance pathways and supplier qualification timelines for foodservice operators.
Type:
FDA food-contact material rules and NSF/ANSI standards 2 and 8 create divergent compliance burdens across mechanism categories, with electric units facing additional FCC electromagnetic interference testing for motor assemblies.
- Manual:Rotating wheel and serrated blade construction rated at 52-58 HRC hardness dominates high-volume foodservice environments where durability outweighs convenience. Commercial kitchens in the United States specify manual units for backup redundancy when electrical infrastructure fails.
- Electric:Motor and gear assembly complexity commands premium positioning in residential channels, though battery-powered alternatives are compressing countertop unit volumes. Mass-market retail partnerships anchor distribution for established brands with direct supplier relationships.
- Ergonomic:Reduced-effort mechanisms with specialized handle geometries serve aging populations and accessibility standards. Specialty housewares channels pull premium household purchases toward patented designs.
- Standard:Basic pivot-and-cut construction without auxiliary features occupies economy tiers in general merchandise retail.
Established volume favors manual units in commercial procurement; emerging adoption favors ergonomic designs in aging demographics.
Material:
Cost tier differentiation separates professional-grade specifications from residential convenience purchases, with metallurgical testing capabilities determining supplier eligibility.
- Stainless Steel:Non-porous, dishwasher-safe surfaces satisfy NSF/ANSI sanitation protocols for professional food zones. Foundry-integrated manufacturers with captive melt-to-finish operations control blade quality from raw material through hardening.
- Plastic:Polymer selection for housings and handles faces REACH substance restrictions from ECHA for export-bound equipment. ABS compounds require reformulation to eliminate SVHC candidates in EU markets.
- Aluminum:Lightweight construction serves compact and travel-oriented designs where mass reduction outweighs corrosion resistance requirements.
- Silicone:Grip materials trigger California Proposition 65 labeling requirements for silicone imports, creating compliance friction for non-domestic suppliers.
Professional procurement concentrates in stainless steel; residential convenience purchases tolerate mixed-material construction.
Design:
Application context determines form factor selection, with space constraints and task multiplicity driving specification divergence across end-use environments.
- Traditional:Full-size pivot construction with integrated bottle openers dominates legacy household replacement cycles.
- Compact:Foldable and storable configurations serve recreational vehicle, camping, and small-apartment installations where counter space is constrained.
- Multi-Functional:Integrated knife sharpeners and bottle openers face steepest reformulation burdens under EU RoHS directive due to multi-material complexity. Electric models with additional utilities concentrate in premium residential segments.
- Specialty:Side-cut mechanisms and magnetic lid-lift configurations fragment safety-feature specifications for hands-free operation in hospital cafeterias and school nutrition programs.
Volume procurement favors traditional and compact formats; specification innovation favors multi-functional and specialty designs.
End User:
Customer type segmentation aligns certification requirements with operational scale, separating institutional procurement discipline from discretionary household purchasing.
- Households:Discretionary replacement cycles respond to ergonomic innovation and design differentiation rather than regulatory mandates. Specialty housewares channels capture premium positioning through direct-to-retailer partnerships.
- Restaurants:High-throughput foodservice environments in North American chains drive replacement demand for ISO 8442-certified equipment. Group purchasing organization contracts now require metallurgical certificates as mandatory bid attachments.
- Canteens:Institutional feeding operations in healthcare and education sectors specify hands-free lid removal capabilities at accelerating rates, fragmenting procurement specifications previously tolerant of manual handling.
- Catering Services:Mobile food preparation contexts prioritize compact and durable manual units over electric alternatives dependent on reliable power infrastructure.
Procurement discipline concentrates in restaurants and canteens; price sensitivity dominates household and catering segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-volume foodservice operators in the United States drive replacement demand for certified equipment, while export-bound manufacturers navigate divergent metallurgical and chemical compliance regimes across destination markets.
United States
Commercial kitchens in restaurant chains and institutional feeding operations specify ISO 8442-certified manual units for backup redundancy. FDA food-contact material rules govern stainless steel blade sourcing for NSF/ANSI protocol compliance. Wisconsin hosts foundry-integrated producers controlling melt-to-finish quality for blade hardening at 52-58 HRC.
Germany
Professional foodservice equipment distributors emphasize REACH-compliant polymer formulations for handle grips in export-bound electric models. ECHA substance restrictions force reformulation of silicone and ABS compounds to eliminate SVHC candidates. Industrial clusters in North Rhine-Westphalia concentrate metallurgical testing capabilities for EU market access.
China
Manufacturing scale supports cost-competitive manual unit production for global private-label programs. GB standards for kitchen utensils align with ISO frameworks for corrosion resistance certification. Yangtze River Delta fabricators supply blade components to brands seeking captive melt-to-finish integration.
Japan
Aging demographics pull household purchases toward ergonomic designs with reduced-effort mechanisms. METI guidelines on product safety influence electric can opener electromagnetic compatibility requirements. Kansai region specialty housewares channels capture premium positioning for patented handle geometries.
United Kingdom
Group purchasing organization contracts for hospital cafeterias and school nutrition programs specify hands-free lid removal capabilities. CE marking requirements intersect with evolving post-EU regulatory alignment for food-contact materials. Midlands-based distributors consolidate procurement specifications for ISO 8442 documentation.
Can Opener Market Competitive Environment
Player mix skews toward diversified housewares conglomerates with foundry-integrated specialists occupying premium commercial tiers. Market structure concentrates volume among brands with direct retail partnerships and captive metallurgical capabilities. Three archetypes dominate: mass-market electric manufacturers, ergonomic design specialists, and commercial-grade fabricators with in-house steel production. Competitive moves center on certification-driven supplier consolidation and specialty channel partnerships bypassing mass-market margin compression.
Among diversified housewares conglomerates, Hamilton Beach Brands, Inc. and BLACK+DECKER occupy positions anchored by mass-market retail distribution networks. Edlund Company, LLC exemplifies the foundry-integrated archetype with Wisconsin-based operations controlling quality from raw material through finished blade. OXO sits within the ergonomic design tier, commanding premium placement through patented handle geometries in specialty housewares channels.
| Leading Market Players |
|---|
| Cuisinart |
| KitchenAid |
| OXO |
| Proctor Silex |
| Kuhn Rikon |
| BLACK+DECKER |
| Zyliss |
| Edlund Company, LLC |
| Hamilton Beach Brands, Inc. |
| Others |
Value Chain & Pricing Dynamics
Battery-powered alternatives replacing countertop electric units are simultaneously redrawing procurement geography toward Asian battery-cell suppliers and compressing pricing power for legacy motor-gear assembly manufacturers. This substitution dynamic concentrates margin capture with cell producers while forcing traditional electric brands into defensive cost restructuring.
Pricing Analysis
Cost-plus contracts indexed to nickel and chromium LME benchmarks dominate blade procurement between foundry-integrated suppliers and North American foodservice distributors. Three-tier pricing structure across ISO 8442-certified premium, NSF/ANSI-compliant standard, and uncertified economy levels reflects metallurgical testing investment recovery. Cost compression in manual stainless steel segments is intensifying because Yangtze River Delta fabricators are absorbing margin to secure GPO contract volume. Quick-service restaurant chains exhibit highest price sensitivity; hospital systems with federal nutrition funding show lowest.
Supply Chain Analysis
Just-in-time blade component flows from Wisconsin foundries contrast with strategic stockpiling of nickel cathode by cell producers serving battery-powered alternatives. Geographic supply concentration centers on China for stamped blade components, Germany for REACH-compliant polymer formulations, and the United States for melt-to-finish stainless steel hardening. Raw material dependencies rest on nickel-chromium alloys, ABS compounds, and lithium-ion cells. Single-source vulnerability concentrates in ISO 8442-certified foundry capacity. Distribution runs through foodservice distributors and mass-market retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat story where ISO 8442 certification entrenchment creates switching costs that lock foodservice operators into qualified supplier relationships. The structural advantage compounds as metallurgical talent scarcity extends replacement timelines for non-compliant vendors.
For Market Incumbents: Shield market position by accelerating captive foundry capacity expansion in Wisconsin to pre-empt competitor qualification timelines. Deepen backward integration into nickel-chromium melt operations before ECHA REACH restrictions tighten raw material sourcing. Battery-powered substitute entrants from consumer electronics represent the primary threat vector.
For New Entrants and Emerging Players: ISO 8442 fast-track partnerships with Yangtze River Delta fabricators offering pre-certified blade components lower barrier entry for ergonomic design specialists. European commercial kitchens lag North American replacement rates, creating the most penetrable geography. Direct-to-retailer specialty housewares partnerships bypass mass-market margin compression.
For Investors and Strategic Acquirers: FDA food-contact material rule enforcement reshapes the acquisition landscape toward foundry-integrated targets with captive metallurgical capabilities. Long-term viability centers on regulatory entrenchment durability across 5-10 year equipment replacement cycles. Acquisition target archetype: mid-cap specialists with ISO 8442 documentation and GPO contract relationships. Signal to monitor: Group purchasing organization contract renewal rates for metallurgical certificate requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Integration | Captive melt-to-finish operations secure ISO 8442 compliance and blade hardness consistency. |
| Ergonomic Patent Portfolio | Specialized handle geometries command premium placement in aging-demographic household channels. |
| REACH Reformulation Program | ECHA-compliant polymer selection eliminates SVHC candidates for EU market access. |
| GPO Contract Expansion | Group purchasing organization relationships embed mandatory metallurgical certificate requirements. |
| Battery-Powered Line Launch | Rechargeable alternatives capture residential volume shifting from countertop electric units. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foodservice procurement directors, commercial kitchen equipment distributors, foundry operations managers, and NSF/ANSI certification auditors. Secondary validation drew from FDA food-contact substance filings, ECHA REACH substance restriction updates, SEC 10-K disclosures from diversified housewares conglomerates, and customs import records for stainless steel kitchen utensil classifications. Bottom-up volume estimates from foodservice operator replacement cycles were triangulated against top-down market sizing from retail channel audit data.
Across the analysis window, the forecasting framework modeled segmentation dimensions including mechanism type, material grade tier, end-user operational scale, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis and penetration rate modeling. Industry-specific forecast inputs incorporated nickel price volatility assumptions and ISO 8442 certification timeline compression effects.
Decision-makers should treat outputs as directional under stable regulatory enforcement and raw material supply continuity assumptions; material deviation would warrant model refresh. Specific risk factors include ECHA SVHC list expansion, FDA stainless steel sourcing rule amendments, and lithium-ion cell cost trajectories. Revision becomes warranted when battery-powered alternative penetration crosses 25% of residential segment volume.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Desktop Air Purifier Market
Household Items
Portable Humidifiers Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
USA Residential Cotton Candy Maker Market
Household Items
Europe Ice/Cooler Box Market
Household Items
Jet Hand Dryer Market
Household Items
Canada Digital Showers Market
Household Items
Toilet Hygiene Products Market
Household Items
Insulated Lunch Box Market
Household Items
Saudi Arabia Cookware Market
Household Items
Deodorizer Bag Market
Household Items
North America Ceramic Barbeque Grill Market
Household Items
Smart Drying Racks Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Hands-Free Faucet Market
Household Items
North America Glassware Market