
 North America Ceramic Barbeque Grill Market | 2026-2036
North America Ceramic Barbeque Grill Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ceramic Barbeque Grill Market Analytics
The EPA's updated particulate emissions standards for charcoal combustion equipment is rebalancing the cost-of-entry calculus for new competitors, forcing investments in ceramic kiln redesign and airflow engineering before products reach retail shelves. Big Green Egg leverages its decades-long brand equity and proprietary ceramic formulation to sustain premium pricing across specialty outdoor retailers. Kamado Joe competes through an extensive accessory ecosystem and hinged-lid innovations that differentiate its cooking experience. Primo Ceramic Grills anchors its position with oval-shaped cooking chambers and American-made manufacturing credentials that resonate with patriotic buyer segments.
A ceramic barbeque grill consists of a thick-walled, refractory ceramic vessel—typically composed of cordierite, alumina-silicate blends, or proprietary clay composites fired at temperatures exceeding 2,000°F—that traps radiant heat and moisture to create an oven-like cooking environment with precise temperature control from 200°F to over 700°F. Freestanding units dominate residential installations due to their mobility and lower structural commitment, while built-in configurations command higher margin pools as they integrate with custom outdoor kitchen projects requiring professional installation. Charcoal fuel types retain the largest volume share among purists, though gas hybrid systems represent the fastest-growing fuel segment as convenience-oriented buyers seek ignition speed without sacrificing ceramic thermal performance.
The Consumer Product Safety Commission enforces stability and tip-over standards that shape base-weight requirements and wheel-lock mechanisms, while CSA Group certification governs gas-fuel compatibility testing for hybrid models entering Canadian distribution. State-level air quality districts in California and Texas impose additional seasonal burn restrictions that manufacturers must navigate through adjustable vent designs and cleaner-burning accessory fuels. Stakeholders must monitor evolving municipal outdoor appliance codes and building permit requirements for built-in installations, as these local frameworks increasingly dictate whether premium ceramic grills qualify for new construction incentives or face setback limitations.
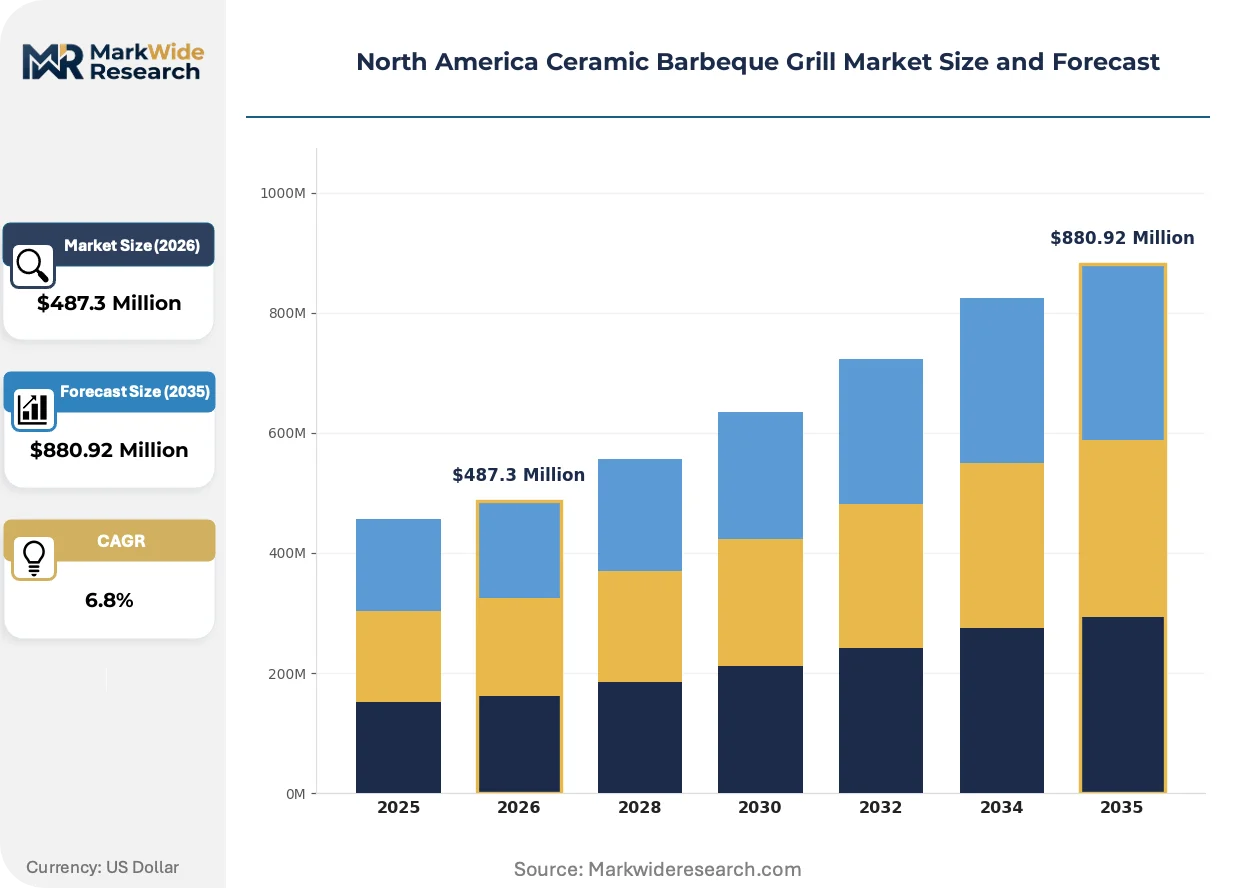
Market Dynamics
The EPA's updated particulate emissions guidelines for charcoal combustion equipment is compelling manufacturers to redesign airflow systems and ceramic compositions before products reach retail shelves, fundamentally altering the cost-of-entry calculus for new competitors.
Growth Catalysts
- Residential Patio Kitchen Investment:Homeowners in Texas and Florida are installing permanent outdoor cooking infrastructure, creating sustained replacement cycles and premium upgrade demand for ceramic grills with integrated ventilation.
- REACH Compliance Alignment:Manufacturers serving cross-border markets are reformulating ceramic composites to meet European chemical safety standards, which simultaneously satisfies emerging state-level air quality requirements in California and Texas.
- Cordierite-Alumina Blends:Advanced refractory ceramics fired above 2,000°F now trap radiant heat more efficiently, extending temperature precision from 200°F to over 700°F and attracting serious barbecue enthusiasts.
Market Restraints
- Specialized Kiln Infrastructure:Domestic production of thick-walled ceramic vessels requires capital-intensive firing equipment that few North American suppliers possess, concentrating manufacturing in specific regional clusters.
- Charcoal Supply Volatility:Lump hardwood charcoal prices fluctuate with forestry harvest cycles and transportation fuel costs, squeezing margins for fuel-dependent grill operators.
- CSA Group Certification Burden:Gas-hybrid models entering Canadian distribution face extended testing timelines for fuel compatibility, delaying revenue recognition by multiple quarters.
Strategic Opportunities
- Gas-Hybrid Convenience Segment:Convenience-oriented buyers in the southeastern United States are adopting ignition-speed solutions without sacrificing ceramic thermal performance, representing the fastest-growing fuel category.
- Municipal Incentive Alignment:Local building permit frameworks in high-growth Sun Belt metros increasingly qualify premium built-in ceramic grills for new construction incentives when paired with adjustable vent designs.
- Smart-Temperature Convergence:Bluetooth-enabled thermocouples paired with ceramic thermal mass are unifying precision cooking control with traditional charcoal flavor profiles.
Industry Challenges
- Refractory Ceramic Engineering Talent:The specialized knowledge required for alumina-silicate formulation and kiln firing protocol development remains concentrated among aging workforce cohorts in traditional ceramics regions.
- Multi-Jurisdiction Compliance Sequencing:Manufacturers must navigate overlapping EPA emissions standards, CPSC stability requirements, and state-level seasonal burn restrictions simultaneously, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ceramic Barbeque Grill Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freestanding, Built-in, Portable, Tabletop Fuel Type: Charcoal, Wood, Gas, Electric End User: Residential, Commercial, Hospitality, Recreational Size: Small, Medium, Large, Extra Large |
| Companies Covered | Big Green Egg, Kamado Joe, Primo Ceramic Grills, Vision Grills, Char-Griller, Blaze, Monolith, Pit Boss, Broil King, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ceramic Barbeque Grill Market Evolving Landscape
Active innovation across fuel systems, thermal engineering, and distribution channels is compressing traditional product lifecycles while opening new buyer segments previously excluded by skill barriers or installation complexity.
Smart-temperature monitoring systems embedded in ceramic grill lids are unifying digital precision with analog cooking tradition. Enthusiast buyers in Texas and Florida are adopting these interfaces fastest, compressing the learning curve for low-and-slow barbecue techniques that previously required years of manual vent adjustment experience.
California Air Resources Board seasonal burn restrictions are forcing manufacturers to engineer adjustable vent designs and cleaner-burning accessory fuels. The regulatory pressure most affects charcoal purists in the western United States, who are responding by demanding hybrid fuel flexibility that maintains ceramic thermal performance during restricted burning periods.
Specialty outdoor retailers are ceding volume to direct-to-consumer channels for replacement parts and accessory ecosystems. Homeowners completing custom outdoor kitchen projects in the southeastern United States now research built-in configurations online before engaging contractors, shifting specification influence from installers to end-users.
North America Ceramic Barbeque Grill Market Segmentation
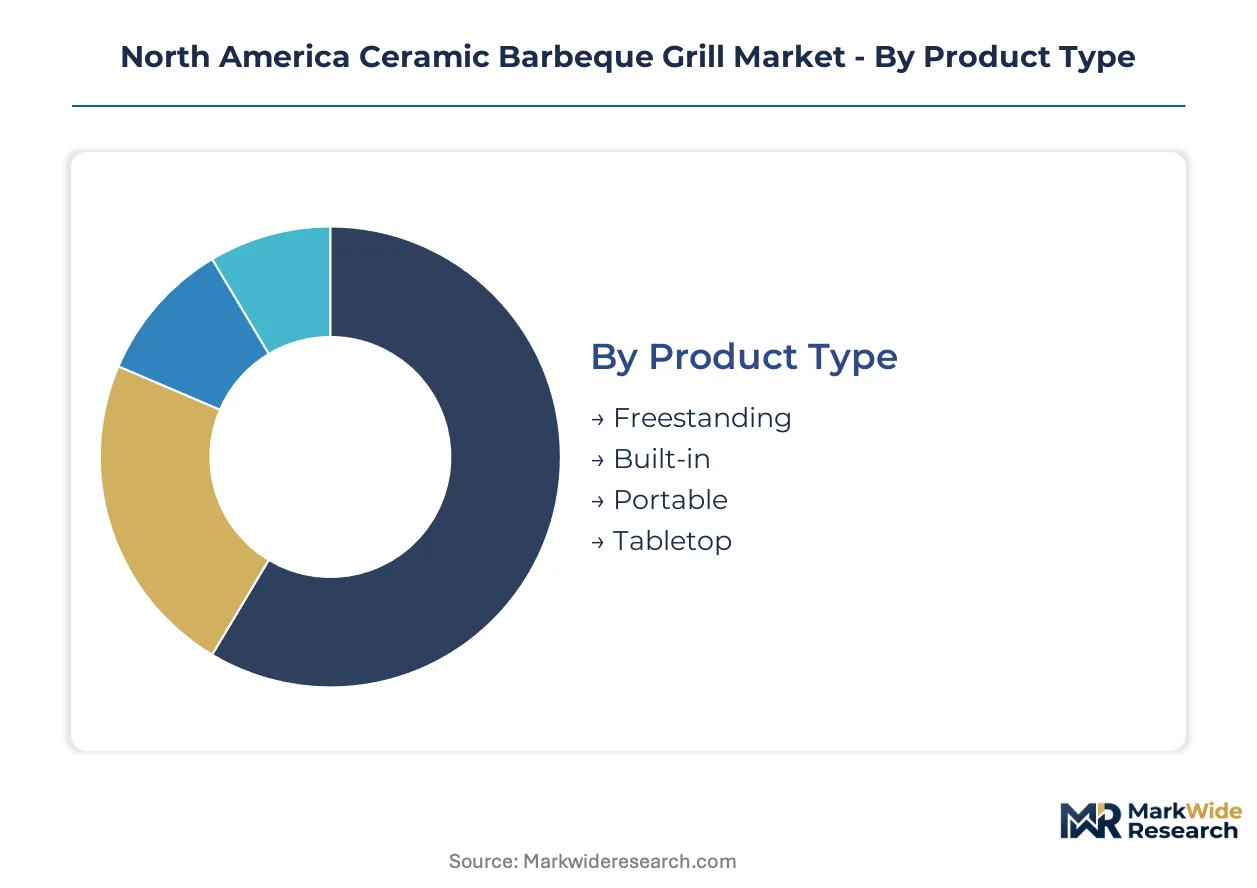
Ceramic barbeque grill segmentation reflects divergent buyer priorities across installation permanence, fuel ritual, and cooking scale. Manufacturers configure product lines to capture value pools ranging from mobile entry-level units to integrated outdoor kitchen centerpieces requiring professional installation and ventilation engineering.
Product Type:
Customization intensity varies sharply across this category, from mass-produced portable units to bespoke built-in configurations requiring site-specific dimensional coordination.
- Freestanding:Self-supporting units with wheeled bases and hinged lids dominate residential patio installations where mobility and lower structural commitment matter. Demand concentrates in Texas and Florida residential markets, where homeowners prioritize relocation flexibility for seasonal layout changes and property resale scenarios.
- Built-in:Fixed installations integrated into custom outdoor kitchen cabinetry command premium margin pools through professional specification and ventilation integration. Demand concentrates in southeastern United States custom construction projects, where municipal building codes increasingly govern setback requirements and gas line accessibility.
- Portable:Compact ceramic vessels designed for tailgating and camping applications sacrifice thermal mass for transportability. These units appeal to recreational buyers in the western United States seeking burn restriction compliance during seasonal wildfire risk periods.
- Tabletop:Minimal-footprint designs target apartment dwellers and balcony cooking environments with reduced charcoal capacity. Urban buyers in California metros favor these configurations where space constraints and air quality district regulations intersect.
Most installed capacity flows through Freestanding. Expansion is steepest in Built-in.
Fuel Type:
Cost tier stratification separates purist charcoal systems from convenience-oriented hybrid configurations, with electric representing a distinct value proposition for regulatory-constrained environments.
- Charcoal:Lump hardwood and briquette systems retain the largest volume share among enthusiast segments prioritizing smoke flavor development and traditional barbecue technique. EPA particulate emissions guidelines are compelling manufacturers to redesign airflow geometry and ceramic porosity to reduce incomplete combustion byproducts.
- Wood:Split hardwood and pellet-fed configurations appeal to competition barbecue practitioners and smoke-forward culinary applications. Demand concentrates in Texas Hill Country and Kansas City metro areas where regional barbecue styles specify wood species and combustion duration.
- Gas:Propane and natural gas hybrid systems represent the fastest-climbing fuel category as convenience-oriented buyers in the southeastern United States seek ignition speed without sacrificing ceramic thermal retention properties. CSA Group certification requirements extend Canadian market entry timelines for these configurations.
- Electric:Resistance-heated elements eliminate combustion emissions entirely, positioning these units for California Air Resources Board restricted burning periods and multi-family housing installations where open flame prohibitions apply.
Charcoal retains the largest installed base. Gas-hybrid configurations are gaining share fastest among new purchasers.
End User:
Application maturity separates established residential replacement cycles from emerging commercial specifications requiring durability warranties and volume throughput engineering.
- Residential:Single-family homeowners drive replacement demand through patio kitchen renovations and premium upgrade cycles, particularly in Florida and Texas where year-round grilling seasons sustain shorter product lifecycles.
- Commercial:Independent restaurants and catering operations specify heavy-duty refractory ceramics with accelerated preheat capabilities for service pressure environments.
- Hospitality:Resort and hotel properties integrate built-in configurations into poolside dining concepts and event catering infrastructure, requiring coordinated ventilation and aesthetic consistency with landscape architecture.
- Recreational:Campgrounds, RV parks, and community associations deploy shared-access units with tamper-resistant vent controls and enhanced stability engineering for unattended public use.
Residential channels move the highest unit volumes. Hospitality represents the steepest expansion trajectory for built-in specifications.
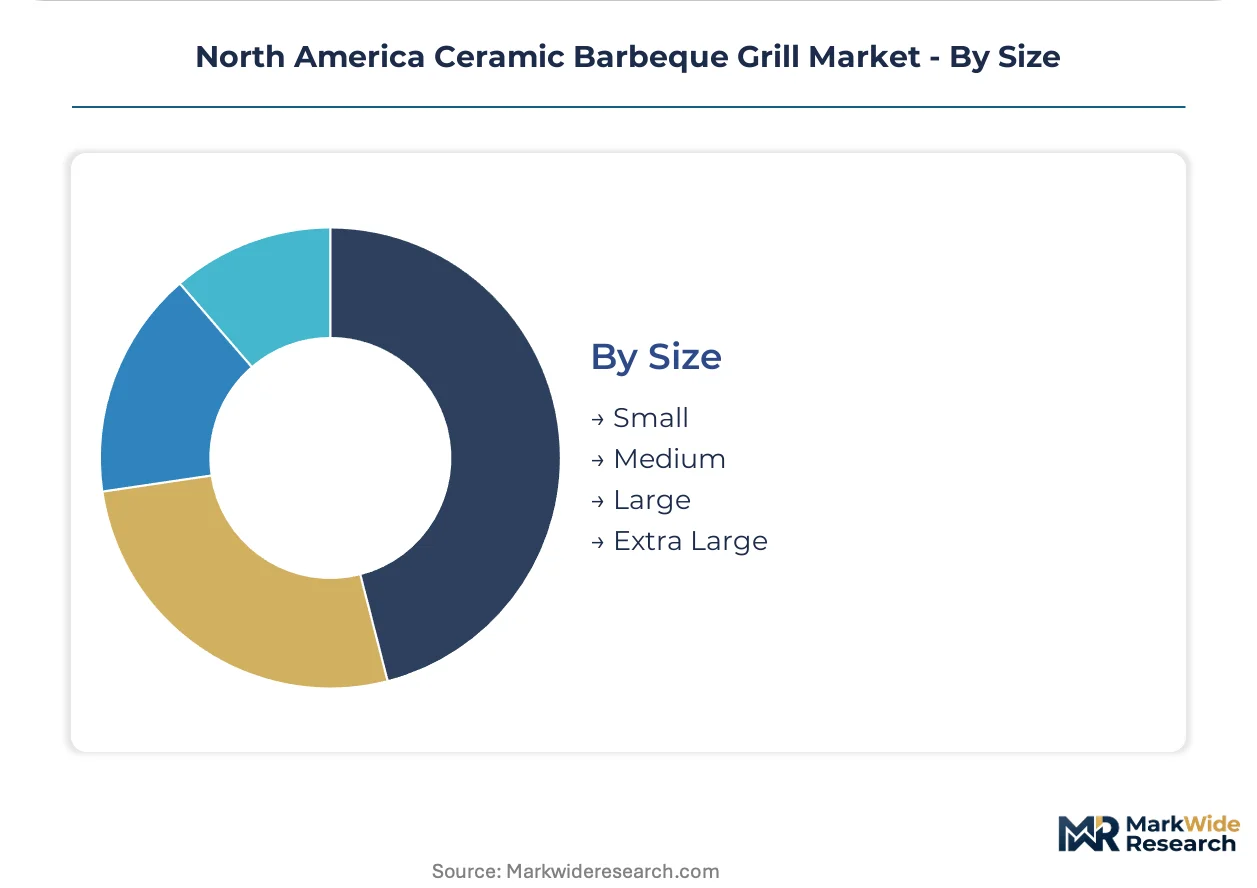
Size:
Customer type and cooking scale determine dimensional requirements, from individual meal preparation to competition-grade protein volume.
- Small:Compact cooking chambers below 14 inches in diameter serve single-person households and supplementary side-dish preparation in multi-grill installations.
- Medium:Standard 18-inch configurations balance fuel efficiency with family-scale protein capacity, dominating suburban replacement purchases across the southeastern United States.
- Large:Extended 24-inch chambers accommodate whole brisket and multiple rack configurations for enthusiast buyers hosting large gatherings and practicing competition barbecue techniques.
- Extra Large:Oversized vessels exceeding 24 inches target commercial catering and dedicated smokehouse operations requiring continuous high-volume output.
Medium dimensions anchor the installed base. Large configurations are climbing fastest among replacement buyers upgrading from entry-level ceramic grills.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refractory ceramic engineering talent concentrates in traditional manufacturing regions of the southeastern United States, anchoring production clusters while residential demand spreads across Sun Belt metros.
United States
Texas and Florida homeowners drive replacement cycles through permanent patio kitchen installations. EPA particulate emissions guidelines force ceramic kiln redesigns and airflow engineering investments before products reach retail. Atlanta and Dallas-Fort Worth anchor distribution networks serving southeastern year-round grilling markets.
California
Air quality district burn restrictions constrain charcoal purists in western metro areas. California Air Resources Board seasonal regulations accelerate demand for hybrid fuel flexibility and adjustable vent designs. Los Angeles and San Francisco Bay Area buyers favor electric and gas-hybrid configurations for multi-family housing compliance.
Canada
CSA Group certification requirements extend testing timelines for gas-hybrid models entering distribution. Ontario and Quebec residential buyers adopt ceramic thermal performance for shorter grilling seasons. Toronto and Vancouver retail channels emphasize built-in configurations for custom outdoor kitchen projects.
Mexico
Mexico City and Monterrey metros see emerging demand for compact portable units among urban apartment dwellers. National environmental standards for combustion equipment remain less stringent than EPA benchmarks. Baja California and Yucatán Peninsula resort properties specify built-in configurations for hospitality infrastructure.
North America Ceramic Barbeque Grill Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered positioning strata. The vendor base separates into three strategic archetypes: heritage ceramic formulators with decades-long brand equity, accessory-ecosystem builders competing through cooking experience differentiation, and American-made manufacturers leveraging patriotic buyer segments. Dominant competitive moves include strategic partnerships with specialty outdoor retailers and portfolio diversification into smart-temperature monitoring systems.
Among heritage ceramic specialists, Big Green Egg occupies a position exemplifying proprietary formulation advantages. Kamado Joe and Primo Ceramic Grills represent competing archetypes—one emphasizing hinged-lid innovations and accessory breadth, the other anchoring oval-shaped cooking chambers with domestic manufacturing credentials. These three companies collectively illustrate how brand equity, engineering differentiation, and geographic origin positioning fragment competitive dynamics across premium price tiers.
| Leading Market Players |
|---|
| Big Green Egg |
| Kamado Joe |
| Primo Ceramic Grills |
| Vision Grills |
| Char-Griller |
| Blaze |
| Monolith |
| Pit Boss |
| Broil King |
| Others |
Value Network & Pricing Analysis
Gas-hybrid ignition system adoption across southeastern United States markets is compressing charcoal-only premium tiers while elevating built-in configuration margins, simultaneously reshaping supplier power toward ceramic kiln operators in Georgia and Tennessee who control refractory firing capacity. This technology transition concentrates pricing leverage among heritage formulators with proprietary alumina-silicate blends while forcing commodity competitors toward accessory bundling and direct-to-consumer channel economics.
Pricing Analysis
Accessories-unbundled base configurations dominate entry-level transactions, while professional installation and ventilation engineering bundle into built-in premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates Big Green Egg's proprietary formulation from Kamado Joe's hinged-lid engineering and Char-Griller's mass-market positioning. Pricing pressure stems from EPA-mandated kiln redesign costs flowing through to retail. Residential replacement buyers in Texas and Florida show lowest price sensitivity; apartment-bound tabletop purchasers in California metros exhibit highest.
Supply Chain Analysis
Cordierite and alumina-silicate refractory supply rests on Mexican clay extraction, Chinese processed ceramic precursors, and domestic Georgia-Tennessee kiln firing clusters. Specialty hardwood charcoal for lump fuel draws from Argentine forestry operations and domestic Missouri-Ozark harvest cycles. Single-source vulnerability concentrates in high-temperature kiln infrastructure, where only three North American operators maintain 2,000°F firing capability. Distribution runs through specialty outdoor retailers for premium specification, direct-to-consumer channels for replacement parts and accessories, and contractor-direct for built-in installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EPA-regulated United States jurisdictions with escalating compliance costs and Mexican manufacturing zones with less stringent combustion equipment standards, enabling margin preservation through cross-border production strategies.
For Market Incumbents: Cement proprietary ceramic formulation advantages through captive kiln capacity additions in Georgia clay belts, insulating margin pools from EPA-driven competitor entry costs. Defend against gas-hybrid convenience displacement by embedding Bluetooth thermocouple ecosystems that lock enthusiast buyers into branded accessory orbits. Prioritize CSA Group certification pre-positioning for Canadian distribution expansion before testing timelines extend further. For New Entrants and Emerging Players: Apartment-dwelling balcony cooks in California Air Resources Board-constrained metros represent the most penetrable white-space segment, underserved by incumbent tabletop offerings optimized for southeastern suburban patios. Target electric-heated compact configurations with CARB-compliant zero-emission positioning. Pursue direct-to-consumer launch bypassing specialty retailer gatekeeping that favors heritage brand equity. For Investors and Strategic Acquirers: Valuations sit cheapest among regional kiln operators with refractory engineering talent but underdeveloped brand architecture, offering vertical integration synergies to platform acquirers. Long-term viability hinges on regulatory compliance capability rather than volume scale. Watch EPA enforcement intensity and state-level burn restriction proliferation as inflection signals for ceramic-purist versus gas-hybrid demand mix shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Ceramic Formulation Investment | Big Green Egg's decades-long refractory R&D creates kiln-firing moats that compound EPA compliance advantages. |
| Gas-Hybrid Fuel System Expansion | Kamado Joe's ignition-speed engineering captures convenience-oriented buyers without sacrificing thermal mass performance. |
| Direct-to-Consumer Channel Buildout | Specialty retailer bypass shifts specification influence from installers to end-users researching built-in configurations online. |
| Smart-Temperature Monitoring Integration | Bluetooth-enabled thermocouples unify digital precision with analog tradition, compressing low-and-slow learning curves. |
| American-Made Manufacturing Credentialing | Primo Ceramic Grills' domestic production positioning resonates with patriotic buyer segments in Texas and Florida markets. |
Research Methodology
Bottom-up residential patio kitchen modeling reconciled against top-down ceramic kiln capacity tracking forms the analytical core, combining primary interviews with outdoor kitchen contractors, specialty retailer category managers, refractory ceramics plant engineers, and EPA regulatory affairs specialists with secondary validation through EPA enforcement databases, CSA Group certification registries, California Air Resources Board seasonal restriction calendars, and customs records of refractory ceramic precursor imports. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map cordierite-alumina blend consumption against freestanding, built-in, portable, and tabletop configuration outputs across the projection horizon. Segmentation dimensions include installation permanence, fuel ritual preference, cooking chamber scale, and regional regulatory cluster intensity. CAGRs derive from replacement cycle velocity in year-round grilling climates versus seasonal markets, cross-referenced with municipal outdoor kitchen permit issuance trends.
Underlying measurement precision varies by segment; built-in configurations with professional installation documentation carry tighter precision than portable unit estimates dependent on recreational buyer survey responses. Forecasts reflect assumptions around EPA enforcement continuity, charcoal supply harvest stability, and gas-hybrid technology adoption curves. A small set of regulatory triggers—CARB seasonal restriction expansion, CSA Group testing timeline extensions, and municipal incentive program launches—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Toilet Hygiene Products Market
Household Items
Sleeping Pillow Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Coin-Operated Laundries Market
Household Items
US Air Fresheners Market
Household Items
Oman Gas Hobs Market
Household Items
Household Scales Market
Household Items
Robotic Vacuum Cleaner Market
Household Items
Drain Cleaners Market
Household Items
Neck Pillows Market
Household Items
MENA POU Water Purifiers Market
Household Items
Germany Induction Hobs Market
Household Items
Leaf Blower Market
Household Items
Commercial Lawnmower Market
Household Items
Towel Warmers Market
Household Items
Folded Tissues Market