
 Aubergine Market | 2026-2036
Aubergine Market Size, Share, and Industry Trends Forecast 2026-2036
Aubergine Market Analysis
Seed subscription and trait-licensing models are broadening what vegetable seed companies monetize beyond raw germplasm. Sakata leverages its hybrid breeding infrastructure to lock in recurring royalty streams across tropical aubergine varieties. Limagrain anchors its position through deep R&D investment in disease-resistant rootstocks. Bayer competes by extending its digital agronomy platform to tie seed purchases with predictive crop management tools.
Aubergine comprises the fruit of Solanum melongena, a nightshade species cultivated for its spongy, low-acidity flesh that absorbs oils and seasonings during cooking; commercial grades measure firmness, skin gloss, and seed cavity ratio to determine processing suitability. The vegetable serves as a staple meat alternative in vegetarian cuisines and as a processed ingredient in frozen meals, dips, and canned preparations. Italian Eggplant dominates fresh retail channels due to its uniform oval shape and extended shelf stability, while Thai Eggplant leads growth in food service applications where small, bitter varieties anchor authentic Southeast Asian menu formulations. Distribution through supermarkets captures the largest volume flow, though specialty stores command premium pricing for heirloom and organic-certified lines.
FDA food safety standards govern aubergine imports into the United States, with residue testing protocols shaping grower chemical application practices. EU REACH and EFSA pesticide maximum residue limits restrict active ingredient portfolios available to European and export-oriented producers. India's FSSAI labeling and cold-chain directives are tightening quality benchmarks for domestic distribution. Stakeholders must monitor how evolving phytosanitary requirements redirect sourcing geography and variety selection before committing long-term breeding programs.
Market Dynamics
EU Green Deal sustainability standards are redirecting procurement toward reduced-chemical cultivation protocols, forcing seed companies and growers to reconfigure variety portfolios and input regimens across Mediterranean and Asian supply belts.
Growth Catalysts
- EU REACH residue limits:Stricter EFSA maximum residue limits on chlorpyrifos and neonicotinoids are accelerating breeding investment in pest-resistant hybrid lines that reduce chemical dependency.
- Food service channel expansion:Restaurant chains across Southeast Asia are standardizing Thai Eggplant specifications for authentic menu formulations, creating pull-through demand for uniform small-fruit varieties.
- Controlled-environment agriculture:Glasshouse and vertical farming installations in the Netherlands and Spain are adopting soilless aubergine cultivation to extend growing seasons and compress harvest-to-retail windows.
Market Restraints
- Input cost volatility:Natural gas and fertilizer price swings constrain profitability for heated greenhouse operators in northern European production zones.
- Geographic supply concentration:Fresh aubergine exports depend heavily on Indian and Chinese port infrastructure, exposing buyers to phytosanitary hold risks and container availability fluctuations.
- Technical shelf-life limitation:Italian Eggplant varieties suffer chilling injury below 10°C, restricting cold-chain optimization and extending logistics costs for long-haul distribution.
Strategic Opportunities
- India domestic cold-chain investment:FSSAI-mandated temperature monitoring and traceability requirements are opening contracted procurement relationships between organized retail and large-scale growers in Karnataka and Maharashtra.
- Biostimulant integration:Seaweed extract and microbial inoculant combinations are proving effective in reducing synthetic fertilizer rates while maintaining yield in open-field Indian cultivation.
- Direct-to-processor channels:Frozen food manufacturers are establishing captive supply agreements with grower cooperatives, bypassing auction markets and securing variety-specific tonnage for dip and ready-meal production.
Industry Challenges
- Hybrid seed cost escalation:Trait licensing fees and royalty stacking from multiple germplasm providers inflate per-hectare input costs for smallholder growers in Andhra Pradesh and Telangana.
- Phytosanitary certification timelines:USDA APHIS and EU DG Sanco inspection backlogs delay export approvals, forcing Indian exporters to absorb demurrage and spoilage losses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aubergine Market |
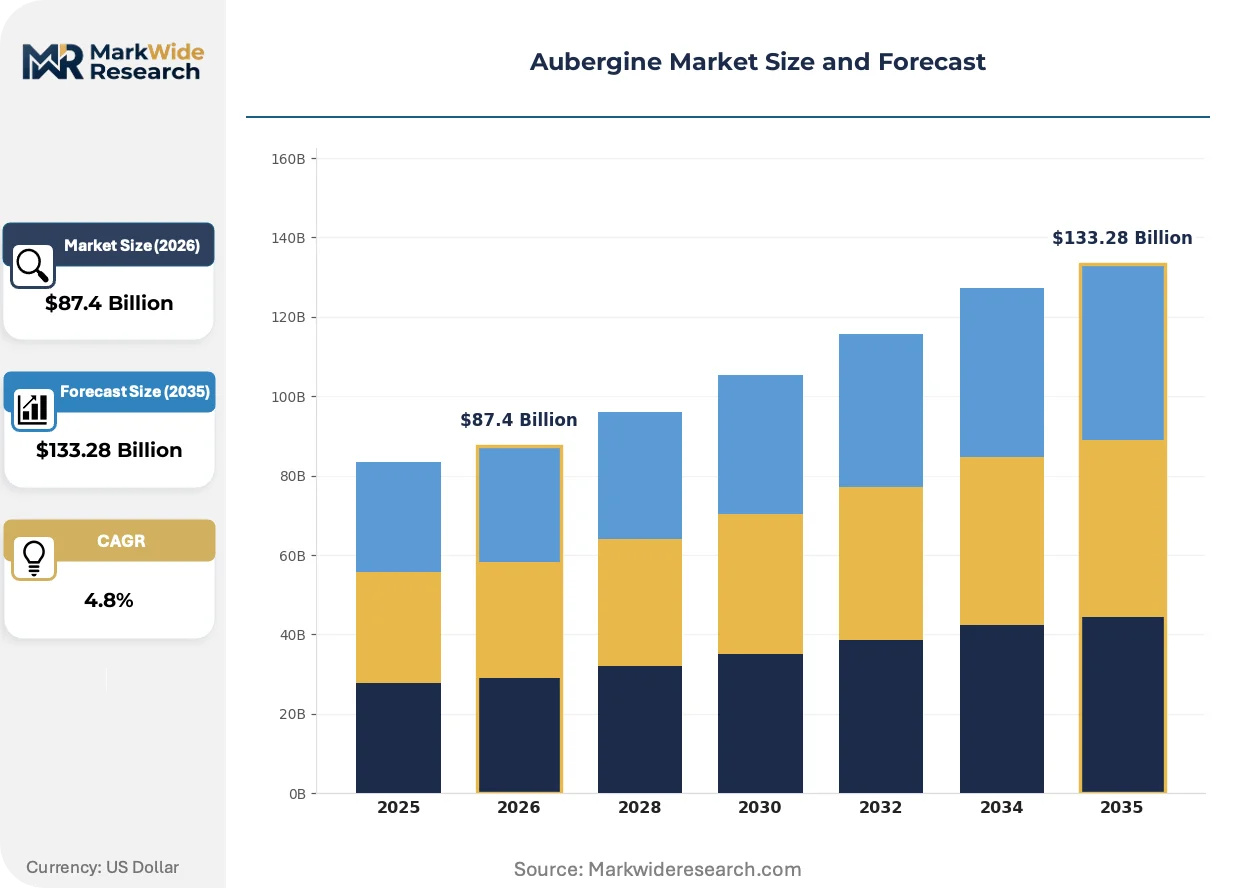
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chinese Eggplant, Japanese Eggplant, Thai Eggplant, Italian Eggplant Distribution Channel: Supermarkets, Farmers' Markets, Online Retail, Specialty Stores End User: Households, Restaurants, Food Processing Units, Catering Services Packaging Type: Plastic Bins, Cardboard Boxes, Mesh Bags, Bulk Packaging |
| Companies Covered | Sakata, Bejo, Limagrain, Advanta, Takii, Syngenta, East West Seed, Namdhari Seeds, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aubergine Market Emerging Trajectories
Seed economics are shifting from one-time germplasm sales toward recurring revenue architectures, while digital agronomy tools and biological input systems are compressing the information gap between breeders and field-level cultivation decisions.
Marker-assisted selection is decentralizing hybrid development timelines by enabling breeders to stack multiple disease-resistance traits without successive backcrossing generations. Regional seed companies in India and Turkey are adopting these genomic screening protocols to compress variety release cycles from eight years to four. The structural consequence is fragmenting the historical R&D concentration held by large multinational breeding programs.
EU F-Gas Regulation phase-down schedules are pressuring protected-culture operators to abandon high-global-warming-potential refrigerants in climate-controlled greenhouses. Spanish and Italian growers are retrofitting facilities with CO2 heat pumps and geothermal exchange systems to maintain temperature regimes. The investment burden falls most heavily on small-to-mid-scale operations that lack balance-sheet capacity for infrastructure replacement.
Restaurant procurement teams are consolidating supplier relationships around single-source accountability for food safety and variety consistency. Large Southeast Asian food service groups are replacing spot-market purchasing with annual volume contracts specifying fruit size, bitterness profile, and harvest-date windows. This concentration is most visible in Bangkok and Singapore, where centralized commissary kitchens demand predictable input streams for standardized menu execution.
Aubergine Market Segmentation
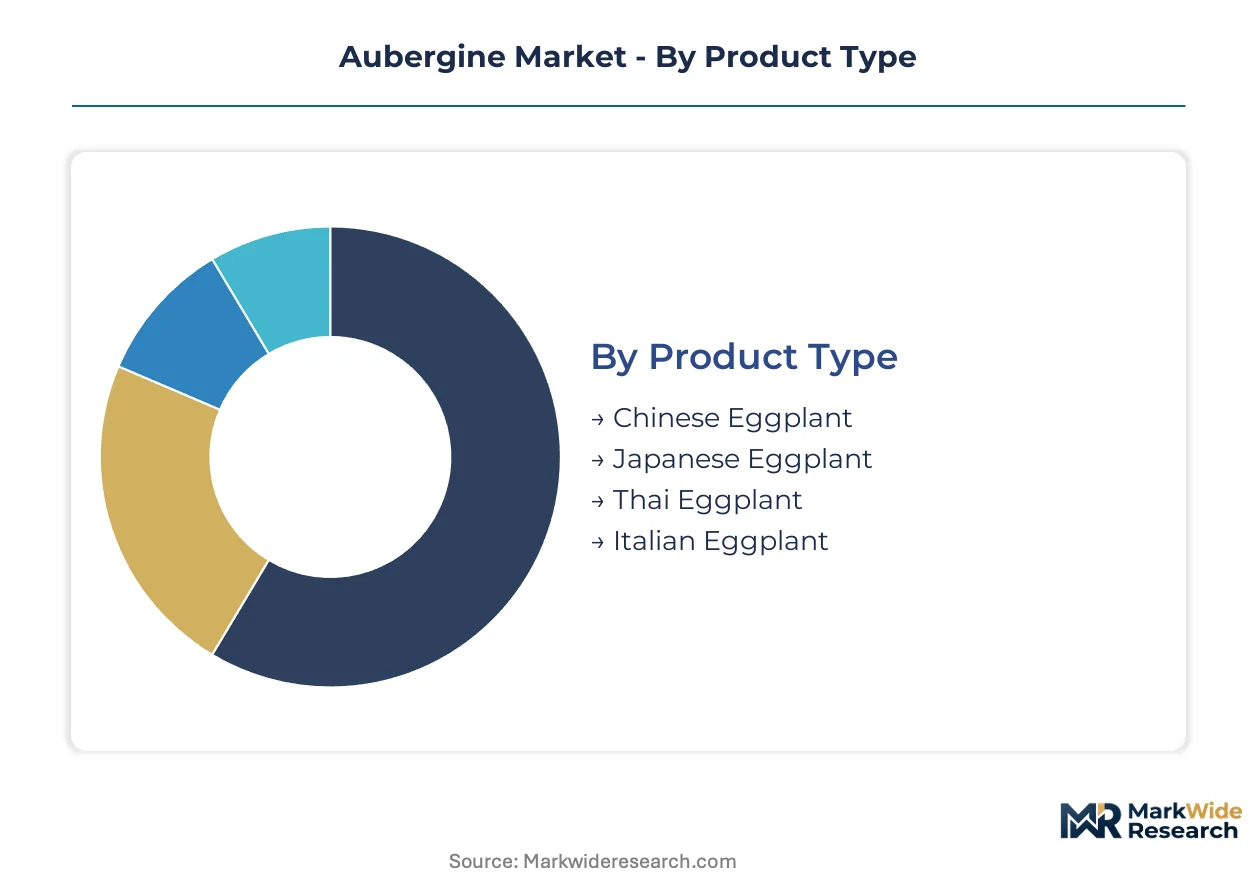
Aubergine segmentation reveals divergent quality standards across fresh retail and industrial channels. Italian Eggplant commands premium positioning in European supermarkets while Thai Eggplant anchors food service procurement contracts. Understanding these segment boundaries helps suppliers align breeding investments with downstream margin structures.
Product Type:
Volume flows through elongated Asian varieties while premium pricing concentrates in Mediterranean oval types.
- Italian Eggplant:Oval-shaped fruit with dense, low-seed flesh delivers extended shelf stability and uniform slicing yield. Demand concentrates in EU supermarket chains where EFSA residue standards favor reduced-chemical cultivation protocols. The segment captures the largest share of fresh retail value.
- Thai Eggplant:Small, round, bitter varieties with thin skin cook rapidly and hold shape in high-heat preparations. Bangkok and Singapore restaurant groups specify harvest-date windows and bitterness profiles in annual volume contracts. This segment is expanding most quickly in Southeast Asian food service channels.
- Chinese Eggplant:Slender, lavender-skinned fruit with tender flesh suits stir-fry applications and absorbs sauces efficiently.
- Japanese Eggplant:Dark purple, thin-skinned varieties with minimal seeds target high-end sushi and tempura operations.
Today's leader: Italian Eggplant. Tomorrow's challenger: Thai Eggplant.
Distribution Channel:
Supermarket procurement is consolidating around single-source accountability while specialty channels defend margin through provenance differentiation.
- Supermarkets:Centralized buying desks in Spain, Italy, and India negotiate variety-specific tonnage with cold-chain guarantees. FSSAI-mandated temperature monitoring in Indian organized retail is tightening supplier qualification criteria.
- Specialty Stores:Heirloom and organic-certified lines command 40-60% price premiums over conventional grades through direct grower relationships.
- Farmers' Markets:Local provenance and harvest freshness attract urban consumers in Mediterranean cities and Indian metros.
- Online Retail:Quick-commerce platforms in Bangalore and Mumbai are piloting 30-minute delivery of pre-cut aubergine SKUs.
Supermarkets dominate volume. Specialty stores extract margin. Online retail shows steepest expansion trajectory.
End User:
Industrial buyers are bypassing auction markets to secure captive supply while household demand fragments across format convenience.
- Restaurants:Southeast Asian chains standardize Thai Eggplant specifications for authentic menu execution. Centralized commissary kitchens in Bangkok demand predictable input streams with defined fruit size parameters.
- Food Processing Units:Frozen meal manufacturers in India and Italy establish direct grower contracts for dip and ready-meal production, specifying seed cavity ratios and firmness thresholds.
- Households:Fresh retail purchases concentrate in urban India and EU cities, with preference shifting toward pre-trimmed and portion-packed formats.
- Catering Services:Institutional buyers in Indian wedding halls and corporate cafeterias prioritize cost-stable supply over variety specificity.
Food processing units are pulling volume out of spot markets. Restaurants are pushing specification upstream.
Packaging Type:
EU Green Deal packaging directives are accelerating material transitions while Indian cold-chain gaps favor breathable formats.
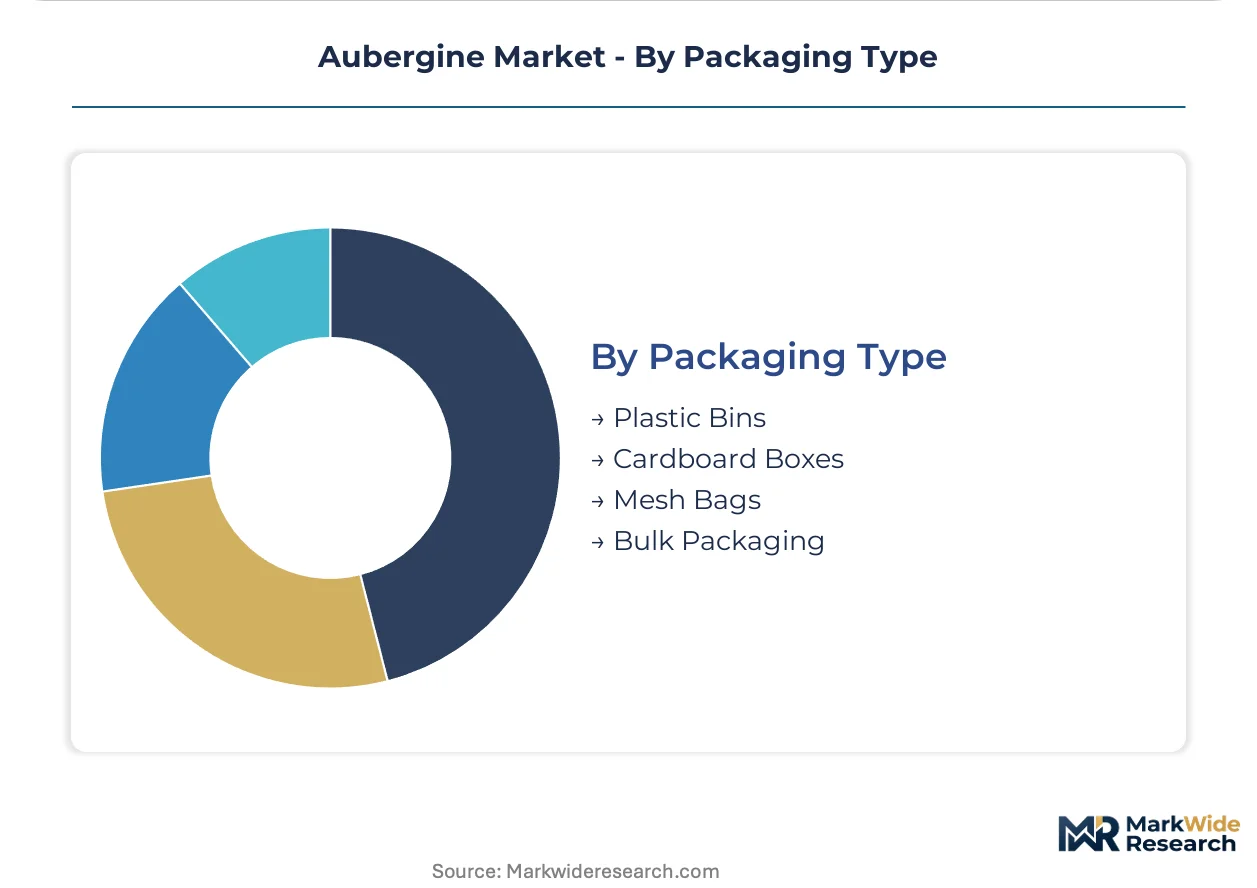
- Cardboard Boxes:Ventilated corrugated designs with moisture-wicking liners dominate EU supermarket shelf-ready requirements. REACH-compliant adhesives and recycled fiber content satisfy sustainability procurement criteria.
- Mesh Bags:Polypropylene netting enables field-heat dissipation in Indian open-air distribution, reducing post-harvest losses in Karnataka and Maharashtra supply belts.
- Plastic Bins:Reusable rigid containers circulate between Dutch glasshouse operators and retail distribution centers.
- Bulk Packaging:Food processors accept loose-bin delivery for immediate factory-line intake, eliminating retail packaging cost.
Cardboard boxes lead in regulated markets. Mesh bags retain dominance in infrastructure-constrained geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India dominates fresh aubergine production volume while Spain concentrates protected-culture output for EU retail channels. China anchors processing-grade supply for frozen food manufacturers across Asia. The Netherlands leads glasshouse technology adoption, extending harvest windows through climate-controlled cultivation.
India
Domestic restaurant chains and food processing units in Bangalore and Mumbai drive hybrid variety demand. FSSAI cold-chain directives tighten temperature monitoring requirements for organized retail procurement. Karnataka and Maharashtra production belts scale contract farming arrangements with Namdhari Seeds for export-grade Italian Eggplant tonnage.
Spain
EU supermarket buyers consolidate procurement around Almería and Murcia glasshouse clusters for year-round supply. EU F-Gas Regulation phase-down schedules force CO2 heat pump retrofits in climate-controlled facilities. Andalusian growers adopt geothermal exchange systems to maintain temperature regimes while eliminating high-global-warming-potential refrigerants.
China
Frozen meal manufacturers in Yangtze River Delta processing zones specify slender Chinese Eggplant varieties for stir-fry applications. NMPA food safety standards govern residue testing protocols for export-oriented producers. Shandong Peninsula cultivation belts supply domestic quick-service restaurant chains with volume-contracted tonnage.
Netherlands
Vertical farming installations around Rotterdam and Amsterdam adopt soilless aubergine cultivation for harvest-to-retail compression. REACH-compliant input regimens restrict synthetic pesticide portfolios available to protected-culture operators. Westland glasshouse cluster invests in LED supplementation and closed-loop irrigation to optimize Italian Eggplant yield per square meter.
Thailand
Bangkok restaurant groups standardize Thai Eggplant specifications for authentic menu execution in centralized commissary kitchens. The country's national agricultural regulator enforces phytosanitary certification for export shipments to Singapore and Malaysia. Central Plains growing regions contract directly with food service distributors to secure defined fruit size and bitterness profile parameters.
Aubergine Market Vendor Landscape
Top-tier vendors anchor trait-licensing and digital agronomy platforms, while regional specialists compete on hybrid breeding speed for tropical adaptation. The vendor base stratifies across multinational R&D conglomerates, mid-scale seed houses with regional germplasm depth, and emerging genomic screening adopters compressing variety release cycles. Two dominant competitive moves are reshaping positioning: strategic partnerships between breeders and food processors for captive supply agreements, and backward integration into biostimulant portfolios to reduce grower synthetic input dependency.
Among Japan-based breeders, Sakata and Takii occupy positions within the premium hybrid tier, leveraging tropical aubergine germplasm libraries to secure royalty streams across Southeast Asian cultivation belts. Bayer represents the integrated agronomy archetype, extending digital crop management tools to tie seed purchases with predictive field-level recommendations. Limagrain exemplifies the disease-resistance specialization vector, anchoring market presence through rootstock R&D investment for protected-culture operators in Mediterranean production zones.
| Leading Market Players |
|---|
| Sakata |
| Bejo |
| Limagrain |
| Advanta |
| Takii |
| Syngenta |
| East West Seed |
| Namdhari Seeds |
| Bayer |
| Others |
Supply Flow & Price Mechanics
Hybrid breeding specialists concentrated in Karnataka and Maharashtra drive labor-cost differentials that widen spreads between premium Italian Eggplant contract tiers and economy-grade open-market lots. EU REACH compliance costs and FSSAI cold-chain mandates further stratify procurement pricing across export-oriented and domestic-only supply channels.
Pricing Analysis
Capacity additions in Indian protected-culture facilities are reshaping price floors for Italian Eggplant export grades. Three-tier pricing structure across premium certified-organic, standard EU-compliant, and economy domestic levels anchors transaction frameworks. Price differentiation rests on phytosanitary certification status and cold-chain integrity guarantees. Cost compression in standard tiers is intensifying because royalty-stacked hybrid seed fees inflate per-hectare input costs for smallholders. Food processing units demonstrate lowest price sensitivity due to captive contract structures, while unorganized retailers in Indian spot markets exhibit highest sensitivity to weekly harvest fluctuations.
Supply Chain Analysis
Domestic-content mandates in Indian organized retail are reshaping sourcing relationships toward Maharashtra and Karnataka grower cooperatives with FSSAI-registered cold-chain infrastructure. Fresh aubergine supply draws from India, Spain, and China as primary source countries. Raw material dependencies center on hybrid seed germplasm, biostimulant inputs, and ventilated packaging materials. Single-source vulnerability runs through Indian port infrastructure concentration for export-grade tonnage. Distribution runs through supermarket centralized buying desks commissary kitchen direct contracts, and spot auction markets in tiered priority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aubergine market functions as a stable compounder anchored by recurring seed subscription revenue architectures that generate predictable royalty streams across tropical variety portfolios.
For Market Incumbents: Anchor market position through disease-resistant rootstock R&D investment for Mediterranean glasshouse operators facing EU F-Gas Regulation retrofit burdens. Deepen backward integration into biostimulant portfolios to reduce grower synthetic input dependency and lock in recurring agronomy service revenue. Defend against regional Indian seed houses compressing variety release cycles through marker-assisted selection adoption. For New Entrants and Emerging Players: Launch via direct-to-processor channels supplying frozen food manufacturers in Bangalore and Mumbai with variety-specific tonnage bypassing auction market intermediaries. Target Thai Eggplant specification standardization for Bangkok restaurant group commissary contracts as the most penetrable white-space segment. Pursue genomic screening partnerships to compress tropical adaptation breeding timelines against incumbent R&D scale advantages. For Investors and Strategic Acquirers: Food processing conglomerates represent the most active acquirer category in this space, seeking captive supply security for dip and ready-meal production lines. Long-term viability frames around five-to-ten year contract farming consolidation trajectories in Indian organized retail expansion zones. Acquisition target archetypes include mid-scale seed houses with regional germplasm depth and established FSSAI-compliant cold-chain grower networks. Monitor Indian domestic restaurant chain expansion rates as the critical inflection signal for hybrid variety demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Trait-Licensing Partnership | Sakata secures recurring royalty streams across Southeast Asian tropical aubergine cultivation belts. |
| Biostimulant Portfolio Integration | Seaweed extract and microbial inoculant combinations reduce synthetic fertilizer rates in open-field Indian production. |
| Direct-to-Processor Supply Agreement | Frozen meal manufacturers in Bangalore bypass auction markets to secure defined seed cavity ratio tonnage. |
| Cold-Chain Infrastructure Retrofit | Spanish glasshouse operators adopt CO2 heat pumps to satisfy EU F-Gas Regulation phase-down schedules. |
| Marker-Assisted Selection Adoption | Regional Indian seed houses compress variety release cycles from eight years to four through genomic screening protocols. |
Methodological Framework
Bottom-up food processing and restaurant procurement modeling reconciled against top-down seed company shipment tracking forms the analytical core of this study. Primary interviews with hybrid breeding program directors, organized retail category buyers, glasshouse operations managers, and food service procurement heads combined with secondary validation against FSSAI regulatory filings, EU REACH substance restrictions, customs trade data, and seed industry association reports. Triangulation across stakeholder perspectives and documentary sources ensures cross-verified demand and supply estimates.
Historical trendline analysis of variety adoption rates and pricing spreads across Italian Eggplant, Thai Eggplant, Chinese Eggplant, and Japanese Eggplant segments informs projection trajectories over the analysis window. Segmentation dimensions modeled include product type, distribution channel, end user, and packaging format alongside regional production cluster regulatory framework differentiation. CAGRs derive from fitted trend extrapolation adjusted for EU Green Deal sustainability standard implementation pacing and Indian cold-chain investment acceleration.
Several conditions sit outside the modeled scope, including abrupt phytosanitary certification timeline disruptions, extreme weather impacts on open-field harvest cycles, and geopolitical trade restriction impositions. Forecasts reflect documented assumptions regarding breeder R&D investment continuity and processor contract farming adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Europe Dried Mushroom Market
Fruits and Vegetables
Grapefruit Peel Market
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Camellia Oil Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
Raisins Market
Fruits and Vegetables
Dried Red Jujube Market
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
Guava Puree Market