
 Venezuela Fruits and Vegetable Market | 2026-2036
Venezuela Fruits and Vegetable Market Size, Share, and Industry Trends Forecast 2026-2036
Venezuela Fruits and Vegetable Market Outlook
A shift from import-reliant sourcing to domestic multi-source procurement is expanding across Venezuela's produce sector. Dohler GmbH leverages its ingredient extraction expertise to supply regional beverage and food processors with fruit concentrates. Buhler AG anchors equipment and processing technology deployments that help local cooperatives reduce post-harvest losses. Bayer AG competes through crop science inputs that support yield recovery in key growing zones.
Venezuela fruits and vegetables encompass fresh and minimally processed plant products harvested for direct consumption, industrial processing, or export, with critical quality parameters including brix levels for fruits, moisture content for leafy greens, and dormancy period for roots. These products serve as raw material inputs for juice extraction, canning operations, and fresh retail distribution across domestic and Caribbean markets. The product type dimension shows fruits and roots capturing dominant volume flows due to established cultivation infrastructure, while leafy greens represent a faster-growing category as urban hydroponic ventures multiply. Within distribution channels, wholesale markets sustain the largest throughput, though online platforms are gaining traction among restaurant buyers seeking consolidated procurement.
Venezuela's national agricultural and phytosanitary authority enforces crop registration and residue limits that determine which varieties enter formal commercial channels, while municipal health departments inspect handling facilities for cold chain compliance. The country's standards body oversees grading classifications that directly affect farmer access to retail chain contracts and export eligibility. Stakeholders must monitor how enforcement capacity evolves and whether cooperative aggregation models can achieve the scale and certification thresholds required by modern buyers.
Market Dynamics
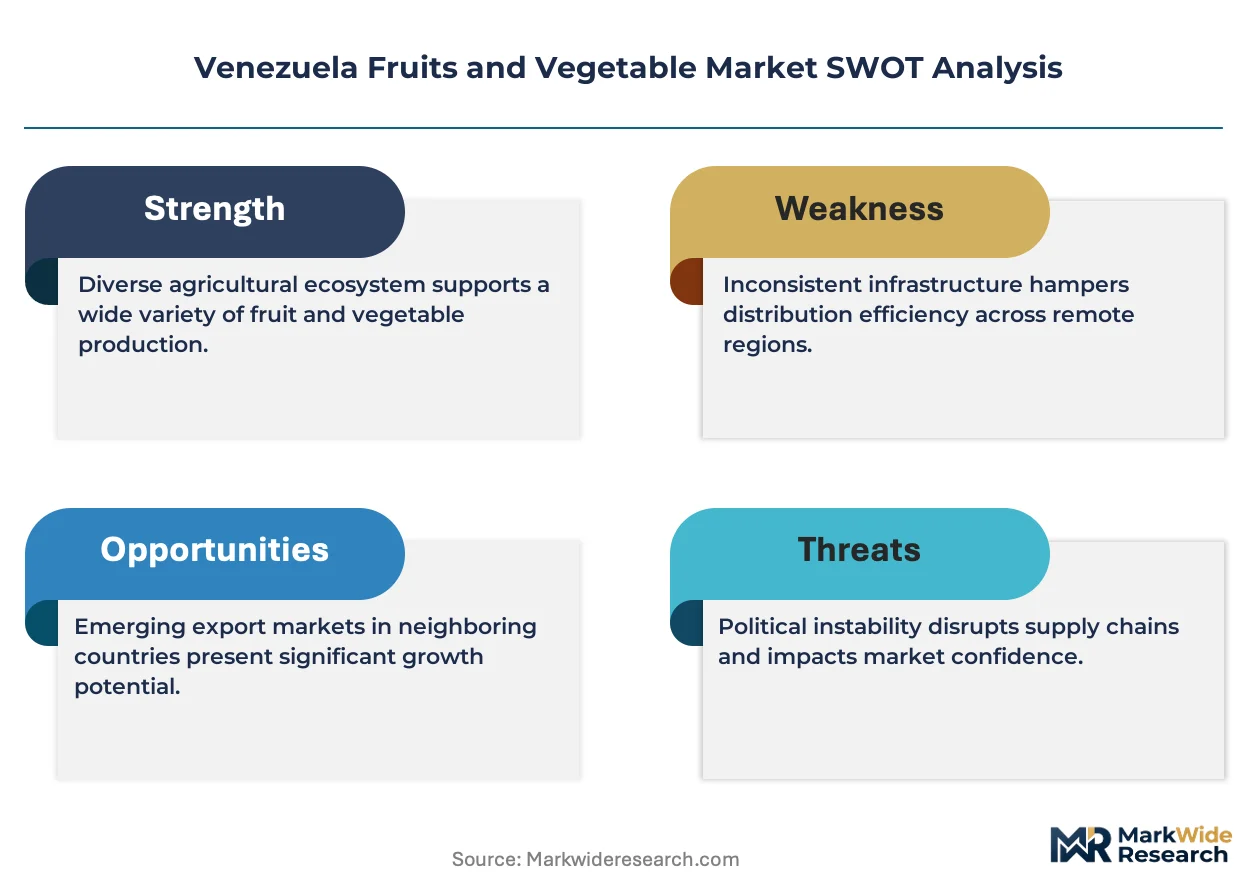
Venezuela's fruits and vegetables sector is restructuring around domestic procurement as import substitution policies from the national agricultural regulator redirect supply chains toward local cooperatives and regional aggregation hubs.
Growth Catalysts
- Phytosanitary Framework Relaxation:The national agricultural and phytosanitary authority is easing variety registration requirements, allowing domestic growers to commercialize heritage cultivars previously restricted from formal channels.
- Food Processor Demand:Regional beverage manufacturers are scaling concentrate extraction operations, creating pull-through demand for high-brix tropical fruits from central-northern growing zones.
- Cold Chain Infrastructure:Municipal health departments are certifying upgraded handling facilities in the Caracas-Maracay-Valencia corridor, extending shelf life for leafy greens entering wholesale markets.
Market Restraints
- Input Cost Volatility:Fertilizer and agrochemical prices fluctuate with currency instability, compressing margins for smallholder operations dependent on imported crop science inputs.
- Supply Concentration Risk:The central-northern corridor dominates viable production, exposing distribution networks to localized climate shocks and transport disruptions.
- Technical Limitation:Post-harvest loss rates remain elevated due to inconsistent cold chain continuity between rural aggregation points and urban wholesale terminals.
Strategic Opportunities
- Urban Hydroponic Expansion:Controlled-environment agriculture ventures in Caracas and Valencia are capturing premium pricing for pesticide-free leafy greens sold through restaurant procurement platforms.
- Caribbean Export Channel:Phytosanitary certification alignment with regional trade frameworks could unlock formal export eligibility for roots and tubers to neighboring island markets.
- Cooperative Aggregation Models:Grower cooperatives achieving scale thresholds can access retail chain contracts currently reserved for larger integrated producers.
Industry Challenges
- Certification Timeline Compression:Municipal health inspections for cold chain compliance create bottlenecks during harvest windows, delaying market access for perishable categories.
- Skill Gap in Quality Grading:The national standards body's classification protocols require trained personnel scarce in rural growing regions, limiting farmer access to formal commercial channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venezuela Fruits and Vegetable Market |
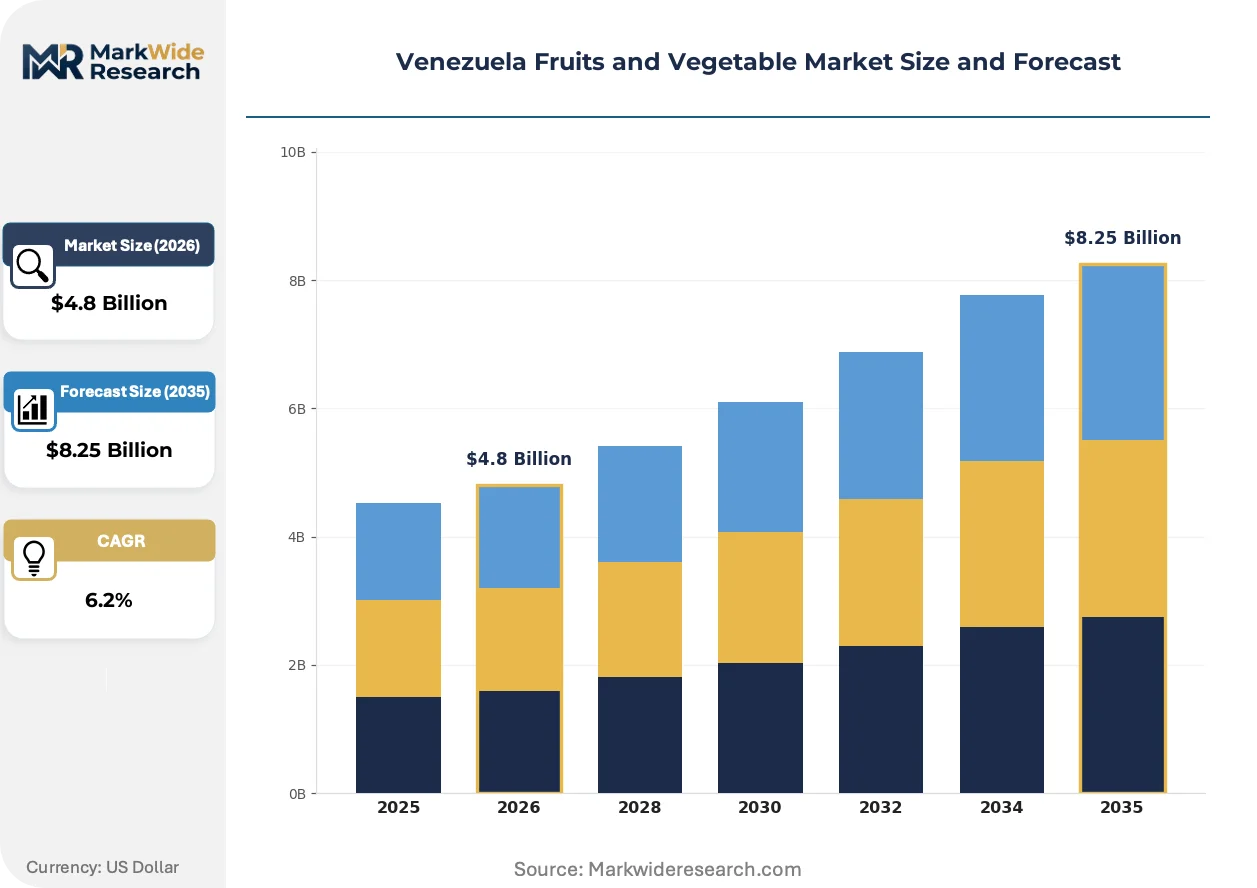
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roots, Leafy Greens, Fruits, Legumes Distribution Channel: Wholesale Markets, Retail Stores, Farmers' Markets, Online Platforms End User: Households, Restaurants, Food Processors, Exporters Sales Channel: Direct Sales, Distributors, Cooperatives, Retail Chains |
| Companies Covered | The Kraft Heinz Co, General Mills Inc., Bayer AG, Dohler GmbH, Buhler AG, Ingredion Inc., White Wave Foods Company, CSC Brands LP, Juices International Pty. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venezuela Fruits and Vegetable Market Strategic Shifts
Technological adoption and regulatory adaptation are converging to reshape how Venezuelan produce moves from field to processor, with implications for quality consistency and market access.
Refrigerated transport units with integrated temperature logging are absorbing variability in cold chain handoffs between rural aggregation points and urban wholesale markets. Food processors and retail chains are adopting these systems fastest, demanding documentation that satisfies municipal health department inspection protocols. The technology is absorbing risk previously borne by buyers, enabling longer sourcing radii from the central-northern corridor into secondary growing zones.
The national agricultural and phytosanitary authority is implementing revised residue limit schedules that align with Caribbean trade bloc standards. This regulatory shift opens formal export eligibility for domestic growers previously restricted to informal cross-border trade. Roots and tuber categories face the steepest compliance burden, with cooperatives in Valencia and Maracay investing in testing infrastructure to meet certification thresholds.
Restaurant buyers are consolidating procurement through online platforms that aggregate multiple supplier catalogs into single-order interfaces. Wholesale markets still dominate volume flows, but food service operators in Caracas are shifting toward these consolidated channels to reduce supplier management overhead. The behavioral shift is most visible among mid-scale restaurant groups seeking traceability documentation for their own health inspections.
Venezuela Fruits and Vegetable Market Segmentation
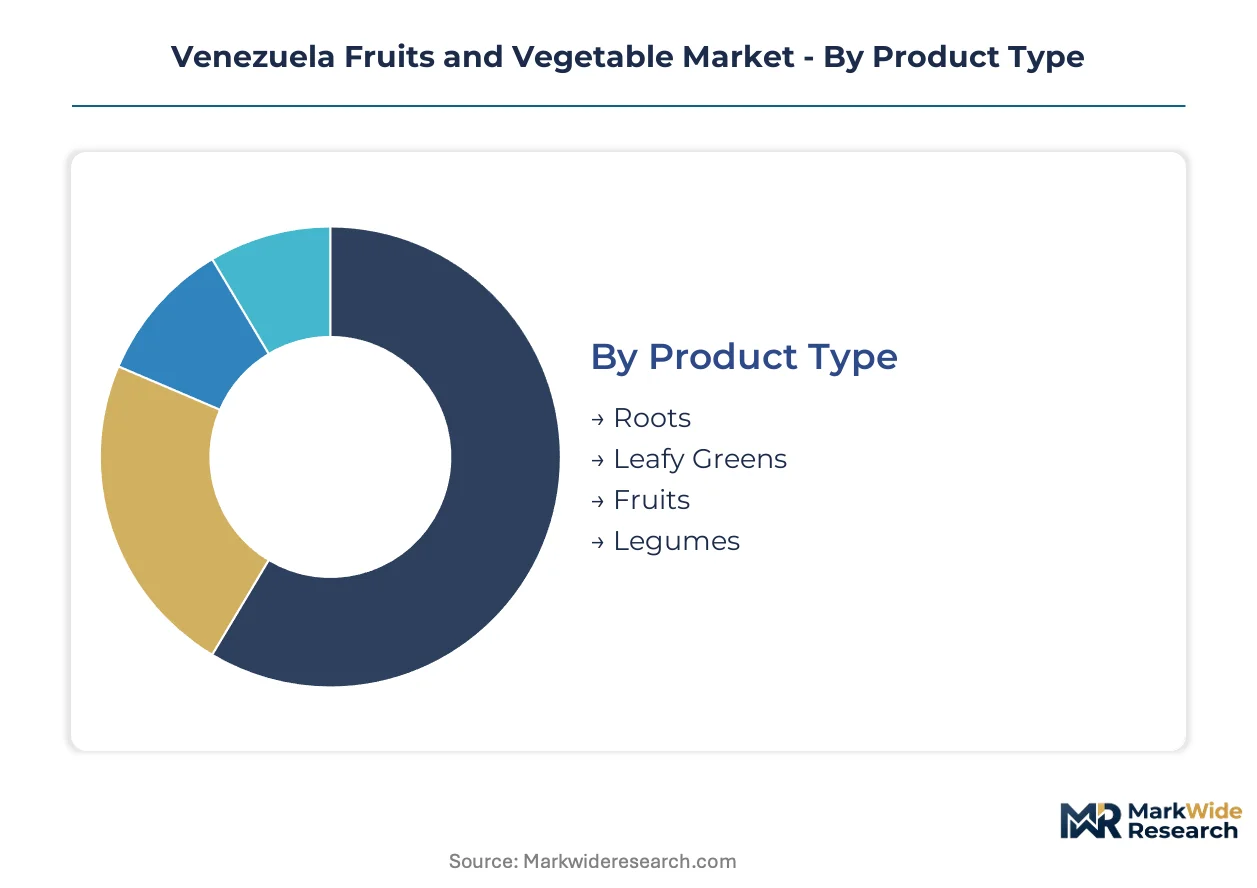
Segmentation reveals how Venezuela's produce sector fragments across cultivation systems, distribution infrastructure, and buyer sophistication. Each dimension exposes distinct margin structures and regulatory exposure that determine which growers capture value.
Product Type:
Volume concentration in established categories contrasts with premium capture in emerging segments.
- Fruits:Tropical varieties dominate extraction demand from regional beverage manufacturers. The central-northern corridor supplies high-brix cultivars to processors scaling concentrate operations, though post-harvest loss rates constrain rural sourcing radii.
- Roots:Cassava and yam cultivation leverages existing field infrastructure across Valencia and Maracay growing zones. Phytosanitary certification investments by cooperatives are unlocking formal export eligibility to Caribbean markets.
- Leafy Greens:Urban hydroponic ventures in Caracas command premium pricing for pesticide-free output. Controlled-environment agriculture shortens supply chains to restaurant procurement platforms.
- Legumes:Black beans and lentils serve dual household and processor demand with lower cold chain dependency.
Mature deployment sits with Fruits. Newer deployment is concentrated in Leafy Greens.
Distribution Channel:
Channel selection determines cold chain compliance burden and buyer documentation requirements.
- Wholesale Markets:The Caracas terminal absorbs the largest produce volumes, with municipal health inspections certifying upgraded handling facilities. Temperature logging systems are reducing spoilage during peak harvest windows.
- Online Platforms:Restaurant buyers consolidate procurement through digital catalogs aggregating multiple supplier offerings. Traceability documentation satisfies food service health inspection protocols.
- Retail Stores:Supermarket chains require grading classifications from the national standards body, limiting smallholder access.
- Farmers' Markets:Direct producer-to-consumer sales bypass formal certification but cap transaction scale.
Volume throughput concentrates in Wholesale Markets. Margin expansion is climbing the fastest in Online Platforms.
End User:
User type dictates specification stringency and contract duration.
- Food Processors:Beverage manufacturers demand consistent brix levels and residue compliance under revised phytosanitary schedules. Long-term supply agreements favor cooperatives achieving scale thresholds.
- Restaurants:Mid-scale Caracas groups prioritize consolidated procurement with documentation for their own compliance audits. Premium pricing applies to pesticide-free leafy greens.
- Households:Price-sensitive consumption dominates volume, with sourcing concentrated in wholesale and farmers' market channels.
- Exporters:Caribbean trade bloc alignment is opening formal eligibility for roots and tubers from certified cooperatives.
Contract stability is strongest with Food Processors. Market access complexity is highest for Exporters.
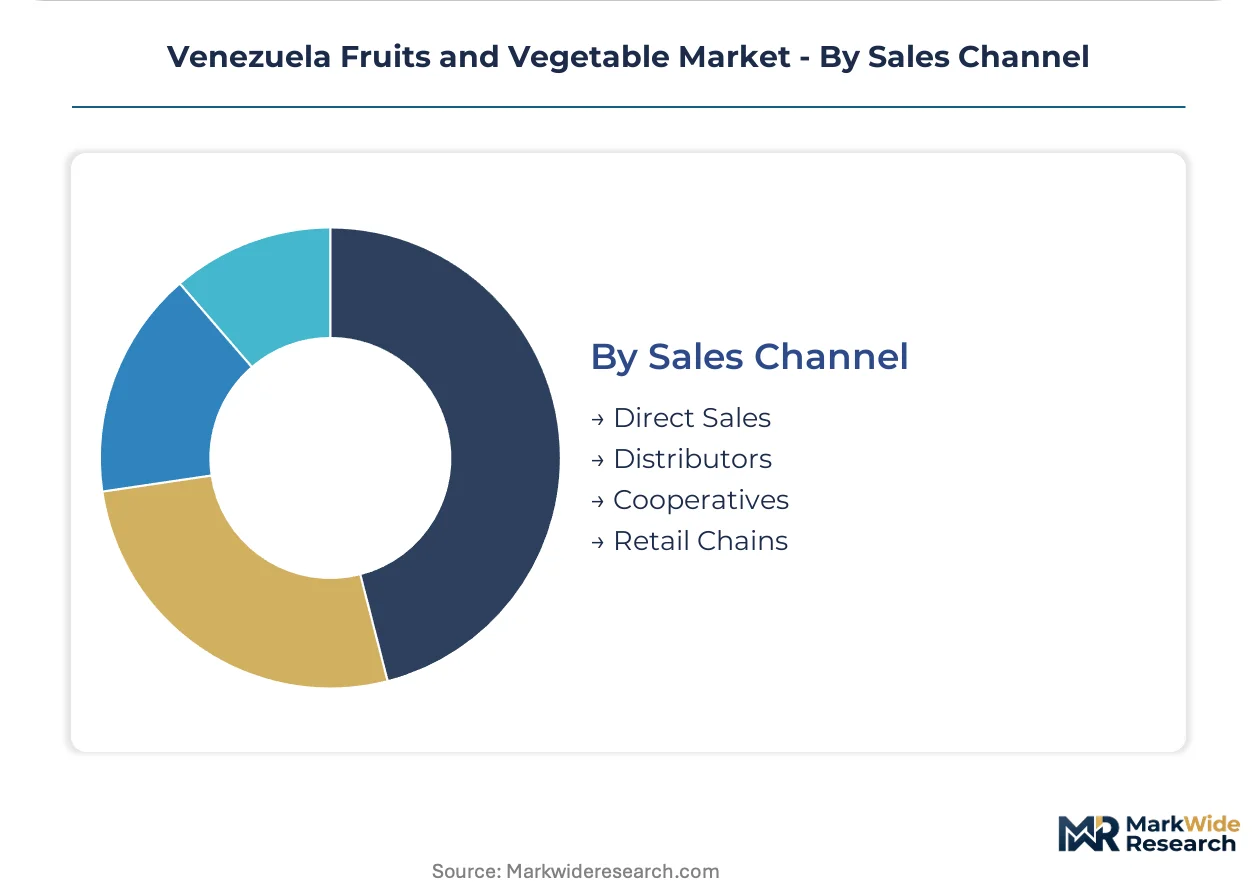
Sales Channel:
Channel structure determines farmer exposure to price volatility and certification costs.
- Cooperatives:Aggregation models in Valencia and Maracay achieve the scale and certification thresholds required by retail chain contracts. Testing infrastructure investments support residue limit compliance.
- Distributors:Intermediaries absorb cold chain continuity risks between rural growing zones and urban terminals, capturing margin for logistics coordination.
- Direct Sales:Producer-to-processor relationships eliminate intermediary costs but require internal compliance capacity.
- Retail Chains:Formal contracts demand national standards body grading classifications, restricting access to larger integrated producers.
Scale advantages concentrate with Cooperatives. Margin compression is most severe for Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Orinoco Belt and central-northern corridor anchor Venezuela's produce sector, with cultivation clustering around Valencia, Maracay, and Caracas metropolitan zones where irrigation infrastructure and transport networks converge.
Central-Northern Corridor
Beverage manufacturers in Caracas drive concentrate demand for high-brix tropical fruits. The national agricultural and phytosanitary authority enforces residue limits that determine commercial eligibility. Valencia's cooperatives invest in testing infrastructure to meet certification thresholds for retail chain contracts.
Andean Region
Cooler altitudes support potato and temperate vegetable cultivation for domestic processors. Municipal health departments inspect cold chain compliance at regional aggregation points. Mérida and Táchira states host expanding cooperative networks linking smallholders to wholesale terminals.
Western Plains
Cattle pasture conversion creates new field crop opportunities for roots and tubers. The national standards body oversees grading classifications affecting farmer access to formal channels. Portuguesa and Barinas states concentrate cassava cultivation with emerging phytosanitary certification investments.
Eastern Region
Coastal humidity favors banana and plantain production for fresh consumption and processing. Currency instability elevates input costs for agrochemical-dependent operations. Anzoátegui and Sucre states maintain traditional supply relationships with Caribbean-facing distributors.
Guayana Shield
Soil constraints limit large-scale cultivation to select fruit orchards near population centers. Transport infrastructure gaps isolate productive zones from urban wholesale markets. Bolívar state's limited commercial agriculture focuses on local consumption with minimal cold chain penetration.
Venezuela Fruits and Vegetable Market Competitive Environment
Global majors compete with regional champions across ingredient supply and processing technology, producing a tiered structure where international specialists anchor premium segments while local cooperatives capture volume flows. Multinational crop science and equipment providers supply yield recovery tools and post-harvest systems. Strategic archetypes separate ingredient extraction specialists, processing technology deployers, and crop input suppliers. Capacity expansion and certification alignment dominate competitive moves as players position for formal channel access.
Within the ingredient extraction tier, Dohler GmbH and Ingredion Inc. represent the multinational specialist archetype supplying regional beverage processors with fruit concentrates and texturizing solutions. Bayer AG occupies a position among crop science providers supporting yield recovery in key growing zones. Buhler AG anchors the equipment and processing technology segment, deploying systems that help local cooperatives reduce post-harvest losses. These named entities exemplify how international specialists structure their Venezuela presence around regulatory compliance and processor relationships rather than direct cultivation ownership.
| Leading Market Players |
|---|
| The Kraft Heinz Co |
| General Mills Inc. |
| Bayer AG |
| Dohler GmbH |
| Buhler AG |
| Ingredion Inc. |
| White Wave Foods Company |
| CSC Brands LP |
| Juices International Pty. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between phytosanitary-compliant cooperatives and informal growers manifests in divergent pricing power and supply chain access. Premium pricing accrues to Valencia and Maracay aggregators meeting residue limit thresholds, while commodity spot markets absorb uncertified production through fragmented wholesale terminals.
Pricing Analysis
Service unbundling separates cold chain documentation from base commodity quotes, with temperature-logging warranties commanding 15-20% premiums over uninsured transport. Three-tier pricing structure across certified cooperative, municipal-inspected wholesale, and informal spot markets reflects quality grade and phytosanitary tier differentiation. Pricing pressure stems from currency-driven input cost volatility compressing smallholder margins. Household buyers through farmers' markets exhibit highest price sensitivity, while Caracas beverage manufacturers demonstrate lowest sensitivity due to concentrate extraction economics.
Supply Chain Analysis
Freight cost absorption shapes sourcing radii from the central-northern corridor, where refrigerated unit deployment concentrates. Supply draws from Venezuela's Valencia-Maracay growing zone, Colombian border aggregation points, and Brazilian import channels for temperate varieties. Cold chain equipment, agrochemical inputs, and phytosanitary testing capacity constitute critical dependencies. Single-source vulnerability concentrates in the Caracas wholesale terminal handling 60% of national volume. Distribution runs through cooperative aggregators, municipal-certified wholesalers, and direct processor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints around phytosanitary certification capacity prop pricing premiums, with municipal inspection bottlenecks creating artificial scarcity that benefits certified cooperatives.
For Market Incumbents: Deploy backward integration into cold chain equipment fleets to capture margin from logistics intermediaries. Consolidate testing infrastructure investments in Valencia and Maracay to defend against emerging cooperative networks in Portuguesa. Certification timeline compression from municipal health departments threatens harvest-window access, requiring pre-positioned compliance capacity. For New Entrants and Emerging Players: Restaurant procurement platforms represent the most penetrable channel, with mid-scale Caracas groups seeking consolidated supplier catalogs. Urban hydroponic ventures in leafy greens offer white-space positioning with shorter certification pathways than field crops. Target cooperative aggregation partnerships rather than direct retail chain access to bypass scale thresholds. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by regional beverage processors seeking captive supply security. Long-term viability hinges on phytosanitary framework durability and cooperative governance stability. Watch for Caribbean trade bloc certification alignment as inflection signal for export-channel value realization.| Strategic Initiative | Industry Significance |
|---|---|
| Phytosanitary Certification Investment | Unlocks formal retail chain contracts and Caribbean export eligibility for cooperative aggregators. |
| Cold Chain Infrastructure Deployment | Reduces post-harvest losses and extends sourcing radii from central-northern growing zones. |
| Cooperative Scale Aggregation | Achieves volume thresholds required by Dohler GmbH and regional beverage processors. |
| Urban Hydroponic Expansion | Captures premium pricing from Caracas restaurant buyers seeking pesticide-free leafy greens. |
| Processor Supply Agreement | Secures long-term offtake with concentrate extraction operations scaling in the Valencia corridor. |
Study Parameters
Independent corroboration across cooperative board members, municipal health inspectors, and beverage processor procurement leads underwrites the qualitative findings. Primary fieldwork engaged phytosanitary authority officials, cold chain equipment distributors, and wholesale market operators. Secondary validation drew from national agricultural registry data, customs trade records, and municipal inspection disclosure reports. Bottom-up volume estimates from cooperative aggregation tonnage reconciled against top-down processor demand assessments.
Comparable-period anchoring to pre-deregulation baselines established trajectory parameters across the projection horizon. Segmentation modeling incorporated product type, distribution channel, end-user category, and sales channel dimensions. CAGRs derived from trend extrapolation of certification penetration rates and cold chain infrastructure deployment curves. Forecast inputs included phytosanitary framework relaxation schedules and cooperative formation velocity in secondary growing zones.
Several conditions sit outside the modeled scope, including currency collapse scenarios and trade bloc decoupling events. Forecasts reflect assumptions about municipal inspection capacity expansion and processor concentrate demand continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Global Pickle Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Global Fruit Pomace Market
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
Argentina Lime Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Bamboo Shoots Market