
 Frozen Fruits Market | 2026-2036
Frozen Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Fruits Market Intelligence
The BRCGS Global Standard for Food Safety is rotating market access towards suppliers who can demonstrate rigorous traceability and quality control. Dole Food Company leverages its extensive plantation network to ensure consistent raw material supply for its frozen fruit lines. SunOpta Inc. specializes in organic and non-GMO frozen fruit offerings, targeting a specific health-conscious consumer base. Ardo NV competes on the basis of its wide geographic manufacturing footprint across Europe.
Frozen fruits are raw fruits preserved by freezing, typically using Individual Quick Freezing (IQF) to maintain individual pieces and cellular structure. This process extends shelf life for months while retaining nutritional value for consumers and industrial users. Within product types, berries maintain the largest share due to their widespread use in smoothies and baked goods. The food services segment, including cafes and restaurants, represents the fastest-growing end-user category, outpacing traditional household consumption.
Regulations from the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate permissible pesticide residue levels and labeling requirements. These standards directly influence cross-border trade and sourcing strategies for multinational processors. The key decision for suppliers now centers on balancing investments in advanced freezing technologies against the cost pressures from large-scale retail and food service buyers.
Market Dynamics
The market's central dynamic is the conflict between advanced freezing technologies that preserve fruit integrity and intense cost pressure from consolidated food service and retail buyers. This tension dictates investment priorities for processors globally, balancing quality enhancements against margin preservation.
Growth Catalysts
- IQF Technology Advancement:Individual Quick Freezing (IQF) technology improves the texture, color, and nutrient retention of frozen fruits, expanding their use in applications requiring distinct pieces.
- Food Service Demand:The food services sector, particularly cafes and smoothie bars, provides consistent demand for frozen berries, mangoes, and pineapples as core beverage ingredients.
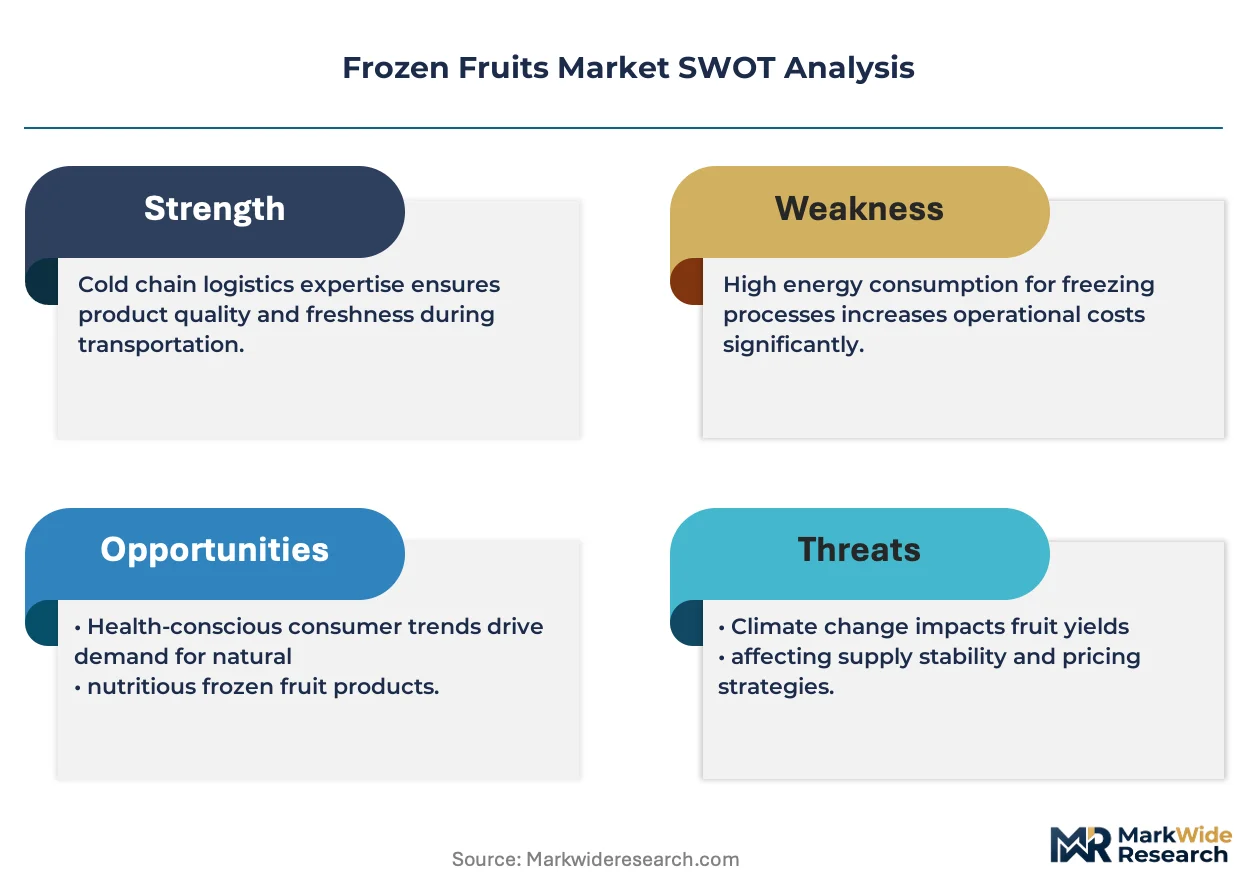
- Consumer Health Trends:A focus on wellness and clean-label foods in developed markets like the United States and Germany boosts demand for non-GMO and organic frozen fruits.
Market Restraints
- Energy Cost Volatility:The freezing process and the maintenance of the cold chain are energy-intensive, exposing processors to fluctuations in electricity and fuel prices.
- Agricultural Dependence:Supply is subject to agricultural seasonality, weather events, and climate change, which can create price volatility and raw material shortages for processors.
- Competition from Alternatives:Frozen fruits compete with fresh, canned, and freeze-dried alternatives, with consumer choice often dictated by price, convenience, and perceived freshness.
Strategic Opportunities
- Emerging Market Penetration:Improving cold chain infrastructure in Asia-Pacific and Latin American countries opens new consumer markets for packaged frozen fruit products beyond industrial use.
- Functional Food Blends:There is an opportunity to develop and market specialized frozen fruit mixes fortified with vitamins, minerals, or probiotics for the nutraceutical and functional food segments.
- Direct-to-Consumer Channels:Subscription-based services delivering pre-portioned frozen fruit packs for smoothies and bowls directly to households represent a growing distribution channel.
Industry Challenges
- Evolving Regulatory Compliance:Processors face the challenge of continuously monitoring and complying with differing pesticide residue limits set by the FDA and EFSA for cross-border trade.
- Capital Investment Intensity:Upgrading facilities with modern IQF tunnels, optical sorters, and automated packaging lines requires significant capital expenditure to remain competitive on quality and cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Fruits Market |
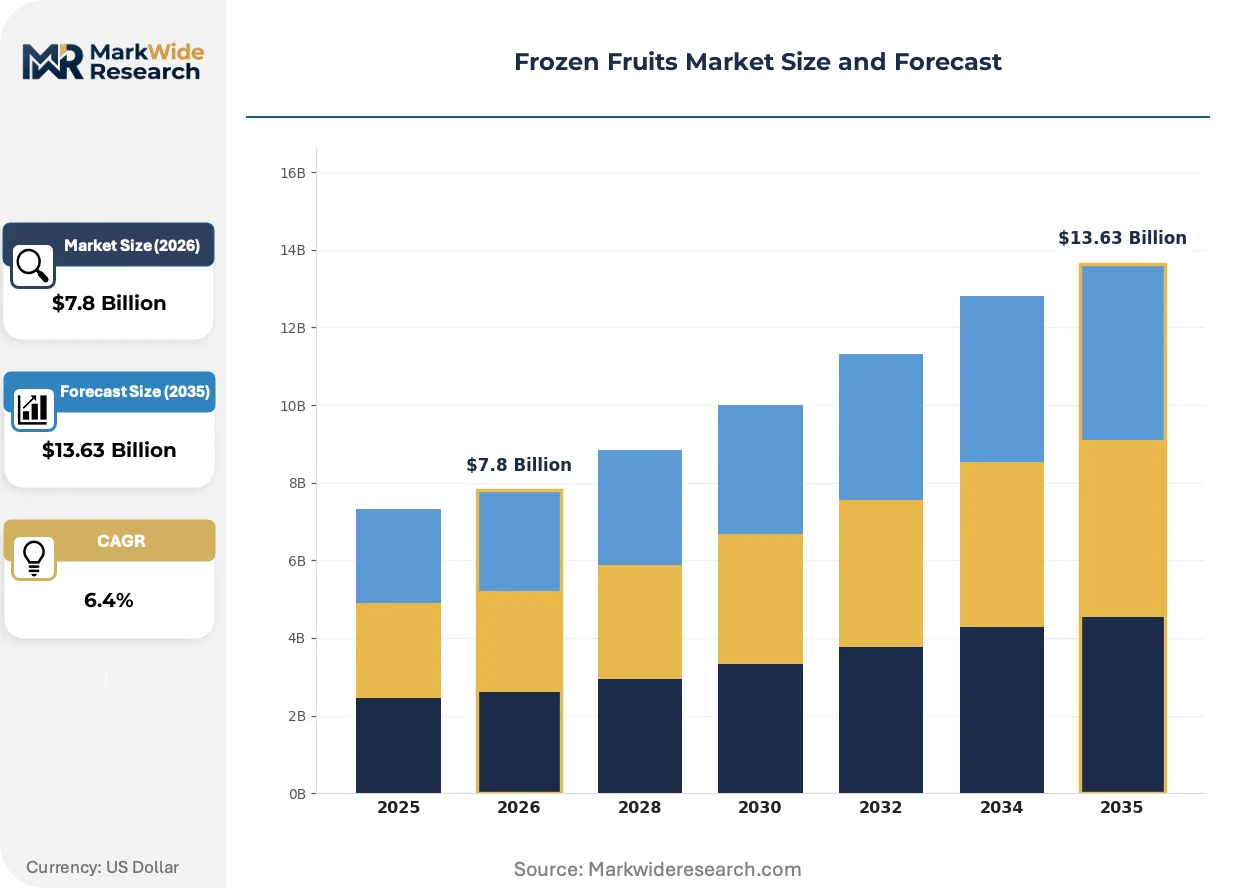
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Berry, Mango, Pineapple, Banana End User: Retailers, Food Services, Manufacturers, Households Size Category: Small Pack, Medium Pack, Bulk, Family Pack Distribution Channel: Supermarkets, Online Retail, Wholesalers, Convenience Stores |
| Companies Covered | Fresh Del Monte Produce Inc., J.R. Simplot Co., General Mills Inc., Bonduelle North America, SunOpta Inc., Dole Food Company, Ardo NV, Pinnacle Foods, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Fruits Market Strategic Shifts & Innovations
Technological advancements and evolving consumer expectations are industrializing the frozen fruit category, moving it beyond simple preservation. The focus is shifting towards delivering a product that rivals fresh fruit in texture, nutrition, and convenience, fundamentally altering processing and procurement strategies.
Cryogenic freezing systems utilize liquid nitrogen to achieve rapid temperature drops. Premium food service clients and processors of high-value fruits like berries are the primary adopters. This ultra-fast process is miniaturizing the ice crystals that form within the fruit's cellular structure, thereby preserving texture and enabling new applications in delicate desserts.
The BRCGS Global Standard for Food Safety is becoming a de facto requirement for market access. This standard mandates rigorous, digitally-enabled traceability from farm to finished product, increasing operational overhead. Processors in Southeast Asia and South America supplying European retailers are most affected, often needing to upgrade their entire quality management systems.
Food service procurement is evolving from buying single-variety bulk cases to sourcing customized, portion-controlled fruit blends. This trend disrupts traditional distribution models by shifting blending and packaging labor from the end-user kitchen to the processor's facility. The shift is most pronounced among quick-service restaurant chains in the United States and Germany seeking menu consistency.
Frozen Fruits Market Segmentation
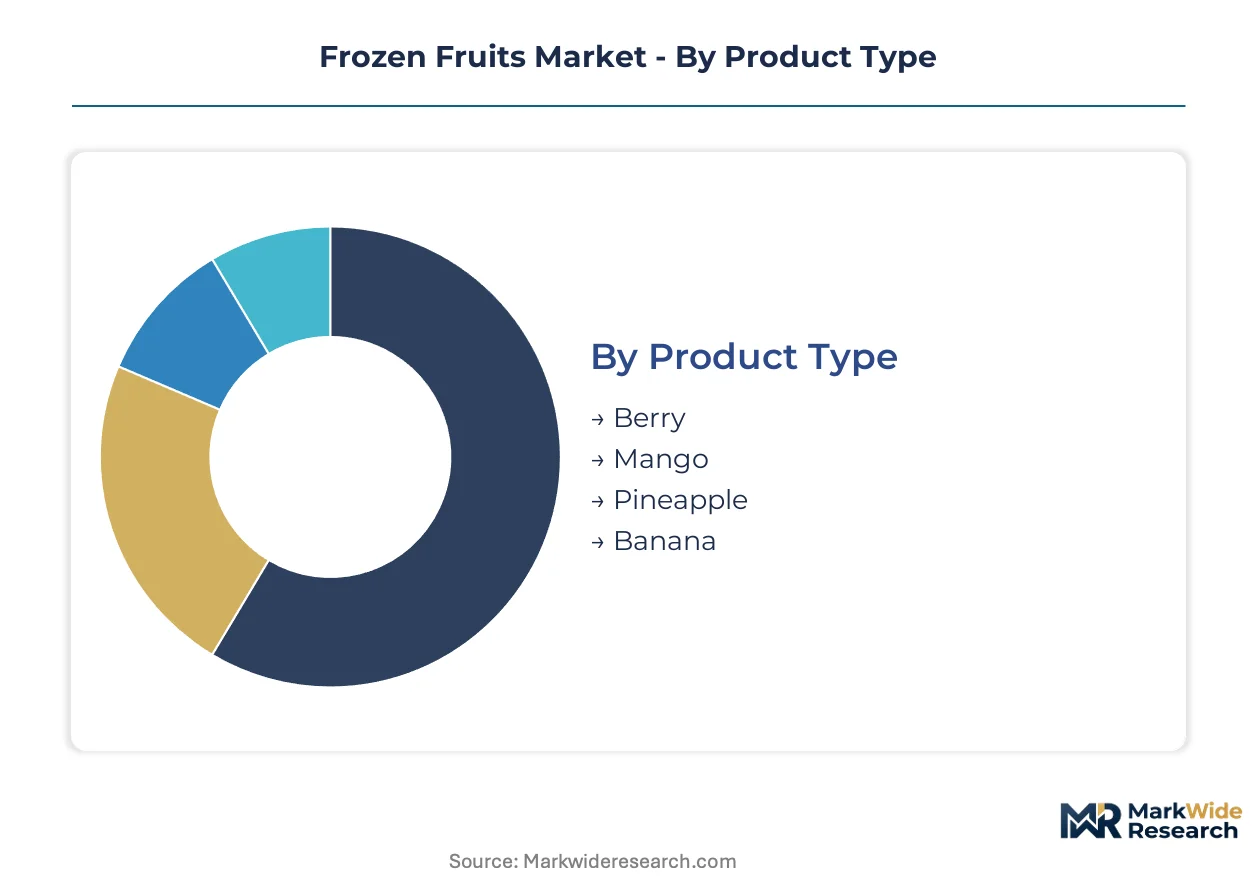
The Frozen Fruits Market is intricately segmented, reflecting diverse product types, end-user applications, and distribution methodologies. Understanding these distinct segments provides clarity on demand drivers and competitive landscapes. This granular analysis helps stakeholders identify specific growth pockets and tailor their strategies effectively across the value chain.
Product Type:
Product types define the core offerings flowing through various commercial and retail channels, influencing sourcing and processing requirements.
- Berry:This segment includes strawberries, blueberries, raspberries, and blackberries, often individually quick frozen to maintain structural integrity. Demand concentrates in the food services sector, particularly for smoothies and dessert preparations in the United States.
- Mango:Mangoes are typically processed into chunks or slices using IQF technology, prized for their tropical flavor and vibrant color. Industrial manufacturers utilize frozen mango for juices and purees, seeing robust demand from beverage companies in Germany.
- Pineapple:Frozen pineapple chunks provide a convenient, ready-to-use ingredient for both household consumers and industrial applications.
- Banana:Frozen banana slices are commonly used in smoothies and as a base for dairy-free desserts, appealing to health-conscious consumers.
By volume, the Berry segment leads the market. By growth pace, Mango is expanding most quickly due to its versatility in various applications.
End User:
End-user categories delineate distinct purchasing behaviors and volume requirements, influencing packaging and delivery logistics.
- Food Services:This segment encompasses restaurants, cafes, and smoothie bars that purchase frozen fruits in bulk for immediate preparation and menu consistency. Cafes in major European cities drive consistent demand for pre-portioned fruit mixes.
- Manufacturers:Industrial food manufacturers utilize large volumes of frozen fruits as raw materials for yogurts, jams, bakery fillings, and ready meals. Beverage producers in Asia-Pacific are a significant end-user, requiring consistent supply for their product lines.
- Retailers:Retailers distribute packaged frozen fruits directly to household consumers through supermarkets and convenience stores.
- Households:Individual consumers purchase frozen fruits for home consumption, primarily for smoothies, breakfast bowls, and baking.
The Food Services segment holds a substantial market share. Meanwhile, the Manufacturers segment exhibits strong potential for future expansion.
Size Category:
Size categories reflect the varying quantities purchased by different customer types, impacting pricing strategies and production line configurations.
- Bulk:These large-volume packages, typically over 5 kg, cater primarily to industrial manufacturers and large food service operations requiring substantial raw material supply. Processors in Southeast Asia often fulfill bulk orders for European importers.
- Family Pack:Designed for larger households, these packs offer greater quantities, usually 1-2 kg, providing value and convenience for frequent home use. Supermarket chains in the United States prioritize stocking diverse family pack options.
- Small Pack:Individual-serving or smaller-portion packs, typically under 500g, target single consumers or specific recipe requirements.
- Medium Pack:These intermediate-sized packages, generally 500g to 1kg, balance convenience and value for average household consumption.
The Bulk size category maintains a dominant market presence. The Family Pack segment is gaining significant traction among consumers seeking value and convenience.
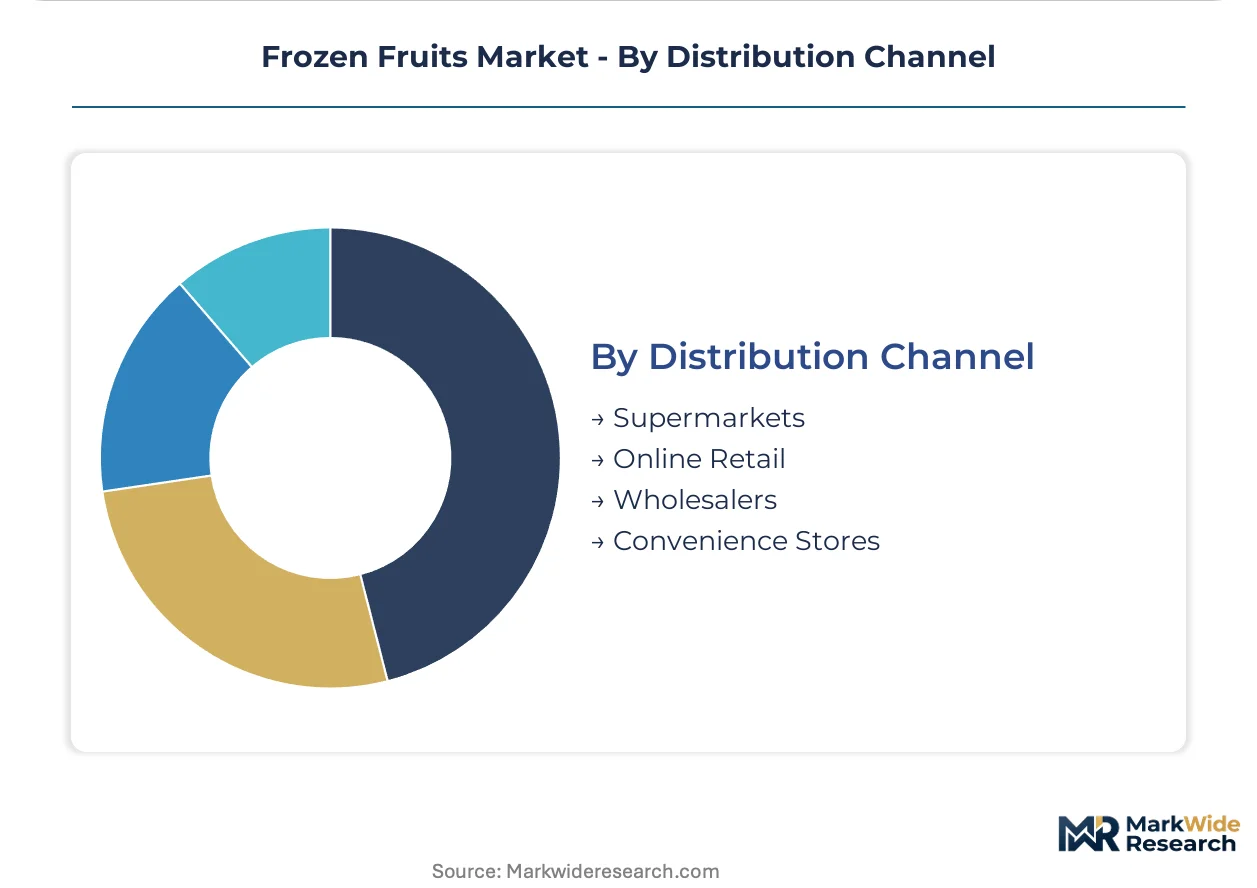
Distribution Channel:
Distribution channels define the pathways through which frozen fruit products reach their end consumers, influencing market reach and logistical investments.
- Supermarkets:These large retail chains serve as a primary distribution channel for packaged frozen fruits, offering wide product selection and broad consumer access. Major supermarket groups in Germany significantly influence product placement and promotions.
- Online Retail:E-commerce platforms and grocery delivery services facilitate direct-to-consumer sales, providing convenience and expanding market penetration, especially in urban areas. Digital platforms in the United States are seeing rapid growth for subscription-based frozen fruit deliveries.
- Wholesalers:Wholesalers act as intermediaries, supplying frozen fruits in larger quantities to smaller retailers, food service providers, and institutional buyers.
- Convenience Stores:These smaller retail outlets offer limited selections of frozen fruits, primarily targeting immediate consumption needs or impulse purchases.
Supermarkets represent the most established distribution channel. Online Retail is steadily expanding its market penetration, driven by evolving consumer shopping habits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration significantly influences the frozen fruits market across diverse geographies. Food service and manufacturing sectors drive substantial demand for bulk frozen fruits globally. Consumer health trends and evolving retail channels further shape regional consumption patterns.
United States
Consumer health trends and the robust food service sector fuel demand for organic and non-GMO frozen fruits. The U.S. Food and Drug Administration (FDA) sets strict standards for pesticide residue levels and labeling. Major cities like Los Angeles and New York exhibit high consumption rates for smoothie ingredients.
Germany
Cafes and industrial beverage producers generate consistent demand for frozen mango and berry products. The European Food Safety Authority (EFSA) mandates stringent regulations on food safety and traceability. The Rhine-Ruhr metropolitan region serves as a hub for food processing and distribution.
China
Beverage producers and ready-meal manufacturers represent a growing end-user segment for frozen fruits. China's General Administration of Customs (GACC) oversees import regulations and quality inspections. Major coastal cities such as Shanghai and Guangzhou are seeing increased cold chain infrastructure development.
Brazil
The expanding food processing industry and rising consumer disposable income drive demand for frozen fruit purees and concentrates. Brazil's National Health Surveillance Agency (ANVISA) regulates food additives and processing standards. São Paulo acts as a key distribution and manufacturing center for frozen food products.
Vietnam
Processors in Southeast Asia fulfill bulk orders for European importers, focusing on cost-effective production. The Ministry of Agriculture and Rural Development (MARD) promotes sustainable agricultural practices for fruit cultivation. Ho Chi Minh City is a significant export hub for frozen fruit products.
Frozen Fruits Market Key Industry Players
Player mix skews toward large-scale food processors and specialized organic suppliers within the frozen fruits market. The competitive structure features both multinational conglomerates with extensive supply chains and niche players focusing on specific product attributes. Strategic archetypes include vertically integrated producers, ingredient specialists, and private label manufacturers. Companies frequently engage in capacity expansion and portfolio diversification, alongside strategic partnerships, to capture market share in evolving segments.
Specialists in organic and non-GMO offerings, such as SunOpta Inc., occupy a significant position by catering to health-conscious consumers seeking clean-label products and sustainable sourcing. Dole Food Company, leveraging its extensive plantation network, exemplifies a large-scale, vertically integrated producer ensuring consistent raw material supply for its diverse frozen fruit lines globally. Ardo NV represents a European-based player competing on the basis of its wide geographic manufacturing footprint across the continent, serving both retail and food service segments with diverse product types and customized blends.
| Leading Market Players |
|---|
| Fresh Del Monte Produce Inc. |
| J.R. Simplot Co. |
| General Mills Inc. |
| Bonduelle North America |
| SunOpta Inc. |
| Dole Food Company |
| Ardo NV |
| Pinnacle Foods |
| Conagra Brands |
| Others |
Cost & Logistics Intelligence
A 90-day inventory buffer for frozen berries underpins processor resilience against seasonal supply shocks, influencing long-term contract pricing power with food service giants.
Pricing Analysis
Cost-plus contract patterns with agricultural commodity indexation dominate procurement, particularly for bulk frozen fruit orders destined for industrial manufacturers. Price differentiation stems from the quality grade of the fruit and the certification level, such as BRCGS Global Standard compliance. Pricing pressure stems from the consolidated buying power of large retail and food service chains, driving a constant need for cost efficiency. The household segment, particularly for small pack sizes, exhibits the highest price sensitivity, while industrial manufacturers prioritize consistent quality and supply stability.
Supply Chain Analysis
Climate change-induced crop failures in Southeast Asia create a chokepoint for mango and pineapple supply, impacting global ingredient availability. Supply concentrates heavily in countries like Vietnam for cost-effective processing and Brazil for fruit purees. The supply chain relies on consistent access to raw fruits, energy for freezing, and specialized cold chain logistics. A structural risk involves the volatility of agricultural yields due to weather events. Distribution runs through a dual model, with bulk orders handled by wholesalers and packaged products moving through supermarkets and online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen fruits market faces a critical capability gap in advanced cold chain logistics, limiting market penetration in emerging economies and efficient distribution of delicate fruits.
For Market Incumbents: Fortify existing supply chain relationships through long-term offtake agreements with growers in Brazil to mitigate agricultural dependence and raw material price volatility. Invest in advanced IQF technology upgrades to enhance product quality and reduce energy consumption, addressing the threat of rising operational costs. Pursue backward integration into fruit cultivation to gain greater control over raw material quality and supply consistency.
For New Entrants and Emerging Players: BRCGS Global Standard certification fast-track enables market entry for specialized organic fruit processors, targeting the underserved nutraceutical segment in Germany. Focus on niche product types like frozen banana slices for dairy-free dessert applications, leveraging direct-to-consumer subscription models. The household segment in urban areas of the United States offers a penetrable market for pre-portioned smoothie packs, with convenience as a key go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because operational efficiencies from scale are paramount for margin preservation against retail buyer pressure. Target mid-sized processors with strong regional distribution networks or specialized IQF capabilities. The signal to watch is the sustained growth in emerging market cold chain infrastructure, indicating new avenues for product distribution and consumption.
| Strategic Initiative | Industry Significance |
|---|---|
| IQF Technology Investment | Enhances fruit texture and nutrient retention, improving product appeal for food service clients. |
| BRCGS Global Standard Certification | Secures market access in regulated markets like Europe, facilitating cross-border trade for processors. |
| Direct-to-Consumer Channel Development | Expands market reach beyond traditional retail, capturing health-conscious household consumers. |
| Long-term Supplier Contracts | Stabilizes raw material procurement and mitigates price volatility for large-scale manufacturers. |
| Functional Fruit Blend Innovation | Addresses evolving consumer demand for fortified food products in the nutraceutical segment. |
Research Approach
Cross-validation between primary interviews with food service procurement managers and secondary trade data from the USDA anchors the qualitative findings on market dynamics. This approach integrated insights from supply chain executives, R&D specialists, and retail category buyers across key geographies. Top-down revenue modeling and bottom-up volume aggregation informed market sizing and segmentation analysis.
Sensitivity analysis on energy cost fluctuations and agricultural yield variability informs the projected market trajectory across the modeling period. The analytical framework modeled market evolution across product types, end-user segments, size categories, and distribution channels. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected demand for specific fruit varieties like mango and berries.
Decision-makers should treat outputs as directional under stable regulatory frameworks; material deviation in pesticide residue limits would warrant model refresh. Forecasts reflect assumptions concerning global economic stability and consumer spending patterns. Practitioners should keep alternative scenarios live as global trade policies and climate patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Butterfly Pea Flowers Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
Morocco Fruits and Vegetables Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Global Avocado Market