
 Fresh Figs Market | 2026-2036
Fresh Figs Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Figs Market Foresight
Specialty produce distribution is rewriting how Mediterranean-origin fruit reaches North American and European retail. Kirlioglu Figs anchors Turkish export volumes through direct control of Aegean packing facilities. Valley Fig Growers Inc. dominates California's organic fig segment with vertically integrated orchards in the San Joaquin Valley. Roland Foods LLC competes in the premium dried and fresh import channel through established relationships with Mediterranean cooperatives.
Fresh figs are the edible, climacteric fruit of Ficus carica, harvested at 35-40 degrees Brix sugar concentration for immediate consumption or controlled-atmosphere storage. Their primary commercial purpose centers on premium fresh retail, ingredient supply for culinary applications, and raw material for nutraceutical extraction. Black Mission and Calimyrna cultivars lead fresh shelf presence in U.S. supermarkets, while the nutraceuticals application draws escalating R&D investment for ficin enzyme and fiber isolates. Food Processing segments show structural margin compression from seasonal supply volatility, pushing processors toward contract farming arrangements.
The USDA Agricultural Marketing Service grades fresh figs for size and defect tolerance under federal standards, while the FDA enforces Produce Safety Rule microbial controls across domestic and import supply chains. Turkey's Ministry of Agriculture and Forestry applies export phytosanitary certification that determines market access timing for Aegean shipments. California's State Water Resources Control Board irrigation restrictions are forcing growers toward deficit-irrigation scheduling and cultivar substitution. Stakeholders must monitor whether evolving water policy and import phytosanitary reciprocity agreements reshape competitive sourcing geography before the next planting cycle.
Market Dynamics
California's State Water Resources Control Board irrigation restrictions are forcing fig growers toward deficit-irrigation scheduling and cultivar substitution, fundamentally altering production economics across the San Joaquin Valley.
Growth Catalysts
- Plant-forward menu expansion:Gourmet food service providers are expanding fig procurement for Mediterranean-inspired dishes, driving premium fresh demand in North American metropolitan markets.
- REACH-compliant nutraceutical extraction:European Union chemical safety standards are accelerating R&D investment for ficin enzyme and fiber isolates from fresh fig biomass.
- Aegean cultivation expertise:Turkey's centuries-old fig farming traditions support consistent premium export grades that command shelf space in EU and US retail channels.
Market Restraints
- Input cost volatility:Water scarcity in California's Central Valley is elevating irrigation infrastructure costs and forcing deficit-irrigation investments that compress grower margins.
- Supply concentration risk:Turkey's Aegean region controls dominant export volumes, creating phytosanitary certification bottlenecks that determine seasonal market access timing.
- Technical limitation:Climacteric ripening physiology restricts fresh fig shelf life to narrow harvest-to-retail windows, limiting distribution radius from production clusters.
Strategic Opportunities
- Controlled-atmosphere storage expansion:Advanced CA technology adoption in Turkish packing facilities is extending export seasonality and opening Asian market access.
- FDA Produce Safety Rule alignment:Import compliance investments by Mediterranean cooperatives are unlocking US retail channel expansion for previously excluded suppliers.
- Culinary ingredient diversification:Food manufacturers are developing fig-based clean-label sweeteners and fiber fortifiers for bakery and beverage applications.
Industry Challenges
- Phytosanitary certification timelines:Turkey's Ministry of Agriculture and Forestry export protocols create unpredictable clearance delays that disrupt just-in-time retail replenishment.
- Orchard reconfiguration costs:California growers face capital-intensive cultivar substitution and drip-irrigation retrofitting to meet State Water Resources Control Board mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Figs Market |
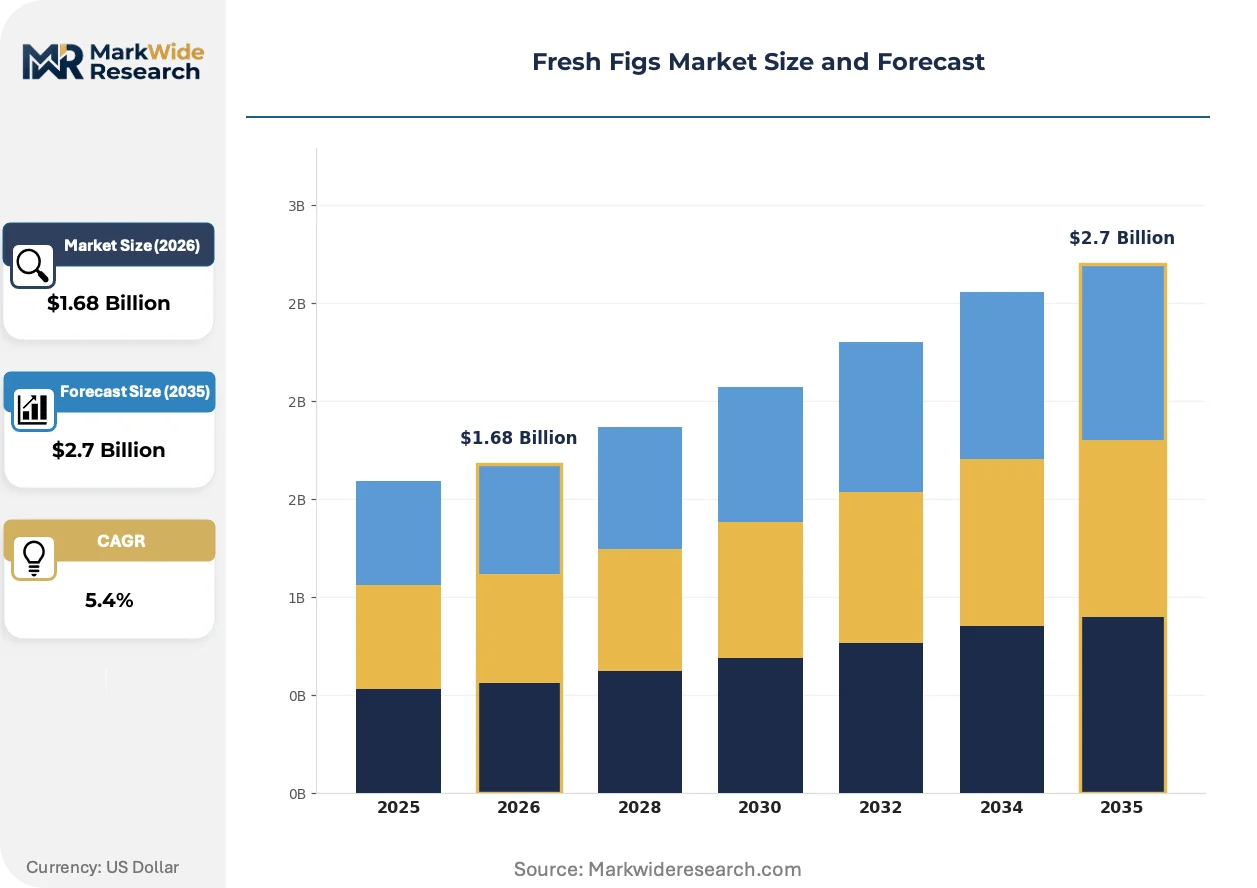
| Market Size in 2026 | $1.68 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Mission, Kadota, Calimyrna, Adriatic, Brown Turkey Application: Direct Consumption, Culinary Ingredients, Food Processing, Confectionery, Nutraceuticals Packaging Type: Plastic Clamshells, Paper Boxes, Bulk Bins, Mesh Bags, Carton Trays End User: Supermarkets, Specialty Stores, Food Service Providers, Farmers Markets, Exporters |
| Companies Covered | Athos Agricola S.A., Earl's Organic Produce, Hadley Fruit Orchards Inc., Valley Fig Growers Inc., Kirlioglu Figs, Roland Foods LLC, Meurens Naturals S.A., FruitLips, Jiaherb Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Figs Market Shifts & Advancements
Fresh fig supply chains are undergoing simultaneous digitization, regulatory tightening, and demand-side channel restructuring that together compress traditional intermediation layers.
Precision agriculture platforms deploying soil-moisture sensors and satellite imagery are digitizing irrigation scheduling across California orchards. Large-scale San Joaquin Valley growers are adopting these systems fastest, with mid-size operations following within two growing seasons. This technology is digitizing water-use accountability and enabling real-time compliance documentation for State Water Resources Control Board audits.
The EU's Farm to Fork Strategy under the European Green Deal is mandating 25% organic agriculture land conversion by 2030. This policy is redirecting Aegean region cultivation toward certified organic protocols that satisfy EU retail procurement standards. Turkish export cooperatives are responding with integrated pest management transitions and third-party organic certification investments.
Direct-procurement relationships between food service operators and Aegean packing facilities are displacing traditional import-distributor intermediaries. Specialty produce distributors in Germany and the Netherlands are losing volume to these direct channels as restaurant chains seek provenance transparency. This disintermediation is most visible in Amsterdam and Berlin's premium restaurant supply networks.
Fresh Figs Market Segmentation
Fresh fig segmentation reveals how cultivar diversity, channel specialization, and end-use differentiation create distinct margin pools across the value chain. Understanding these segment boundaries helps stakeholders align procurement and cultivation investments with where value concentrates.
Product Type:
After-sales service intensity varies sharply by cultivar, as premium varieties demand specialized cold-chain support and varietal-specific handling protocols that extend supplier relationships post-sale.
- Black Mission:Deep purple-black skin with strawberry-red flesh delivers concentrated sweetness at 35-40 degrees Brix. Demand clusters in California's direct-to-retail channels and Mediterranean export markets where visual uniformity commands shelf placement premiums. The cultivar's established grafting protocols and predictable bearing habit sustain grower preference despite water stress vulnerability.
- Calimyrna:Golden-yellow skin with amber flesh offers nutty flavor profiles suited to fresh cheese pairings and charcuterie applications. Turkish Aegean growers dominate supply, with San Joaquin Valley plantings expanding under deficit-irrigation trials. The cultivar's thicker skin extends shelf life, reducing retail shrink and supporting longer distribution radii from production clusters.
- Kadota:Greenish-yellow skin with light amber flesh carries lower sugar intensity, positioning it for processing applications where added sweeteners standardize output.
- Adriatic:Light green skin with strawberry-pink interior commands niche premium positioning in Italian and Croatian coastal markets with strong culinary tourism traffic.
- Brown Turkey:Rust-brown skin with pale pink flesh offers cold-hardiness advantages for marginal growing regions and backyard cultivation volumes.
Black Mission holds the largest share; momentum sits with Calimyrna as water-scarce regions prioritize shelf-stable cultivars.
Application:
Application segmentation tracks how figs traverse from raw agricultural commodity through value-added transformation, with each stage imposing distinct technical specifications and margin structures.
- Direct Consumption:Premium fresh retail demands harvest-stage ripeness at 35-40 degrees Brix, controlled-atmosphere storage, and rapid cold-chain transit. North American metropolitan markets and EU urban centers drive volume, with Turkish Aegean exporters capturing dominant share through phytosanitary-certified shipments.
- Food Processing:Paste, concentrate, and dried fig production requires standardized Brix levels and defect tolerance that contract farming arrangements increasingly secure. California's vertically integrated processors leverage San Joaquin Valley proximity to compress harvest-to-processing windows and minimize spoilage.
- Culinary Ingredients:Restaurant and food service procurement emphasizes provenance documentation and varietal specificity for menu differentiation.
- Confectionery:Chocolate enrobing and fig-based candy applications demand moisture-calibrated supply with consistent texture profiles.
- Nutraceuticals:Ficin enzyme and fiber isolate extraction draws escalating R&D investment under EU REACH compliance frameworks, with biomass sourcing contracts emerging as a distinct procurement category.
Direct Consumption generates the highest unit margins; Nutraceuticals is climbing the fastest as functional food investment accelerates.
Packaging Type:
Packaging configuration determines retail channel access and shelf-life extension, with format selection directly tied to distribution distance and target consumer occasion.
- Plastic Clamshells:Clear PET or recycled plastic shells with ventilation ports dominate supermarket fresh produce sections, offering visibility and physical protection. North American retail chains mandate this format for premium cultivars, with Turkish packing facilities investing in automated clamshell lines to meet volume specifications.
- Paper Boxes:Kraft or coated cardboard containers serve farmers markets and specialty retail channels where sustainability signaling supports price positioning. EU Farm to Fork Strategy alignment is accelerating paper format adoption in German and Dutch procurement specifications.
- Bulk Bins:Wooden or corrugated containers support food service and processing volumes where downstream handling occurs within hours of delivery.
- Mesh Bags:Ventilated polyethylene netting offers economy-tier retail positioning and reduced material cost for high-volume, shorter-shelf-life distribution.
- Carton Trays:Single-layer corrugated with cell dividers protects delicate cultivars for air freight export and long-distance refrigerated transport.
Plastic Clamshells command the greatest volume; Paper Boxes are gaining share fastest as sustainability procurement criteria tighten.
End User:
End-user concentration shapes cultivation planning, with channel-specific quality standards and volume predictability creating distinct supplier relationship models.
- Supermarkets:Multi-banner retail chains demand year-round availability, consistent sizing, and third-party food safety certification. California's Valley Fig Growers and Turkish export cooperatives compete for shelf space through dedicated buyer relationships and promotional calendar alignment.
- Food Service Providers:Restaurant chains and institutional catering operations prioritize provenance transparency and direct-procurement relationships that bypass traditional distributor intermediaries. Amsterdam and Berlin premium restaurant networks exemplify this disintermediation trend.
- Specialty Stores:Gourmet grocers and ethnic food retailers emphasize heritage cultivars and origin-specific merchandising.
- Farmers Markets:Direct producer-to-consumer sales capture highest per-unit margins but limit scale and geographic reach.
- Exporters:Consolidated shipment coordination for Asian and Middle Eastern markets requires phytosanitary certification mastery and controlled-atmosphere logistics investment.
Supermarkets represent the deepest volume base; Food Service Providers are expanding most quickly as plant-forward menu development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey's export incentive programs for Aegean agricultural cooperatives are redirecting investment toward controlled-atmosphere packing infrastructure. California's State Water Resources Control Board mandates are compressing domestic production economics while EU Farm to Fork organic conversion targets reshape Mediterranean cultivation protocols.
United States
Plant-forward menu expansion in metropolitan restaurant chains drives premium fresh fig procurement through direct-procurement channels. The FDA enforces Produce Safety Rule microbial controls across both domestic San Joaquin Valley operations and Turkish import shipments. Fresno County and Madera County orchards face State Water Resources Control Board irrigation restrictions that elevate deficit-irrigation capital requirements.
Turkey
Aegean region exporters command dominant shelf placement in EU and US retail through phytosanitary-certified shipments of Black Mission and Calimyrna cultivars. Turkey's Ministry of Agriculture and Forestry applies export certification protocols that determine seasonal market access timing for Aydın and İzmir packing facilities. Centuries-old cultivation expertise in the Aegean coastal zone supports consistent premium grade output.
Germany
Specialty produce distribution networks in Berlin and Amsterdam are losing volume to direct-procurement relationships between restaurant chains and Aegean packing facilities. The EU Farm to Fork Strategy mandates 25% organic land conversion by 2030, redirecting Turkish export cooperative investment toward integrated pest management transitions. Hamburg and Rotterdam cold-chain hubs handle expanding controlled-atmosphere shipments for Asian market re-export.
France
Culinary tourism traffic in Provence-Alpes-Côte d'Azur sustains niche demand for Adriatic cultivar figs in coastal restaurant supply chains. ECHA REACH compliance frameworks accelerate R&D investment for ficin enzyme extraction from fresh fig biomass. Parisian premium retail channels emphasize provenance documentation through direct relationships with Turkish organic-certified cooperatives.
Spain
Andalusian growers compete with Turkish Aegean exports for EU retail shelf space through shorter distribution radii to Madrid and Barcelona metropolitan markets. Spanish agricultural regulators enforce EU organic certification standards that align with Farm to Fork Strategy procurement criteria. Valencia and Murcia packing facilities invest in automated clamshell lines to meet North American retail volume specifications.
Fresh Figs Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated orchard operators and Mediterranean export cooperatives with direct packing facility control. Two strategic archetypes dominate: Aegean-based exporters leveraging phytosanitary certification mastery for EU and US retail access, and California growers with captive San Joaquin Valley orchards serving organic domestic channels. Competitive moves center on controlled-atmosphere storage capacity expansion and cultivar substitution toward water-efficient varieties.
Within the Aegean export archetype, Kirlioglu Figs represents direct packing facility control models, while Valley Fig Growers Inc. anchors California's vertically integrated organic segment. Roland Foods LLC occupies a position in premium import channel relationships. These three exemplify how geographic concentration and regulatory compliance investments create defendable positioning against distributor disintermediation trends.
| Leading Market Players |
|---|
| Athos Agricola S.A. |
| Earl's Organic Produce |
| Hadley Fruit Orchards Inc. |
| Valley Fig Growers Inc. |
| Kirlioglu Figs |
| Roland Foods LLC |
| Meurens Naturals S.A. |
| FruitLips |
| Jiaherb Inc. |
| Others |
Supply & Pricing Matrix
Turkey's Aegean packing facility concentration funnels margin capture toward phytosanitary-certified exporters while California's water-scarce growers absorb cost compression from State Water Resources Control Board compliance investments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments fresh fig procurement by cultivar grade and certification status. Price differentiation rests on organic certification tier and controlled-atmosphere storage capability, with Aegean-origin Black Mission commanding shelf placement premiums. Pricing pressure stems from deficit-irrigation capital requirements compressing California grower margins. Food service providers show lowest price sensitivity due to provenance transparency demands, while supermarket chains negotiate hardest on volume contracts.
Supply Chain Analysis
Export-control regime phytosanitary certification from Turkey's Ministry of Agriculture and Forestry gates seasonal market access timing for Aegean shipments. Geographic supply concentration centers on Turkey, California, and Spain, with raw material dependencies on irrigation water access, grafted rootstock supply, and cold-chain equipment. Supply chain risk manifests through single-source vulnerability from Aegean export dominance. Distribution runs through direct-procurement channels displacing traditional import-distributor intermediaries in North American and European metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Profitable expansion in fresh fig supply chains hinges on controlled-atmosphere logistics mastery and phytosanitary certification navigation—capabilities concentrated among Aegean export cooperatives with decades of regulatory relationship depth.
For Market Incumbents: Entrench position through backward integration into deficit-irrigation infrastructure and cultivar substitution toward water-efficient Calimyrna varieties. California growers face margin pressure from State Water Resources Control Board mandates; priority lever sits in captive packing facility investment to capture downstream margin pools from direct-procurement restaurant channels. For New Entrants and Emerging Players: Mid-tier organic certification gaps in Spanish Andalusian supply represent the most penetrable entry point for EU retail shelf placement. Target German and Dutch sustainability-focused procurement specifications under Farm to Fork Strategy alignment. Go-to-market angle emphasizes integrated pest management transitions with third-party organic certification investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Mediterranean export cooperatives lacking controlled-atmosphere technology modernization. Long-term viability frames around 5-10 year organic land conversion trajectories and Asian market access expansion. Signal to watch: Turkish Ministry of Agriculture and Forestry reciprocity negotiations with FDA for streamlined phytosanitary clearance timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Atmosphere Storage Expansion | Turkish packing facilities extend export seasonality and unlock Asian market access through advanced CA technology. |
| Organic Certification Investment | Aegean cooperatives align with EU Farm to Fork Strategy procurement criteria for German and Dutch retail channels. |
| Deficit-Irrigation Infrastructure | California growers meet State Water Resources Control Board mandates while stabilizing yield predictability. |
| Direct-Procurement Channel Development | Food service operators bypass distributor intermediaries for provenance transparency in Amsterdam and Berlin networks. |
| Phytosanitary Compliance Alignment | Mediterranean cooperatives unlock US retail expansion through FDA Produce Safety Rule certification investment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA Agricultural Marketing Service grading standards, FDA Produce Safety Rule documentation, and Turkish Ministry of Agriculture and Forestry export protocols. Primary interviews engaged fig growers in California's San Joaquin Valley, Aegean packing facility operators, specialty produce distributors in Germany and the Netherlands, and food service procurement directors in metropolitan North American markets. Secondary validation drew from customs trade data, EU Farm to Fork Strategy policy documents, and State Water Resources Control Board regulatory filings. Bottom-up cultivation volume estimates triangulate against top-down retail channel demand assessments.
Forecast inputs incorporate cultivar-specific yield modeling, water availability scenarios under California irrigation restrictions, and phytosanitary certification timeline distributions. Segmentation dimensions span product type by cultivar, application by end-use transformation stage, packaging format by distribution distance, and end-user channel by procurement relationship structure. CAGRs derive from compounding annual growth assumptions calibrated to historical trade flow patterns and documented policy implementation trajectories. Industry-specific inputs include controlled-atmosphere technology adoption curves and organic land conversion commitment schedules.
Practitioners should monitor regulatory reciprocity negotiations, water policy enforcement intensity, and controlled-atmosphere logistics investment trajectories for early signals of forecast deviation. Material shifts in FDA-Turkey phytosanitary protocol alignment or California groundwater sustainability mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Dill Pickles Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Asia-Pacific Shiitake Mushroom Market
Fruits and Vegetables
Rosehip Market