
 Transient Protein Expression Market | 2026-2036
Transient Protein Expression Market Size, Share, and Industry Trends Forecast 2026-2036
Transient Protein Expression Market Analytics
The capital-intensity divergence between platform-owning incumbents and reagent-reliant challengers is reorganizing competitive tiers in transient protein expression. Thermo Fisher Scientific leverages its end-to-end workflow portfolio to dominate instrument-reagent bundles. Merck KGaA anchors its position through deep expertise in cell line engineering and transfection-grade media. Lonza competes via specialized contract development services that integrate transient expression into larger biomanufacturing pipelines.
Transient protein expression describes a short-duration, non-viral method for producing recombinant proteins in host cells without stable genomic integration, typically achieving milligram-to-gram yields within days using suspension-adapted HEK293 or CHO systems. The technique serves drug discovery timelines that require rapid protein supply for target validation, lead optimization, and early pharmacokinetic studies. Among product types, plasmids and specialized cell lines capture the deepest margin pools due to recurring purchase cycles and customization barriers. Reagents represent the highest-volume category but face price compression from generic alternatives. Electroporation technology leads in clinical-scale applications where transfection efficiency directly determines yield consistency.
FDA guidelines on host cell protein impurities and EMA requirements for genetically modified organism containment shape platform validation protocols and facility investment decisions. ISO 13485 and GMP-adjacent quality standards increasingly govern transient systems used in pre-clinical-to-clinical transitions. Stakeholders must monitor how evolving pharmacopeial standards for cell-derived products redefine acceptable documentation burdens for non-integrated expression methods.
Market Dynamics
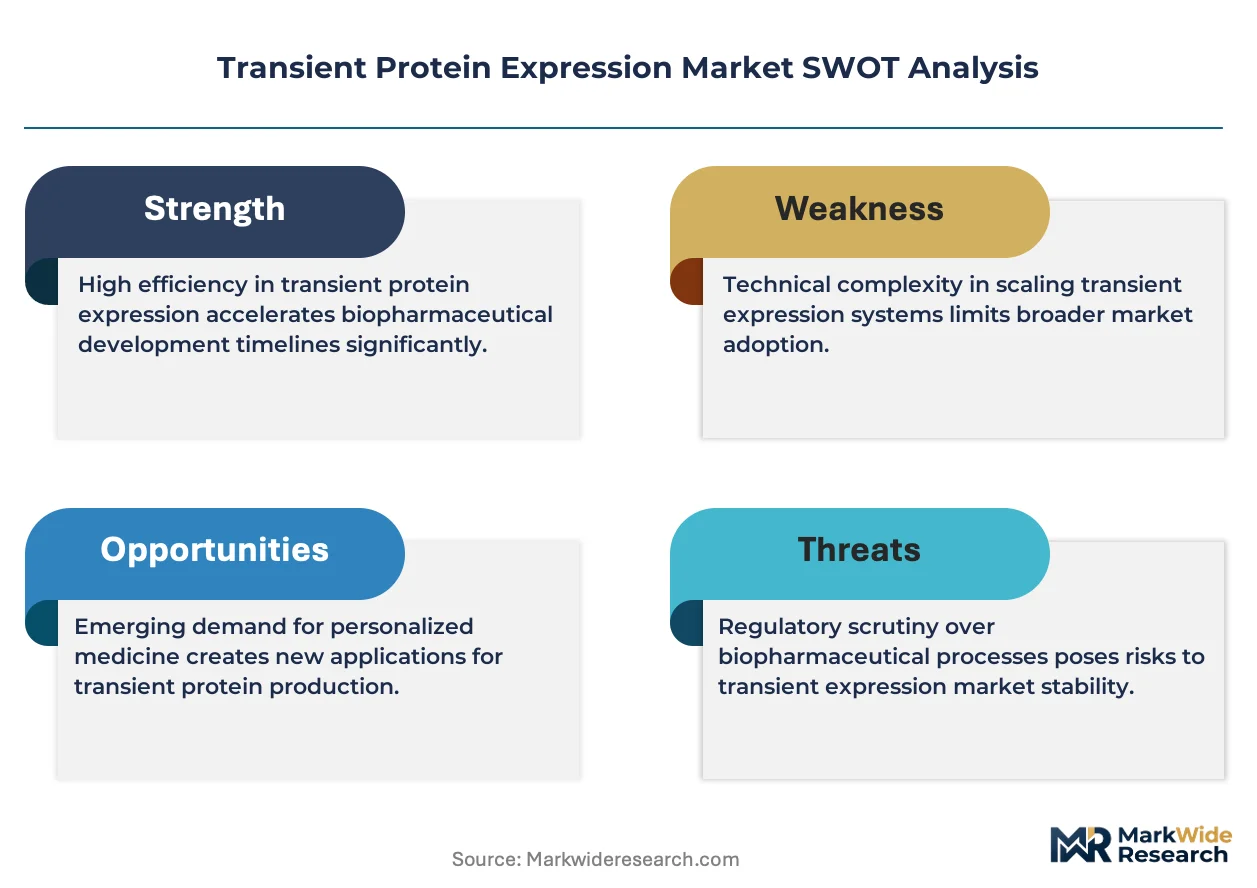
Platform standardization pressure from the FDA and EMA is compressing validation timelines and forcing reagent suppliers to consolidate quality documentation, restructuring how contract manufacturers select transient expression partners.
Growth Catalysts
- EMA containment protocols:Stringent genetically modified organism handling requirements in Europe are accelerating facility upgrades toward closed-system transient platforms that reduce cross-contamination risk.
- Antibody discovery pipelines:Pharmaceutical screening programs require gram-scale protein batches within two-week windows, pulling demand toward high-throughput HEK293 suspension systems.
- Boston-San Diego corridor:Concentrated biotech clusters in these US cities generate dense demand for local contract research organizations offering integrated transient-to-stable expression handoffs.
Market Restraints
- Plasmid DNA supply volatility:Fermentation capacity for GMP-grade plasmid production concentrates among fewer than ten specialized suppliers globally, creating input bottlenecks.
- Host cell protein clearance thresholds:FDA impurity guidelines impose downstream purification burdens that extend process development timelines by 30-40% for clinical-grade batches.
- Stable cell line substitution:Improved CHO pool generation technologies offer comparable speed with better lot-to-lot consistency, capturing share in late-stage preclinical work.
Strategic Opportunities
- India's biologics manufacturing expansion:CDSCO regulatory alignment with ICH guidelines and government production-linked incentives are attracting transient platform investments for export-oriented antibody supply.
- Cell-free expression convergence:Hybrid workflows combining extract-based systems with transient transfection address toxic protein categories that fail in living cells.
- ISO 13485 certification gaps:Fewer than 15% of reagent vendors hold full medical device quality certification, creating white space for documented supply to diagnostic instrument manufacturers.
Industry Challenges
- Transfection optimization expertise:Shortage of scientists proficient in electroporation parameter tuning for novel cell lines delays platform transfer between contract organizations.
- GMP-adjacent facility capital:Single-use bioreactor suites for transient production require $8-12 million per 2,000-liter train, constraining mid-tier service provider expansion.
- Intellectual property thickets:Overlapping patents covering codon-optimized vectors and proprietary enhancer sequences complicate freedom-to-operate assessments for custom plasmid development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transient Protein Expression Market |
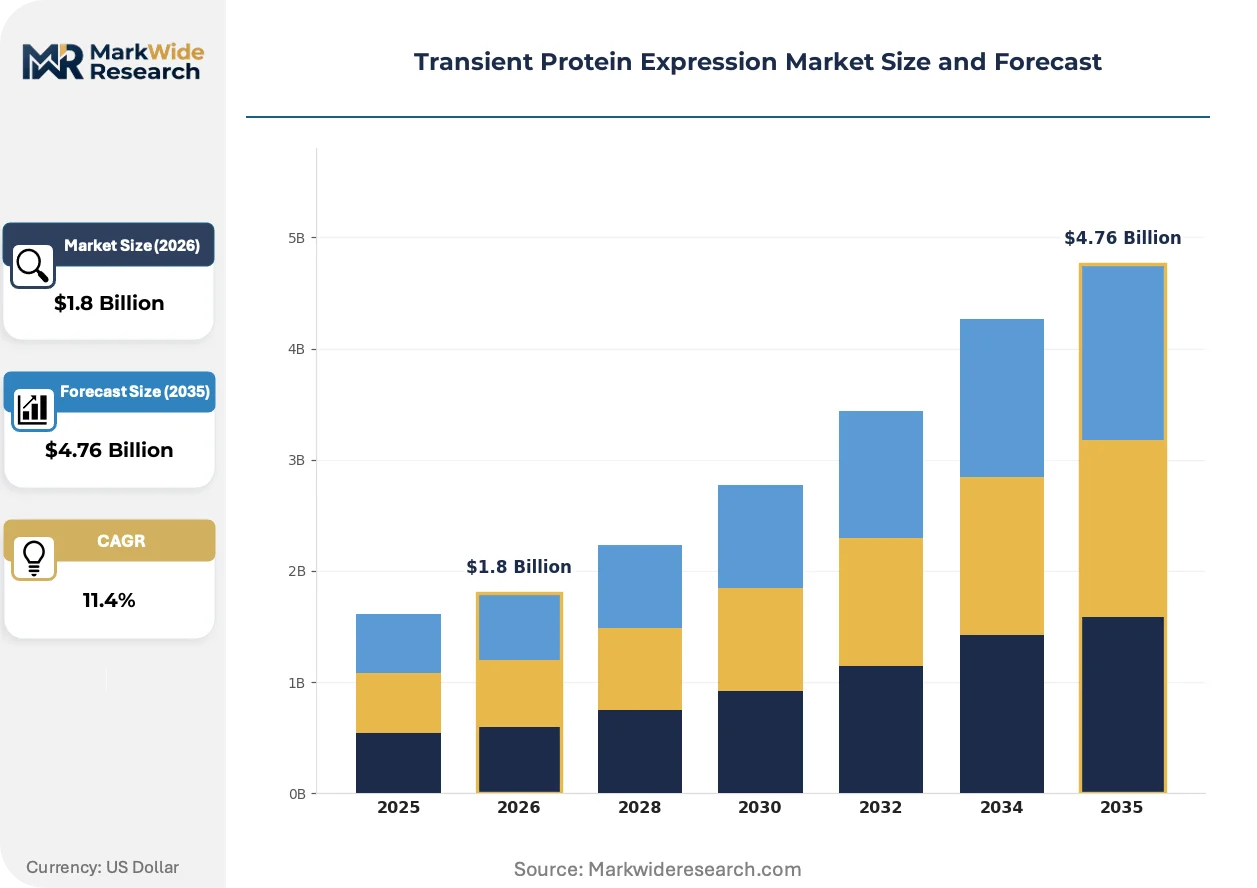
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmids, Vectors, Cell Lines, Reagents Technology: Transfection, Electroporation, Viral Transduction, Microinjection End User: Biotechnology Companies, Pharmaceutical Firms, Academic Institutions, Research Organizations Application: Drug Development, Vaccine Production, Therapeutic Protein Production, Research Studies |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Lonza, Promega Corporation, QIAGEN, Bio-Rad Laboratories, Takara Bio, Agilent Technologies, GenScript Biotech Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transient Protein Expression Market Evolving Landscape
Automation and artificial intelligence are compressing the design-build-test cycle for transient expression constructs, while regulatory agencies tighten traceability requirements for cell-derived starting materials used in clinical manufacturing.
CRISPR-mediated transient knock-in systems are bifurcating the market between rapid screening applications and higher-fidelity protein engineering workflows. Academic core facilities and early-stage biotechs adopt these tools for accelerated target validation. The technology is bifurcating vendor strategies into disposable reagent kits versus capital-intensive automated platforms.
REACH chemical registration requirements for novel transfection reagents are extending European commercialization timelines by 18-24 months. Manufacturers now pre-register polymer components in bulk to avoid batch-specific delays. Smolecule reagent suppliers without dedicated regulatory affairs teams are withdrawing from the EU market, concentrating supply among larger chemical portfolios.
Buyer consolidation among top-20 pharmaceutical companies is compressing supplier qualification cycles and unbundling after-sales technical support from reagent pricing. Procurement teams now negotiate multi-year framework agreements covering plasmid, cell line, and media categories simultaneously. This pattern is most pronounced in the United States, where three large biopharma buyers account for over 40% of high-value transient expression contracts.
Transient Protein Expression Market Segmentation
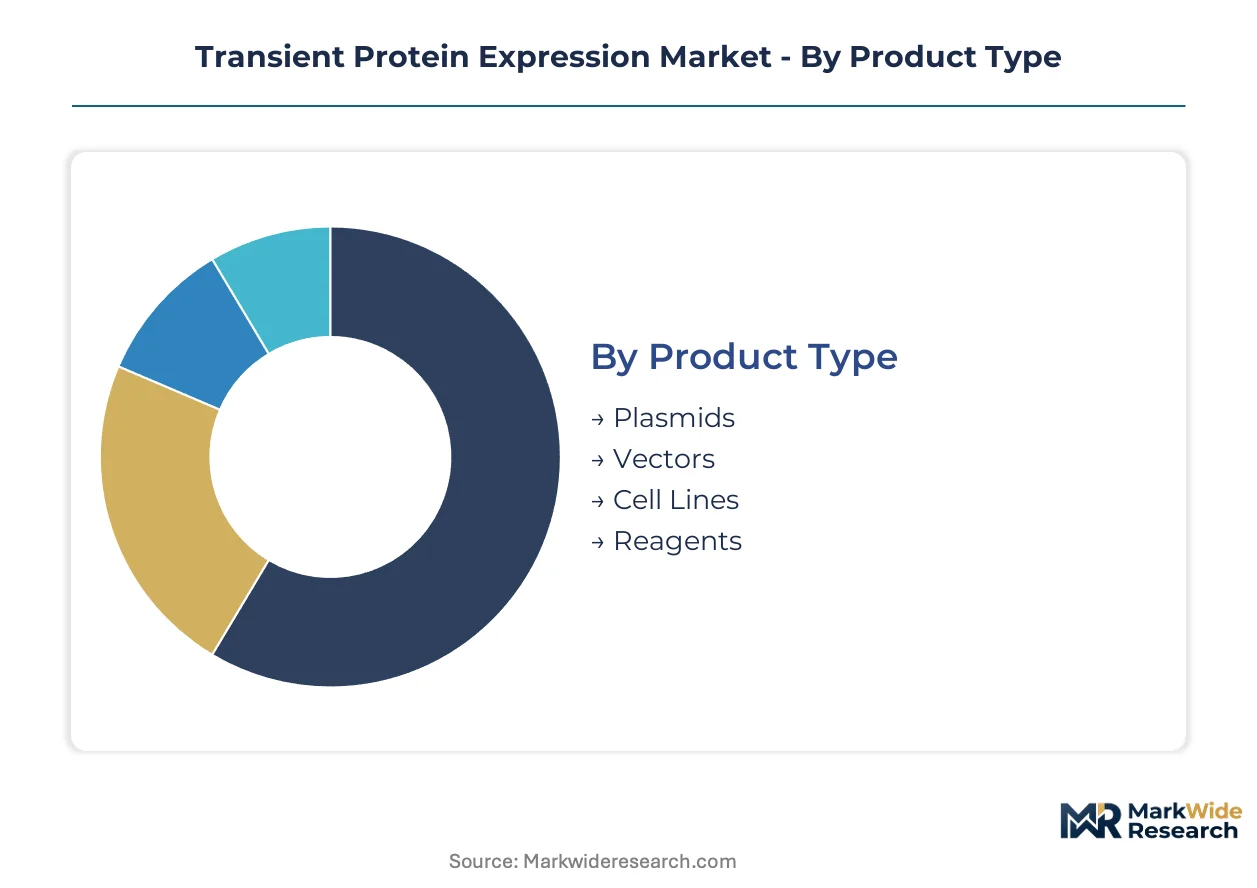
Segmentation in transient protein expression reveals how substitution pressures reshape purchasing patterns across product tiers. Buyers weigh speed against validation depth when selecting between consumables, instruments, and services.
Product Type:
Plasmids and vectors face intensifying substitution pressure from synthetic DNA providers and gene synthesis services that bypass traditional cloning workflows entirely.
- Plasmids:Circular DNA vectors engineered for high-copy replication in bacterial hosts before mammalian transfection. Demand concentrates among contract manufacturers in the United States serving FDA-tracked antibody programs, constrained by fermentation capacity bottlenecks at GMP-grade suppliers.
- Vectors:Viral and non-viral delivery systems optimized for specific cell types and expression durations. Academic core facilities in Germany and Switzerland are expanding purchases of inducible vector systems to meet EMA containment protocol requirements for genetically modified organism handling.
- Cell Lines:Suspension-adapted HEK293 and CHO derivatives with documented lineage traceability.
- Reagents:Transfection chemicals, media supplements, and cryopreservation solutions.
Reagents anchor the volume base while plasmids gain share at the steepest rate as clinical programs demand higher documentation grades.
Technology:
Cost tier differentiation separates capital-intensive electroporation platforms from reagent-heavy chemical transfection methods favored by budget-constrained academic users.
- Transfection:Lipid and polymer-based chemical delivery methods scalable from multiwell plates to bioreactors. Pharmaceutical firms in Japan favor cationic lipid formulations for rapid antibody screening where METI guidelines emphasize process reproducibility documentation.
- Electroporation:Electrical pulse-mediated membrane permeabilization achieving high efficiency in hard-to-transfect cells. Clinical-scale manufacturers in Switzerland and the United States deploy closed-system electroporation to satisfy FDA and Swissmedic requirements for host cell protein impurity control.
- Viral Transduction:Lentiviral and adenoviral vectors for stable or extended expression applications.
- Microinjection:Direct physical delivery into individual cells for specialized research applications.
Transfection dominates transaction volume while electroporation expands most quickly in regulated manufacturing settings.
End User:
Customer type determines whether procurement prioritizes speed and flexibility or validation depth and audit readiness.
- Biotechnology Companies:Venture-funded drug developers requiring gram-scale protein batches within compressed timelines. Clusters in Boston and San Diego generate concentrated demand for integrated transient-to-stable expression handoffs from specialized contract research organizations.
- Pharmaceutical Firms:Large-cap developers with established quality systems and multi-year framework agreements. Procurement teams negotiate bundled contracts covering plasmid, cell line, and media categories simultaneously, compressing supplier qualification cycles.
- Academic Institutions:University core facilities with flexible budgets and publication-driven timelines.
- Research Organizations:Government and nonprofit laboratories with standardized purchasing protocols.
Pharmaceutical firms anchor the revenue base while biotechnology companies drive platform innovation adoption.
Application:
Application maturity varies from established research workflows to emerging therapeutic manufacturing where regulatory burden reshapes supplier selection.
- Drug Development:Target validation, lead optimization, and pharmacokinetic studies requiring rapid protein supply. Screening programs in the United States pull demand toward HEK293 suspension systems capable of two-week turnaround for antibody candidate batches.
- Vaccine Production:Antigen expression for preclinical immunogenicity assessment and early-phase clinical material. India's CDSCO-aligned facilities are expanding transient platform investments to serve export-oriented supply under production-linked incentive schemes.
- Therapeutic Protein Production:Clinical-grade biologics manufacturing with full GMP documentation.
- Research Studies:Fundamental biology and tool antibody generation with minimal regulatory overhead.
Research studies anchor the installed base while therapeutic protein production climbs the fastest as regulatory pathways mature for non-integrated expression methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature biopharma clusters demanding validated transient systems and emerging manufacturing hubs prioritizing cost-efficient scale-up capacity. The United States concentrates high-value contract research demand, while Switzerland and Germany anchor European regulatory compliance investment. India's production-linked incentive schemes are redirecting export-oriented antibody supply chains toward South Asian manufacturing bases.
United States
Boston and San Diego biotech clusters generate dense demand for integrated transient-to-stable expression handoffs from specialized contract research organizations. FDA guidelines on host cell protein impurities compress validation timelines for clinical-grade batches. Pharmaceutical procurement teams in New Jersey and Massachusetts negotiate multi-year framework agreements covering plasmid, cell line, and media categories simultaneously.
Germany
Academic core facilities in Heidelberg and Munich expand purchases of inducible vector systems to meet EMA containment protocol requirements for genetically modified organism handling. REACH chemical registration requirements for novel transfection reagents extend commercialization timelines by 18-24 months. The country's national pharmaceutical regulator enforces strict documentation burdens for non-integrated expression methods used in pre-clinical transitions.
Switzerland
Clinical-scale manufacturers in Basel deploy closed-system electroporation to satisfy Swissmedic requirements for host cell protein impurity control. The country's pharmaceutical regulator aligns with FDA standards on cell-derived biologics, pushing developers toward validated transient platforms. Zurich-based contract development organizations specialize in rapid antibody screening programs requiring gram-scale protein batches within compressed timelines.
India
CDSCO regulatory alignment with ICH guidelines attracts transient platform investments for export-oriented antibody supply under government production-linked incentive schemes. Hyderabad and Bengaluru biologics manufacturing clusters expand GMP-adjacent facility capacity to serve European and North American pharmaceutical firms. The country's central drug regulator tightens oversight of cell-derived starting materials used in clinical manufacturing.
Japan
Pharmaceutical firms favor cationic lipid formulations for rapid antibody screening where METI guidelines emphasize process reproducibility documentation. Tokyo and Osaka biotech clusters concentrate demand for high-throughput HEK293 suspension systems capable of two-week turnaround. The country's national pharmaceutical regulator enforces documentation standards that compress supplier qualification cycles for multi-year framework agreements.
Transient Protein Expression Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in transient protein expression. Thermo Fisher Scientific leverages end-to-end workflow portfolios to dominate instrument-reagent bundles, while Merck KGaA anchors position through deep expertise in cell line engineering and transfection-grade media. Lonza competes via specialized contract development services that integrate transient expression into larger biomanufacturing pipelines. Strategic moves concentrate on M&A for fermentation capacity and technology licensing for electroporation platforms.
Within the integrated platform tier, Thermo Fisher Scientific, Merck KGaA, and Lonza represent divergent competitive archetypes. The Massachusetts-based corporation exemplifies instrument-reagent bundling power through workflow portfolio breadth. The German entity occupies a position anchored in cell line engineering heritage and transfection-grade media specialization. The Swiss organization sits within the contract development vector, manufacturing integration services that bridge transient screening into stable production pipelines.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Lonza |
| Promega Corporation |
| QIAGEN |
| Bio-Rad Laboratories |
| Takara Bio |
| Agilent Technologies |
| GenScript Biotech Corporation |
| Others |
Value Network & Pricing Analysis
Ninety-day fermentation lead times for GMP-grade plasmid DNA concentrate pricing power among fewer than ten specialized suppliers globally, while downstream contract manufacturers absorb cost volatility through multi-year framework agreements that bundle reagent, cell line, and media categories.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical procurement, with procurement teams in New Jersey and Massachusetts negotiating multi-year framework agreements covering plasmid, cell line, and media categories simultaneously. Price differentiation separates ISO 13485-certified reagent vendors from uncertified suppliers serving diagnostic instrument manufacturers. Cost compression in standard-grade reagents is intensifying because generic alternatives proliferate from Asian chemical portfolios. Academic core facilities exhibit highest price sensitivity, while clinical-scale manufacturers prioritize validation depth over unit cost.
Supply Chain Analysis
The United States and Switzerland anchor GMP-grade plasmid fermentation capacity, while India and Germany concentrate transfection-grade media production. The supply chain draws from bacterial fermentation hosts, mammalian cell substrates, and polymer-based transfection chemistries. Single-source vulnerability concentrates at GMP plasmid suppliers, where fewer than ten facilities serve global clinical demand. Distribution runs through direct sales forces for pharmaceutical accounts and distributor networks for academic and smaller biotechnology customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform standardization pressure from the FDA and EMA fragments supplier tiers, creating niches for documented quality providers as procurement teams unbundle after-sales technical support from reagent pricing.
For Market Incumbents: Secure fermentation capacity additions in India and Switzerland to offset plasmid DNA supply volatility, while investing in ISO 13485 certification gaps that fewer than fifteen percent of reagent vendors currently hold. Threat from synthetic DNA providers intensifies substitution pressure on traditional plasmid workflows. Channel control through integrated instrument-reagent bundling anchors margin defense. For New Entrants and Emerging Players: Lead with cell-free expression convergence workflows targeting toxic protein categories that fail in living cells, where hybrid extract-based systems face limited incumbent specialization. India's CDSCO-aligned biologics manufacturing expansion offers the most penetrable geography under government production-linked incentive schemes. Go-to-market through contract development partnerships with export-oriented antibody suppliers in Hyderabad and Bengaluru bypasses direct incumbent confrontation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates with underoptimized transient expression divisions lacking dedicated regulatory affairs teams for REACH compliance. Long-term viability centers on platform-owning positions with captive fermentation capacity and electroporation technology licensing. Signal to monitor: withdrawal of small-molecule reagent suppliers from EU markets as REACH registration timelines extend commercialization by eighteen to twenty-four months.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | GMP-grade plasmid supply constraints concentrate among under ten global suppliers, creating acquisition premiums for qualified assets. |
| ISO 13485 Certification Investment | Diagnostic instrument manufacturers face documented supply shortages as fewer than fifteen percent of reagent vendors hold full medical device quality certification. |
| Electroporation Platform Licensing | Closed-system electroporation satisfies FDA and Swissmedic host cell protein impurity requirements for clinical-scale manufacturing. |
| Cell-Free Expression Capability Buildout | Hybrid workflows address toxic protein categories that fail in living cells, opening white space beyond incumbent mammalian platforms. |
| India Manufacturing Footprint Establishment | CDSCO regulatory alignment with ICH guidelines attracts export-oriented antibody supply under production-linked incentive schemes. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, contract manufacturing procurement managers, and academic core facility directors; and secondary validation through FDA filings, EMA submissions, CDSCO regulatory circulars, and ISO certification databases. Bottom-up segment sizing triangulated against top-down market boundary checks from trade flow analysis and reagent import records.
Across the projection horizon, the analytical framework modeled value and volume through product type, technology, end user, application, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate blending anchored in plasmid fermentation capacity expansion trajectories and electroporation platform adoption curves in clinical manufacturing settings.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO regimes; material policy shifts on host cell protein impurities or genetically modified organism containment would require re-modeling. Recalibration cycles align with material shifts in plasmid supply concentration, electroporation technology licensing activity, and REACH enforcement patterns affecting reagent commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Biology
Asia-Pacific Gene Synthesis Market
Synthetic Biology
Global Cell-Free Protein Expression Market
Synthetic Biology
Synthetic Stem Cells Market
Synthetic Biology
Synthetic Hormones Market
Synthetic Biology
DNA Synthesizer Market
Synthetic Biology
Difficult-To-Express Proteins Market
Synthetic Biology
Gene Synthesis (Research Use) Market
Synthetic Biology
Synthetic Genomics Market
Synthetic Biology
Mutation Generation Systems Market