
 Hong Kong Used Car Market | 2026-2036
Hong Kong Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Used Car Market Insights
The Hong Kong used car landscape is consolidating around a sharp divergence between premium near-new inventory and aging commodity stock. Tan Chong International leverages its established dealer network to dominate the premium tier, while China Meidong Auto Holdings LIMITED anchors its position through specialized refurbishment capabilities. BYD Auto competes aggressively in the electric pre-owned segment as battery technology leadership reshapes buyer preferences.
A used car constitutes a previously registered motor vehicle transferred through resale rather than first retail sale, typically evaluated by odometer reading, service history, and structural integrity against Transport Department roadworthiness protocols. Its primary commercial purpose centers on providing accessible personal mobility at depreciated cost points below new vehicle taxation brackets. The SUV segment sustains the strongest structural momentum as family buyers prioritize cabin flexibility and elevated driving positions in dense urban environments. Electric and hybrid fuel types are capturing expanding margin pools as charging infrastructure matures and emissions-based registration incentives redirect demand from petrol equivalents.
The Transport Department enforces biennial vehicle examinations under the Road Traffic Ordinance, while the Environmental Protection Department administers progressive emissions standards that filter older diesel and petrol units from registrable inventory. These frameworks compress the economically viable ownership horizon and systematically elevate supply velocity in the 4-7 year age category. Stakeholders must monitor how the territory's phased commercial vehicle electrification mandates propagate into private used car eligibility criteria and resale value calculations.
Market Dynamics
The Hong Kong used car market is compressing vehicle ownership cycles as the Transport Department's biennial inspection regime under the Road Traffic Ordinance systematically filters aging inventory from registrable supply. This regulatory pressure accelerates turnover and concentrates transaction velocity in younger vehicle cohorts.
Growth Catalysts
- Ride-hailing fleet expansion:Platform operators including Uber and local taxi fleets are scaling pre-owned acquisitions to manage capital efficiency and replacement schedules. These buyers prioritize 2-4 year old inventory with verified maintenance records.
- Electric vehicle transition:The Environmental Protection Department's progressive emissions standards and first registration tax incentives for EVs are redirecting demand toward pre-owned battery electric and plug-in hybrid units.
- Biennial inspection enforcement:Transport Department roadworthiness protocols are disqualifying older diesel and petrol vehicles from renewal eligibility, compressing supply and elevating prices for compliant younger stock.
Market Restraints
- Limited land availability:Hong Kong's constrained physical space restricts dealership lot capacity and vehicle storage infrastructure, elevating holding costs and compressing inventory turns.
- Import dependency:The territory relies entirely on external supply chains for replacement parts and diagnostic equipment, exposing margins to currency fluctuation and shipping disruption.
- Battery degradation uncertainty:Pre-owned electric vehicle buyers face information asymmetry regarding battery state-of-health, suppressing price discovery and transaction liquidity in the EV segment.
Strategic Opportunities
- Certified pre-owned programs:Dealer networks can capture margin expansion by implementing battery health certification and extended warranty products for electric and hybrid inventory.
- Cross-border remarketing:Right-hand drive vehicles disqualified from Hong Kong registration retain export value to Southeast Asian markets including Thailand and Malaysia.
- Digital auction platforms:Online wholesale marketplaces are disintermediating traditional dealer-to-dealer transactions and expanding price transparency across the territory.
Industry Challenges
- Technical workforce scarcity:The shortage of technicians qualified in high-voltage battery systems and electric powertrain diagnostics constrains refurbishment capacity and extends turnaround times.
- Compliance documentation burden:The Environmental Protection Department's emissions verification requirements and Transport Department transfer procedures create administrative friction that delays transaction closure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Used Car Market |
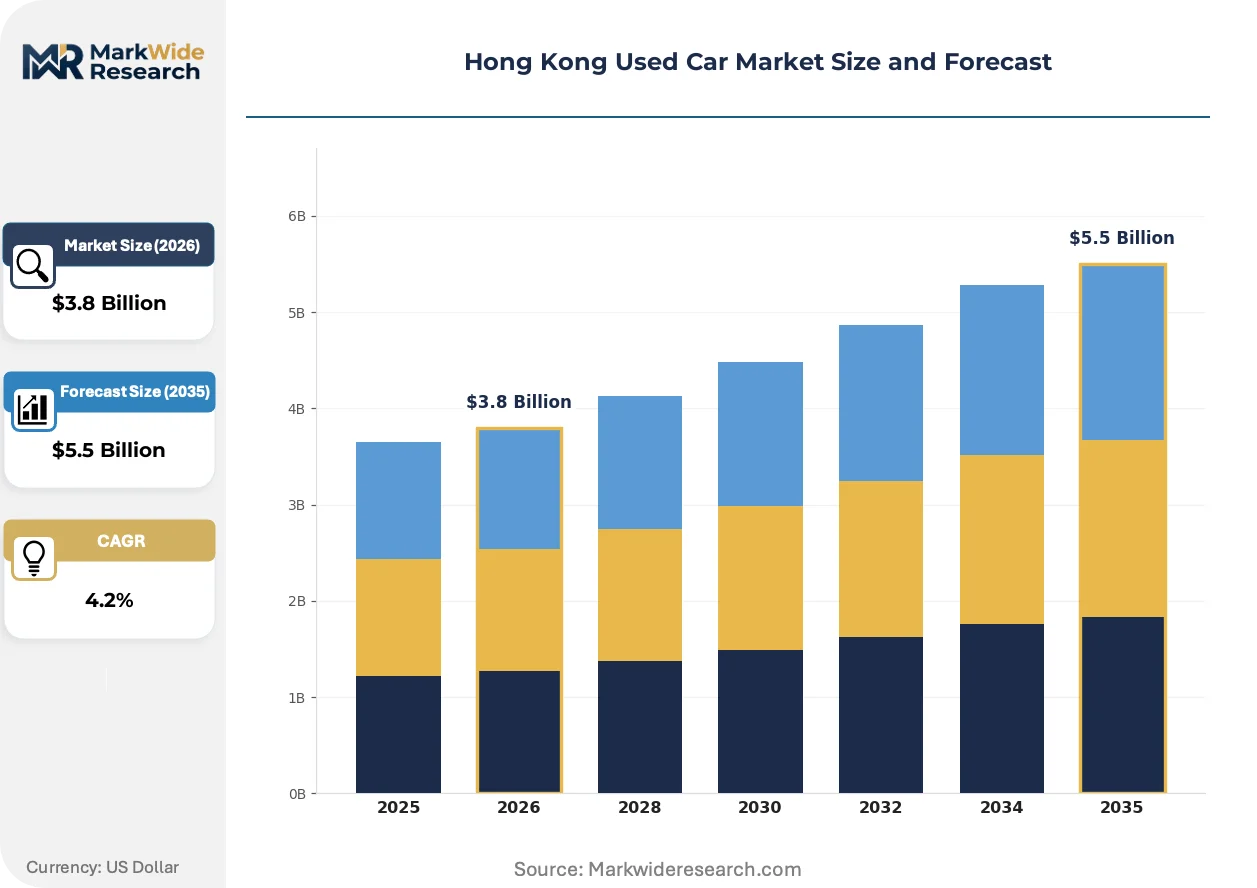
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid Market Channel: Dealer, Online Marketplace, Auction, Private Sale Age Group: 0-3 Years, 4-7 Years, 8-10 Years, 10+ Years |
| Companies Covered | Tan Chong International, China Automobile New Retail (Holdings), Cimc Vehicles (group) CO., LTD. Hongkong, Minth Group LIMITED, China Meidong Auto Holdings LIMITED, New Gonow Recreational Vehicles INC., Nio Nextev LIMITED, Pagani China Automotive LIMITED, BYD Auto, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Used Car Market Trends and Innovations
Digital infrastructure and electrification are restructuring how vehicles change hands in Hong Kong. Transaction platforms, diagnostic technologies, and regulatory compliance systems are evolving in parallel.
Vehicle telemetry systems are converging with blockchain-based provenance verification to create immutable service history records. Fleet operators and premium buyers are adopting these tools to reduce information asymmetry in high-value transactions. This technology convergence is compressing due diligence timelines and elevating trust premiums for documented inventory.
The Environmental Protection Department's tightening emissions standards under the Air Pollution Control Ordinance are systematically excluding pre-Euro 5 diesel vehicles from registration eligibility. This regulatory compression is accelerating scrappage of commercial vehicle stock and redirecting supply-side investment toward electric and hybrid refurbishment capabilities. Dealers are responding by reallocating floor space and technician training budgets.
Subscription and short-term lease models are fragmenting traditional ownership patterns among younger urban consumers. Digital-native platforms are displacing conventional dealership relationships for initial vehicle access, with physical showrooms retaining relevance only for final inspection and handover. This channel shift is most visible in Kowloon and Hong Kong Island districts where parking costs and congestion charges suppress long-term ownership economics.
Hong Kong Used Car Market Segmentation
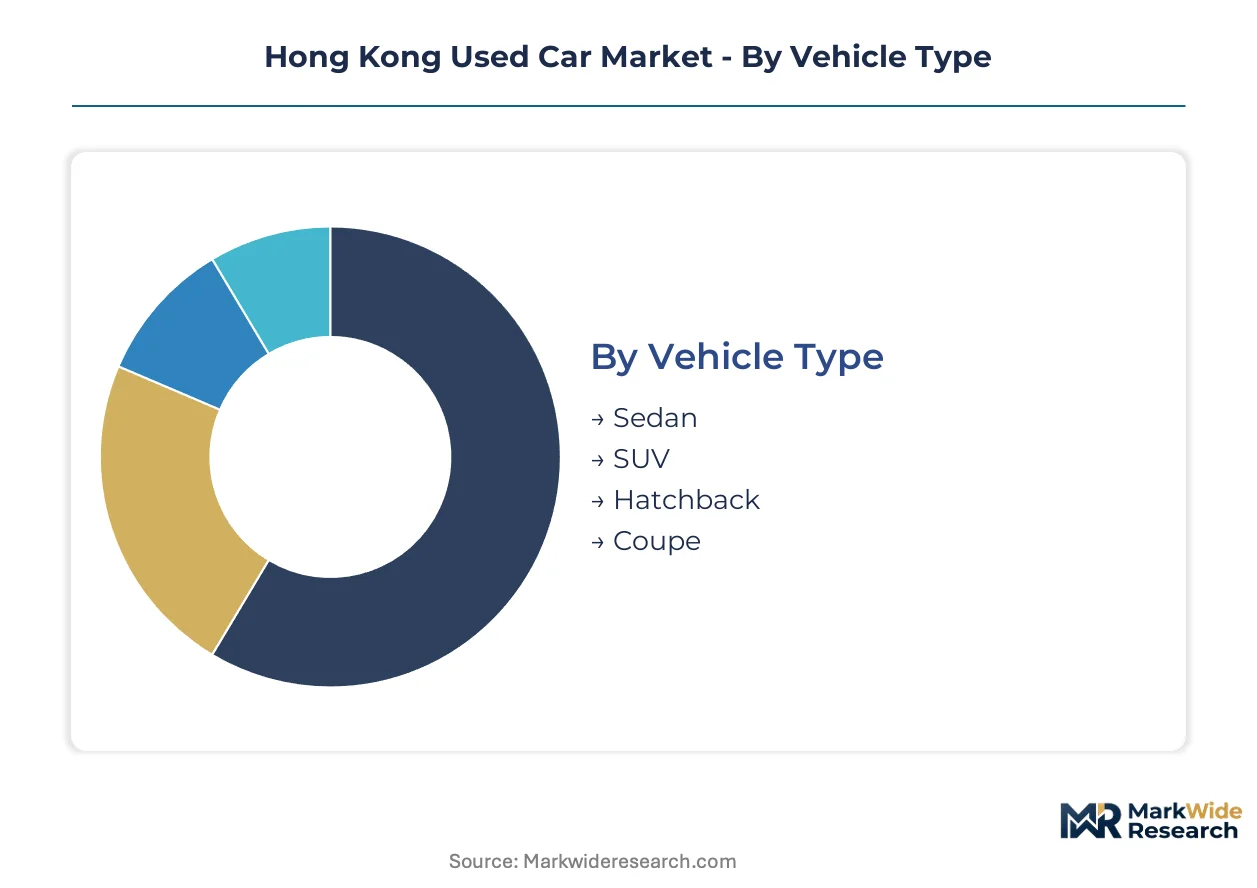
Hong Kong's used car market fragments across four structural dimensions that determine transaction economics and regulatory compliance. Each segmentation axis carries distinct Transport Department certification burdens and resale value implications.
Vehicle Type:
Transport Department roadworthiness protocols apply differential inspection intensity based on vehicle architecture and passenger capacity classifications.
- SUV:Elevated ride height and flexible cabin configurations attract family buyers in dense urban districts. Demand concentrates in Kowloon and Hong Kong Island residential zones where parking constraints favor single-vehicle solutions. The segment commands residual value premiums due to import scarcity and alignment with ride-hailing fleet specifications.
- Sedan:Three-box configurations dominate corporate fleet turnover and executive personal use. Transaction velocity runs highest in Central and Wan Chai commercial corridors where parking costs suppress larger vehicle ownership. Biennial inspection compliance rates exceed other categories due to professional maintenance patterns.
- Hatchback:Compact footprints suit first-time buyers and island-district commuters. Urban parking efficiency drives preference in Aberdeen and Ap Lei Chau neighborhoods with constrained street capacity.
- Coupe:Two-door sport configurations occupy a narrow prestige tier with limited supply and extended holding periods. Collector interest sustains liquidity despite restricted practicality.
SUV sits at the top of the volume ranking, with Hatchback climbing the fastest among younger buyer cohorts.
Fuel Type:
Environmental Protection Department emissions tiers and first registration tax differentials create sharp valuation spreads across propulsion technologies.
- Electric:Battery electric vehicles face battery state-of-health verification requirements under emerging Transport Department guidelines. Demand clusters among technology adopters in Mid-Levels and Cyberport districts with reliable charging access. Information asymmetry around degradation curves suppresses price discovery relative to petrol equivalents.
- Hybrid:Dual-powertrain units bridge regulatory incentives and range security concerns. Fleet operators prioritize Toyota and Honda systems with proven durability records and established service networks.
- Petrol:Internal combustion engines face progressive exclusion from low-emission zones under Air Pollution Control Ordinance amendments. Transaction liquidity concentrates in Euro 5 and newer compliance tiers.
- Diesel:Compression-ignition units encounter registration restrictions that compress supply and redirect inventory toward export markets. Commercial vehicle electrification mandates accelerate obsolescence timelines.
Petrol retains volume leadership, though Electric is expanding most quickly as charging infrastructure matures.
Market Channel:
Transaction venue determines documentation burden, warranty transferability, and buyer recourse mechanisms under Hong Kong consumer protection frameworks.
- Dealer:Licensed premises provide statutory warranty coverage and Transport Department transfer facilitation. Franchise networks concentrate in Kowloon Bay and Wong Chuk Hang industrial zones with dedicated inspection facilities.
- Online Marketplace:Digital platforms reduce search friction and expand price transparency. Younger demographics in Sha Tin and Tseung Kwan O new towns favor app-based discovery and remote negotiation.
- Auction:Wholesale channels serve fleet disposals and lease returns with volume efficiency. Professional buyers dominate participation due to limited consumer protection provisions.
- Private Sale:Direct transfers minimize intermediary margins but shift compliance documentation burden to individual parties. Legal complexity constrains participation among inexperienced sellers.
Dealer channels anchor transaction volume, while Online Marketplace gains share fastest among digital-native demographics.
Age Group:
Biennial inspection cycles under Road Traffic Ordinance create discrete value depreciation cliffs at compliance threshold years.
- 0-3 Years:Near-new inventory carries manufacturer warranty remainder and minimal mechanical risk. Premium pricing reflects first-registration tax avoidance and immediate availability. Ride-hailing fleets target this bracket for capital efficiency.
- 4-7 Years:First major inspection interval compresses supply as non-compliant units exit registrable stock. Price discovery becomes volatile around Transport Department failure rates.
- 8-10 Years:Second inspection cycle and rising maintenance costs accelerate depreciation. Export viability to right-hand drive Southeast Asian markets sustains residual floor values.
- 10+ Years:Classic registration eligibility and parts scarcity define a thin collectible tier. Scrappage incentives redirect most volume toward recycling streams.
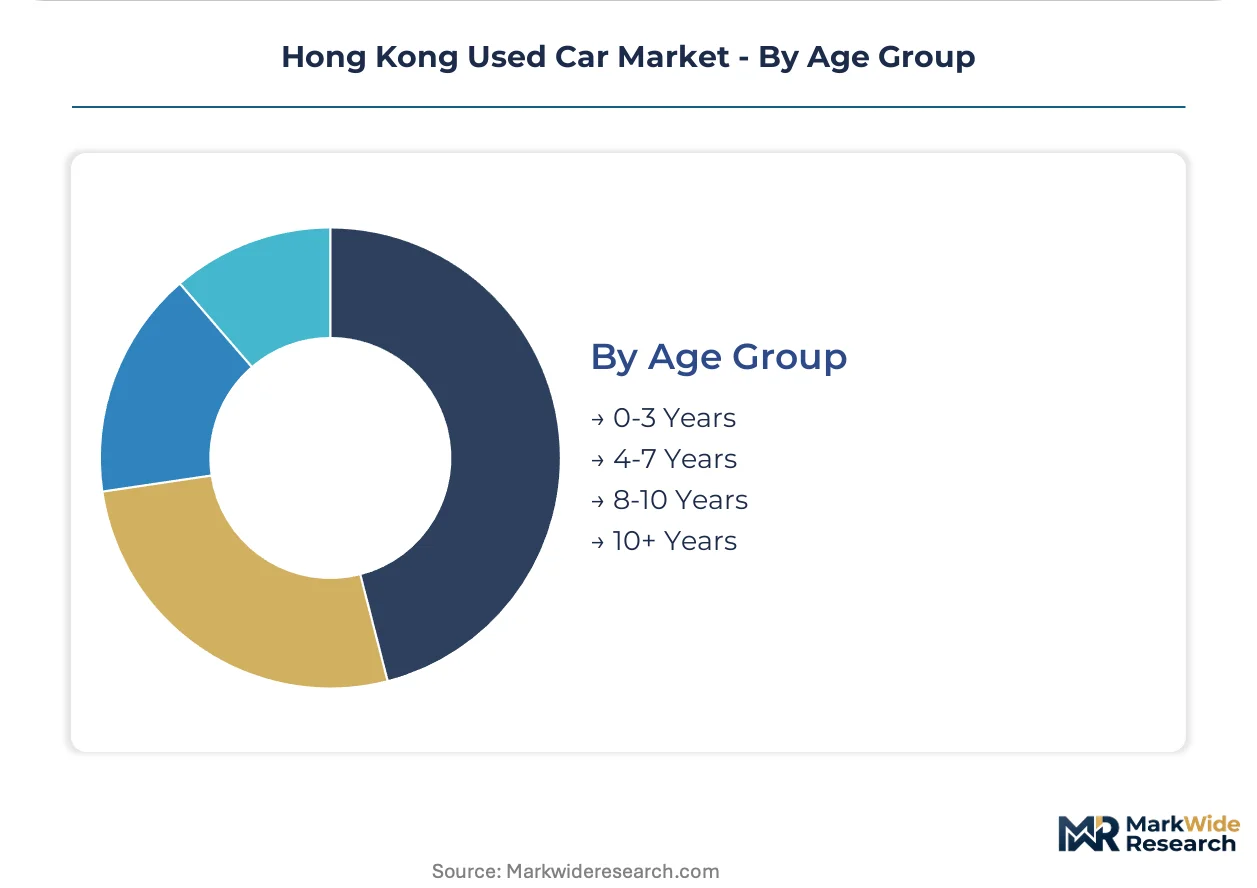
0-3 Years commands the steepest expansion trajectory, with 4-7 Years representing the largest transaction flow by unit count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled automotive technicians and certified vehicle inspectors concentrate in Hong Kong Island and Kowloon districts, anchoring the territory's vehicle refurbishment and compliance verification capacity.
Hong Kong Island
Corporate fleet operators and executive buyers drive demand for premium sedans and electric vehicles in Central and Wan Chai commercial corridors. The Transport Department's vehicle examination centers in Causeway Bay and Ap Lei Chau enforce biennial roadworthiness protocols that accelerate turnover in the 4-7 year age bracket. Wong Chuk Hang industrial zone hosts concentrated dealer inspection facilities serving the territory's southern districts.
Kowloon
Ride-hailing fleet operators scale pre-owned acquisitions in Kowloon Bay and Mong Kok districts to optimize capital deployment across vehicle replacement cycles. Environmental Protection Department emissions verification requirements filter older diesel units from registrable inventory in this high-traffic corridor. Kowloon Bay industrial precinct accommodates the territory's largest concentration of licensed dealership premises with dedicated workshop capacity.
New Territories
Family buyers in Sha Tin and Tseung Kwan O new towns prioritize SUVs and hatchbacks suited to suburban commuting patterns and parking constraints. The Transport Department's vehicle licensing offices in Sha Tin process transfer documentation for cross-district transactions. Yuen Long and Tuen Mun districts serve as staging points for right-hand drive vehicle exports to Southeast Asian markets.
Lantau Island
Tourism and airport-related fleet operators sustain demand for commercial vehicle replacements near Hong Kong International Airport. The Environmental Protection Department's progressive emissions standards redirect investment toward electric commercial vehicle refurbishment in this logistics corridor. Tung Chung new town development expands residential buyer pools for compact vehicle categories.
Hong Kong Used Car Market Competitive Landscape
Capital-heavy dealer networks compete with asset-light digital platforms for transaction flow and customer relationships. Market structure fragments across franchise dealership groups, independent refurbishment specialists, and emerging online marketplaces. Three archetypes dominate: established multi-brand dealer networks, electric vehicle-focused specialists, and cross-border remarketing operators. Competitive moves concentrate on certified pre-owned program development and battery health verification capabilities.
Within the established dealer tier, Tan Chong International occupies a position representing premium network coverage, while China Meidong Auto Holdings LIMITED exemplifies specialized refurbishment concentration. BYD Auto anchors the electric vehicle specialist archetype as battery technology leadership reshapes buyer preferences in the territory.
| Leading Market Players |
|---|
| Tan Chong International |
| China Automobile New Retail (Holdings) |
| Cimc Vehicles (group) CO., LTD. Hongkong |
| Minth Group LIMITED |
| China Meidong Auto Holdings LIMITED |
| New Gonow Recreational Vehicles INC. |
| Nio Nextev LIMITED |
| Pagani China Automotive LIMITED |
| BYD Auto |
| Others |
Pricing and Supply Chain Analysis
Horizontal integration among Kowloon Bay dealer networks anchors both inventory sourcing power and pricing discipline across the territory's used car channels. This consolidation pattern concentrates procurement leverage against Japanese and Korean OEM parts suppliers while enabling bundled service premiums that independent operators cannot match.
Pricing Analysis
Bundled certification-warranty packages separate franchised dealer pricing from unbundled private sale transactions. Three-tier pricing structure across certified pre-owned, standard dealer, and private sale levels reflects Transport Department inspection grade and battery health verification status. Cost compression in the 4-7 year age bracket intensifies because biennial roadworthiness failures redirect supply toward export markets. Fleet buyers exhibit lowest price sensitivity due to capital efficiency priorities, while first-time owner segments in New Territories new towns drive hardest bargain pressure.
Supply Chain Analysis
Replacement parts supply rests on Japanese precision component producers, Korean OEM distribution networks, and mainland Chinese aftermarket manufacturers. Critical inputs include high-voltage battery diagnostics equipment, emission testing hardware, and right-hand drive steering assemblies. Single-source vulnerability concentrates in proprietary electric powertrain components where BYD and Tesla control service tool access. Distribution runs through Kowloon Bay wholesale hubs to island district retail premises, with cross-border logistics feeding Yuen Long export staging points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Hong Kong's used car market rests on certified pre-owned program penetration and battery health verification premiums that extract value from information asymmetry reduction.
For Market Incumbents: Acquire high-voltage diagnostic capability and certified technician training capacity to defend against electric vehicle specialist entrants. Integrate backward into proprietary battery refurbishment operations in Wong Chuk Hang industrial zones to capture margin pools currently flowing to third-party service providers. Lock exclusive parts distribution agreements with Korean and Japanese OEMs to constrain independent dealer access. For New Entrants and Emerging Players: Begin with digital auction platform development targeting fleet disposal volumes in Kowloon Bay and Mong Kok districts where incumbent dealer networks lack price transparency tools. Penetrate the 8-10 year export-ready segment where cross-border remarketing to Thailand and Malaysia remains underdeveloped. Deploy mobile inspection units to reduce customer acquisition friction in New Territories suburban markets. For Investors and Strategic Acquirers: Consolidation pressure builds where family-owned dealer premises face succession gaps and regulatory compliance cost escalation. Five-to-ten year viability favors operators with captive battery certification capabilities and Transport Department examination center relationships. Watch electric vehicle registration incentive modifications as the inflection signal for pre-owned EV liquidity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Health Certification Program | Transport Department guidelines on state-of-health verification create first-mover premium capture opportunity. |
| Cross-Border Remarketing Partnership | Thai and Malaysian right-hand drive demand sustains residual value floors for aged inventory. |
| Mobile Inspection Unit Deployment | Sha Tin and Tseung Kwan O new town coverage reduces customer acquisition cost versus fixed premises. |
| Proprietary Diagnostic Tool Investment | High-voltage system access constraints independent competitors from electric vehicle service revenue. |
| Fleet Disposal Channel Exclusive | Uber and taxi fleet replacement schedules provide predictable volume and reduced holding cost. |
Research Methodology
Multiple input streams — dealer operations executives, Transport Department vehicle examination officers, ride-hailing fleet procurement managers, and cross-border logistics operators — were reconciled against secondary validation. Primary fieldwork encompassed Kowloon Bay wholesale hub observation, Causeway Bay inspection center process mapping, and Yuen Long export staging facility assessment. Secondary sources included Transport Department vehicle registration databases, Environmental Protection Department emissions compliance records, and customs export documentation for right-hand drive vehicle flows. Bottom-up transaction volume modeling and top-down macroeconomic anchoring were cross-checked for consistency.
Data-stream reconciliation across vehicle age cohort flows, fuel type transition rates, and channel migration patterns informed the analytical framework over the projection horizon. Segmentation dimensions modeled encompass vehicle architecture, propulsion technology, transaction venue, and compliance age bracket alongside district-level demand clustering. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporated biennial inspection failure rate projections and electric vehicle incentive policy evolution.
Caveats apply where Transport Department inspection protocol amendments or Environmental Protection Department emissions tier adjustments could materially shift the outlook. Forecasts reflect assumptions regarding charging infrastructure buildout pace and cross-border export market access continuity. A small set of named triggers — battery degradation liability rulings, commercial vehicle electrification mandate propagation, and mainland China import policy shifts — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
Norway Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
Italy Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
North America Used Car Market
Used Vehicles
Used Cars in Russia Market
Used Vehicles
Switzerland Used Car Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Oman Used Car Market
Used Vehicles
Belgium Used Car Market
Used Vehicles
UAE Used Cars Industry Market
Used Vehicles
Netherlands Used Car Market
Used Vehicles
Sri Lanka Used Car Market
Used Vehicles
Middle East and Africa Used Car Market