
 Saudi Arabia Used Car Market | 2026-2036
Saudi Arabia Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Used Car Market Outlook
Automotive technician certification shortfalls is reorganizing how dealers scale reconditioning operations across the kingdom. Abdul Latif Jameel Motors leverages its multi-brand service network to control reconditioning quality at volume. Al-Futtaim Automotive anchors its AutoTrust certified pre-owned program on standardized 120-point inspections. Syarah competes through digital-first inventory aggregation, reducing physical lot dependence.
A used car is a previously registered motor vehicle transferred through resale channels, typically evaluated by odometer reading, service history, and structural integrity against manufacturer specifications; its commercial purpose centers on mobility provision at depreciated capital outlay versus new vehicle acquisition. SUVs dominate transaction flow in Saudi Arabia given family size norms and terrain requirements, while hybrid engine types represent the fastest-growing sub-category as fuel economy regulations tighten and resale values stabilize. The certified pre-owned condition tier commands margin premiums through warranty-backed assurance, separating organized dealer channels from informal classified transactions.
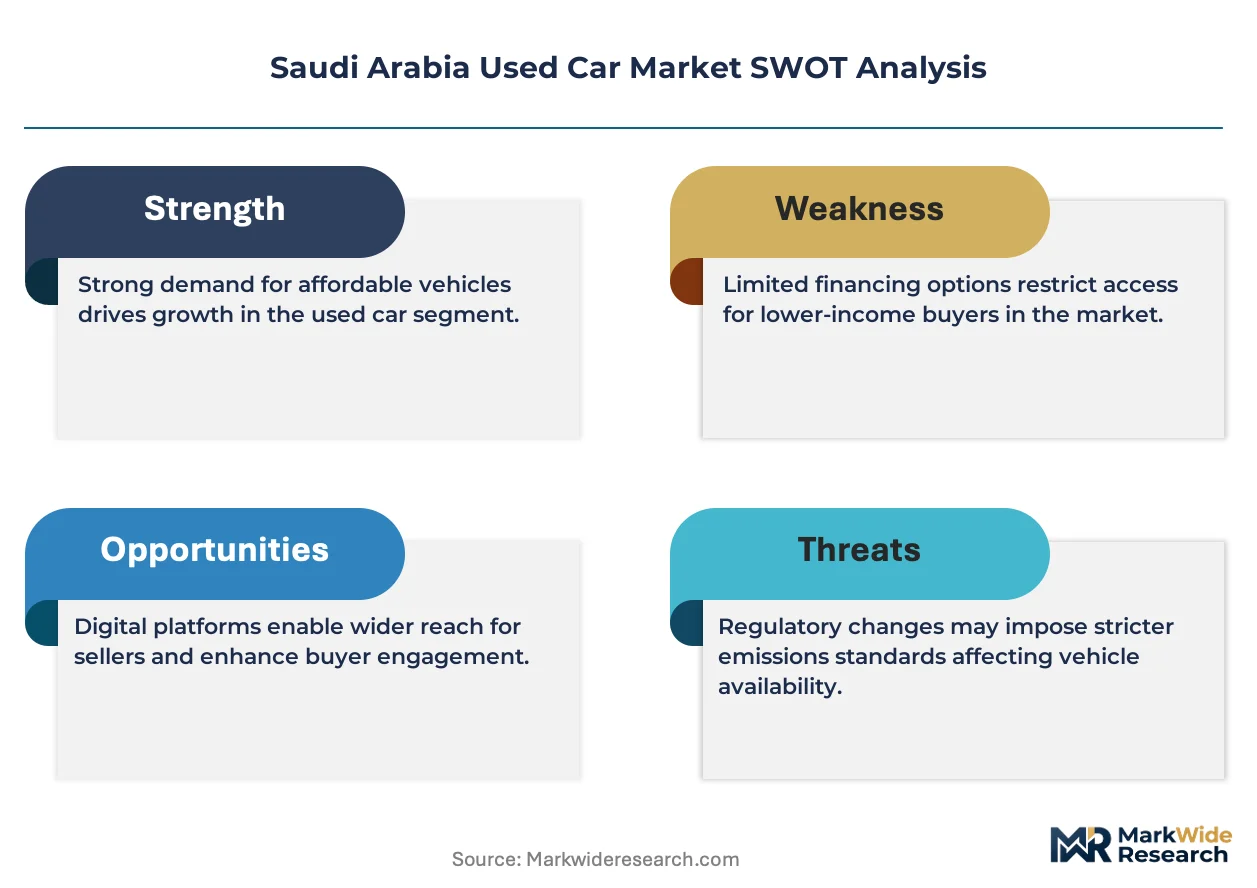
SAMR enforces used vehicle disclosure standards that mandate accident history reporting, while the Saudi Standards, Metrology and Quality Organization specifies mechanical inspection benchmarks for cross-border transfers. MOHAP coordinates with transport authorities on commercial fleet safety compliance, shaping eligibility criteria for ride-hailing vehicle registration. Stakeholders must monitor how Zakat and VAT treatment of used vehicle margins evolves, as fiscal policy recalibration could restructure dealer profitability models and consumer financing access.
Market Dynamics
Fleet operators in Riyadh and Jeddah are accelerating procurement of certified pre-owned units as total cost of ownership pressures intensify. SAMR's tightening quality certification mandates are restructuring dealer reconditioning operations nationwide.
Growth Catalysts
- Fuel economy regulations:Hybrid engine types are gaining transaction share as resale values stabilize under tightening efficiency standards. Family mobility needs sustain SUV demand across the Central Region.
- Riyadh wholesale auction infrastructure:Concentrated physical trading hubs reduce search costs for volume buyers and accelerate inventory velocity for organized dealers.
- SAMR inspection protocols:Mandatory accident history disclosure and mechanical benchmarks are compressing information asymmetry between dealers and retail purchasers.
Market Restraints
- Automotive technician certification shortfalls:Reconditioning quality bottlenecks limit dealer scaling velocity as certified labor pools fail to match procurement expansion.
- Cross-border transfer friction:Saudi Standards, Metrology and Quality Organization mechanical benchmarks create compliance delays for imported used vehicle flows.
- Informal classified channels:Unregulated peer-to-peer transactions without warranty backing erode organized dealer margin premiums through price undercutting.
Strategic Opportunities
- Digital inventory aggregation:Platform-based sourcing reduces physical lot dependence and expands geographic reach beyond Riyadh-Jeddah corridor concentration.
- MOHAP fleet safety coordination:Ride-hailing vehicle registration criteria create certified pre-owned eligibility standards that favor organized supply channels.
- Zakat and VAT policy evolution:Fiscal recalibration on used vehicle margins could restructure dealer profitability models and expand consumer financing access.
Industry Challenges
- 120-point inspection standardization:Dealer investment in certified pre-owned programs requires sustained capital deployment without guaranteed volume absorption.
- Service history verification:Incomplete maintenance documentation from informal prior ownership compresses residual value accuracy and financing eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Used Car Market |
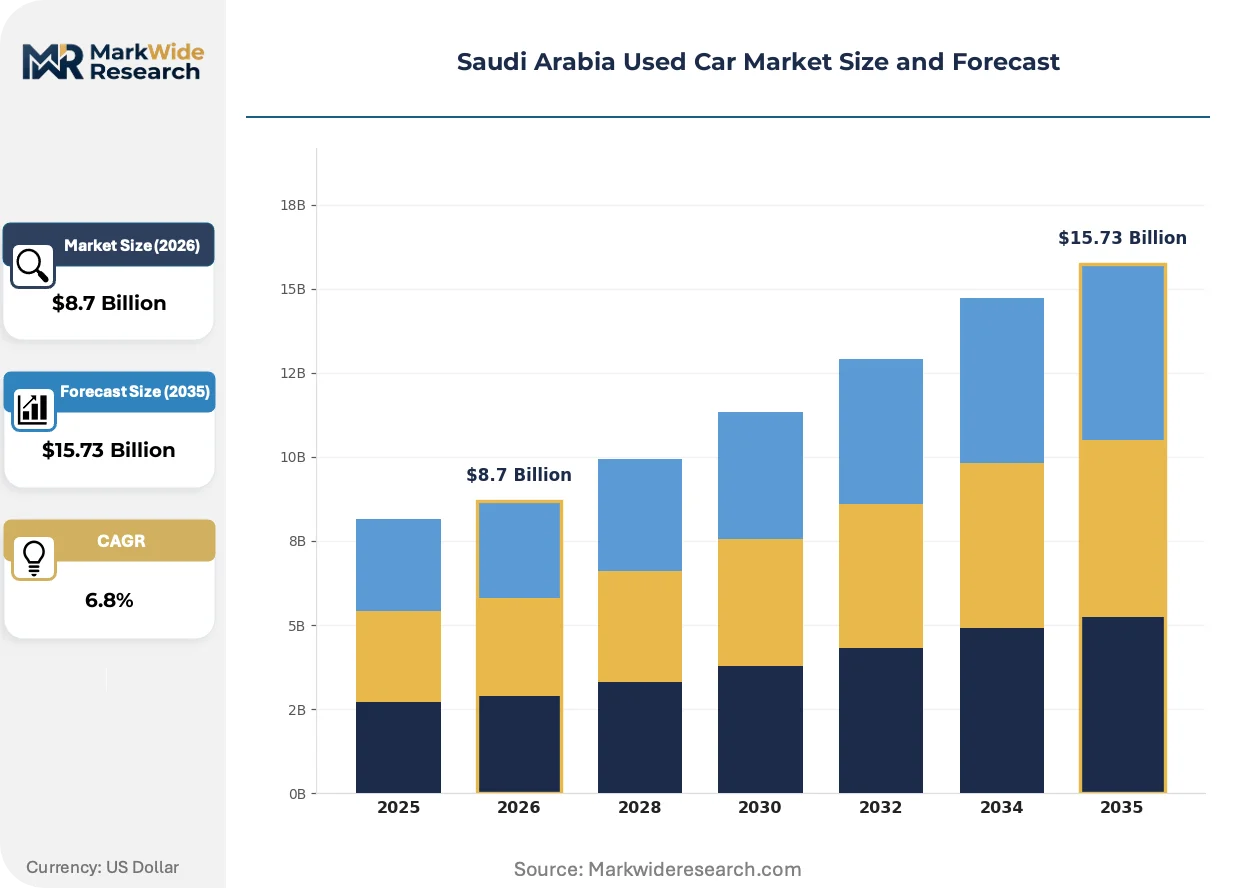
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedans, SUVs, Hatchbacks, Coupes Engine Type: Petrol, Diesel, Hybrid, Electric Usage: Personal, Commercial, Fleet, Ride-Hailing Condition: Certified Pre-Owned, Used, Damaged, Repaired |
| Companies Covered | Al-Nabooda Automobiles, Aljomaih Automotive Company, Abdul Latif Jameel Motors, YallaMotor, Syarah, Al-Futtaim Automotive (AutoTrust), Arabian Auto Agency, Dubizzle Motors, Al-Tayer Motors, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Used Car Market Strategic Shifts
Digital platforms are restructuring how inventory aggregates and prices discover across the kingdom's fragmented supply base. Three developments are compressing traditional dealer intermediation and accelerating transparency.
Artificial intelligence-driven vehicle condition assessment is bifurcating valuation methodologies across the market. Computer vision systems analyze exterior damage and interior wear patterns from smartphone submissions. Fleet operators and digital-first aggregators adopt these tools at scale to reduce physical inspection dependency. The technology is bifurcating dealer competitive position between tech-enabled volume players and inspection-dependent traditional operators.
SAMR disclosure standards mandate accident history reporting and mechanical inspection benchmarks for all registered transfers. The regulation compresses information rents previously captured by dealers with superior documentation access. Certified pre-owned programs anchored on standardized inspections gain relative advantage as regulatory compliance costs rise. Central Region wholesale infrastructure responds fastest given concentration of compliance-capable operators.
Fleet procurement contracts now specify certified pre-owned tiers with warranty-backed assurance rather than informal auction sourcing. Volume buyers in Riyadh and Jeddah consolidate supplier relationships around multi-brand service networks that control reconditioning quality. The Central Region's auction concentration enables this consolidation through proximity to inspection and certification facilities. Family-size SUV preferences sustain transaction flow even as hybrid drivetrains capture incremental share.
Saudi Arabia Used Car Market Segmentation
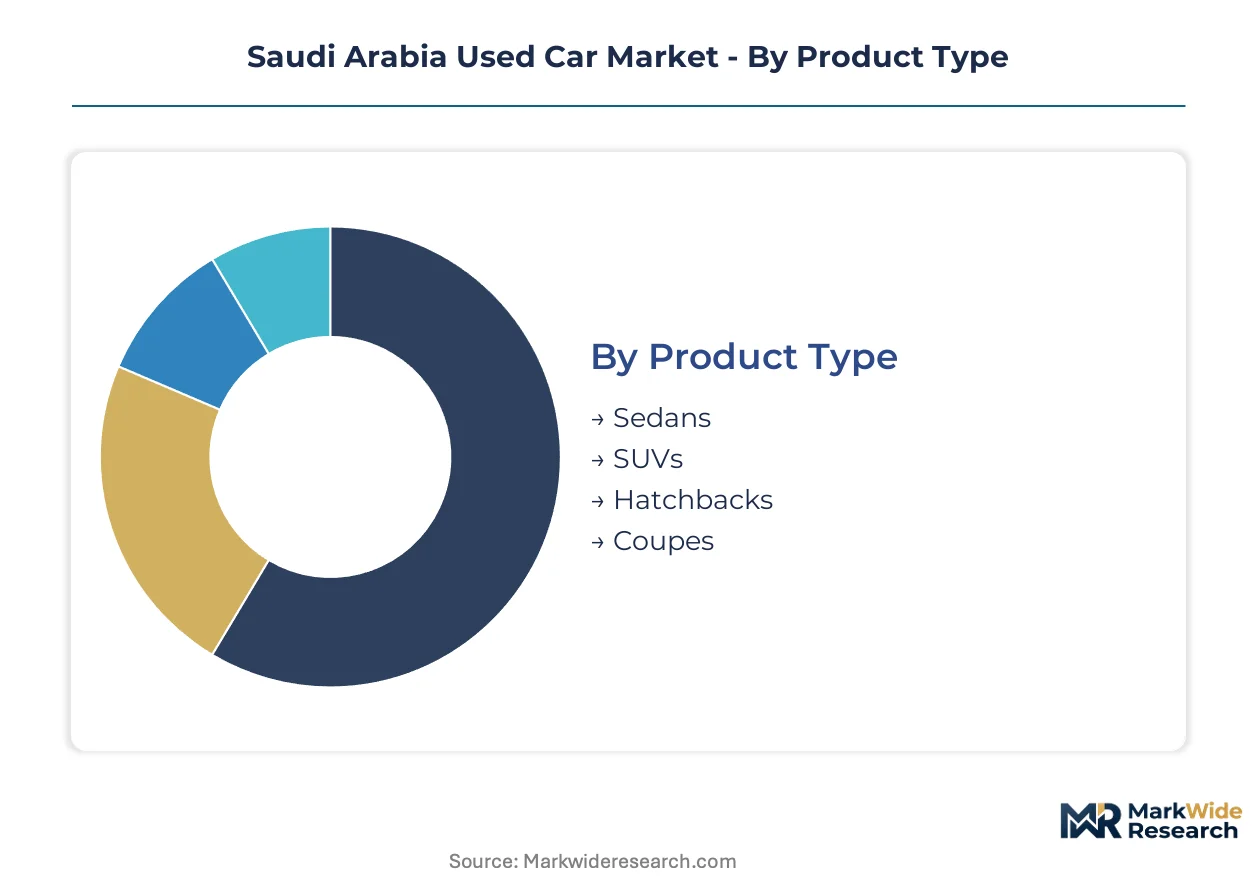
Saudi Arabia's used car market segments along four dimensions that directly shape dealer profitability and inventory strategy. Product type and engine configuration determine reconditioning investment levels, while usage patterns and condition tiers govern pricing power and financing eligibility.
Product Type:
Margin pools concentrate in utility vehicles where family mobility requirements sustain premium pricing through depreciation cycles.
- SUVs:Three-row and full-size sport utility vehicles dominate transaction flow given Saudi family size norms and terrain requirements. Central Region fleet procurement in Riyadh anchors wholesale demand for seven-passenger configurations.
- Sedans:Mid-size sedans retain residual value stability through corporate fleet rotation cycles. Jeddah-based commercial buyers prioritize four-door configurations for executive transport applications.
- Hatchbacks:Compact urban runabouts serve entry-level personal mobility in dense metropolitan cores.
- Coupes:Two-door performance variants attract niche enthusiast demand with compressed volume but elevated per-unit margins.
The dominant share belongs to SUVs, while sedans maintain pricing discipline through fleet channel concentration.
Engine Type:
Powertrain selection now divides the market between regulatory compliance advantages and established infrastructure familiarity.
- Hybrid:Dual-mode petrol-electric systems capture expanding transaction share as SAMR fuel economy benchmarks tighten. Residual value stabilization in Riyadh-Jeddah corridor auctions rewards early dealer inventory positioning.
- Petrol:Internal combustion engines retain volume leadership through service network ubiquity and consumer familiarity with maintenance intervals.
- Diesel:Compression-ignition variants serve commercial hauling applications with torque-dense power delivery.
- Electric:Battery-electric drivetrains remain nascent in secondary channels pending charging infrastructure maturation and battery warranty transferability clarity.
Petrol configurations retain transaction leadership, though hybrid powertrains are climbing the fastest as efficiency regulations harden.
Usage:
Customer procurement patterns separate recurring volume buyers from discretionary one-time purchasers with diverging service expectations.
- Fleet:Multi-unit commercial operators in Riyadh and Jeddah specify certified pre-owned tiers with warranty-backed assurance to control total cost of ownership.
- Commercial:Small business proprietors prioritize payload capacity and durability over cabin amenities for goods transport applications.
- Ride-Hailing:Platform-registered drivers face MOHAP safety compliance criteria that restrict eligibility to inspected and documented vehicles.
- Personal:Individual households trade up through depreciation curves with financing-dependent purchase timing.
Fleet channels anchor organized dealer revenue, while ride-hailing registration requirements are gaining share fastest as platform economics mature.
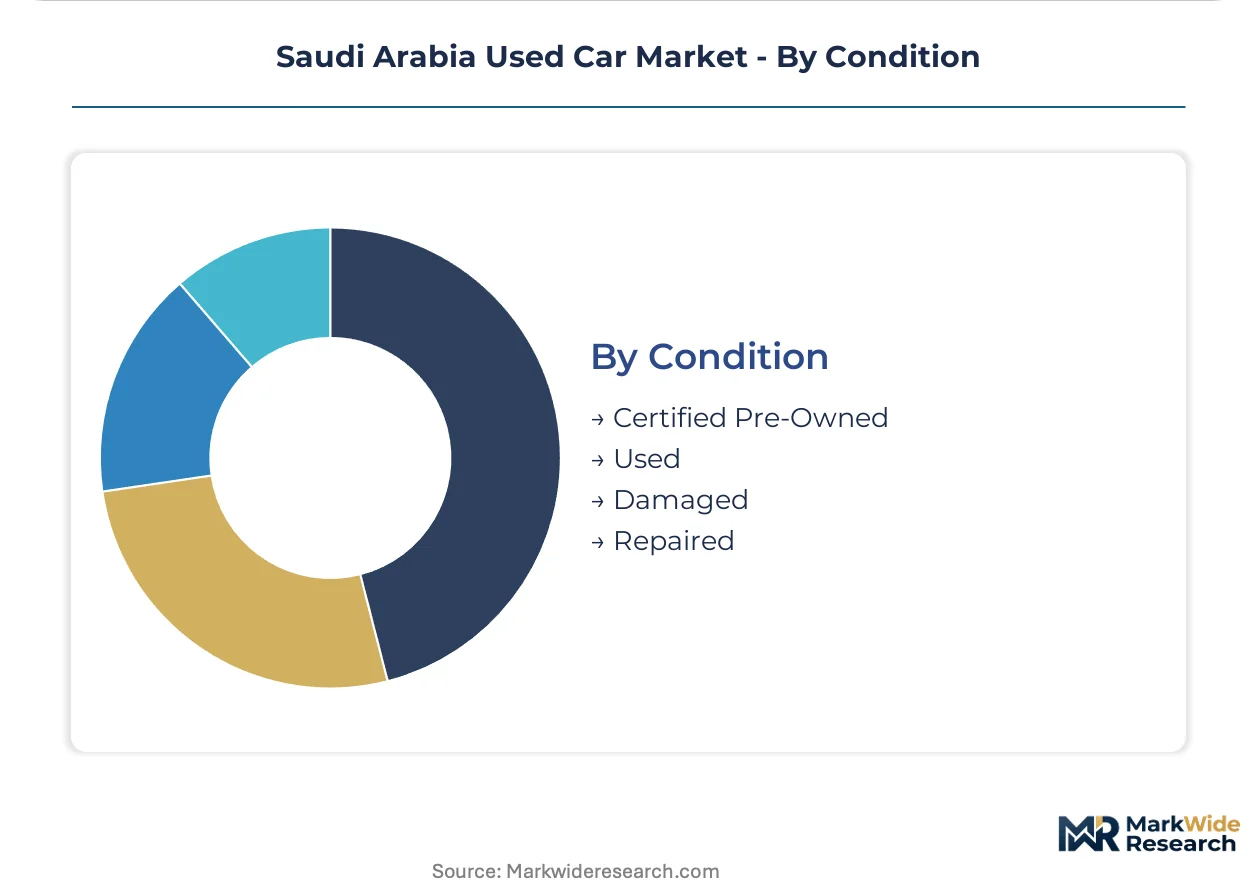
Condition:
Certification tiers separate warranty-backed organized channels from price-driven informal transactions with diverging risk profiles.
- Certified Pre-Owned:Dealer-backed 120-point inspection programs command margin premiums through manufacturer-aligned warranty coverage. SAMR disclosure mandates compress information asymmetry advantages for compliant operators.
- Used:As-is vehicles without warranty backing trade at depreciation discounts through auction and classified channels.
- Repaired:Collision-restored units with documented structural work attract budget-constrained buyers with transparent damage history.
- Damaged:Salvage-title vehicles require specialized reconditioning investment and face financing eligibility restrictions.
Certified pre-owned captures the dominant margin pool, while repaired vehicles with full documentation are expanding most quickly as auction transparency improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA certification requirements and SAMR disclosure mandates anchor Riyadh's dominance in Saudi Arabia's used car value chain. The Central Region concentrates wholesale auction infrastructure and inspection capacity that serves nationwide distribution networks.
Riyadh
Fleet procurement contracts from commercial operators drive transaction velocity through Riyadh's concentrated auction facilities. SAMR's accident history disclosure requirements compress information asymmetry for volume buyers sourcing certified pre-owned inventory. The Riyadh-Jeddah corridor anchors reconditioning investment as dealer groups scale multi-brand service networks to control quality at volume.
Eastern Province
Petrochemical sector fleet rotation sustains steady supply of low-mileage executive sedans entering secondary channels. MOHAP coordination on commercial vehicle safety compliance shapes ride-hailing eligibility standards that filter inventory toward organized dealers. Dammam's port infrastructure handles cross-border transfer flows subject to Saudi Standards, Metrology and Quality Organization mechanical benchmarks.
Western Region
Jeddah's commercial buyer base prioritizes four-door configurations for executive transport applications in corporate fleet refresh cycles. The city's dense metropolitan core supports compact hatchback demand for entry-level personal mobility. Western Region dealers face compressed margins from informal classified channel competition without warranty backing.
NEOM Northwest
Planned smart mobility infrastructure creates forward demand signals for electric and hybrid drivetrain secondary channels. Regulatory frameworks for autonomous vehicle integration remain under development with transport authority coordination. The zone's construction phase generates commercial vehicle demand that filters into used truck and van procurement pools.
Saudi Arabia Used Car Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Saudi Arabia's used car distribution structure. Multi-brand automotive groups leverage captive service networks to control reconditioning quality and warranty fulfillment. Digital-first aggregators compete on inventory breadth and search cost reduction rather than physical lot presence. Competitive moves concentrate on certification program standardization and geographic platform expansion beyond Riyadh-Jeddah corridor concentration.
Within the integrated automotive group tier, Abdul Latif Jameel Motors and Al-Futtaim Automotive exemplify scale-driven reconditioning control through multi-brand service infrastructure. Syarah occupies a position representing digital-native inventory aggregation that reduces physical asset intensity. These three anchors illustrate the market's bifurcation between quality-certification-heavy organized channels and technology-enabled marketplace models.
| Leading Market Players |
|---|
| Al-Nabooda Automobiles |
| Aljomaih Automotive Company |
| Abdul Latif Jameel Motors |
| YallaMotor |
| Syarah |
| Al-Futtaim Automotive (AutoTrust) |
| Arabian Auto Agency |
| Dubizzle Motors |
| Al-Tayer Motors |
| Others |
Value Chain & Pricing Dynamics
Riyadh's concentrated wholesale auction infrastructure compresses reconditioning cost curves for volume operators while establishing regional price floors that informal channels struggle to match. Scale economies in multi-brand service networks anchor certified pre-owned premiums as SAMR disclosure mandates raise compliance barriers for fragmented competitors.
Pricing Analysis
The Riyadh-Jeddah corridor commands a 12-18% price premium over Eastern Province auction floors due to inspection capacity concentration and faster inventory velocity. Three-tier pricing separates certified pre-owned units with 120-point inspections from documented used vehicles and as-is auction lots. Price differentiation rests on warranty backing and service history completeness rather than brand alone. Fleet procurement contracts show lowest price sensitivity given total cost of ownership frameworks, while personal buyers in Jeddah's dense urban core drive hardest bargain compression.
Supply Chain Analysis
King Fahd Causeway transit and Dammam port clearance underwrite cross-border used vehicle flows from Bahrain and UAE auction houses. Geographic supply concentrates in Japan, South Korea, and the United States as source markets for low-mileage sedans and hybrid SUVs entering Saudi channels. Raw material dependencies span automotive-grade steel, catalytic converter precious metals, and lithium-ion battery packs for hybrid refurbishment. Single-source vulnerability runs through Japanese OEM parts networks for specialized hybrid components. Distribution runs through Riyadh's bonded auction facilities before radiating to Jeddah and Dammam dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's used car market is reshaping around regulatory technology adoption as SAMR's digital disclosure mandates and AI-driven condition assessment compress traditional information advantages.
For Market Incumbents: Consolidate reconditioning capacity around Riyadh-Jeddah corridor inspection hubs before technician certification shortfalls worsen. Lock multi-brand service network exclusivity to defend margin premiums against digital aggregators. SAMR's tightening accident history mandates favor operators with capitalized documentation systems over informal auction competitors. For New Entrants and Emerging Players: Differentiate on AI-driven condition assessment to reduce physical inspection dependency and expand beyond Riyadh-Jeddah concentration. Target ride-hailing fleet procurement in Jeddah where MOHAP safety compliance creates certified pre-owned eligibility barriers for informal channels. Deploy platform-based inventory aggregation with smartphone-enabled damage submission to capture personal buyer segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among multi-brand service networks with captive reconditioning capacity and warranty fulfillment infrastructure. Long-term viability over a five-to-ten year horizon favors operators with backward integration into parts distribution and technician training pipelines. Monitor SAMR's Zakat and VAT policy evolution as the signal for dealer profitability model restructuring and consumer financing access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Condition Assessment Deployment | Computer vision systems reduce physical inspection dependency and compress valuation timelines for fleet buyers. |
| Multi-Brand Service Network Expansion | Captive reconditioning capacity controls quality at volume and anchors certified pre-owned warranty fulfillment. |
| Digital Inventory Aggregation Platform | Smartphone-enabled sourcing expands geographic reach beyond Riyadh-Jeddah corridor concentration. |
| Technician Certification Pipeline Investment | Structured training programs address labor bottlenecks limiting dealer scaling velocity under SAMR mandates. |
| Ride-Hailing Fleet Partnership Program | MOHAP safety compliance criteria create certified pre-owned eligibility standards favoring organized supply channels. |
Study Parameters
A standing panel of fleet procurement managers, dealership operations directors, auction house executives, and SAMR compliance officers provided ongoing calibration against market developments. Primary interviews with reconditioning technicians and digital platform engineers combined with secondary validation from vehicle registration databases, customs import records, and SAMR regulatory filings. Bottom-up transaction volume modeling and top-down macroeconomic triangulation anchored value estimates across the analysis window.
Consistency checks against auction clearance rates and dealer inventory turnover benchmarks validated projection outputs. The analytical framework segments by product type, engine configuration, usage pattern, and condition tier across the modeling period. CAGRs derive from fitted trend analysis incorporating fuel economy regulation trajectories and fleet rotation cycle patterns. Hybrid drivetrain adoption curves and certified pre-owned penetration rates served as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside SAMR enforcement intensity and technician supply expansion assumptions would require recalibration. Forecasts reflect documented assumptions about regulatory compliance costs and digital platform adoption trajectories. Practitioners should keep alternative scenarios live as Zakat and VAT policy evolution and cross-border transfer friction conditions develop.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
Poland Used Car Market
Used Vehicles
Germany Used Car Market
Used Vehicles
South Africa Used Car Market
Used Vehicles
Qatar Used Car Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Indonesia Used Car Financing Market
Used Vehicles
North America Used Car Market
Used Vehicles
United Kingdom Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Bangladesh Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
Europe Used Car Market
Used Vehicles
France Used Car Market
Used Vehicles
GCC Used Car Market
Used Vehicles
Hong Kong Used Car Market
Used Vehicles
Norway Used Car Market