
 Spain AI in Fintech Market | 2026-2036
Spain AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Spain AI in Fintech Market Insights
A persistent shortage of machine learning engineers fluent in financial risk modeling is unwinding growth timelines for Spanish fintech deployments. SNAB leverages its Barcelona engineering base to sustain proprietary natural language processing tools for payment automation. IAHORRO anchors its competitive position through specialized robo-advisory algorithms tailored to Spanish mortgage products. TaxDown competes on automated tax-optimization workflows that navigate Spain's complex regional fiscal codes.
Spain AI in Fintech encompasses algorithmic systems that process transactional data, generate credit risk assessments, and automate customer interactions through machine learning pipelines operating on distributed cloud infrastructure. These systems primarily reduce operational latency in financial decision-making while maintaining audit trails for regulatory examination. Machine Learning dominates technology deployment as Spanish institutions prioritize pattern recognition for fraud detection over conversational interfaces. Predictive Analytics represents the fastest-expanding segment as insurers and payment providers build anticipatory models for default probability. Consulting services capture disproportionate margin pools because Spanish mid-tier banks lack in-house data science capacity and require external architecture guidance.
The Bank of Spain and the National Securities Market Commission (CNMV) enforce transparency standards for algorithmic credit decisions, while the EU AI Act imposes conformity requirements on high-risk financial AI systems that restrict market access for non-compliant vendors. Spanish fintech operators must reconcile national consumer protection statutes with Brussels-mandated algorithmic accountability frameworks. Stakeholders should monitor how the European Banking Authority refines technical standards for model risk management before committing to platform investments.
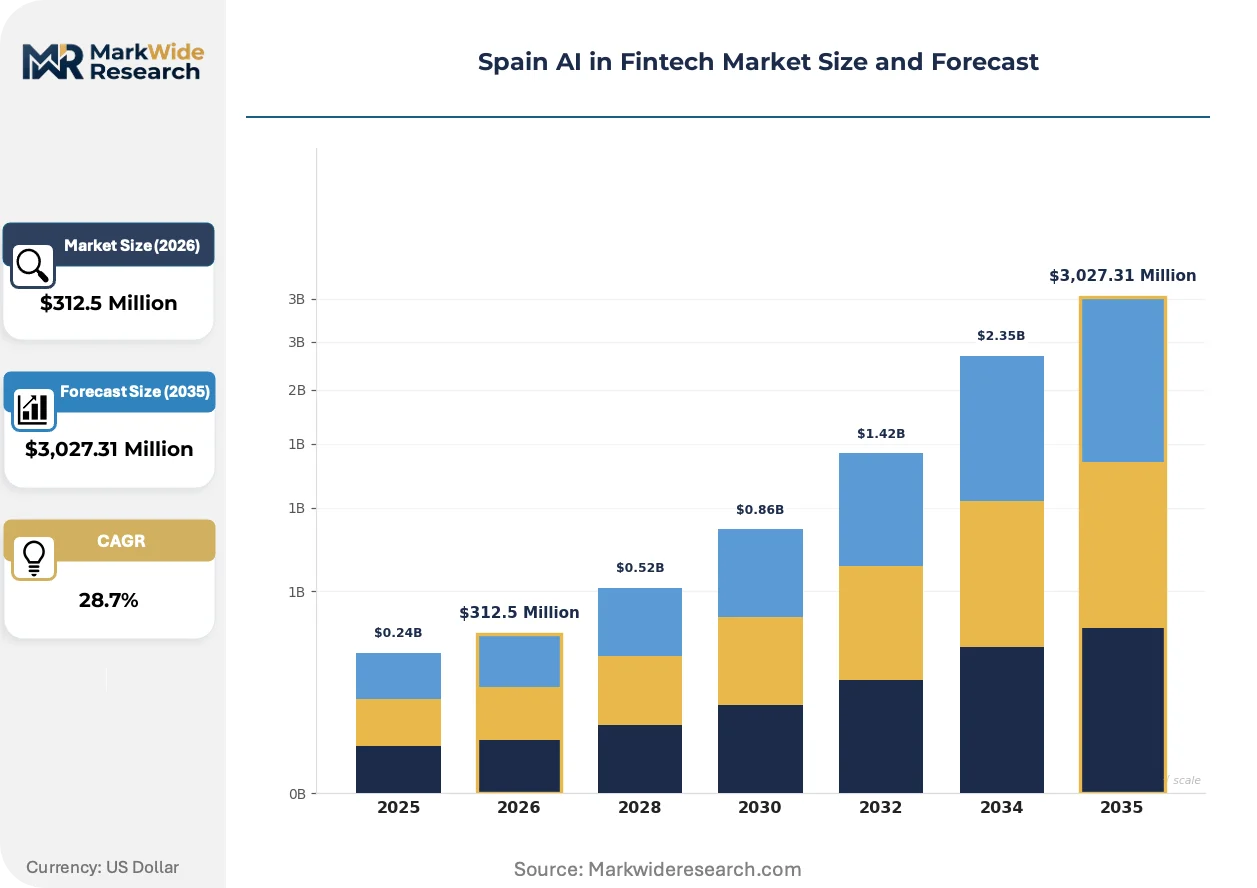
Market Dynamics
The EU AI Act's risk-based classification system for algorithmic credit decisions is forcing Spanish retail banks to restructure their machine learning governance frameworks before enforcement deadlines solidify.
Growth Catalysts
- Automated Credit Scoring:Spanish retail banks deploy machine learning pipelines to compress loan approval cycles from weeks to hours. The Bank of Spain's sandbox regime permits controlled algorithmic testing before full authorization.
- EU AI Act Conformity:Madrid-based compliance consultancies capture margin pools by guiding mid-tier institutions through high-risk system documentation requirements. The regulation mandates audit trails for all automated lending decisions.
- Barcelona Engineering Concentration:Catalonia's technical universities feed specialized talent into natural language processing applications for payment automation. This geographic cluster sustains proprietary tool development for invoice reconciliation workflows.
Market Restraints
- Machine Learning Engineer Scarcity:Spanish fintech operators compete with German and French institutions for risk modeling specialists fluent in both Python and Basel III frameworks. Recruitment timelines stretch deployment schedules.
- Cloud Infrastructure Concentration:Three hyperscale providers dominate the distributed computing backbone for Spanish financial AI, creating single-point vulnerability for latency-sensitive fraud detection systems.
- Regional Fiscal Code Complexity:Spain's autonomous communities maintain divergent tax treatments that fragment training data for automated advisory tools. Basque Country and Navarre regimes require separate model calibration.
Strategic Opportunities
- Andalusian Agricultural Lending:Underpenetrated cooperative banks in southern Spain lack in-house data science capacity for crop yield prediction models. External architecture partnerships unlock this segment.
- Embedded Insurance Convergence:Payment providers integrate predictive analytics with point-of-sale terminals to offer micro-coverage at transaction moments. This convergence creates new revenue streams beyond interchange fees.
- CNMV Regulatory Sandboxes:The National Securities Market Commission's controlled testing environment accelerates authorization for robo-advisory algorithms. Early entrants capture mortgage advisory market share before framework standardization.
Industry Challenges
- Model Risk Management Certification:Spanish institutions await European Banking Authority technical standards before committing to platform investments. This timeline uncertainty freezes procurement decisions.
- Core Banking Integration Complexity:Legacy COBOL systems at mid-tier Spanish banks resist API connectivity with cloud-native machine learning pipelines. Middleware development consumes disproportionate project resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain AI in Fintech Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $3,027.31 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Credit Scoring, Customer Service, Risk Management Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Blockchain Service Type: Consulting, Deployment, Support, Managed Services End User: Retail Banking, Investment Firms, Insurance Companies, Payment Providers |
| Companies Covered | SNAB, Unibo Neobank, Murphy, IAHORRO, Lana XYZ, Klara AI, TaxDown, Alfa Blockchain, Fintonic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain AI in Fintech Market Trends and Innovations
Spanish fintech operators are restructuring their technology stacks around explainable AI architectures that satisfy both regulatory auditors and commercial underwriters. This reconfiguration prioritizes interpretability over raw predictive accuracy.
Transformer-based natural language processing is displacing rule-based document extraction in Spanish mortgage origination workflows. Santander and BBVA subsidiaries deploy these models to parse notarized property records across Castilian, Catalan, and Galician language variants. The technology compresses due diligence timelines while generating the audit trails that EU AI Act conformity assessments demand.
The EU AI Act's high-risk system designation for credit scoring algorithms triggers mandatory conformity assessments before market deployment. Spanish fintech vendors must now maintain technical documentation, human oversight protocols, and accuracy benchmarking that exceeds previous national standards. The robo-advisory segment faces the steepest compliance burden as investment recommendation algorithms fall under strictest scrutiny.
Spanish corporate treasurers now require outcome-based pricing for fraud detection services rather than per-seat software licenses. Payment processors respond with performance-linked contracts that tie fees to measured reduction in false-positive transaction blocks. This procurement evolution concentrates vendor selection among providers with proven deployment histories at Iberian retail banks.
Spain AI in Fintech Market Segmentation
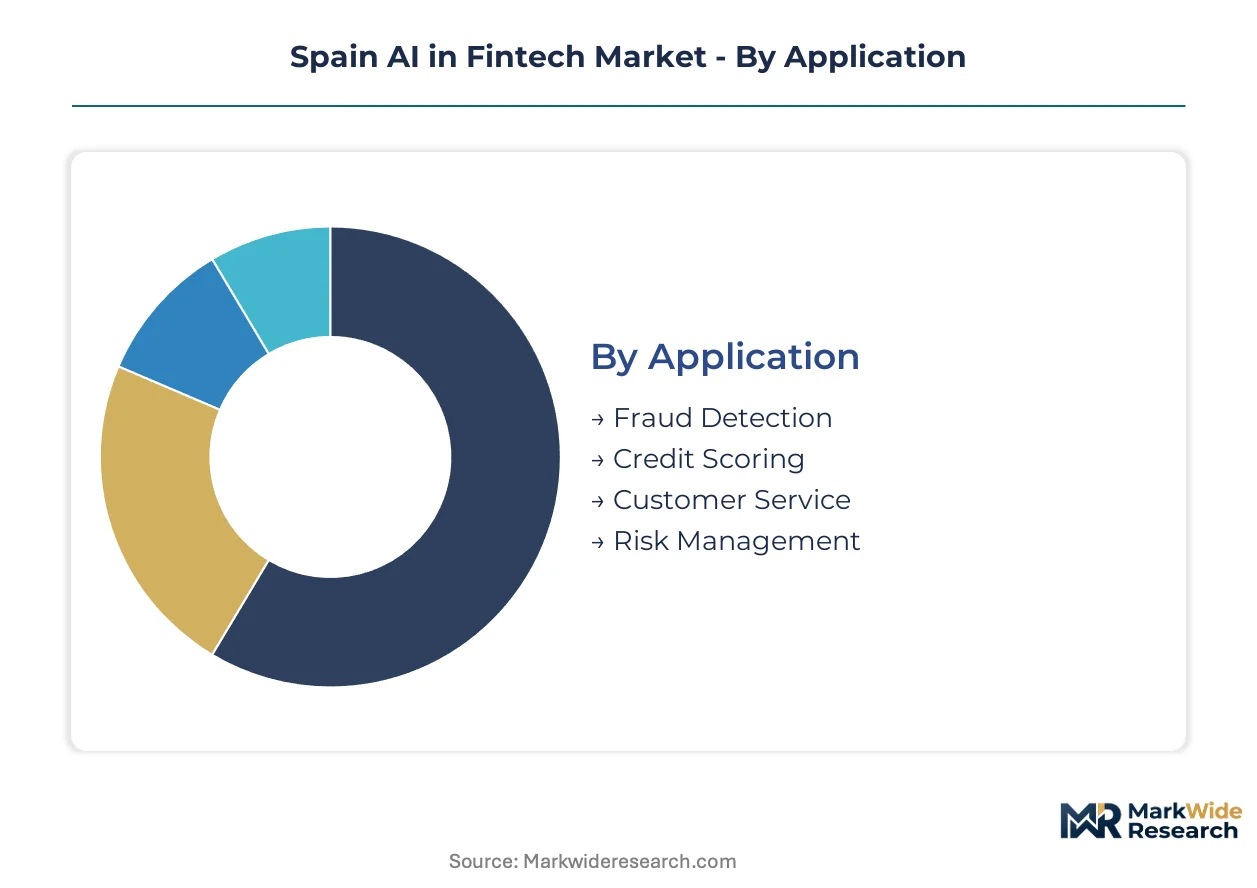
Spanish fintech operators structure their AI investments around four intersecting dimensions that determine both regulatory exposure and margin capture. Application focus dictates compliance burden under EU AI Act risk classifications. Technology choices reflect talent availability concentrated in Barcelona and Madrid corridors.
Application:
Fraud detection and credit scoring concentrate investment within Spanish borders, while customer service automation increasingly serves cross-border EU clients from Barcelona engineering bases.
- Fraud Detection:Real-time transaction pattern recognition systems operating on distributed cloud infrastructure. Demand clusters at BBVA and Santander subsidiaries in Madrid, driven by EU AI Act mandates for audit trails on payment monitoring algorithms.
- Credit Scoring:Machine learning pipelines assessing default probability from alternative data sources. Spanish retail banks deploy these systems domestically, constrained by Bank of Spain transparency requirements for algorithmic lending decisions.
- Customer Service:Conversational interfaces and chatbot deployments for account inquiries. Mid-tier institutions outsource development to Barcelona NLP specialists serving both domestic and Portuguese markets.
- Risk Management:Portfolio stress-testing and market risk quantification tools. Investment firms in Madrid's financial district drive demand for regulatory capital optimization models.
Fraud detection holds the largest share; momentum sits with credit scoring as retail banks accelerate automated lending timelines.
Technology:
Cost tier differentiation separates established Spanish institutions investing in full machine learning stacks from mid-tier players purchasing predictive analytics as managed services.
- Machine Learning:Supervised and unsupervised learning frameworks for pattern recognition in transactional data. Spanish banks prioritize these deployments for Basel III compliance, though engineer scarcity stretches implementation schedules.
- Predictive Analytics:Anticipatory models for customer churn and default probability. Insurance companies in Barcelona's insurtech cluster expand these capabilities fastest for usage-based pricing products.
- Natural Language Processing:Document extraction and conversational systems processing Castilian, Catalan, and Galician variants. SNAB maintains proprietary tools for invoice reconciliation workflows.
- Blockchain:Distributed ledger applications for trade finance and identity verification. Spanish adoption lags other EU markets due to regulatory uncertainty from CNMV and Bank of Spain guidance gaps.
Machine learning dominates current investment; predictive analytics is expanding most quickly as insurers build anticipatory capabilities.
Service Type:
Customer type fragmentation splits the market between large Spanish banks with internal data science teams and mid-tier institutions dependent on external architecture guidance.
- Consulting:Regulatory compliance and model risk management advisory. Madrid-based consultancies capture margin pools guiding EU AI Act conformity assessments for high-risk credit systems.
- Deployment:End-to-end implementation of machine learning pipelines. Spanish mid-tier banks require extensive middleware development to connect cloud-native tools with legacy COBOL infrastructure.
- Support:Ongoing model monitoring and retraining services. Payment providers demand 24/7 coverage for latency-sensitive fraud detection systems.
- Managed Services:Fully outsourced AI operations with outcome-based pricing. Corporate treasurers now require performance-linked contracts tying fees to measured false-positive reduction.
Consulting commands premium margins today; managed services are gaining share fastest as procurement shifts toward outcome-based structures.
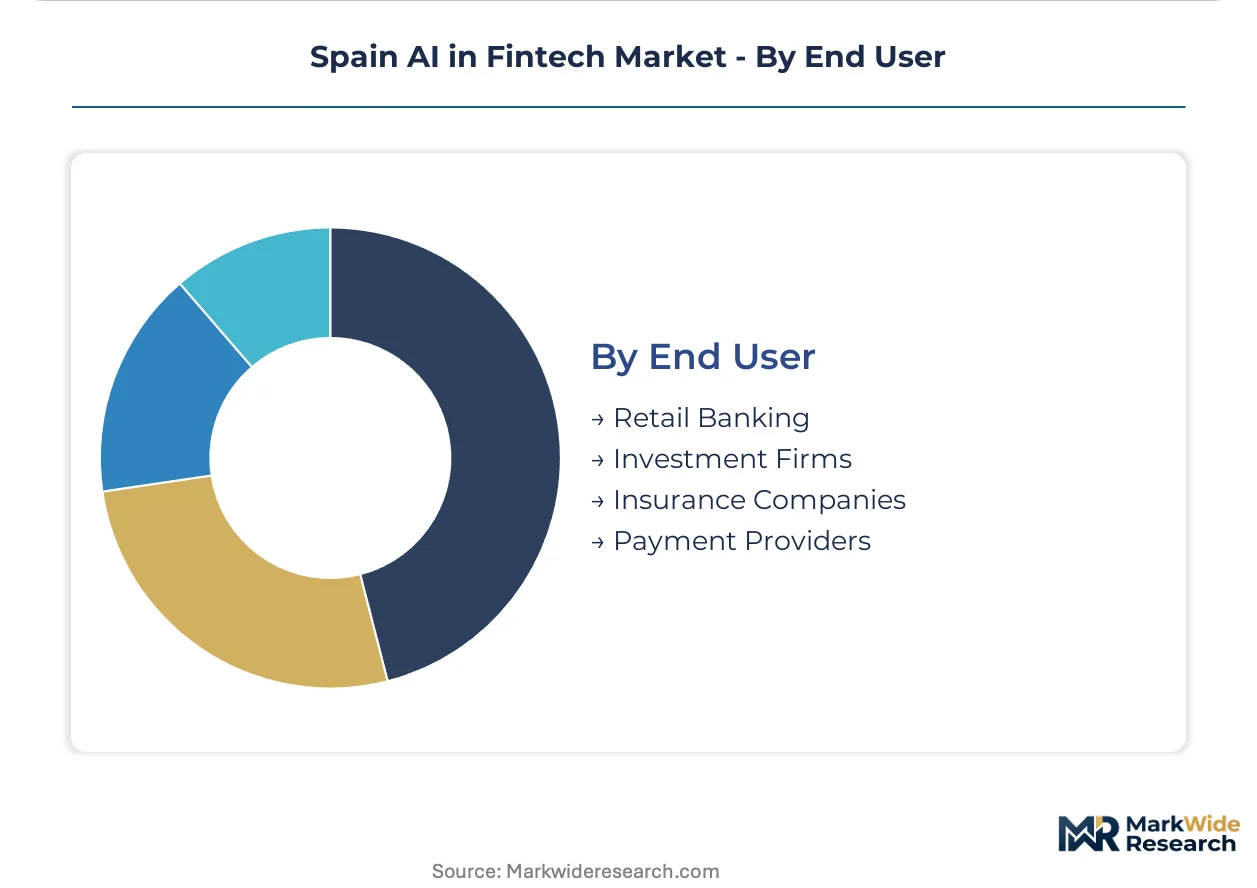
End User:
Volume concentration varies sharply across Spanish financial subsectors, with retail banking absorbing the majority of compliance-driven investment while payment providers lead on innovation velocity.
- Retail Banking:Automated credit decisions and customer onboarding workflows. Spanish institutions compress loan approval cycles from weeks to hours through machine learning pipelines tested in Bank of Spain sandboxes.
- Payment Providers:Real-time fraud detection and embedded insurance integration. Barcelona-based operators converge predictive analytics with point-of-sale terminals for micro-coverage at transaction moments.
- Insurance Companies:Claims automation and risk pricing models. IAHORRO anchors competitive position through robo-advisory algorithms tailored to Spanish mortgage products.
- Investment Firms:Algorithmic trading and portfolio optimization. CNMV regulatory sandboxes accelerate authorization for these systems before framework standardization.
Retail banking absorbs the largest investment volume; payment providers show the steepest expansion trajectory as embedded finance converges with AI infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Bank of Spain and CNMV anchor national oversight for algorithmic financial systems, while the EU AI Act imposes cross-border conformity requirements on high-risk credit scoring deployments across Spanish territory.
Madrid
Retail banking concentration drives automated lending pipeline investment across the capital region. The Bank of Spain's sandbox regime permits controlled algorithmic testing for credit decision systems before full market authorization. Madrid's financial district hosts BBVA and Santander innovation subsidiaries developing real-time fraud detection infrastructure.
Catalonia
Barcelona's technical universities feed specialized natural language processing talent into payment automation ventures. The regional government supports AI cluster development through Catalan Trade & Investment programs targeting fintech scale-ups. SNAB leverages this engineering base for proprietary invoice reconciliation tools serving Iberian corporate treasurers.
Basque Country
Divergent fiscal treatment from Spain's common regime fragments training data requirements for tax-optimization algorithms. The regional economic development agency SPRI promotes financial technology adoption among Bilbao-based cooperative banks. Local operators must maintain separate model calibrations for Navarre's distinct tax code alongside Basque fiscal frameworks.
Andalusia
Agricultural cooperative banks in southern Spain lack in-house data science capacity for crop yield prediction models. The Junta de Andalucía's digital transformation incentives target rural financial inclusion through external architecture partnerships. Seville and Málaga emerging as secondary hubs for embedded insurance convergence with point-of-sale payment terminals.
Valencia
Mid-tier insurance operators accelerate predictive analytics deployment for usage-based pricing products along the Mediterranean corridor. The regional innovation agency Innovall channels EU structural funds toward insurtech algorithm development. Valencia's lower operational costs attract Barcelona-based fintechs establishing satellite engineering centers.
Spain AI in Fintech Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Spanish fintech AI segment. Established banking subsidiaries command infrastructure scale for real-time fraud detection, while specialized neobanks and tax-optimization ventures capture niche margin pools through focused algorithmic development. The competitive structure separates three archetypes: incumbent-backed technology divisions, venture-funded vertical specialists, and compliance-focused advisory services. Dominant competitive moves include strategic partnerships with cloud infrastructure providers and portfolio diversification into embedded insurance products.
Among Barcelona-based engineering ventures, SNAB anchors the payment automation archetype through natural language processing specialization. IAHORRO occupies a position within the mortgage-focused robo-advisory tier, while TaxDown exemplifies the tax-optimization vertical through automated workflow development for Spain's complex regional fiscal codes.
| Leading Market Players |
|---|
| SNAB |
| Unibo Neobank |
| Murphy |
| IAHORRO |
| Lana XYZ |
| Klara AI |
| TaxDown |
| Alfa Blockchain |
| Fintonic |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day lead times for specialized GPU clusters concentrate pricing power among three hyperscale cloud providers serving Spanish financial AI deployments. This inventory constraint tightens margins for mid-tier banks while amplifying the negotiating leverage of Madrid-based retail institutions with volume commitments.
Pricing Analysis
Madrid-based institutions pay fifteen to twenty percent premiums over Barcelona engineering ventures for equivalent compute capacity due to proximity-driven service bundling. Spanish fintech AI operates on subscription-tiered SaaS structures with premium-mid-economy pricing differentiation anchored to model complexity tiers. Cost compression in the mid-market tier is intensifying because payment processors now demand outcome-based contracts tying fees to false-positive reduction metrics. Retail banking subsidiaries of BBVA and Santander show least price sensitivity due to captive compliance budgets, while Andalusian agricultural cooperatives exhibit highest sensitivity to per-seat licensing costs.
Supply Chain Analysis
Sixty-day lead times for NVIDIA H100 clusters currently constrain deployment timelines for Spanish fraud detection pipelines. Hardware supply concentrates in the United States, Taiwan, and South Korea, with Spanish operators drawing from Amsterdam and Frankfurt distribution hubs to minimize latency. The supply chain hinges on specialized AI accelerators, high-bandwidth memory modules, and liquid cooling infrastructure. Single-source vulnerability around TSMC fabrication for advanced GPUs exposes Spanish institutions to allocation priority shifts. Distribution runs through direct hyperscaler contracts rather than channel intermediaries, with Madrid and Barcelona hosting primary availability zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent Spanish fintech operators face substitution pressure from German and French institutions recruiting Barcelona engineering talent at premium compensation multiples. Defense requires structural moves before talent scarcity hardens into permanent competitive disadvantage.
For Market Incumbents: Fortify proprietary model architectures through backward integration into specialized NLP training pipelines for Catalan and Galician document variants. Lock Barcelona engineering talent through equity participation structures that match German competitor offers. The EU AI Act documentation burden is the priority threat; preemptive compliance investment creates switching costs for mid-tier bank clients. For New Entrants and Emerging Players: Differentiate on Andalusian agricultural lending workflows where cooperative banks lack internal data science capacity. Target embedded insurance convergence at point-of-sale terminals in Seville and Málaga as the most penetrable white-space segment. Lead with crop yield prediction partnerships that unlock Junta de Andalucía digital transformation subsidies. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EU AI Act conformity assessments will consolidate vendor relationships around proven documentation capabilities. Acquisition targets should display established Bank of Spain sandbox track records and proprietary tooling for regional fiscal code navigation. Monitor European Banking Authority technical standard releases as the signal for procurement decision thawing.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Architecture Investment | Interpretability tooling satisfies EU AI Act audit trail mandates for BBVA and Santander compliance teams. |
| Barcelona Engineering Talent Acquisition | NLP specialist concentration at UPC and UPF feeds proprietary invoice reconciliation development for SNAB. |
| CNMV Regulatory Sandbox Entry | Early authorization for robo-advisory algorithms captures mortgage advisory share before framework standardization. |
| Embedded Insurance Partnership | Predictive analytics integration with POS terminals creates micro-coverage revenue beyond interchange fees. |
| Andalusian Cooperative Bank Alliance | External architecture partnerships unlock agricultural lending segment lacking in-house data science capacity. |
Research Methodology
The analysis maps machine learning deployment, predictive analytics adoption, NLP tooling development, and blockchain integration, each validated through CTO interviews at Spanish retail banks, compliance officers at CNMV-regulated investment firms, procurement leads at Barcelona payment processors, and engineering directors at insurtech ventures. Primary fieldwork combined with secondary validation against Bank of Spain sandbox disclosures, CNMV authorization registries, EU AI Act implementation guidance, and hyperscaler capex announcements enabled bottom-up and top-down triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology type, application focus, service tier, and end-user segment dimensions alongside deployment complexity and regional regulatory cluster variations. CAGRs derived from historical adoption curves adjusted for EU AI Act enforcement timing and engineer supply constraints. Forecast inputs incorporated Bank of Spain sandbox authorization velocity and Catalan university NLP program graduation rates.
The analysis sits within stated boundaries; outcomes outside EU AI Act enforcement adherence or sustained hyperscaler GPU allocation would require recalibration. Forecasts reflect documented assumptions about regulatory timeline stability and talent migration patterns. Specific risks that could revise projections include European Banking Authority technical standard delays and accelerated German recruitment of Barcelona engineering talent. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Latin America Fintech Market
FinTech
Smart Advisors Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
AI in Fintech Market
FinTech
Digital Banking Platform Market
FinTech
Stock Trading App Market
FinTech
France AI in Fintech Market
FinTech
Australia Fintech Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Fintech-As-A-Service Market
FinTech
Europe AI in Fintech Market
FinTech
Fintech Crisis Management Market
FinTech
Spend Management Platform Market
FinTech
Robo-Advisory Services Market
FinTech
India AI in Fintech Market
FinTech
Canada AI in Fintech Market