
 Asia Pacific Digital Forensics Market | 2026-2036
Asia Pacific Digital Forensics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Digital Forensics Market Outlook
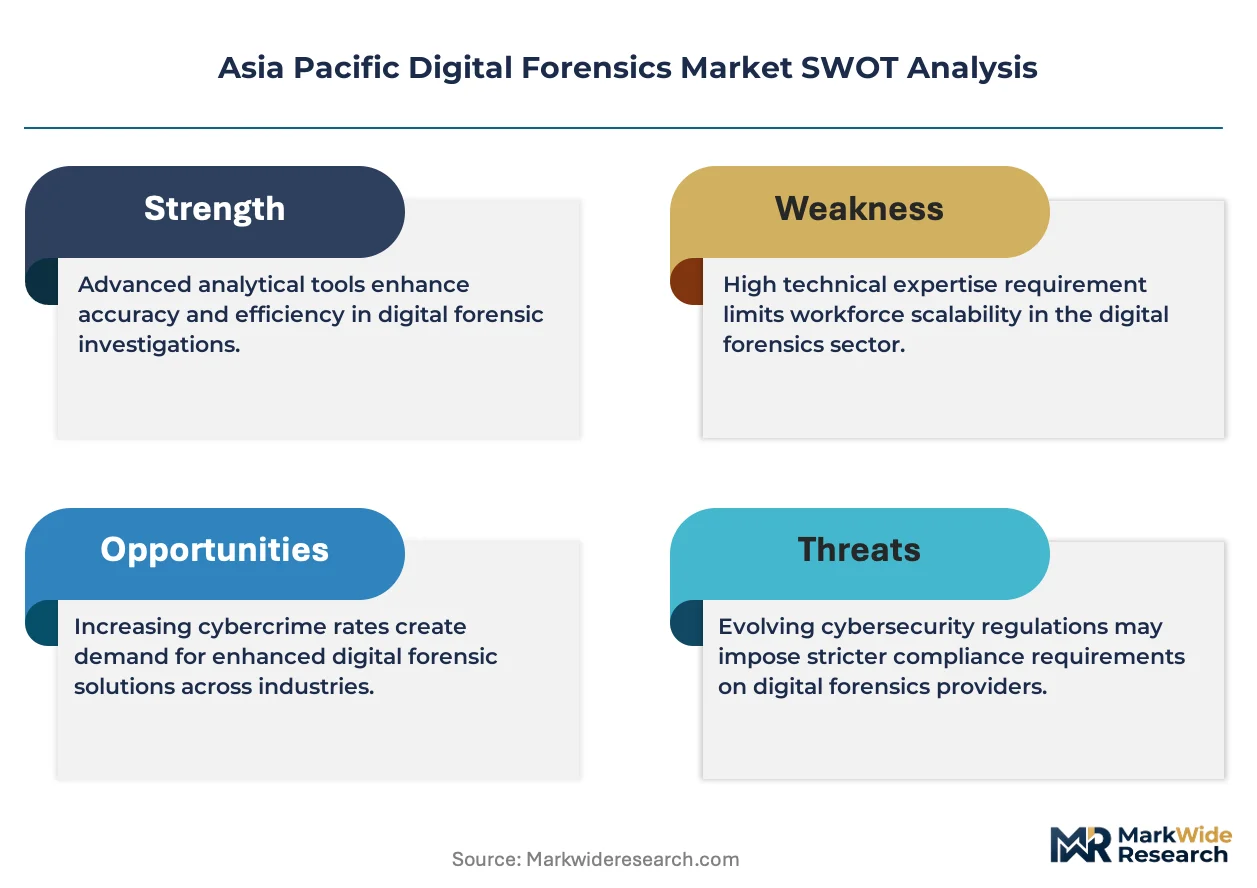
Enterprise-grade forensic certification standards are redrawing competitive boundaries in the Asia Pacific Digital Forensics Market. Cellebrite leverages its mobile extraction specialization to anchor premium service tiers across Australian federal contracts. MSAB Inc. competes through hardware-software integration for law enforcement field kits. IBM Corporation extends its cloud-native forensic architecture into hybrid enterprise environments across Japan and South Korea.
Asia Pacific digital forensics encompasses the scientific recovery, preservation, and analysis of electronic evidence from computing devices, networks, and storage media, operating at throughput rates exceeding terabyte-scale data volumes per investigation. The discipline serves criminal prosecution, civil litigation, corporate compliance, and national security operations across the region. Cloud forensics now leads technology segment momentum as distributed evidence repositories outpace on-premise architectures. Mobile forensics sustains the fastest growth trajectory given smartphone penetration rates and encrypted messaging proliferation across Southeast Asian markets. Incident response commands the largest application margin pool due to mandatory breach notification timelines compressing procurement cycles.
Australia's TGA-aligned cybersecurity frameworks and India's CERT-In directives are mandating forensic readiness for critical infrastructure operators, directly expanding compliance service demand. China's GB standards for data classification and Japan's METI cybersecurity guidelines further segment product certification requirements across national procurement channels. Stakeholders must monitor divergence between national encryption access policies and cross-border evidence transfer protocols when allocating regional R&D resources.
Market Dynamics
Cloud forensics adoption is bifurcating enterprise procurement patterns across Asia Pacific as distributed evidence repositories outpace traditional on-premise architectures, forcing vendors to recalibrate service delivery models around hybrid deployment options.
Growth Catalysts
- India's PLI scheme:Electronics manufacturing incentives accelerate data center construction requiring forensic-ready infrastructure and incident response capabilities.
- Smartphone penetration:Encrypted messaging proliferation across Southeast Asian markets sustains mobile forensics as the fastest-expanding technology segment.
- Australia's TGA-aligned frameworks:Mandatory cybersecurity readiness for critical infrastructure operators directly expands compliance service procurement cycles.
Market Restraints
- Encryption access divergence:National policies on lawful interception vary sharply between Australia, India, and China, complicating cross-border evidence transfer protocols.
- Certification fragmentation:China's GB standards, Japan's METI guidelines, and India's CERT-In directives create incompatible product certification requirements across procurement channels.
- Talent scarcity:Forensic examiner certification programs lag behind terabyte-scale investigation throughput requirements in tier-one Chinese cities.
Strategic Opportunities
- Indonesia's underpenetrated enterprise segment:Banking and telecommunications sectors lack mature forensic capabilities, creating first-mover advantages for cloud-native service providers.
- AI-augmented analysis:Machine learning integration with mobile extraction tools addresses encrypted device volume backlogs overwhelming law enforcement units.
- Vietnam's data localization mandates:New cybersecurity laws require domestic evidence storage, stimulating local forensic infrastructure investment.
Industry Challenges
- Legacy system integration:Enterprises in Japan and South Korea struggle to embed cloud-native forensic architectures within decades-old on-premise security stacks.
- Cross-border evidence protocols:Divergent national encryption access policies create legal uncertainty for multinational incident response engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Digital Forensics Market |
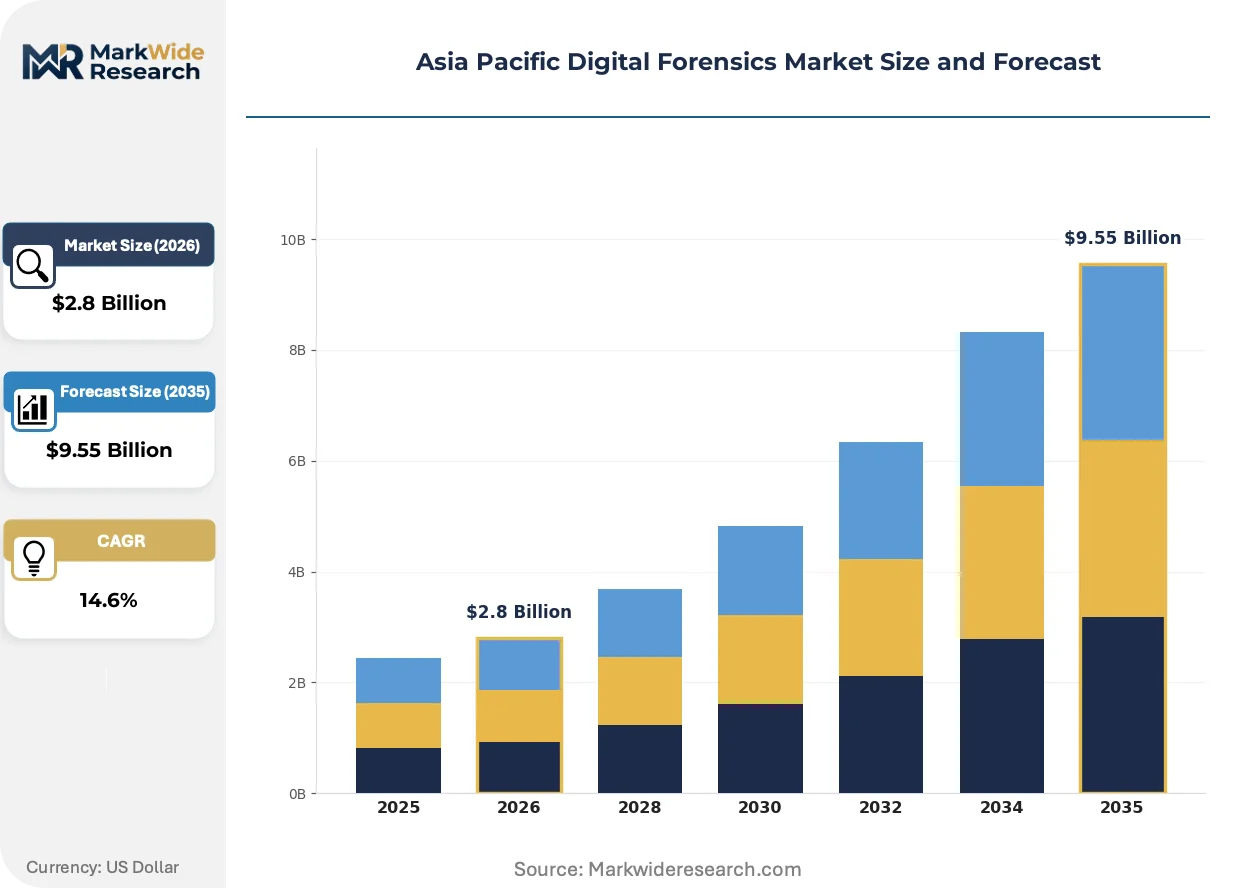
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Data Recovery, Cyber Security, Incident Response, Legal Investigation End User: Law Enforcement, Corporates, Legal Firms, Government Agencies Technology: Cloud Forensics, Network Forensics, Mobile Forensics, Database Forensics Service Type: Consulting, Training, Assessment, Compliance |
| Companies Covered | Paraben Corporation, FireEye Inc., MSAB Inc., IBM Corporation, Cisco Systems Inc., Cellebrite, OpenText, Oxygen Forensics Inc., SecureWorks Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Digital Forensics Market Strategic Shifts
Forensic technology deployment patterns across Asia Pacific are fragmenting around divergent national data sovereignty requirements and encryption governance frameworks, reshaping vendor competitive positioning.
Cloud-native forensic architectures are bifurcating enterprise procurement in Japan and South Korea. Financial services and critical infrastructure operators adopt hybrid deployment models at accelerated pace. This technology is compressing traditional on-premise hardware refresh cycles while expanding recurring service revenue pools for platform providers.
India's CERT-In directives now mandate forensic readiness for critical infrastructure operators with specified incident reporting timelines. Industrial consequence includes compressed procurement cycles for incident response services and mandatory breach notification infrastructure. Energy and telecommunications verticals are responding with dedicated digital evidence unit investments.
Enterprise buying patterns are rotating toward integrated hardware-software field kits for law enforcement applications. Traditional standalone software licensing models face displacement by bundled subscription offerings across Australian federal and state contracts. This shift concentrates procurement authority within national security agencies seeking operational standardization.
Asia Pacific Digital Forensics Market Segmentation
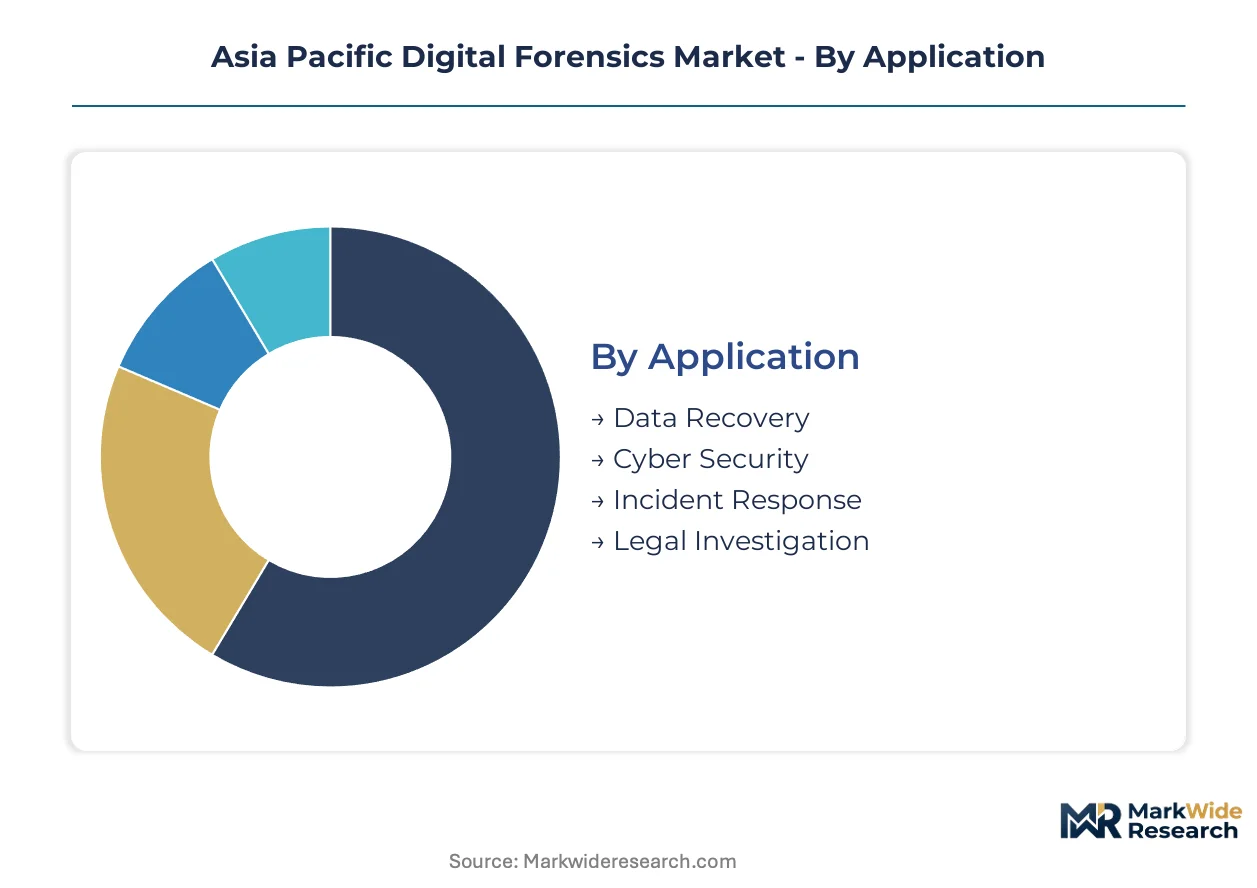
Asia Pacific digital forensics procurement fragments sharply across national security mandates and enterprise maturity curves. Segmentation reveals how technology adoption, regulatory pressure, and end-user capability gaps redistribute competitive advantage across the region.
Application:
Domestic demand concentrates in incident response and legal investigation across Australia's critical infrastructure operators and India's CERT-In regulated sectors. Export-oriented service delivery dominates data recovery and cyber security applications serving multinational corporations with regional headquarters in Singapore and Hong Kong.
- Incident Response:Compressed breach notification timelines under Australia's TGA-aligned frameworks and India's CERT-In directives compress procurement cycles. Energy and telecommunications operators in tier-one Chinese cities and Australian federal agencies drive the largest compliance-driven contract volumes.
- Legal Investigation:Civil litigation discovery requirements and criminal prosecution evidence standards create dual demand tracks. Australian state courts and Indian commercial tribunals sustain the highest case throughput per examiner.
- Data Recovery:Hardware failure and ransomware recovery services target enterprise storage infrastructure across Japan and South Korea manufacturing clusters.
- Cyber Security:Threat hunting and post-breach analysis integrate with SOC operations across Southeast Asian banking and telecommunications verticals.
Incident Response commands the established base. The steepest expansion runs through Legal Investigation.
End User:
Cost tier differentiation separates premium certified service providers serving law enforcement and government agencies from volume-oriented consultancies targeting corporate compliance budgets. Legal firms occupy a mid-tier procurement position with case-specific engagement models.
- Law Enforcement:Federal and state agencies across Australia, India, and China procure integrated hardware-software field kits under national security procurement frameworks. Operational standardization mandates concentrate buying authority within national agencies.
- Government Agencies:Critical infrastructure regulators and defense intelligence units require air-gapped forensic laboratories with domestic data sovereignty compliance. China's GB standards and Japan's METI guidelines segment certification requirements.
- Corporates:Banking, telecommunications, and energy operators in Indonesia and Vietnam lack mature in-house capabilities, creating first-mover opportunities for managed service providers.
- Legal Firms:Discovery and litigation support services concentrate in Singapore and Hong Kong as regional dispute resolution hubs.
Law Enforcement anchors procurement volume. Corporates are climbing the fastest as breach notification mandates expand.
Technology:
Volume concentration in mobile forensics reflects smartphone penetration and encrypted messaging proliferation across Southeast Asian markets. Cloud forensics adoption bifurcates between hybrid enterprise deployments in Japan and South Korea and domestic data localization requirements in Vietnam.
- Mobile Forensics:Device extraction and encrypted messaging analysis tools address backlogs overwhelming law enforcement units across India and Southeast Asia. AI-augmented analysis integration is displacing manual examiner workflows.
- Cloud Forensics:Distributed evidence repository analysis outpaces on-premise architectures across Japanese and South Korean financial services. Hybrid deployment models compress traditional hardware refresh cycles.
- Network Forensics:Packet capture and traffic analysis support critical infrastructure monitoring under Australia's TGA-aligned cybersecurity frameworks.
- Database Forensics:Structured data integrity verification targets enterprise ERP and customer database investigations across Chinese tier-one manufacturing clusters.
Mobile Forensics dominates current deployment. Cloud Forensics is gaining share fastest as data center investments accelerate.
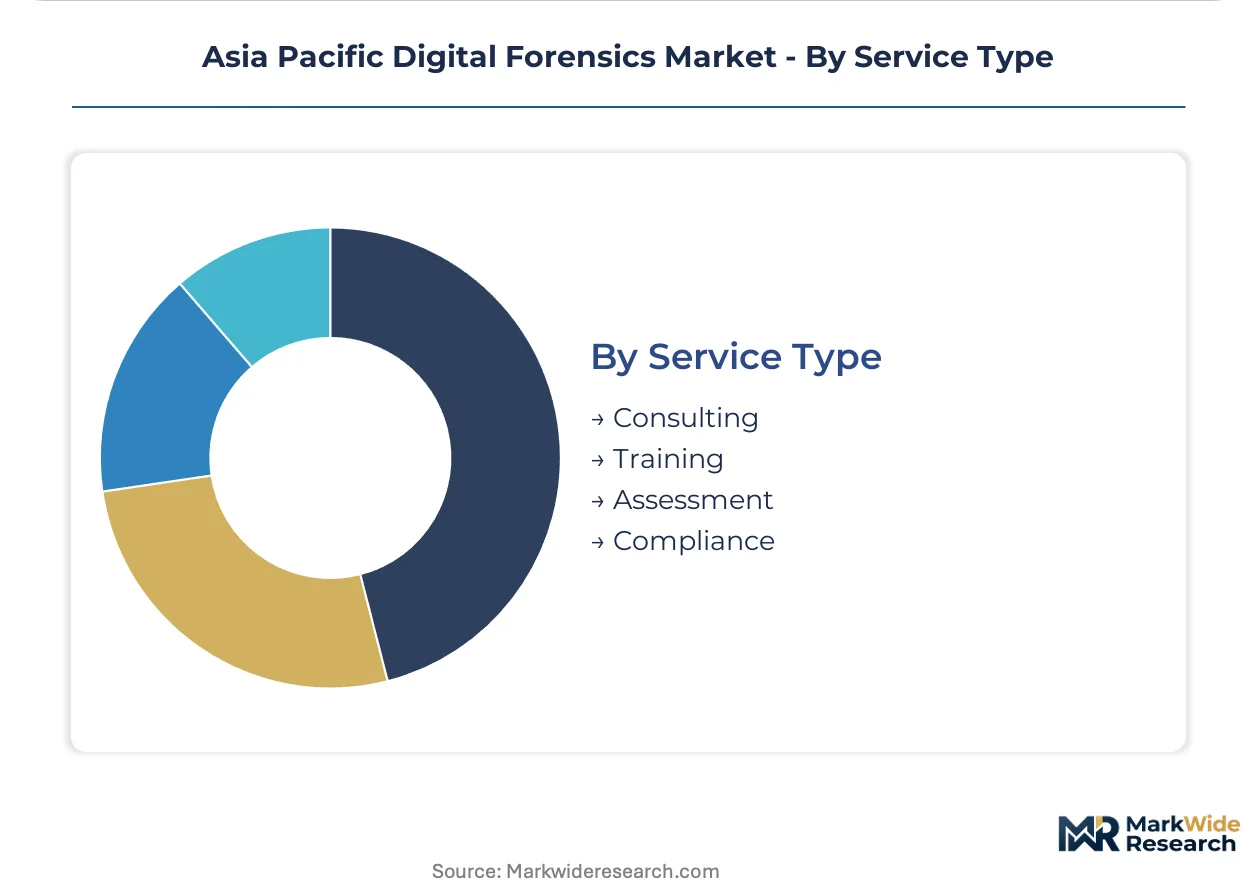
Service Type:
Customer type stratification separates recurring compliance subscription models from discrete project-based engagements. Assessment and compliance services align with mandatory readiness audits, while consulting and training address capability gaps in underpenetrated markets.
- Compliance:Mandatory forensic readiness assessments under India's CERT-In directives and Australia's critical infrastructure frameworks create recurring revenue pools. Procurement concentrates in energy, telecommunications, and financial services verticals.
- Consulting:Incident response retainer agreements and digital evidence unit design services target enterprises building in-house capabilities across Indonesia and Vietnam.
- Training:Forensic examiner certification programs lag behind throughput requirements, creating capability-building demand from Australian federal and Indian state police academies.
- Assessment:Pre-incident forensic maturity evaluations support cyber insurance underwriting and regulatory preparedness across Singapore and Hong Kong regional headquarters.
Compliance captures the recurring revenue base. Consulting shows the steepest expansion trajectory as enterprise capability investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in digital forensics services favor net-importing jurisdictions across Asia Pacific, with Australia and Singapore serving as regional service hubs while India and Vietnam build domestic capability to reduce foreign dependency. Trade in forensic hardware and cloud-native platforms concentrates through Singapore's data center corridor. Cross-border evidence transfer protocols remain the primary friction point in regional service flows.
China
Tier-one cities including Beijing, Shanghai, and Shenzhen drive enterprise-grade forensic procurement under state-backed cybersecurity mandates. GB standards for data classification segment certification requirements across national procurement channels. Yangtze River Delta manufacturing clusters deploy database forensics for ERP integrity verification.
India
Electronics manufacturing incentives under the PLI scheme accelerate data center construction requiring forensic-ready infrastructure. CERT-In directives mandate forensic readiness for critical infrastructure operators with compressed incident reporting timelines. Mumbai and Bengaluru financial services operators invest in dedicated digital evidence units.
Japan
Hybrid cloud-native forensic architectures displace traditional on-premise deployments across financial services and critical infrastructure. METI cybersecurity guidelines segment product certification requirements distinct from regional standards. Tokyo and Osaka enterprise clusters compress hardware refresh cycles through subscription-based service models.
Australia
Federal and state law enforcement agencies procure integrated hardware-software field kits under national security frameworks. TGA-aligned cybersecurity mandates expand compliance service demand for critical infrastructure operators. Sydney and Melbourne concentrate litigation support and discovery services as regional dispute resolution hubs.
Vietnam
Data localization mandates under new cybersecurity laws require domestic evidence storage infrastructure. Banking and telecommunications sectors lack mature forensic capabilities, creating first-mover advantages for cloud-native service providers. Ho Chi Minh City and Hanoi stimulate local forensic infrastructure investment.
Asia Pacific Digital Forensics Market Competitive Environment
Listed leaders compete with private specialists across certification tier and deployment model dimensions, producing a bifurcated structure where premium certified providers serve government contracts while volume consultancies target corporate compliance budgets. The vendor base stratifies around three archetypes: mobile extraction specialists, hardware-software integrators, and cloud-native platform providers. Dominant competitive moves include M&A for capability consolidation and strategic partnerships for hybrid deployment certification.
Among mobile-focused specialists, Cellebrite and MSAB Inc. exemplify the premium-tier archetype through law enforcement field kit integration. IBM Corporation occupies a position within the cloud-native platform tier, extending hybrid architectures across enterprise environments. These three anchors represent distinct competitive vectors: device-centric extraction, integrated hardware-software bundling, and distributed evidence repository analysis.
| Leading Market Players |
|---|
| Paraben Corporation |
| FireEye Inc. |
| MSAB Inc. |
| IBM Corporation |
| Cisco Systems Inc. |
| Cellebrite |
| OpenText |
| Oxygen Forensics Inc. |
| SecureWorks Inc. |
| Others |
Value Chain & Pricing Dynamics
Cloud-native forensic platforms displacing on-premise hardware bundles simultaneously redistribute supply geography toward Singapore data center corridors and compress pricing premiums historically attached to physical field kit certification tiers.
Pricing Analysis
Law enforcement agencies anchor pricing structures around bundled hardware-software subscription contracts under national security procurement frameworks. Three-tier pricing stratifies across certified forensic laboratory services, standard enterprise incident response retainers, and volume-oriented compliance assessments. Cost compression in the mid-tier corporate segment intensifies as managed service providers from India and Vietnam compete on examiner labor arbitrage. Banking and telecommunications operators in Jakarta and Ho Chi Minh City exhibit highest price sensitivity, while Australian federal agencies demonstrate lowest sensitivity due to operational standardization mandates.
Supply Chain Analysis
Inventory lead times for mobile extraction hardware extend twelve to eighteen weeks as semiconductor component shortages persist across Taiwan, South Korea, and Japan manufacturing nodes. Forensic software licensing draws from cloud infrastructure provisioned through Singapore and Hong Kong data center clusters, with encryption chipset supply anchored in Taiwan and South Korea foundries. Single-source vulnerability concentrates in advanced node semiconductor fabrication for AI-augmented analysis accelerators. Distribution runs through direct national security procurement channels in Australia and India, supplemented by regional value-added reseller networks serving Southeast Asian corporate markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where certification moats deepen through divergent national encryption access policies and incompatible procurement standards across China, Japan, and Australia.
For Market Incumbents: Consolidate through acquisition of AI-augmented analysis specialists to address encrypted device backlogs overwhelming Indian and Southeast Asian law enforcement units. Deepen backward integration into domestic cloud infrastructure provision in Vietnam and Indonesia to satisfy data localization mandates before foreign competitors establish operational presence. Certification investment in China's GB standards and Japan's METI guidelines preserves access to segmented national procurement channels. For New Entrants and Emerging Players: Managed forensic services for Indonesia's banking sector represents the most penetrable white-space target, as domestic institutions lack mature in-house digital evidence capabilities under new regulatory pressure. Cloud-native incident response retainers targeting Vietnamese telecommunications operators exploit data localization requirements that disadvantage legacy on-premise vendors. Go-to-market execution should prioritize channel partnerships with regional cyber insurance underwriters in Singapore and Hong Kong to embed forensic readiness assessments within policy procurement workflows. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platform providers with hybrid cloud certification spanning Japan and South Korea enterprise environments. Long-term viability hinges on sustained regulatory fragmentation that protects incumbent certification investments across national procurement channels. Acquisition targets should demonstrate established law enforcement field kit deployments combined with AI-augmented analysis roadmaps. The signal to watch is convergence between Australia's TGA-aligned frameworks and India's CERT-In directives, which would compress first-mover advantages currently enjoyed by geography-specific specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Certification Investment | Enables simultaneous access to Japan METI-regulated financial services and South Korean critical infrastructure procurement channels. |
| AI-Augmented Analysis Acquisition | Addresses encrypted messaging backlogs overwhelming Indian state police and Southeast Asian federal agencies. |
| Domestic Data Center Buildout | Satisfies Vietnam cybersecurity law mandates requiring local evidence storage infrastructure for banking operators. |
| Law Enforcement Field Kit Integration | Captures Australian federal and state contracts under operational standardization procurement frameworks. |
| Regional Channel Partnership | Embeds forensic readiness assessments within Singapore cyber insurance underwriting workflows for multinational corporate clients. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and hyperscaler infrastructure disclosures across the analysis window. Primary interviews engaged forensic laboratory directors, national security procurement officers, cyber insurance underwriters, and cloud platform engineering leads. Secondary validation drew from CERT-In directive documentation, Australia's TGA cybersecurity framework publications, Japan METI guideline releases, and China GB standard certification registries. Bottom-up segment sizing triangulated against top-down macroeconomic absorption models.
Segmentation dimensions modeled include technology deployment architecture, end-user procurement authority tier, service delivery model, and national regulatory compliance cluster across the projection horizon. CAGRs derived from exponential smoothing of annualized adoption curves with elasticity adjustments for mandatory breach notification timeline compressions. Industry-specific forecast inputs incorporated data center construction permits under India's PLI scheme and smartphone penetration trajectories across Southeast Asian markets.
Material uncertainties — encryption policy reversals, cross-border evidence treaty negotiations, and semiconductor supply disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision contingent on regulatory divergence or convergence between national procurement frameworks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Global Container and Kubernetes Security Market
Cybersecurity
Botnet Detection Market
Cybersecurity
Thailand Cybersecurity Market
Cybersecurity
Endpoint Protection Platforms (EPP) Market
Cybersecurity
Cloud Access Security Broker Market
Cybersecurity
Data Security Market
Cybersecurity
Italy Cybersecurity Market
Cybersecurity
Peru Cybersecurity Market
Cybersecurity
Global Content Disarm and Reconstruction Market
Cybersecurity
Hungary Cybersecurity Market
Cybersecurity
LAMEA Deception Technology Market
Cybersecurity
Global Database Security Market
Cybersecurity
Cloud Security in Banking Market
Cybersecurity
Singapore Cybersecurity Market
Cybersecurity
Anti-Malware Market
Cybersecurity
Africa Cybersecurity Market