
 Spray Dried Food Market | 2026-2036
Spray Dried Food Market Size, Share, and Industry Trends Forecast 2026-2036
Spray Dried Food Market Intelligence
FSSC 22000 certification is reorganizing the competitive landscape by setting stringent food safety management system requirements for suppliers. This standard creates a significant barrier to entry for smaller, less-capitalized firms. Ingredion Incorporated leverages its extensive portfolio of starch-based carriers to meet these standards for diverse applications. Nestlé S.A. sustains its market position through large-scale production capabilities and brand recognition in infant nutrition, a segment with exceptionally high quality demands.
Spray dried food is a powder produced by rapidly drying a liquid or slurry with a hot gas. The process involves atomizing the feed into a spray of droplets and contacting it with hot air, which controls final particle size and moisture content. Its primary industrial purpose is to convert perishable liquid foods into stable, easily transportable powders with extended shelf life. Dairy products represent a mature and high-volume product type, while fruit powders are experiencing rapid uptake within the healthcare end-user category for nutritional supplements.
Food safety regulations from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) govern allowable additives and processing aids. In China, the State Administration for Market Regulation (SAMR) enforces GB standards for infant formula ingredients, a key application. These rules directly influence ingredient sourcing and market access for producers. Future competitive advantage will depend on balancing the capital investment in advanced multi-stage drying technology against customer price sensitivity.
Market Dynamics
The central structural force in the spray dried food market is the tension between capital investment in advanced multi-stage drying technologies and persistent customer price sensitivity. This dynamic forces producers to balance the pursuit of higher nutritional retention with the cost pressures of commodity applications.
Growth Catalysts
- Multi-Stage Drying Technology:Innovations in drying processes enable higher retention of vitamins and bioactive compounds, meeting demand from the healthcare and nutraceutical sectors for stable, high-potency powders.
- Chinese Infant Formula Demand:China's expanding infant nutrition industry, governed by strict GB standards, creates sustained, high-volume demand for spray dried dairy and protein ingredients that meet exacting quality specifications.
- Nutritional Supplement Uptake:The expanding use of spray dried fruit and vegetable powders within nutritional supplements and functional foods provides a high-growth avenue, particularly in North American and European markets.
Market Restraints
- Energy Cost Volatility:The spray drying process is energy-intensive, exposing producers to significant margin pressure from fluctuations in natural gas and electricity prices, which are a major component of operational costs.
- Heat Degradation of Bioactives:Despite technological advancements, the inherent heat of the process can still degrade sensitive compounds like certain enzymes and probiotics, limiting applications for highly delicate ingredients.
- Regulatory Compliance Burden:Adhering to diverse international food safety standards from bodies like the FDA and EFSA, especially concerning additives and allergen cross-contamination, adds complexity and cost for producers.
Strategic Opportunities
- Plant-Based Alternatives:The growing consumer preference for vegan and vegetarian diets creates a significant opportunity for spray dried plant-based protein isolates and milk alternative powders from sources like peas, soy, and oats.
- Microencapsulation Integration:Combining spray drying with microencapsulation techniques offers a pathway to protect sensitive ingredients like omega-3 fatty acids and probiotics, opening new functional food and medical food applications.
- Southeast Asian Market Penetration:Rising disposable incomes and urbanization in Southeast Asian countries create new demand for convenient, shelf-stable food products, including fortified milk powders, coffee creamers, and soup mixes.
Industry Challenges
- Capital Expenditure for Advanced Systems:Upgrading to multi-stage drying systems that comply with food safety certifications like FSSC 22000 requires substantial capital investment, creating a high barrier to entry and expansion.
- Skilled Operator Scarcity:Achieving consistent product quality, including precise moisture content and particle size distribution, demands a workforce with specialized technical skills in operating and maintaining complex drying equipment.
- Raw Material Sourcing Consistency:Securing a year-round supply of liquid raw materials with consistent quality, particularly for seasonal items like fruits, presents a significant logistical challenge for maintaining continuous production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spray Dried Food Market |
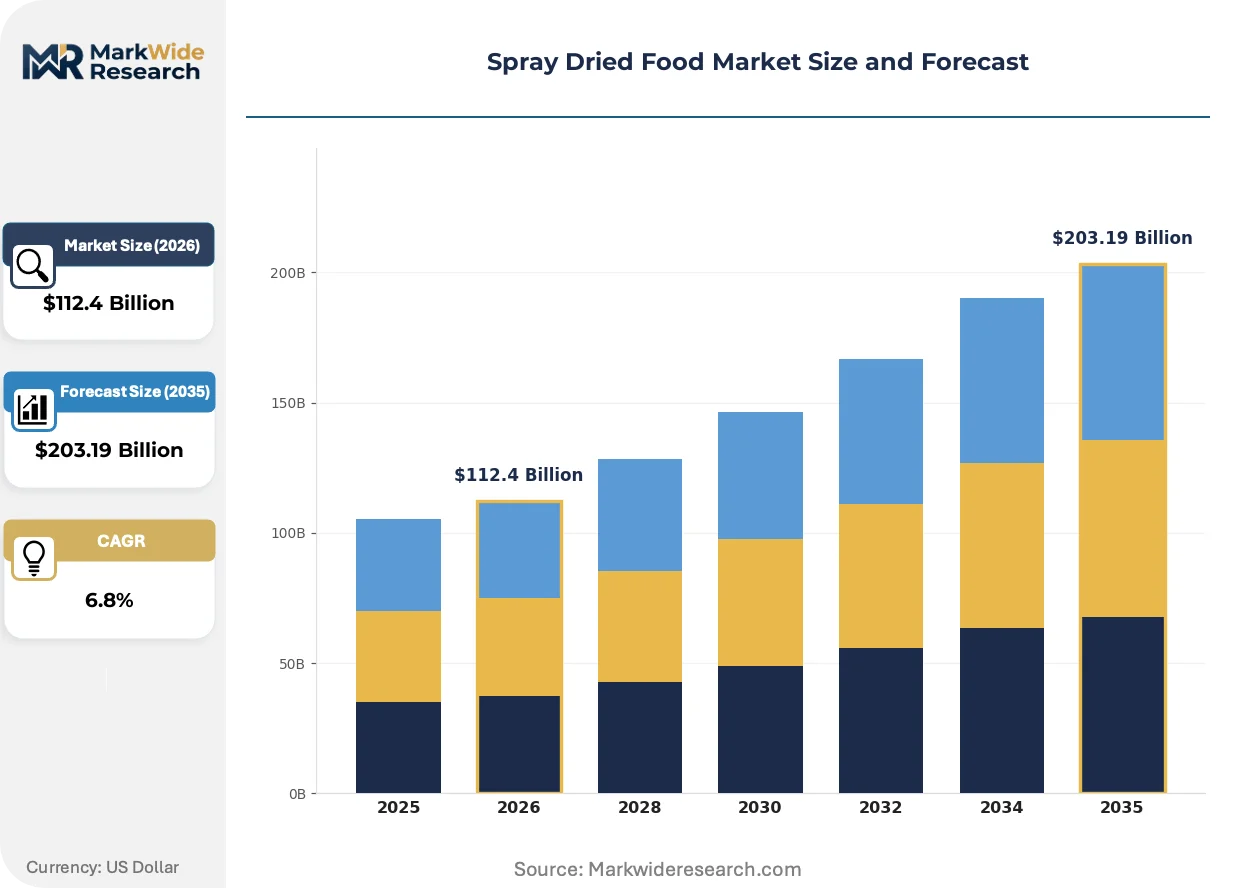
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Protein End User: Food Industry, Healthcare, Retail, Catering Packaging Type: Bags, Tins, Pouches, Bottles Technology: Single-Stage, Multi-Stage, Continuous, Batch |
| Companies Covered | Ingredion Incorporated, Sensient Technologies Corporation, Nestlé S.A., Glanbia plc, Tate & Lyle PLC, Kerry Group plc, Cargill, Incorporated, FrieslandCampina, Fonterra Co-operative Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spray Dried Food Market Strategic Shifts & Innovations
The market is evolving beyond simple preservation, with innovation now centered on enhancing the functional and nutritional value of powders. This shift is driven by demand from end-users for ingredients that actively contribute to the performance and health profile of the final product.
Multi-stage spray drying is an advanced process allowing for precise temperature and residence time control in different drying zones. Nutraceutical and infant formula manufacturers are rapidly adopting this method to better preserve heat-sensitive vitamins and bioactive compounds. This advanced technique is displacing conventional single-stage, high-heat drying, which often results in greater degradation of a product's nutritional profile.
The increasing implementation of FSSC 22000 as a globally recognized food safety management system is setting a higher bar for suppliers. This standard mandates rigorous hazard analysis, traceability, and validated process controls, compelling investment in hygienic equipment and documented procedures. The dairy and infant nutrition segments are most impacted, as large-scale buyers now frequently require this certification as a prerequisite for supply chain partnership.
A notable change in buyer behavior is the prioritization of functional powder characteristics, such as solubility and flowability, over simple cost-per-unit metrics. This focus on performance is disrupting traditional commodity procurement models, creating an advantage for suppliers offering technical, application-specific support. The trend is most prominent within the functional beverage and prepared food sectors, where powder performance directly influences consumer experience and manufacturing efficiency.
Spray Dried Food Market Segmentation
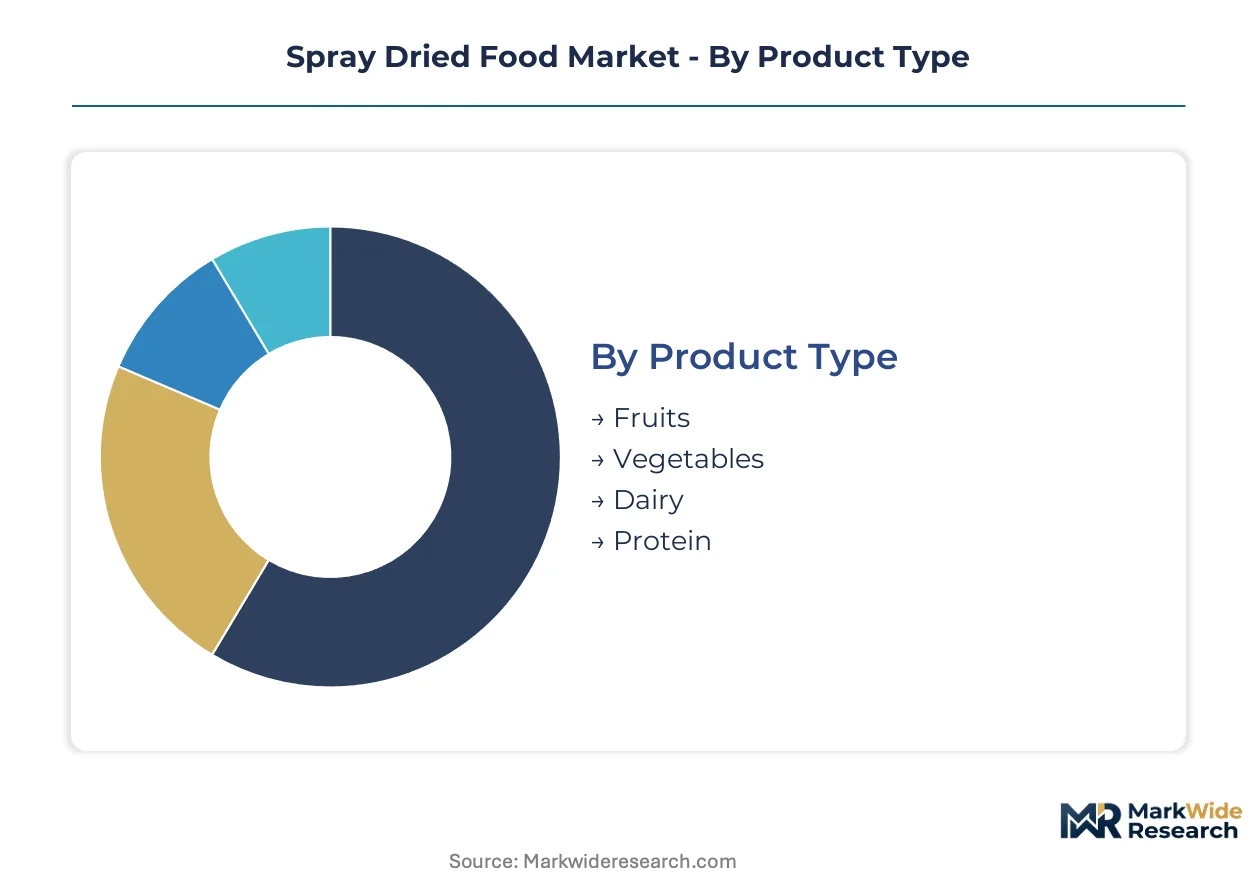
Understanding the spray dried food market's segmentation reveals the diverse applications and technological nuances driving its expansion. This granular analysis distinguishes between product types, end-user industries, packaging solutions, and underlying drying technologies. Each segment presents unique growth dynamics and competitive landscapes for producers.
Product Type:
Product type segmentation highlights how certain ingredients dominate domestic consumption while others are primarily export-driven commodities across global supply chains.
- Dairy:This segment includes milk powders, whey protein concentrates, and cheese powders, integral for their nutritional profile and functional properties. Demand concentrates in China for infant formula production, where strict GB standards necessitate high-quality, stable ingredients.
- Protein:Encompasses plant-based proteins like pea and soy, alongside animal-derived proteins such as collagen and egg white powders. Demand for these highly functional powders is accelerating in North America and Europe, driven by the expansion of sports nutrition and vegan food trends.
- Fruits:This category includes powders from berries, citrus, and tropical fruits, valued for natural flavors and bioactive compounds in health supplements.
- Vegetables:Comprises powders from ingredients like spinach, carrot, and beetroot, primarily utilized in savory snacks and nutritional blends for their concentrated nutrients.
Dairy holds the largest share; momentum sits with Protein.
End User:
End-user segmentation reflects varying price sensitivities and quality requirements, from commodity-grade ingredients to highly specialized, premium applications.
- Food Industry:This broad segment includes manufacturers of bakery, confectionery, convenience foods, and beverages, requiring spray-dried ingredients for flavor, texture, and shelf-life extension. Procurement within this segment is highly sensitive to ingredient cost and processing efficiency.
- Healthcare:Encompasses producers of nutraceuticals, medical foods, and pharmaceutical excipients, where ingredient purity, stability, and controlled release are paramount. Demand is particularly strong in Germany and the United States for high-value bioactive compounds and protein isolates.
- Retail:Involves direct-to-consumer products such as instant coffee, powdered drinks, and soup mixes, prioritizing convenience and brand recognition.
- Catering:Utilizes spray-dried ingredients for bulk food preparation in institutions, restaurants, and airlines, focusing on operational efficiency and consistent quality.
The Food Industry represents the largest volume consumption; Healthcare is expanding most quickly due to specialized nutritional demands.
Packaging Type:
Packaging type segmentation is driven by product stability requirements, distribution logistics, and consumer convenience across diverse application scenarios.
- Bags:Primarily large format, multi-layer bags used for bulk industrial ingredients like dairy powders and plant proteins, optimizing for cost-effectiveness and protection during transit. This packaging type dominates bulk procurement in manufacturing facilities across India and Brazil.
- Pouches:Offer flexibility and convenience, commonly used for consumer-ready products such as instant coffee, powdered beverages, and infant formula refills. Their lightweight nature and resealable options appeal to consumers in Southeast Asian markets.
- Tins:Provide robust protection against moisture and light, favored for premium infant formula and specialized nutritional supplements in markets like Japan.
- Bottles:Utilized for smaller quantities of high-value ingredients or functional powders, offering consumer-friendly dispensing and extended shelf life for retail.
Bags account for the majority of industrial volume; Pouches are rapidly gaining share in retail segments.
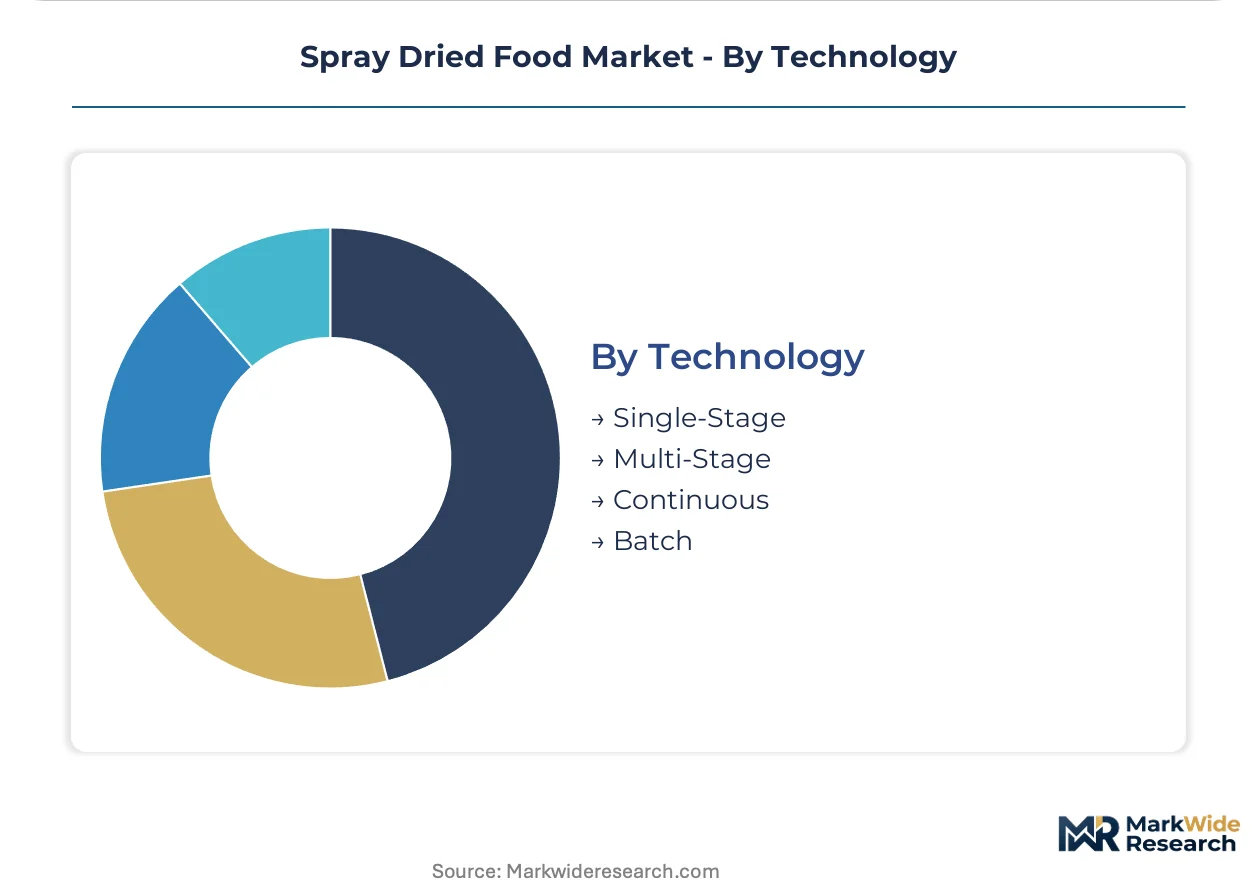
Technology:
Technology segmentation reflects the market's evolution from mature, high-volume processes to advanced methods focused on preserving sensitive compounds and enhancing product functionality.
- Multi-Stage:Employs sequential drying zones with precise temperature control, minimizing thermal degradation of heat-sensitive components like vitamins and probiotics. Manufacturers in Switzerland and the Netherlands adopt this for high-value nutraceutical ingredients.
- Single-Stage:A traditional, simpler process involving one drying chamber, suitable for robust, less heat-sensitive products like commodity dairy powders. This technology remains prevalent in large-scale production facilities in New Zealand and Ireland due to its cost efficiency.
- Continuous:Characterized by uninterrupted material flow through the drying system, optimizing throughput for high-volume, consistent product streams.
- Batch:Involves processing discrete quantities of material, offering flexibility for smaller production runs or specialized product formulations with strict control requirements.
Single-Stage technology maintains a dominant installed base; Multi-Stage systems are experiencing the steepest expansion trajectory for performance-critical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food safety regulations from bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) significantly influence market access and ingredient sourcing. These standards, coupled with national policies promoting nutritional health, shape regional investment in advanced processing technologies. This creates distinct market dynamics across key geographies.
China
China's expanding infant formula and convenience food industries drive substantial demand for spray dried dairy and protein ingredients. The State Administration for Market Regulation (SAMR) enforces stringent GB standards for these products, requiring high-quality inputs. Major food processing hubs in Shanghai and Guangzhou actively seek ingredients meeting these exacting specifications.
United States
The United States market exhibits strong uptake in the healthcare sector for nutritional supplements and functional foods. FDA regulations govern allowable additives and processing aids, ensuring product safety and efficacy. Food technology clusters in California and the Midwest are centers for innovation in plant-based protein powders and bioactive ingredient development.
Germany
Germany represents a significant market for spray dried ingredients within the healthcare end-user category, particularly for nutraceuticals and medical foods. European Food Safety Authority (EFSA) guidelines dictate ingredient purity and stability requirements. Advanced food processing facilities in Bavaria and North Rhine-Westphalia focus on high-value, performance-critical applications.
New Zealand
New Zealand maintains a dominant position in commodity dairy powders, leveraging its large-scale production capabilities. The country's robust food safety standards, often aligned with global certifications, support its export-oriented dairy industry. The Waikato and Canterbury regions are key centers for large-scale spray drying operations, primarily for milk and whey products.
India
India's food manufacturing sector utilizes bulk industrial ingredients, with demand for spray dried products concentrated in cost-effective solutions. The Food Safety and Standards Authority of India (FSSAI) regulates food product quality and safety across the diverse market. Industrial food hubs in Maharashtra and Gujarat are significant consumers of large-format bagged ingredients.
Spray Dried Food Market Key Industry Players
Listed leaders compete with private specialists across advanced drying technologies and global distribution networks. The market structure features large-scale commodity producers alongside specialized ingredient suppliers and niche technology providers. Companies primarily engage in capacity expansion and strategic partnerships to secure raw material supply and broaden their product portfolios.
At the scale-driven end, Nestlé S.A. anchors its position through extensive brand recognition in infant nutrition, a segment demanding exceptionally high quality. Ingredion Incorporated represents a key player leveraging its extensive portfolio of starch-based carriers to meet diverse application requirements. Fonterra Co-operative Group Limited, a New Zealand-based cooperative, exemplifies a major producer of dairy powders, supplying global markets with high-volume ingredients.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Sensient Technologies Corporation |
| Nestlé S.A. |
| Glanbia plc |
| Tate & Lyle PLC |
| Kerry Group plc |
| Cargill, Incorporated |
| FrieslandCampina |
| Fonterra Co-operative Group Limited |
| Others |
Cost & Logistics Intelligence
Capacity utilization in spray drying facilities shapes supply concentration and influences price floors for commodity ingredients. This dynamic forces producers to balance high capital expenditure with persistent customer price sensitivity across diverse applications.
Pricing Analysis
Certification level like FSSC 22000 creates the primary spread in spray dried food pricing. Contract-based long-term offtake agreements dominate for bulk ingredients, while value-based pricing applies to specialized nutraceutical powders. Price differentiation also stems from multi-stage drying technology investment and application-specific functional performance. Pricing softness affects commodity dairy products due to large-scale production in New Zealand. The Food Industry exhibits the highest price sensitivity, contrasting with the Healthcare sector's lower sensitivity for critical ingredients.
Supply Chain Analysis
Just-in-time inventory strategies are common for high-volume dairy powders, while specialized ingredients often require strategic stockpiles due to lead times for specific raw materials. Geographic supply concentrations for spray dried ingredients draw from New Zealand for dairy, and China for infant formula protein inputs. Key raw material dependencies include liquid milk, fresh fruits, and specific plant-based proteins. Energy cost volatility poses a structural risk across the entire production chain. Distribution runs through bulk industrial channels for manufacturers and increasingly through flexible pouches for retail consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spray dried food market presents an early-cycle expansion story, justified by the accelerating uptake of nutritional supplements and functional foods. This growth trajectory highlights opportunities for strategic positioning across the value chain.
For Market Incumbents: Compound existing advantages by investing further in advanced multi-stage drying technology to preserve sensitive bioactives. This move counters the threat of heat degradation of delicate compounds, which limits application scope. Reinforce market position through continuous FSSC 22000 certification upgrades and specialized operator training to ensure consistent product quality and safety.
For New Entrants and Emerging Players: Certification fast-tracking via FSSC 22000 compliance offers a pathway to differentiate quickly. Target the rapidly expanding plant-based protein powder segment, leveraging novel raw material sources like oats or peas. Focus on microencapsulation integration for sensitive ingredients, opening new functional food applications. Penetrate Southeast Asian markets with convenient, shelf-stable fortified milk powders, using local distribution partnerships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized ingredient providers with proprietary drying processes. The long-term viability of this market, spanning a 5-10 year window, hinges on innovation in nutritional retention and functional characteristics. Target acquisition archetypes include agile technology firms and regional producers with strong regulatory compliance. A signal to watch is the increasing M&A activity in plant-based and microencapsulated ingredient sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Stage Drying Investment | Enhances retention of vitamins and bioactive compounds, meeting demand for high-potency nutraceuticals. |
| FSSC 22000 Certification Upgrade | Secures market access and supply chain partnerships, especially in infant nutrition segments. |
| Plant-Based Protein Portfolio Expansion | Captures growing consumer preference for vegan and vegetarian dietary alternatives. |
| Microencapsulation Technology Integration | Protects sensitive ingredients like omega-3s, opening new functional food applications. |
| Southeast Asian Market Entry | Addresses rising demand for convenient, shelf-stable food products in urbanizing populations. |
Research Approach
A spread of perspectives from R&D directors, procurement leads, food safety officers, and plant managers converged on the working assumptions for the spray dried food market. This involved extensive primary interviews with industry stakeholders, validated against secondary data. Key secondary sources included FDA regulations, EFSA guidelines, SAMR GB standards, and relevant industry association reports. Bottom-up and top-down triangulation ensured data consistency and market sizing accuracy.
Segmentation dimensions modeled included product type, end-user, packaging type, technology, and regional regulatory frameworks. The analytical framework projected market trends across the analysis window, with CAGRs derived from historical growth patterns and anticipated shifts in demand drivers. Key industry-specific forecast inputs included population growth in China and per capita consumption of convenience foods in Southeast Asia.
Underlying assumptions cover stable regulatory environments and consistent raw material availability, with deviation risk concentrated in energy cost volatility and unforeseen food safety mandates. Forecasts reflect these assumptions. Revision becomes warranted when new multi-stage drying technologies significantly alter production costs or consumer preferences for functional foods shift dramatically.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Aseptic Processing Market
Food Processing Equipment
Countertop Blast Chiller Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Freeze-Drying Equipment Market
Food Processing Equipment
India Household Flour Milling Machines Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Industrial Planetary Mixers Market
Food Processing Equipment
Food-Grade Mixing Tank Market
Food Processing Equipment
Pea Protein Processing Equipment Market
Food Processing Equipment
Ice Cream Machine Market
Food Processing Equipment
Oven Market
Food Processing Equipment
Fluidized Bed Dryer Market
Food Processing Equipment
Exhaust Hood Filters and Cleaning Kits Market
Food Processing Equipment
Global Food Dehydrators Market