
 Saudi Arabia Mattress Market | 2026-2036
Saudi Arabia Mattress Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Mattress Market Analytics
Aftermarket service revenue including mattress recycling and refurbishment is reconfiguring margin pools away from pure product sales toward circular economy models. Sealy leverages its global manufacturing scale to anchor premium positioning in Saudi retail channels. Intercoil competes through localized production and regional distribution control across Gulf markets. AI-Mutlaq specializes in traditional bedding formats while extending into hospitality supply contracts for new hotel developments.
A mattress is a padded, fabric-encased sleep support system constructed with spring coils, foam layers, or latex cores designed to distribute body weight and maintain spinal alignment during rest; specifications include density ratings, coil counts, and firmness indices measured in indentation load deflection. Memory foam and hybrid constructions now lead residential replacement cycles as consumers prioritize pressure relief and temperature regulation. The hospitality application segment represents the fastest-growing demand pool tied to Saudi Vision 2030 tourism infrastructure. Economy and mid-range price tiers dominate volume, while luxury and premium tiers capture disproportionate margin concentration in specialty store and online channels.
SFDA oversees product safety and material hygiene standards for mattresses sold in Saudi Arabia, while SASO mandates quality certification and labeling compliance under technical regulations for furniture products. The Saudi Building Code, enforced by municipal authorities in Riyadh, Jeddah, and Dammam, specifies fire resistance requirements for hospitality and commercial installations. Stakeholders must monitor evolving sustainability mandates and circular economy regulations as the kingdom advances industrial diversification targets beyond hydrocarbon dependence.
Market Dynamics
Vision 2030 infrastructure deployment is compressing procurement cycles for hospitality-grade sleep systems while SFDA material compliance deadlines force rapid manufacturing retooling across Riyadh-based production clusters.
Growth Catalysts
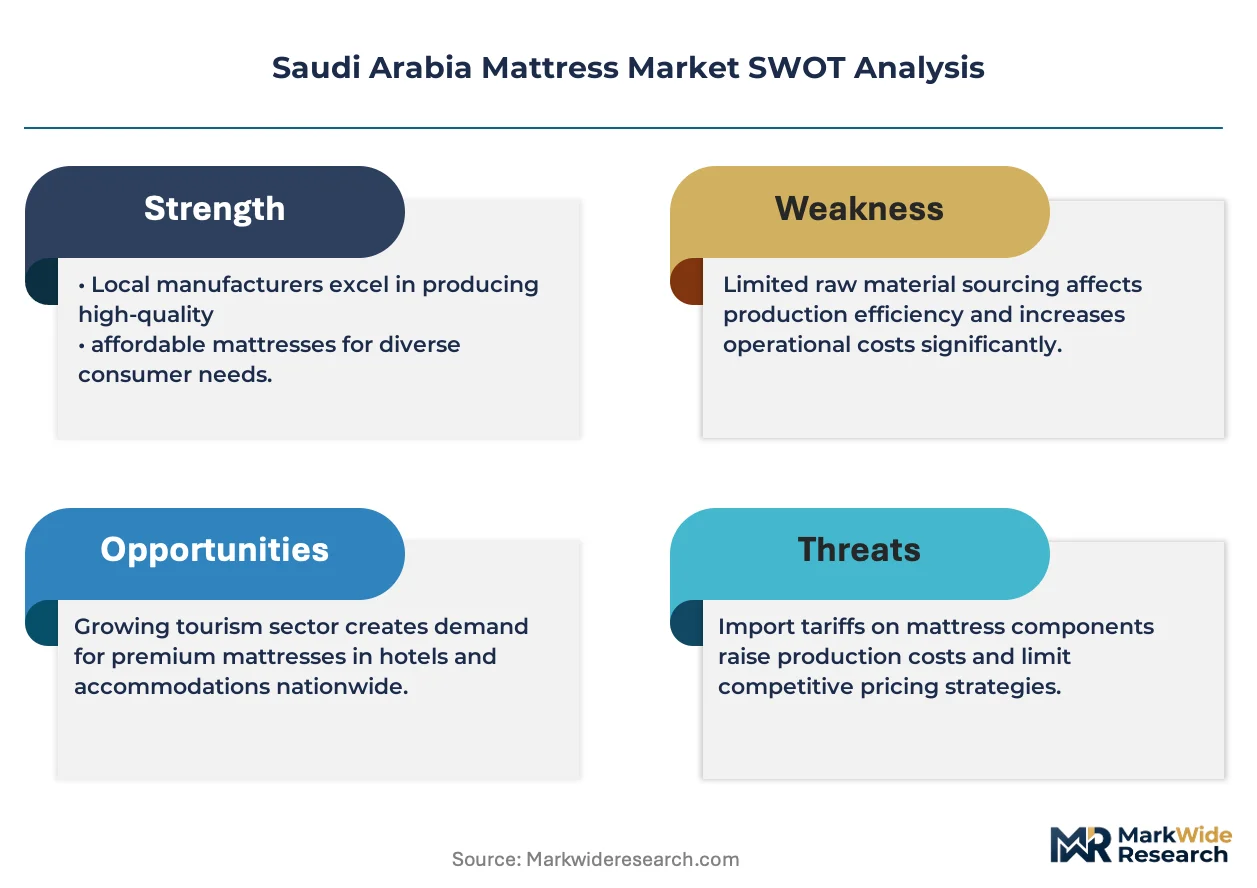
- SFDA Safety Mandates:Stricter foam density and fire-resistance testing protocols are filtering out low-grade imports and elevating certified domestic manufacturers into preferred supplier status for hotel developers.
- Hospitality Construction Pipeline:Giga-project developments across Diriyah, Qiddiya, and the Red Sea coast are generating concentrated demand for fire-rated commercial mattresses with 10-year warranty specifications.
- Polyurethane Recycling Infrastructure:New industrial zones near Dammam are deploying chemical recycling lines that convert post-consumer foam into certified rebonded core material, reducing virgin petrochemical input costs.
Market Restraints
- Petrochemical Feedstock Volatility:TDI and polyether polyol prices fluctuate with crude oil benchmarks, compressing margin predictability for foam-core manufacturers in the Eastern Province.
- Import Concentration Risk:Latex raw material supply clusters in Southeast Asian rubber plantations create 90-day inventory exposure for Saudi producers lacking backward integration into natural rubber cultivation.
- SASO Certification Friction:Extended laboratory testing queues at SASO-accredited facilities delay product launches by 4-6 months for new market entrants.
Strategic Opportunities
- Central Region Residential Density:Riyadh's northern expansion zones and King Salman Park vicinity present underpenetrated demand for smart-temperature mattresses targeting high-income expatriate households.
- AI-Driven Customization Convergence:Integration of pressure-mapping sensors with adjustable base mechanisms enables personalized firmness profiles for chronic pain management applications.
- Direct-to-Consumer Channel Expansion:E-commerce platforms with augmented reality visualization tools are bypassing traditional furniture souk intermediaries in Jeddah's retail corridor.
Industry Challenges
- Technical Workforce Scarcity:Foam formulation chemistry and CNC cutting machine operation skills remain concentrated among expatriate technicians, constraining production scaling for Saudi-owned facilities.
- SFDA Compliance Timeline Compression:Accelerated regulatory update cycles force manufacturers to maintain parallel inventory batches—pre-certified and post-certified—tying up working capital.
- Legacy ERP Integration Friction:Family-owned distributors in Makkah and Madinah resist cloud-based inventory management adoption, fragmenting demand forecasting accuracy for upstream suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Mattress Market |
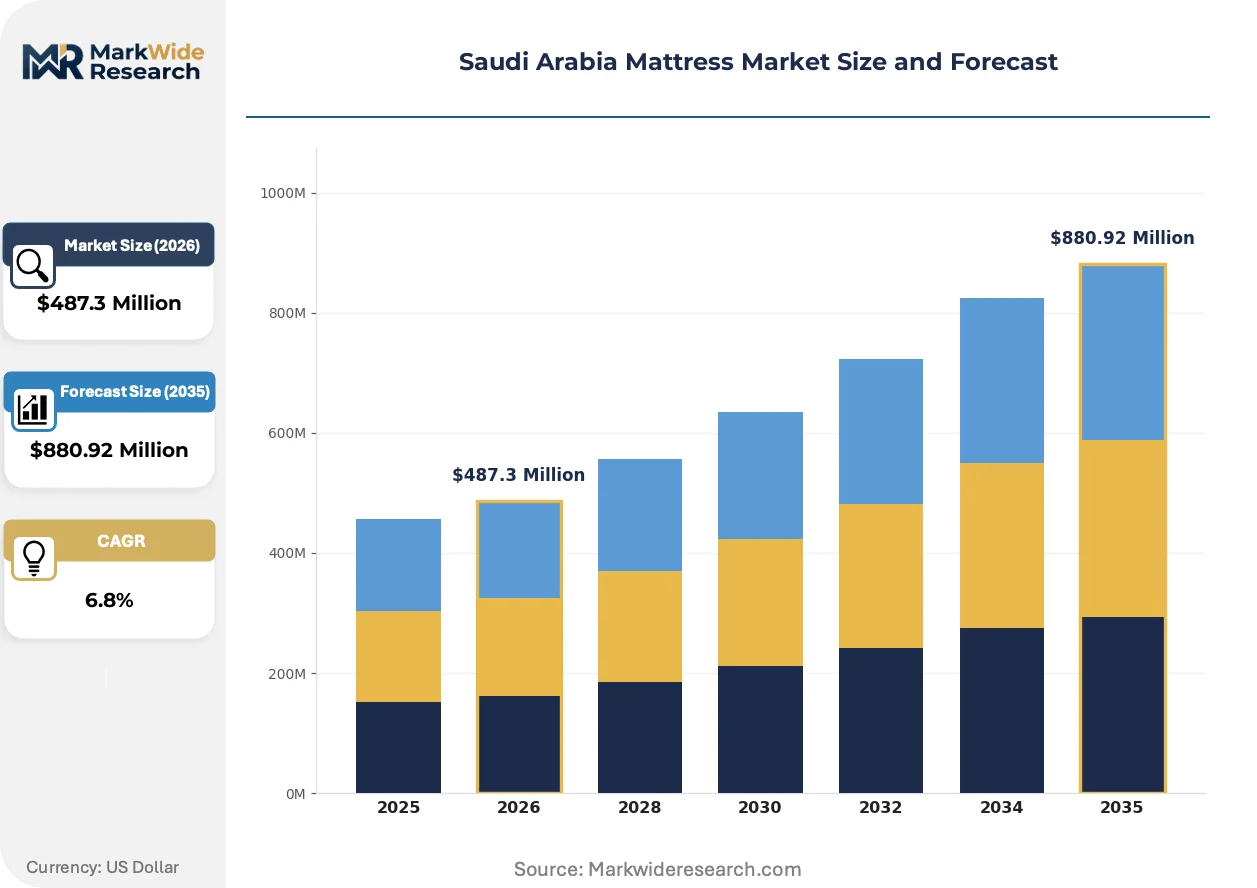
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Innerspring, Memory Foam, Latex, Hybrid Application: Residential, Hospitality, Healthcare, Commercial Distribution Channel: Online, Supermarkets, Specialty Stores, Warehouses Price Tier: Economy, Mid-Range, Luxury, Premium |
| Companies Covered | Sealy, ALMazro, SleepHigh, AI-Mutlaq, AI Rajhi Group, Intercoil, Serta, Tempur, King Koil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Mattress Market Evolving Landscape
Sleep technology convergence with Saudi wellness priorities is reconfiguring product specifications and procurement criteria across residential and commercial verticals.
Pressure-mapping sensor arrays embedded within hybrid coil-foam constructions are digitizing sleep quality assessment for hospitality procurement teams. Marriott and Hilton franchise operators in Riyadh and Jeddah now specify real-time occupancy and comfort scoring as contract requirements. This capability is digitizing supplier selection criteria away from static warranty terms toward continuous performance verification.
SFDA's updated Technical Regulation for Furniture Products mandates flame-retardant barrier layers and formaldehyde emission limits aligned with EU REACH Annex XVII standards. Domestic manufacturers must reformulate adhesive systems and source certified barrier fabrics, increasing unit costs but creating competitive moats against uncertified imports. Hospitality procurement departments in Dammam and Khobar are now requiring batch-level compliance documentation as standard contract riders.
Subscription-based mattress refresh programs are displacing outright ownership models among young professional households in Riyadh's Diplomatic Quarter and King Abdullah Financial District. Sleep-as-a-service providers collect, sanitize, and redistribute units across 18-month cycles, compressing traditional 8-10 year replacement intervals. This pattern is most visible in urban Central Region districts where space constraints and mobility preferences favor asset-light consumption.
Saudi Arabia Mattress Market Segmentation
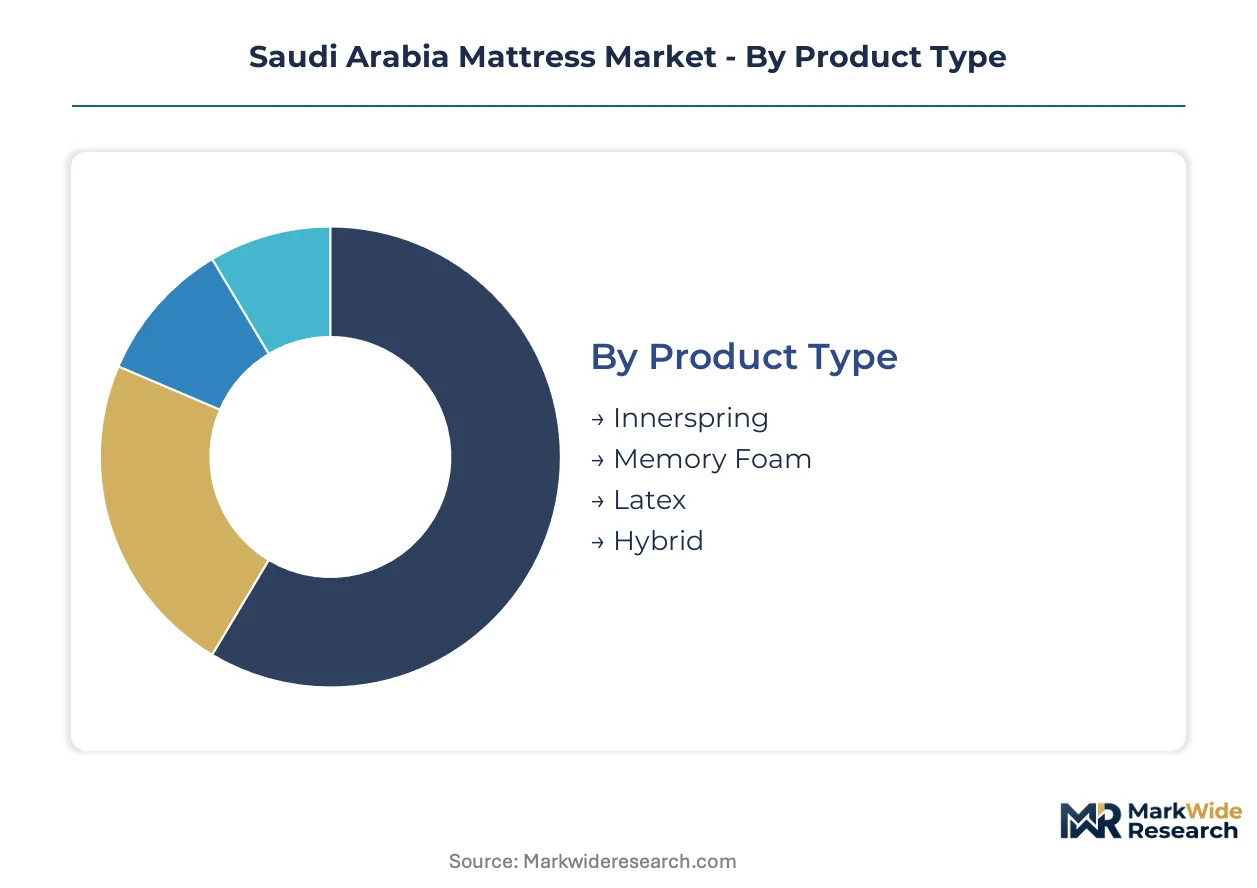
Mattress procurement patterns across Saudi Arabia fragment sharply by end-use requirements and buyer sophistication. SFDA compliance thresholds and Vision 2030 hospitality specifications create divergent technical standards that reshape manufacturing priorities and channel economics.
Product Type:
Construction technology determines performance characteristics, warranty positioning, and manufacturing capital intensity across Saudi production clusters.
- Innerspring:Coil-based support systems with interconnected or pocketed spring arrays deliver proven durability at accessible price points. Riyadh-based manufacturers supply bulk contracts for workforce housing developments and mid-tier hotel properties seeking 7-year replacement cycles.
- Memory Foam:Viscoelastic polyurethane formulations contour to body pressure points while isolating motion transfer. Demand concentrates in King Abdullah Financial District residential towers where expatriate professionals prioritize sleep quality and temperature regulation.
- Latex:Natural or synthetic rubber core constructions offer inherent antimicrobial properties and resilient support. Jeddah's coastal humidity drives preference for breathable, mold-resistant sleep surfaces in villa developments.
- Hybrid:Combined coil and foam layers balance responsiveness with pressure relief. Hospitality procurement teams at Red Sea giga-projects specify hybrid constructions for guest room durability under intensive occupancy rotation.
Innerspring commands the established base. The steepest expansion runs through Hybrid configurations.
Application:
End-use verticals impose distinct certification burdens, volume scales, and replacement cadences on suppliers.
- Residential:Individual household purchases across Riyadh, Jeddah, and Dammam metropolitan zones drive replacement demand tied to real estate transaction cycles. Northern Riyadh expansion corridors and King Salman Park vicinity generate concentrated demand for premium sleep systems.
- Hospitality:Hotel, resort, and serviced apartment procurement requires fire-rated commercial specifications with batch-level SFDA documentation. Qiddiya, Diriyah, and Red Sea Project developments compress procurement timelines for 10-year warranty products.
- Healthcare:Medical-grade pressure redistribution surfaces for hospitals and long-term care facilities. SFDA medical device registration creates elevated compliance barriers versus standard furniture classification.
- Commercial:Corporate housing, student dormitories, and institutional sleeping quarters. Eastern Province industrial zone workforce accommodations prioritize economy-tier bulk procurement with accelerated replacement schedules.
Residential captures volume concentration. Hospitality exhibits the most rapid demand acceleration.
Distribution Channel:
Channel structure determines customer touchpoint economics, inventory carrying costs, and post-sale service attachment rates.
- Online:Direct-to-consumer platforms with augmented reality visualization and compressed delivery windows. Young professional households in Riyadh's Diplomatic Quarter favor digital purchase journeys with 48-hour fulfillment guarantees.
- Supermarkets:Mass-market retail penetration for economy-tier roll-packed products. Hypermarket chains in Jeddah's retail corridor move high-velocity SKUs with minimal sales assistance.
- Specialty Stores:Consultative selling environments with pressure-mapping demonstrations and customization services. Premium and luxury tiers concentrate in Riyadh's northern district showrooms targeting high-net-worth Saudi households.
- Warehouses:Bulk procurement channels for hospitality developers and institutional buyers. Dammam-based logistics hubs service Eastern Province construction projects with direct-to-site delivery coordination.
Specialty stores anchor premium positioning. Online channels demonstrate the sharpest growth trajectory.
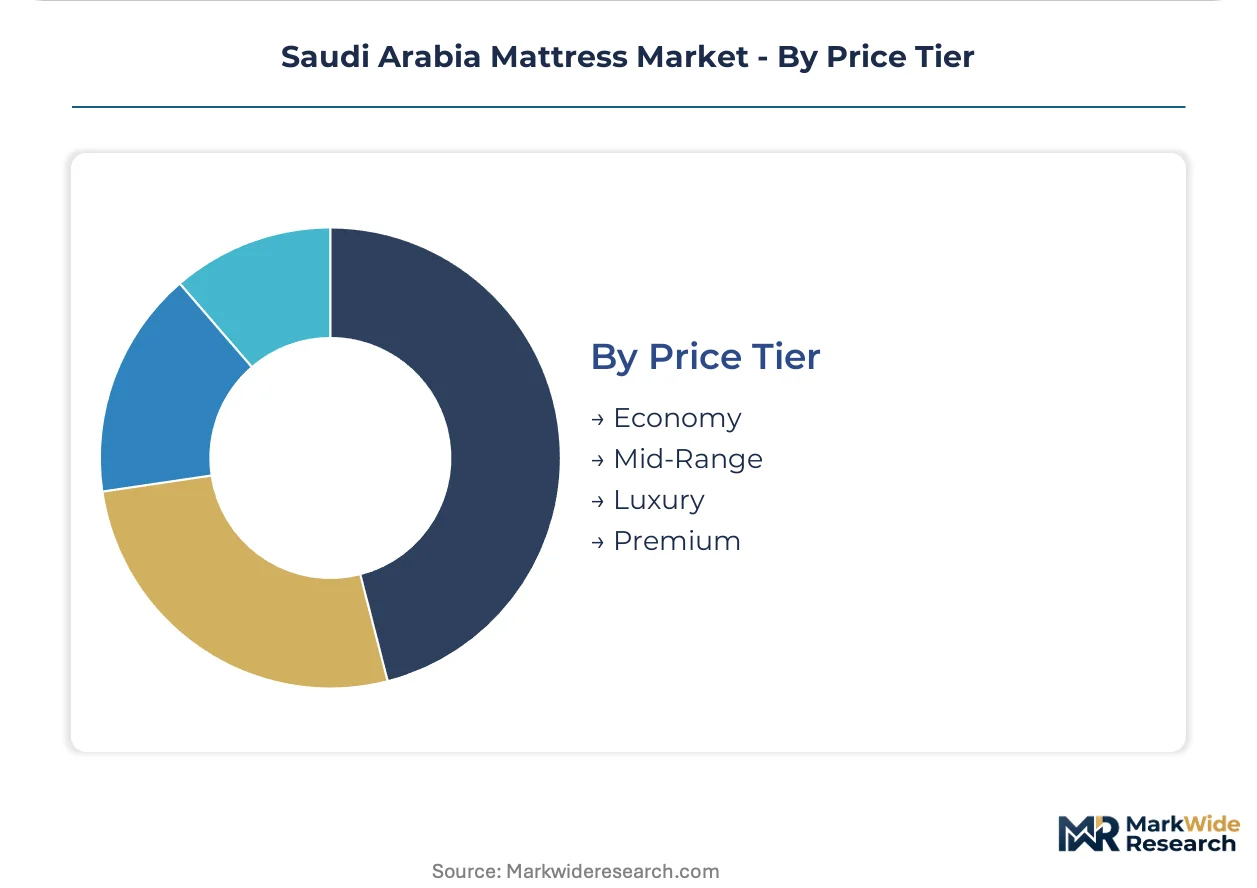
Price Tier:
Purchase thresholds segment buyer capabilities and determine margin architecture across the value chain.
- Economy:Entry-level polyurethane foam and basic innerspring constructions. Workforce accommodation contractors and price-sensitive residential buyers in peripheral Riyadh districts dominate this tier.
- Mid-Range:Enhanced coil counts, denser foam layers, and modest brand premiums. Represents the volume core for family households in Jeddah's middle-income neighborhoods.
- Luxury:Advanced material combinations, extended warranties, and design-forward aesthetics. Riyadh's northern expansion zones and gated compounds generate concentrated demand.
- Premium:Custom configurations, imported components, and concierge-level service. Ultra-high-net-worth collectors and flagship hospitality properties in Diriyah and Red Sea developments specify this tier.
Mid-Range holds volume dominance. Premium tier delivers the most aggressive expansion in absolute value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Riyadh's northern expansion zones show the least price sensitivity for premium sleep systems, while Eastern Province workforce accommodations concentrate volume at economy-tier thresholds. This elasticity gradient shapes procurement patterns across the kingdom's sub-regions.
Riyadh
Diplomatic Quarter and King Abdullah Financial District households drive demand for smart-temperature mattresses with pressure-mapping capabilities. SFDA product safety standards enforce foam density and fire-resistance testing for all residential sales. King Salman Park vicinity developments generate concentrated procurement for luxury-tier hybrid constructions targeting high-income expatriate professionals.
Eastern Province
Dammam and Khobar hospitality procurement teams specify batch-level SFDA compliance documentation for commercial mattress contracts. SASO quality certification requirements mandate laboratory testing at accredited facilities before product launch. Industrial zone workforce accommodations near Dammam prioritize economy-tier bulk procurement with accelerated replacement schedules tied to project cycles.
Jeddah
Coastal humidity drives preference for breathable latex and antimicrobial sleep surfaces in villa developments across the Western Region. The Saudi Building Code enforces fire resistance requirements for hospitality and commercial installations through municipal authorities. Jeddah's retail corridor hypermarkets move high-velocity economy SKUs while specialty showrooms in northern districts target premium household segments.
NEOM Northwest
Red Sea Project and giga-project developments compress procurement timelines for 10-year warranty commercial mattresses with real-time occupancy scoring capabilities. Vision 2030 infrastructure deployment accelerates supplier qualification cycles for fire-rated sleep systems. Direct-to-site delivery coordination from Dammam-based logistics hubs services construction phases across the northwest development zone.
Makkah and Madinah
Pilgrimage accommodation upgrades drive institutional procurement for durable innerspring constructions with extended replacement intervals. Family-owned distributors in both cities resist cloud-based inventory management adoption, fragmenting demand forecasting accuracy. Religious tourism infrastructure expansion generates steady demand for mid-range commercial specifications across hospitality properties serving seasonal visitor surges.
Saudi Arabia Mattress Market Competitive Landscape
Capability concentration sits with localized manufacturers holding SASO certification and hospitality supply relationships; scale advantage sits with global brands leveraging manufacturing footprint and retail channel presence. The market structures around three tiers: international licensees with premium positioning, domestic producers with regulatory compliance advantages, and regional specialists with Gulf distribution control. Dominant competitive moves include strategic partnerships with hospitality developers and portfolio diversification into sleep-as-a-service subscription models.
Within the international licensee tier, Sealy and Serta anchor premium positioning through retail channel penetration and brand recognition. Intercoil occupies a position exemplifying regional specialization with localized production and Gulf market distribution control. AI-Mutlaq represents the domestic compliance-advantaged archetype, extending traditional bedding expertise into hospitality supply contracts for Vision 2030 developments.
| Leading Market Players |
|---|
| Sealy |
| ALMazro |
| SleepHigh |
| AI-Mutlaq |
| AI Rajhi Group |
| Intercoil |
| Serta |
| Tempur |
| King Koil |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility in TDI and polyether polyol inputs compresses margin predictability for Saudi foam-core manufacturers while simultaneously widening spreads between economy-tier bulk contracts and premium hospitality specifications. This single-source dependency on crude oil benchmarks forces parallel inventory strategies that elevate working capital requirements across all pricing tiers.
Pricing Analysis
Aftermarket service revenue from mattress recycling and refurbishment programs now drives lifetime value extraction beyond initial unit sales. Three-tier pricing structure across premium, standard, and economy levels segments buyer capabilities, with SASO certification grade and volume scale serving as primary price differentiation drivers. Cost compression in economy-tier polyurethane foam is intensifying because of import concentration from Southeast Asian latex suppliers. Workforce accommodation contractors in the Eastern Province exhibit highest price sensitivity, while Red Sea giga-project hospitality procurement teams show minimal elasticity for fire-rated commercial specifications.
Supply Chain Analysis
Supplier-financing facilities with 90-day extended payment terms have become standard for Saudi manufacturers sourcing natural rubber from Thailand, Indonesia, and Malaysia. Raw material supply draws from petrochemical complexes in the Eastern Province for polyurethane foam, Southeast Asian rubber plantations for latex cores, and certified barrier fabric mills in Turkey and Egypt. Single-source vulnerability concentrates in natural rubber feedstock given the absence of backward integration into rubber cultivation. Distribution runs through Dammam-based logistics hubs servicing hospitality developers, Jeddah retail corridor hypermarkets, and Riyadh specialty showroom clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi mattress market rewards operators who control scarce foam formulation chemistry capabilities and SASO certification pathways, while penalizing those dependent on expatriate technical labor and import-heavy input structures.
For Market Incumbents: Harden compliance infrastructure against accelerating SFDA update cycles by maintaining parallel pre-certified and post-certified inventory batches. Anchor premium positioning through exclusive hospitality supply contracts at Qiddiya and Diriyah developments, while investing in captive polyurethane recycling capacity near Dammam industrial zones to offset petrochemical feedstock volatility. For New Entrants and Emerging Players: Northern Riyadh expansion corridors around King Salman Park present underpenetrated demand for smart-temperature mattresses targeting high-income expatriate households. White-space opportunities concentrate in direct-to-consumer channels with augmented reality visualization tools bypassing traditional furniture souk intermediaries, and in subscription-based mattress refresh programs for young professional households in the Diplomatic Quarter. For Investors and Strategic Acquirers: SFDA's alignment with EU REACH Annex XVII standards reshapes the acquisition landscape toward domestic manufacturers holding accredited laboratory relationships and batch-level compliance documentation capabilities. Long-term viability centers on circular economy infrastructure plays with chemical recycling integration. The signal to watch is hospitality procurement specification shifts toward real-time occupancy scoring and continuous performance verification clauses.| Strategic Initiative | Industry Significance |
|---|---|
| SASO Certification Investment | Accelerates product launch timelines by reducing laboratory testing queue exposure at accredited facilities. |
| Hospitality Supply Contract Lock-in | Secures 10-year warranty specifications at Vision 2030 giga-projects ahead of competitor qualification cycles. |
| Polyurethane Recycling Integration | Captures cost advantages from Dammam industrial zone chemical recycling lines converting post-consumer foam. |
| Direct-to-Consumer Platform Launch | Bypasses fragmented family-owned distributor networks in Makkah and Madinah with cloud-based inventory management. |
| AI-Driven Customization Development | Enables pressure-mapping sensor integration for personalized firmness profiles in King Abdullah Financial District residential towers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA technical regulations, SASO quality certification databases, and hospitality procurement documentation from Vision 2030 giga-project developers. Primary interviews engaged foam formulation chemists, hospitality procurement managers at Marriott and Hilton franchise operations, and distribution channel partners across Riyadh, Jeddah, and Dammam. Secondary sources incorporated Saudi Building Code enforcement records, customs trade data on polyurethane and latex imports, and municipal real estate development permits. Bottom-up demand modeling triangulated against top-down petrochemical feedstock consumption patterns.
Forecast inputs include hospitality construction pipeline progression across Diriyah, Qiddiya, and Red Sea coast developments, SFDA compliance timeline acceleration, and residential real estate transaction cycles in Riyadh's northern expansion zones. Segmentation dimensions encompass product construction technology, end-use vertical, distribution channel economics, and price tier positioning. CAGRs derive from elasticity-adjusted demand curves and replacement cycle compression effects. Industry-specific inputs incorporate Vision 2030 infrastructure deployment schedules and circular economy regulation evolution.
Practitioners should monitor SFDA technical regulation updates, crude oil benchmark volatility affecting TDI and polyether polyol pricing, and hospitality procurement specification shifts toward continuous performance verification for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bedroom Furniture
Bed Slats Market
Bedroom Furniture
Luxury Bedding Market
Bedroom Furniture
Smart Bed Market
Bedroom Furniture
Bedding Market
Bedroom Furniture
US Daybeds Market
Bedroom Furniture
Baby Cribs Market
Bedroom Furniture
Germany Mattress Market
Bedroom Furniture
Foam Mattress Market
Bedroom Furniture
Bed and Bath Furnishing Market
Bedroom Furniture
Turkey Mattress Market
Bedroom Furniture
Global Cervical Pillows Market
Bedroom Furniture
Teen Room Décor Market
Bedroom Furniture
Bunk Beds Market
Bedroom Furniture
India Mattress Market
Bedroom Furniture
United States Mattress Market
Bedroom Furniture
Luxury Mattress Market