
 Industrial Wireless Solution Market | 2026-2036
Industrial Wireless Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Wireless Solution Market Outlook
German automation suppliers is recalibrating output schedules to address backlogs in industrial gateway production. Honeywell International Inc. leverages its process control heritage to anchor wireless deployments in hazardous environments. Siemens AG sustains R&D intensity across its industrial 5G portfolio, while Cisco Systems, Inc. competes through edge-computing integration with wireless access points.
Industrial wireless solutions encompass radio-based communication systems operating in licensed and unlicensed spectrum bands, typically transmitting data at frequencies between 900 MHz and 6 GHz with latency requirements under 10 milliseconds for time-critical control loops. These systems replace or augment wired fieldbus networks in factories, refineries, and distribution centers to enable mobile equipment connectivity, rapid reconfiguration of production lines, and telemetry from remote assets. Mesh networks occupy the largest installed base due to self-healing topology advantages in sprawling facilities, while cellular segments record the fastest expansion as private 5G networks gain traction in automotive and semiconductor fabs. Wi-Fi technology leads current revenue pools given its maturity and interoperability, though LoRaWAN carves out margin-rich niches in long-range, low-power asset tracking across utilities and agriculture adjacencies.
FCC Part 15 rules govern unlicensed industrial radio operation in the United States, while the EU Radio Equipment Directive mandates harmonized spectrum use across member states, and Japan's MIC establishes technical standards for 5G private networks. These frameworks shape demand by certifying equipment categories, defining interference limits, and determining which frequency bands factories may legally utilize. Stakeholders must monitor spectrum auction outcomes and cybersecurity labeling requirements as regulatory conditions directly determine product roadmaps and geographic deployment feasibility.
Market Dynamics
Private 5G network deployments are compressing decision cycles for factory automation buyers, as spectrum licensing frameworks in Germany, Japan, and the United States simultaneously mature and create first-mover advantages for early adopters.
Growth Catalysts
- EU Radio Equipment Directive harmonization:Cross-border equipment certification is reducing deployment friction for multinational manufacturers operating across Belgium, Netherlands, and Luxembourg industrial corridors.
- Process automation retrofit demand:Oil and gas facilities in the US Gulf Coast are replacing wired fieldbus networks with wireless telemetry to monitor remote wellhead assets.
- Sub-6 GHz spectrum availability:Japan's MIC technical standards for local 5G licenses are enabling semiconductor fabrication plants to build deterministic low-latency control loops.
Market Restraints
- Industrial gateway supply concentration:Production backlogs at German automation suppliers are extending lead times for mesh network deployment hardware.
- Copper and gallium nitride input volatility:RF component manufacturing faces raw material cost swings that compress margin on high-frequency access point production.
- Legacy wired infrastructure substitution ceiling:Safety-critical control systems in chemical processing retain hardwired redundancy requirements that wireless protocols cannot satisfy.
Strategic Opportunities
- Ruhr industrial cluster digitization:Germany's manufacturing retrofit programs are creating concentrated demand for wireless equipment upgrades in legacy mechanical engineering facilities.
- Edge-computing convergence:Wireless access point integration with on-premise data processing is opening new service revenue streams for systems integrators serving automotive assembly lines.
- Agriculture adjacency expansion:LoRaWAN-based asset tracking is penetrating utility vegetation management and irrigation monitoring applications beyond traditional factory boundaries.
Industry Challenges
- IT/OT cybersecurity skill scarcity:Plant engineering teams lack personnel trained to configure zero-trust architectures across converged operational and information technology networks.
- Multi-protocol integration complexity:Facilities deploying simultaneous Wi-Fi, 5G, and proprietary mesh networks face interoperability testing burdens that delay commissioning timelines.
- FCC Part 15 interference mitigation:Unlicensed band congestion in dense industrial zones requires specialized RF planning expertise that exceeds in-house capabilities at mid-sized manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Wireless Solution Market |
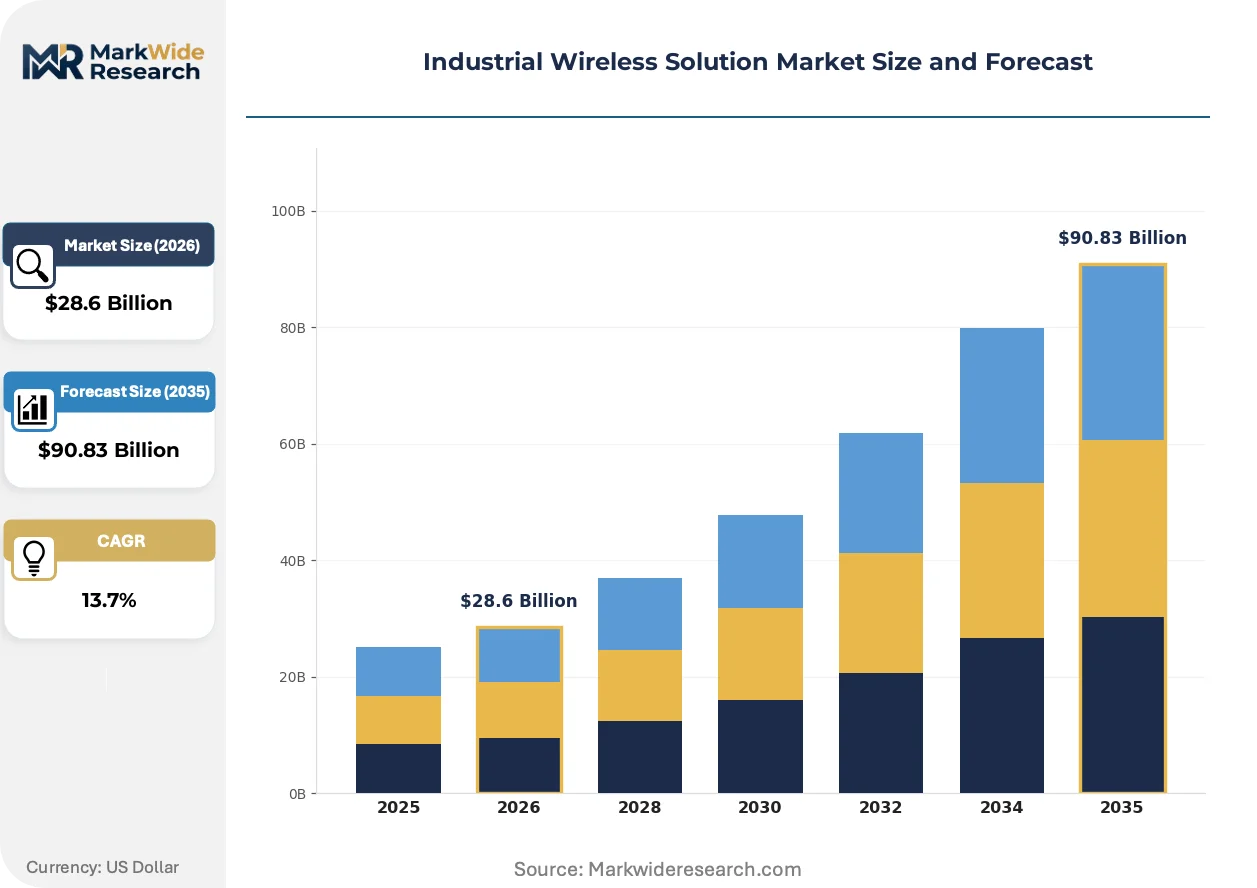
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesh Networks, Point-to-Point, Cellular, Satellite Technology: Wi-Fi, Zigbee, LoRaWAN, Bluetooth Application: Remote Monitoring, Inventory Management, Asset Tracking, Process Automation End User: Manufacturing, Oil & Gas, Transportation, Utilities |
| Companies Covered | Honeywell International Inc., Siemens AG, Schneider Electric SE, Cisco Systems, Inc., Rockwell Automation, Inc., ABB Ltd., Emerson Electric Co., Moxa Inc., Belden Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Wireless Solution Market Strategic Shifts
Radio hardware is fusing with compute infrastructure at the network edge, while spectrum policy and procurement patterns are simultaneously rewriting how industrial buyers evaluate connectivity investments.
Time-Sensitive Networking over wireless is converging with 5G Ultra-Reliable Low-Latency Communication to synchronize robotic motion control across automotive assembly lines. German and Japanese automotive OEMs are piloting these combined protocols in greenfield battery cell manufacturing plants. This convergence is compressing the vendor landscape by forcing traditional fieldbus suppliers to develop radio expertise or cede socket positions to telecom equipment providers.
FCC Part 15 rules governing unlicensed industrial radio operation are tightening emission limits in the 5.9 GHz band to protect automotive safety applications. Equipment manufacturers must redesign power amplifiers and filtering stages to maintain compliance, raising non-recurring engineering costs for access point product lines. US-based factory automation vendors are responding by accelerating licensed-band private cellular alternatives that sidestep unlicensed spectrum contention entirely.
Buying committees at process industry facilities are consolidating vendor selection authority from plant engineering departments into centralized procurement functions with cybersecurity risk mandates. Systems integrators and value-added resellers are losing specification influence as direct OEM relationships become the preferred contracting path. This shift is most pronounced in US oil and gas and German chemical processing, where CISO offices now hold veto power over wireless architecture decisions.
Industrial Wireless Solution Market Segmentation
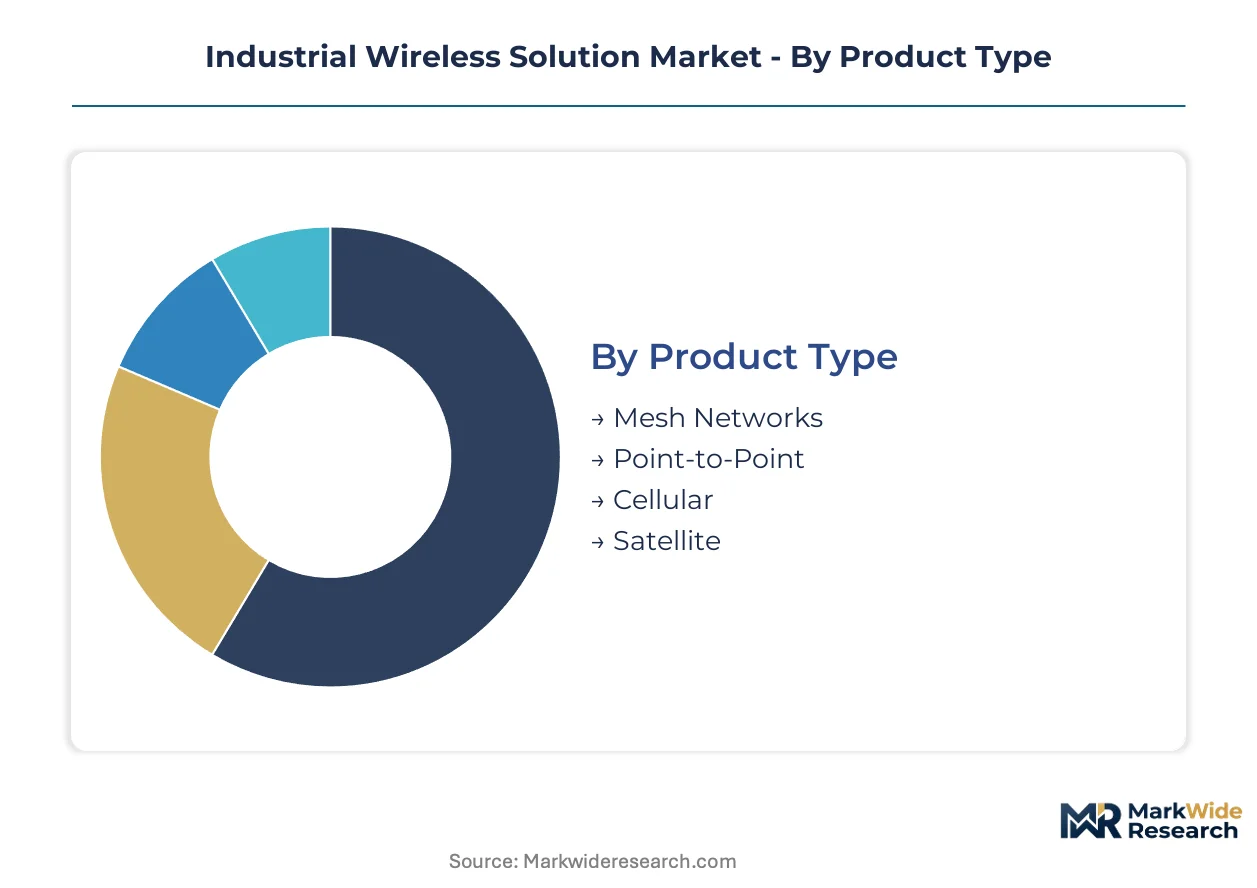
Industrial wireless architectures vary dramatically in deployment complexity, spectrum licensing requirements, and latency performance. Buyers select configurations based on facility scale, mobility needs, and legacy integration constraints rather than pursuing one-size-fits-all approaches.
Product Type:
Customization intensity spans from self-configuring mesh topologies to highly engineered satellite links, with standardization increasing as deployment scale rises.
- Mesh Networks:Self-healing radio topologies automatically reroute traffic around failed nodes without controller intervention. Demand clusters in sprawling US Gulf Coast petrochemical complexes where cable trenching costs exceed wireless hardware premiums by multiples. German Ruhr industrial retrofit programs specify mesh for legacy mechanical engineering halls lacking conduit infrastructure.
- Cellular:Licensed-spectrum systems leveraging private 4G/5G infrastructure deliver deterministic latency under 10 milliseconds for closed-loop control. Japan's MIC local 5G licensing framework accelerates semiconductor fabrication plant deployments in Kumamoto and Hiroshima prefectures where electromagnetic interference from plasma etching equipment disrupts unlicensed alternatives.
- Point-to-Point:Directional radio links bridge geographically separated facility zones over distances exceeding one kilometer. Utilities in Texas and California deploy these for substation interconnects where fiber burial is geologically prohibitive.
- Satellite:Geostationary and low-earth-orbit backhaul extends connectivity to remote wellheads, offshore platforms, and mining operations beyond terrestrial infrastructure reach. Arctic oil exploration and Australian iron ore haulage corridors drive procurement.
Most installed capacity flows through mesh networks. Expansion is steepest in cellular as private 5G licensing frameworks mature across Germany, Japan, and the United States.
Technology:
Protocol selection trades off power consumption, data rate, and ecosystem maturity against specific industrial workload requirements.
- Wi-Fi:Mature IEEE 802.11 standards dominate high-throughput applications with existing IT infrastructure. Manufacturing floors in Michigan and Bavaria standardize on Wi-Fi 6E for AGV fleet management and quality vision systems requiring hundreds of megabits per second.
- LoRaWAN:Ultra-narrowband modulation enables decade-long battery life for sparse telemetry from geographically distributed assets. US electric utilities deploy these networks for vegetation encroachment monitoring along thousands of miles of transmission corridors where cellular data costs would prove prohibitive.
- Zigbee:Mesh-native protocol optimized for low-power sensor networks in building automation and secondary process monitoring. German chemical processors use Zigbee for non-critical temperature and vibration sensing in auxiliary equipment rooms.
- Bluetooth:Short-range protocol dominates personnel safety applications and portable diagnostic tool connectivity. Maintenance technicians in Japanese automotive plants rely on Bluetooth Low Energy for handheld vibration analyzers and thermal imaging cameras.
Wi-Fi commands the largest revenue pool given interoperability maturity. LoRaWAN climbs the fastest as utility and agriculture adjacencies expand beyond traditional factory boundaries.
Application:
Use case segmentation reflects diverging requirements for data freshness, mobility support, and integration depth with existing control systems.
- Process Automation:Closed-loop control applications demanding sub-10-millisecond latency and 99.999% availability. Private 5G networks in German battery cell manufacturing and Japanese semiconductor fabs displace wired fieldbus for robotic motion synchronization.
- Asset Tracking:Location and condition monitoring for mobile equipment, tooling, and inventory. LoRaWAN and UWB combinations penetrate US intermodal rail yards and European automotive sequencing centers where real-time visibility reduces search labor and prevents production stoppages.
- Remote Monitoring:Telemetry from geographically dispersed or hazardous-access assets including wellheads, pipelines, and offshore platforms. Wireless instrumentation in Permian Basin oilfields eliminates manned site visits for pressure and flow readings.
- Inventory Management:Automated identification and cycle counting through RFID and barcode integration with warehouse management systems. Distribution centers in the Netherlands and Belgium deploy wireless mesh for real-time stock positioning across multi-building campuses.
Process automation absorbs the highest average selling prices per node. Asset tracking gains share fastest as RTLS technology costs decline and use cases proliferate beyond manufacturing into healthcare and logistics.
End User:
Vertical specialization drives diverging procurement patterns, with some sectors prioritizing hazardous area certification and others emphasizing rapid reconfiguration flexibility.
- Oil & Gas:Explosion-proof hardware requirements and extreme temperature specifications dominate. US Gulf Coast refineries and North Sea platforms specify IECEx-certified wireless transmitters for tank level monitoring and flare stack thermocouples.
- Manufacturing:Demand concentrates in automotive, electronics, and food processing where production line reconfiguration frequency exceeds wired infrastructure adaptability. German OEM battery plants and Tennessee vehicle assembly lines lead private cellular adoption.
- Utilities:Grid modernization and distributed energy resource integration drive substation automation and demand response networking. California investor-owned utilities deploy wireless for wildfire risk monitoring and rapid sectionalizing.
- Transportation:Intermodal facilities, airports, and rail yards require mobile equipment connectivity and perimeter security. Rotterdam port container terminals integrate wireless with terminal operating systems for straddle carrier positioning.
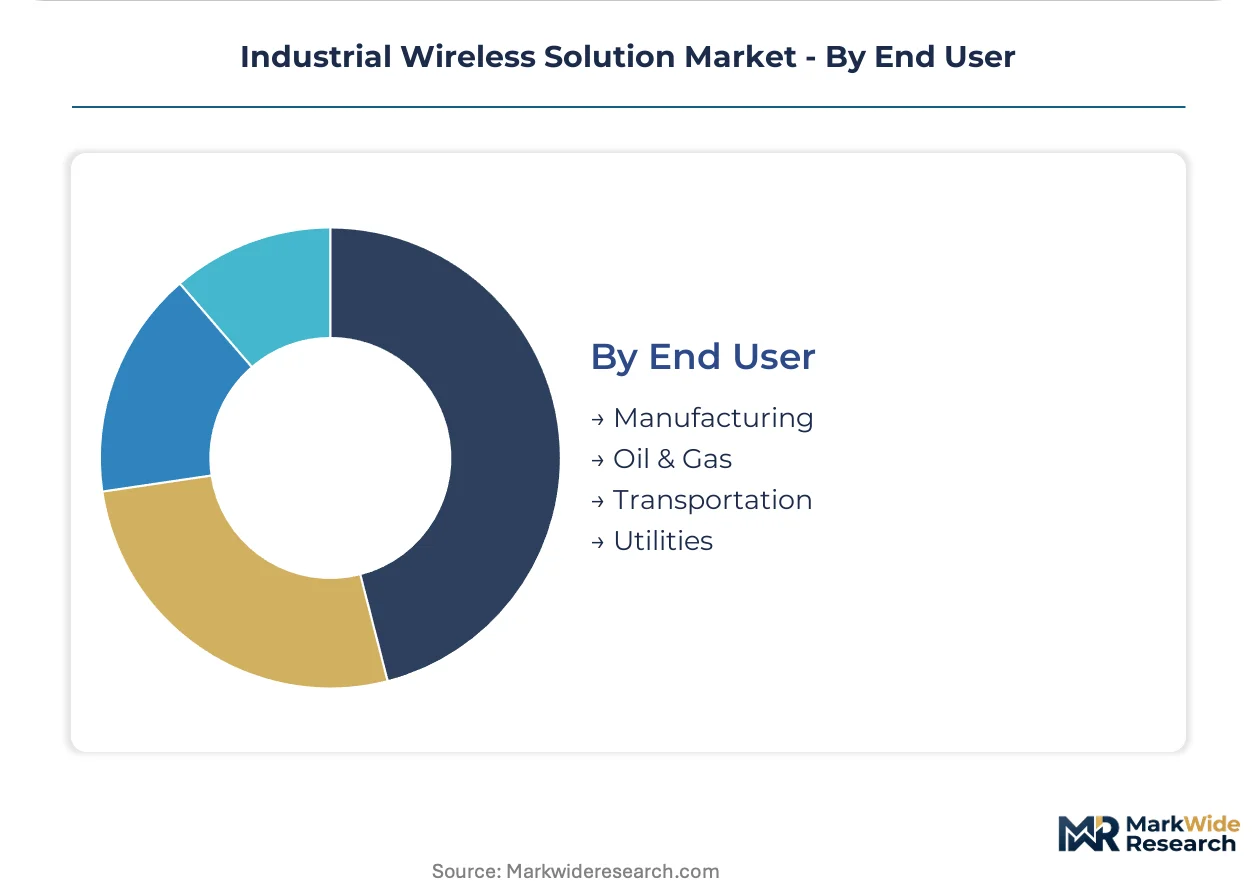
Oil and gas contributes the highest margins per deployment due to hazardous area certification requirements. Manufacturing represents the fastest-expanding addressable base as automotive electrification and reshoring investments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting private 5G deployment capital toward jurisdictions with streamlined spectrum licensing. Germany's local 5G framework and Japan's MIC technical standards attract manufacturing investment that might otherwise flow to markets with heavier compliance burdens.
United States
FCC Part 15 rules govern unlicensed industrial radio operation while Part 96 enables shared spectrum access. The US Gulf Coast petrochemical corridor is replacing wired fieldbus networks with wireless telemetry for remote wellhead monitoring. Permian Basin oilfields deploy wireless instrumentation to eliminate manned site visits.
Germany
The EU Radio Equipment Directive mandates harmonized spectrum use across member states. Ruhr industrial cluster digitization programs prioritize wireless retrofitting of legacy mechanical engineering facilities. Battery cell manufacturing plants in Lower Saxony pilot Time-Sensitive Networking combined with 5G Ultra-Reliable Low-Latency Communication.
Japan
METI and MIC establish technical standards for local 5G licenses in sub-6 GHz bands. Semiconductor fabrication plants in Kumamoto and Hiroshima prefectures build deterministic low-latency control loops. Automotive OEMs in the Chubu region test converged protocols for robotic motion synchronization.
China
MIIT spectrum allocation frameworks prioritize industrial IoT bands for smart manufacturing initiatives. Yangtze River Delta electronics fabs expand private cellular deployments for AGV fleet management. Sichuan-Chongqing manufacturing bases integrate wireless access points with edge-computing infrastructure.
Netherlands
Cross-border equipment certification under EU harmonization reduces deployment friction for multinational manufacturers. Distribution centers in the Randstad region deploy wireless mesh for real-time stock positioning across multi-building campuses. Rotterdam port container terminals integrate wireless with terminal operating systems for straddle carrier positioning.
Industrial Wireless Solution Market Competitive Environment
German automation suppliers anchor one tier; US networking specialists hold another. The vendor base organizes around process control heritage versus information technology integration capabilities. Three archetypes dominate: industrial conglomerates with fieldbus legacies, telecom equipment providers expanding into factories, and pure-play wireless hardware vendors. Capacity expansion and strategic partnerships constitute the primary competitive moves as players address gateway production backlogs.
Within the industrial conglomerate tier, Honeywell International Inc., Siemens AG, and Cisco Systems, Inc. exemplify divergent strategic positions. Honeywell represents the process control heritage archetype, leveraging hazardous environment expertise. Siemens anchors the European automation tradition with sustained R&D intensity across industrial 5G portfolios. Cisco occupies the information technology convergence position, competing through edge-computing integration with wireless access points.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Schneider Electric SE |
| Cisco Systems, Inc. |
| Rockwell Automation, Inc. |
| ABB Ltd. |
| Emerson Electric Co. |
| Moxa Inc. |
| Belden Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between IECEx-certified hazardous-area hardware and standard industrial equipment manifests in both margin structures and supplier qualification requirements. Premium-tier suppliers command pricing power through captive testing facilities in Germany and Japan, while commodity mesh-network vendors compete on volume scale from Taiwan-based manufacturing.
Pricing Analysis
Distributor margins absorb 15-25 points before systems integrators apply project-based markups to factory automation buyers. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with IECEx and ATEX tiers separating oil and gas procurement from general manufacturing. Cost compression in unlicensed Wi-Fi access points is intensifying because gallium nitride RF component shortages force redesign cycles. Mid-sized manufacturers in the US Midwest exhibit highest price sensitivity, while Gulf Coast petrochemical operators prioritize availability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for industrial gateways mandate qualification of secondary suppliers across Germany, Taiwan, and Mexico to mitigate production backlogs. RF component manufacturing draws from copper substrate suppliers in Chile and gallium nitride foundries in Japan and the United States. Single-source vulnerability concentrates in German automation suppliers where gateway lead times extend beyond customer tolerance. Distribution runs through authorized distributors serving systems integrators, with direct OEM contracting gaining share in cybersecurity-sensitive deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory sequencing, with Japan's MIC local 5G licensing framework accelerating private cellular deployment decisions among semiconductor fabricators.
For Market Incumbents: Deploy backward integration into gallium nitride RF component supply to defend margins against raw material volatility. Honeywell and Siemens should accelerate captive production of industrial gateways in Mexico to offset German supplier backlogs. Certification investment in IECEx and ATEX tiers protects socket positions against emerging telecom equipment providers. For New Entrants and Emerging Players: FCC Part 96 shared spectrum access in the United States opens a window for neutral-host private 5G operators serving multi-tenant industrial parks. White-space targets include agriculture adjacencies for LoRaWAN-based irrigation monitoring and mid-sized chemical processors lacking in-house RF planning expertise. Channel partnerships with systems integrators offer faster traction than direct OEM pursuit. For Investors and Strategic Acquirers: Consolidation pressure builds where edge-computing convergence exceeds standalone wireless hardware capabilities. Long-term viability favors vendors integrating on-premise data processing with radio infrastructure. Target acquisition profiles include pure-play wireless hardware vendors with established FCC and MIC certifications but limited software stack. Watch private 5G spectrum auction outcomes as inflection indicators for geographic deployment feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RF Components | Gallium nitride captive supply secures margin against raw material volatility in high-frequency access point production. |
| Private 5G Spectrum Licensing | Japan's MIC local licenses enable deterministic control loops in Kumamoto semiconductor fabrication plants. |
| Edge-Computing Convergence | Wireless access point integration with on-premise processing opens service revenue at automotive assembly lines. |
| Agriculture Adjacency Expansion | LoRaWAN vegetation monitoring penetrates utility corridors beyond traditional factory wireless boundaries. |
| Certification Investment | IECEx and ATEX tiers separate hazardous-area suppliers from commodity competitors in oil and gas procurement. |
Study Parameters
Coverage spans Germany, Japan, the United States, and China, with primary inputs from each market's industrial automation ecosystem. Plant engineers, OEM procurement teams, systems integrators, and aftermarket service heads provided qualitative demand validation. Secondary sources include FCC spectrum allocation records, EU Radio Equipment Directive harmonization documents, Japan MIC technical standards, MIIT industrial IoT band allocations, SEC 10-K filings, and customs trade data. Bottom-up unit economics triangulate against top-down market sizing across the analysis window.
Granularity-level modeling distinguishes mesh, cellular, point-to-point, and satellite product types at the deployment level. Technology segmentation captures Wi-Fi, LoRaWAN, Zigbee, and Bluetooth protocol adoption patterns. Application dimensions include process automation, asset tracking, remote monitoring, and inventory management. End-user verticals span oil and gas, manufacturing, utilities, and transportation. CAGRs derive from regression against industrial capital expenditure cycles and spectrum licensing velocity. Forecast inputs incorporate private 5G deployment timelines and edge-computing infrastructure buildouts.
Revisions become necessary when spectrum auction delays, raw material cost spikes, or cybersecurity regulatory shifts materialize. Forecasts reflect assumptions about regulatory harmonization pace and industrial gateway production capacity expansion. Deviation in FCC Part 15 emission limit tightening or gallium nitride foundry output would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
North America in-Building Wireless Market
Wireless Technologies
5G Spectrum Market
Wireless Technologies
Industrial Bluetooth Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Femtocell Market
Wireless Technologies
5G Wireless Ecosystem Market
Wireless Technologies
Wi-Fi Hotspot (Dongle) Market
Wireless Technologies
Wifi Kiosks Market
Wireless Technologies
Global in-Building Wireless Market
Wireless Technologies
Voice Over LTE (VOLTE) and Voice Over Wi-Fi Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Distributed Antenna System Market
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Telecom Millimeter Wave (MMW) Technology Market
Wireless Technologies
Wireless Paging Systems Market
Wireless Technologies
Wi-Fi Booster Market