
 Low-Temperature Flow Improver Additives for 3D Printing Resins Market | 2026-2036
Low-Temperature Flow Improver Additives for 3D Printing Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Temperature Flow Improver Additives for 3D Printing Resins Market Insights
ISO/ASTM 52900 qualification for additive manufacturing materials is bifurcating supplier tiers in this market. Evonik Industries leverages its specialty methacrylate backbone to sustain premium positioning across photopolymer formulations. BASF anchors European supply through backward integration into polyether polyol feedstocks. Arkema competes on acrylate oligomer specialization for low-viscosity dental resins.
Low-temperature flow improver additives are surface-active compounds, typically siloxane- or polyether-modified chemistries, that reduce dynamic viscosity below 25 degrees Celsius to enable jetting and vat polymerization of resins formulated for photopolymerization and material jetting platforms. These additives prevent shear-thickening and meniscus instability when resins are cooled for precision layer deposition in dental modeling and aerospace components. Polyether-type flow improvers command the deepest margin pools due to compatibility breadth across epoxy and acrylate resin matrices. Siloxane variants represent the fastest-growing technology segment, driven by thermal stability requirements in automotive prototyping applications requiring repeated thermal cycling. Photopolymerization technology dominates volume consumption, though powder bed fusion additive formulations are emerging as a specialized demand pocket requiring tailored rheology modifiers.
EPA chemical safety evaluations under TSCA Section 5 constrain novel additive introductions in the United States, while REACH registration thresholds in Europe mandate full toxicological dossiers for siloxane chemistries above one-ton annual volumes. FDA 510(k) pathways for dental and medical device resins further stratify market access, requiring biocompatibility validation that only formulation houses with dedicated regulatory affairs functions can navigate efficiently. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated flow improver chemistries face substitution pressure across all major regulatory jurisdictions.
Market Dynamics
ISO/ASTM 52900 qualification requirements are restructuring competitive tiers by separating formulation houses with dedicated regulatory affairs functions from commodity additive suppliers unable to navigate multi-jurisdictional compliance dossiers.
Growth Catalysts
- Aerospace prototyping expansion:Sub-ambient resin handling requirements in Germany and the United States are pulling specialized flow improver demand for precision layer deposition in structural component manufacturing.
- REACH registration thresholds:Mandated toxicological dossiers for siloxane chemistries above one-ton annual volumes are consolidating supply toward established European formulation houses with existing compliance infrastructure.
- Photopolymerization platform proliferation:Dental modeling applications requiring jetting stability at reduced temperatures are accelerating consumption of polyether-modified rheology additives.
Market Restraints
- Feedstock concentration:Backward-integrated control over polyether polyol feedstocks by major European chemical conglomerates limits independent additive producer margin flexibility.
- TSCA Section 5 friction:EPA chemical safety evaluations constrain novel additive introductions in the United States, extending time-to-market for innovative siloxane architectures.
- Fluorinated chemistry substitution:Per- and polyfluoroalkyl substance restrictions across major jurisdictions are forcing reformulation of legacy flow improvers without equivalent performance alternatives.
Strategic Opportunities
- Powder bed fusion emergence:Specialized rheology modifier demand for powder bed fusion additive formulations represents an underdeveloped application pocket requiring tailored surface-active compound development.
- Automotive thermal cycling:Repeated thermal cycling requirements in automotive prototyping applications are creating pull for siloxane variants with superior thermal stability profiles.
- FDA 510(k) pathway mastery:Biocompatibility validation capabilities for dental and medical device resins create defensible positioning for formulation houses with dedicated regulatory functions.
Industry Challenges
- ISO/ASTM 52900 certification timelines:Qualification protocols for additive manufacturing materials demand extended validation periods that compress working capital cycles for mid-tier suppliers.
- Multi-jurisdictional dossier management:Simultaneous navigation of REACH, TSCA, and FDA requirements strains regulatory affairs capacity at specialized additive houses without enterprise-scale compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Temperature Flow Improver Additives for 3D Printing Resins Market |
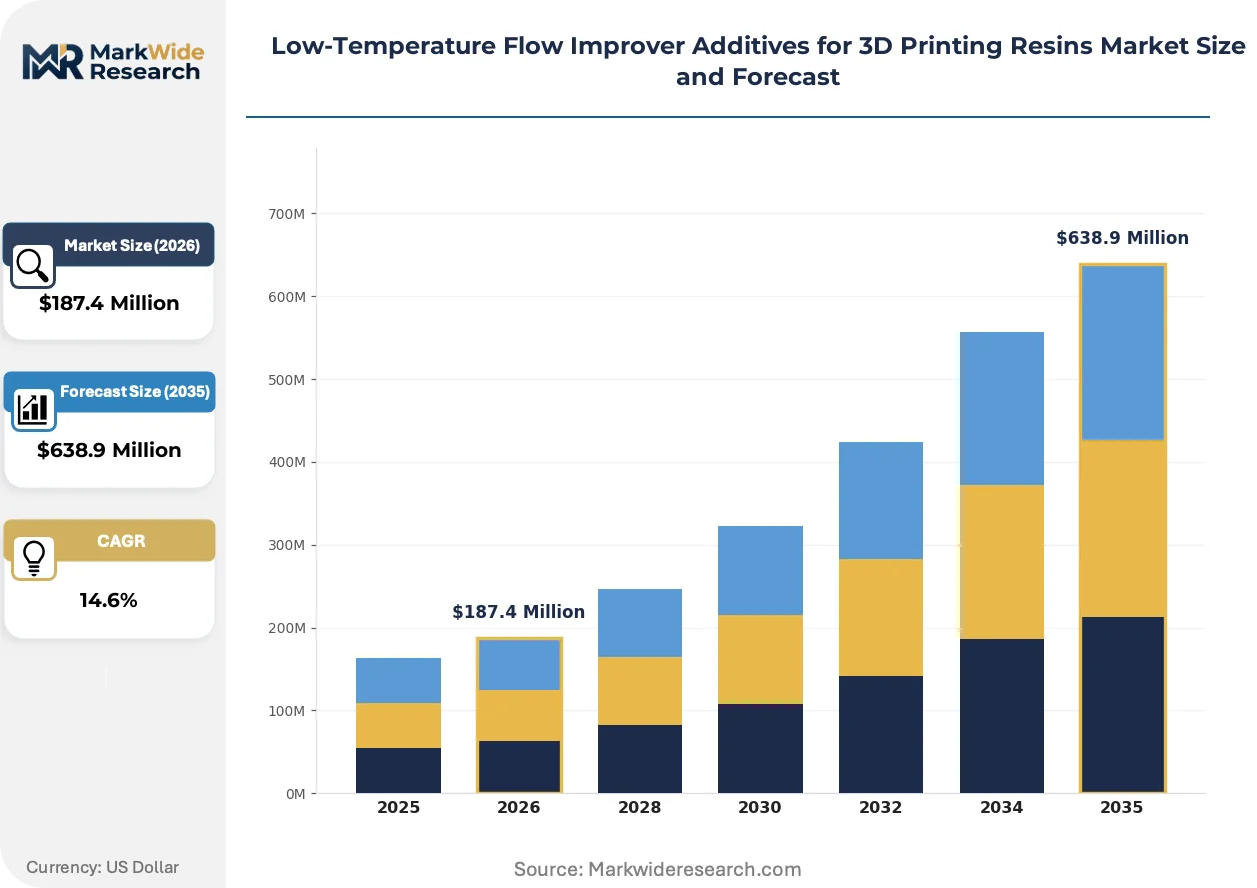
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether, Siloxane, Acrylate, Polyurethane, Epoxy Technology: Photopolymerization, Vat Polymerization, Material Jetting, Binder Jetting, Powder Bed Fusion Application: Dental Modeling, Automotive Prototyping, Jewelry Fabrication, Aerospace Components, Consumer Goods Design End User: Research Laboratories, Rapid Prototyping Firms, Customized Manufacturing Units, Educational Institutions, Product Design Studios |
| Companies Covered | Evonik Industries, BYK-Chemie, BASF, Arkema, Clariant, Dow, Lubrizol, Croda International, Elementis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Temperature Flow Improver Additives for 3D Printing Resins Market Trends and Innovations
Formulation chemistry is splitting along performance-grade lines as end-users segment procurement between premium qualified suppliers and cost-optimized alternatives, reshaping how flow improver additives are specified and sourced.
Siloxane-modified flow improver technology is bifurcating supplier positioning in this market. These surface-active compounds reduce dynamic viscosity below 25 degrees Celsius for jetting and vat polymerization platforms. Automotive prototyping operations in Germany and the United States are adopting siloxane variants at accelerated rates for repeated thermal cycling applications. This adoption pattern is compressing market share for legacy polyether-only suppliers unable to demonstrate equivalent thermal stability performance.
EPA chemical safety evaluations under TSCA Section 5 are constraining novel additive introductions in the United States. The industrial consequence is extended pre-market notification timelines that favor incumbent suppliers with existing substance inventories. Dental and medical device resin segments are most affected, responding by consolidating procurement toward formulation houses with proven FDA 510(k) navigation experience.
Buyer specification behavior is shifting from commodity additive procurement toward qualified-material-system contracting. Tier-one aerospace and dental OEMs are displacing spot-market purchasing with multi-year formulation partnerships tied to ISO/ASTM 52900 certification. This pattern is most visible in Bavaria's industrial corridor and Michigan's automotive supply basin, where precision layer deposition requirements demand validated supply continuity.
Low-Temperature Flow Improver Additives for 3D Printing Resins Market Segmentation
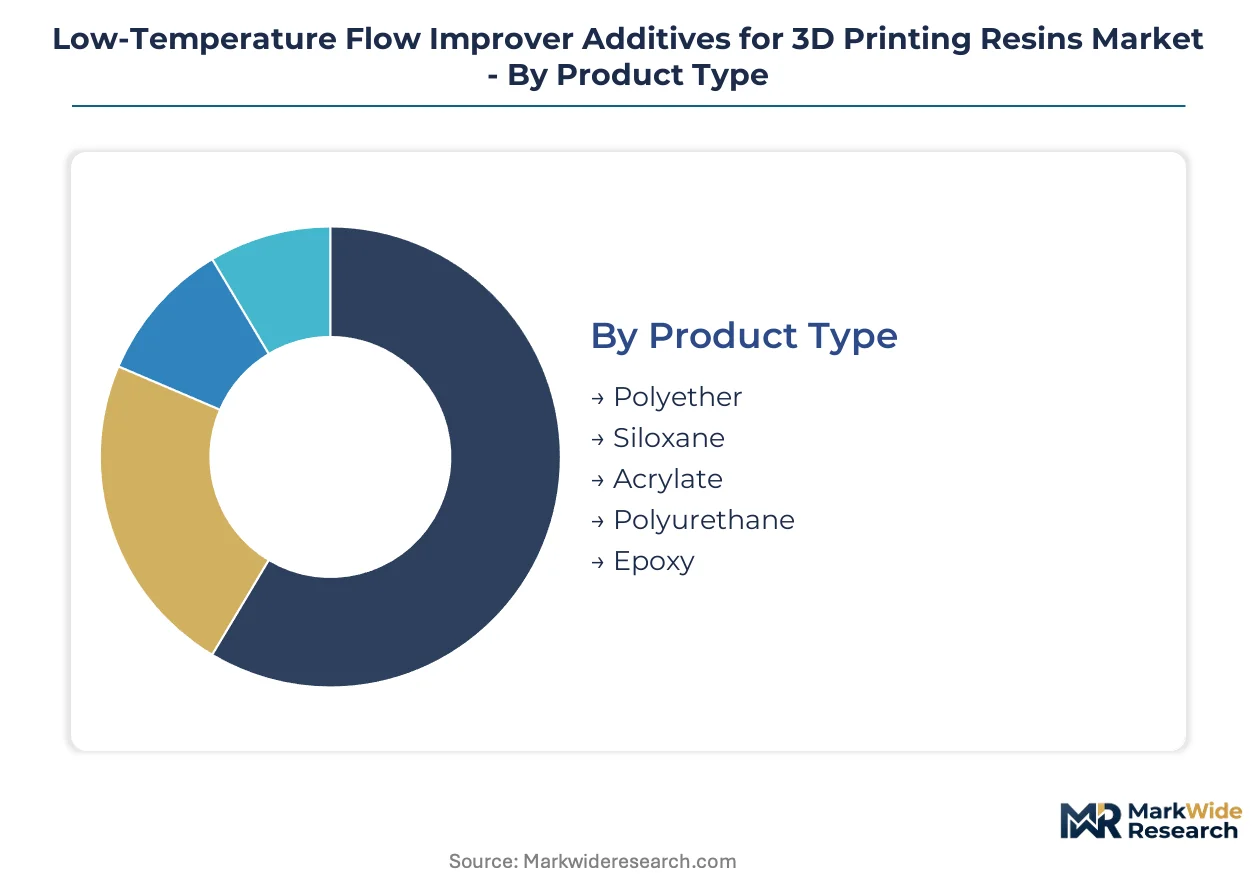
Flow improver additive specifications diverge sharply across 3D printing platforms, with resin chemistry and regulatory compliance requirements dictating procurement patterns. Segmentation in this market reflects the tension between established photopolymer workflows and emerging powder bed fusion applications requiring tailored rheology profiles.
Product Type:
REACH registration thresholds for siloxane chemistries above one-ton annual volumes and EPA TSCA Section 5 evaluations stratify supplier positioning by chemistry family.
- Polyether:These polyether-modified surface-active compounds deliver the broadest compatibility across epoxy and acrylate resin matrices. Demand concentrates in dental modeling applications across Bavaria's industrial corridor, where ISO/ASTM 52900 qualification requirements favor established suppliers with existing toxicological dossiers.
- Siloxane:Siloxane-modified chemistries reduce dynamic viscosity below 25 degrees Celsius while maintaining thermal stability through repeated cycling. Automotive prototyping operations in Michigan's automotive supply basin are adopting these variants for precision layer deposition under sub-ambient conditions.
- Acrylate:Acrylate backbone modifications serve low-viscosity dental resin formulations requiring FDA 510(k) pathway navigation.
- Polyurethane:Polyurethane-based flow improvers address specialized vat polymerization platforms with demanding elasticity specifications.
- Epoxy:Epoxy-compatible variants support aerospace component manufacturing requiring elevated thermal resistance profiles.
Established volume favors polyether; emerging adoption favors siloxane.
Technology:
Platform-specific rheology requirements create distinct additive specification tiers, with photopolymerization commanding mature procurement patterns and powder bed fusion driving specialized development.
- Photopolymerization:Dominant consumption volume for flow improver additives, photopolymerization platforms require surface-active compounds that prevent shear-thickening during precision layer deposition. Dental modeling and jewelry fabrication in Germany and the United States anchor demand for qualified material systems.
- Material Jetting:Jetting stability at reduced temperatures demands polyether-modified rheology additives with precise meniscus control. Aerospace prototyping workflows in the United States are expanding additive manufacturing operations requiring sub-ambient resin handling capabilities.
- Vat Polymerization:Vat-based systems utilize flow improvers to maintain uniform viscosity gradients across large build volumes.
- Binder Jetting:Binder jetting applications require tailored surface-active compounds for powder-resin interaction control.
- Powder Bed Fusion:An underdeveloped application pocket where specialized rheology modifier demand is climbing the fastest as formulation houses develop platform-specific additives.
Mature platforms concentrate procurement volume; emerging platforms command development investment.
Application:
End-use performance requirements segment additive specifications between biocompatibility-validated medical grades and thermal-cycling-tolerant industrial grades.
- Dental Modeling:FDA 510(k) pathways and biocompatibility validation requirements stratify supply toward formulation houses with dedicated regulatory affairs functions. Jetting stability at reduced temperatures accelerates consumption of polyether-modified additives.
- Aerospace Components:Structural component manufacturing in Germany and the United States requires sub-ambient resin handling with validated supply continuity. ISO/ASTM 52900 qualification separates premium suppliers from commodity additive producers.
- Automotive Prototyping:Repeated thermal cycling requirements create pull for siloxane variants with superior thermal stability profiles.
- Jewelry Fabrication:Precision casting applications demand flow improvers enabling fine feature resolution.
- Consumer Goods Design:Cost-optimized procurement patterns favor standard-grade additive specifications.
Regulated medical applications defend margin pools; industrial prototyping scales volume.
End User:
Customer scale and qualification requirements differentiate procurement behavior between enterprise formulation partnerships and spot-market purchasing.
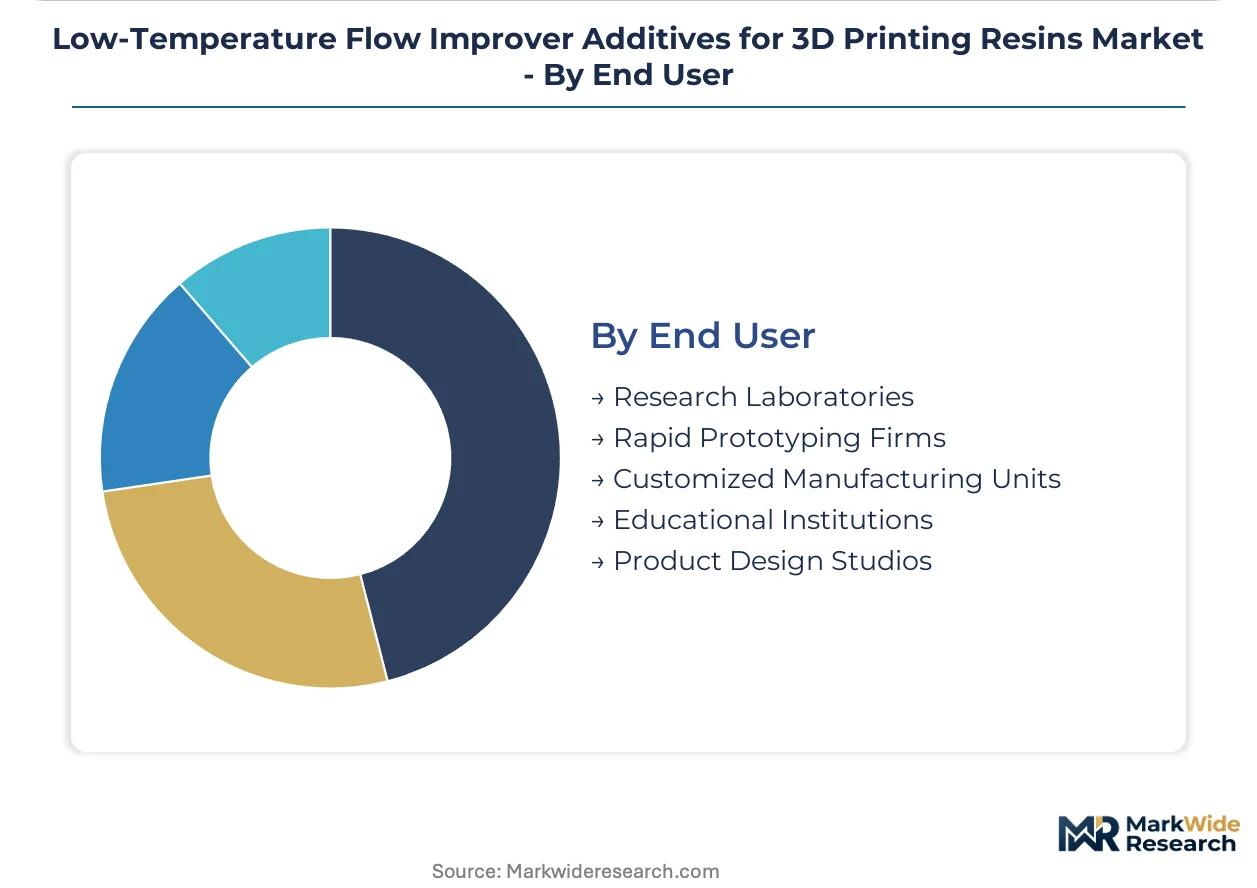
- Rapid Prototyping Firms:These specialized service providers in Michigan's automotive supply basin and Bavaria's industrial corridor are displacing spot-market purchasing with multi-year formulation partnerships tied to ISO/ASTM 52900 certification.
- Customized Manufacturing Units:Production-scale additive operations require validated supply continuity for precision layer deposition workflows.
- Research Laboratories:Experimental resin development drives small-volume demand for novel siloxane architectures.
- Educational Institutions:Training programs utilize standard-grade flow improvers without qualification requirements.
- Product Design Studios:Iterative prototyping workflows prioritize cost-optimized additive procurement.
Enterprise customers consolidate toward qualified suppliers; fragmented buyers remain price-sensitive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites Europe's dominance in specialty additive manufacturing feedstocks, while the Houston Ship Channel anchors North American resin formulation capacity.
Germany
Bavaria's industrial corridor concentrates aerospace prototyping workflows demanding sub-ambient resin handling. ECHA REACH registration thresholds for siloxane chemistries above one-ton annual volumes consolidate supply toward established formulation houses. Munich and Nuremberg anchor precision layer deposition operations for structural component manufacturing.
United States
Michigan's automotive supply basin drives siloxane variant adoption for repeated thermal cycling applications. EPA TSCA Section 5 evaluations constrain novel additive introductions, extending pre-market notification timelines. Detroit and Grand Rapids host expanding additive manufacturing workflows requiring qualified material systems.
China
Shanghai's Yangtze River Delta integrates photopolymerization platform manufacturing with domestic resin formulation. MIIT standards for additive manufacturing materials tighten local qualification requirements. Suzhou and Wuxi cluster dental modeling operations consuming polyether-modified rheology additives.
Japan
Chubu region's precision equipment manufacturers specify low-viscosity resins for fine feature resolution applications. METI industrial technology roadmaps prioritize additive manufacturing material qualification. Nagoya anchors automotive prototyping workflows adopting thermal-stable siloxane chemistries.
South Korea
Seoul Capital Area electronics manufacturers drive material jetting platform proliferation for consumer goods design. MFDS biocompatibility requirements stratify dental resin supply toward qualified formulation houses. Incheon's port infrastructure supports specialty chemical import for photopolymer formulations.
Low-Temperature Flow Improver Additives for 3D Printing Resins Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities, with publicly traded chemical conglomerates leveraging existing toxicological dossiers while independent additive houses navigate certification timelines. The supplier base tiers by ISO/ASTM 52900 qualification status, separating premium formulation partners from commodity producers. Three archetypes dominate: backward-integrated feedstock controllers, specialty chemistry licensors, and regulatory-affairs-heavy formulation houses. Competitive moves concentrate on strategic partnerships for qualification acceleration and portfolio diversification into powder bed fusion additives.
Within the specialty chemistry tier, Evonik Industries and Arkema exemplify European formulation houses with methacrylate and acrylate oligomer specializations. BASF anchors the backward-integrated archetype through captive polyether polyol production. These three companies occupy positions that reflect the market's bifurcation between feedstock control and regulatory navigation capabilities.
| Leading Market Players |
|---|
| Evonik Industries |
| BYK-Chemie |
| BASF |
| Arkema |
| Clariant |
| Dow |
| Lubrizol |
| Croda International |
| Elementis |
| Others |
Pricing and Supply Chain Analysis
Multi-year formulation partnerships tied to ISO/ASTM 52900 certification lock in supply access and price visibility for rapid prototyping firms across Michigan's automotive supply basin and Bavaria's industrial corridor. These contracts insulate qualified suppliers from spot-market volatility while compressing margins for commodity additive producers unable to meet qualification thresholds.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO/ASTM 52900-certified formulation houses from uncertified commodity suppliers. Premium tiers command defensible positioning through FDA 510(k) pathway mastery and REACH dossier completeness, while standard grades compete on polyether-modified compatibility breadth. Cost compression in economy tiers intensifies as fluorinated chemistry substitution forces reformulation investments without equivalent performance alternatives. Dental modeling OEMs exhibit lowest price sensitivity due to biocompatibility validation requirements, whereas consumer goods design studios prioritize cost-optimized procurement.
Supply Chain Analysis
Rotterdam's chemical handling infrastructure underwrites European feedstock security for specialty methacrylate and polyether polyol inputs. BASF's captive polyether polyol production in Germany and Evonik's specialty methacrylate backbone operations anchor regional supply, though EPA TSCA Section 5 evaluations constrain novel siloxane architectures from entering US formulation channels. Single-source vulnerability concentrates in REACH-registered siloxane chemistries above one-ton annual volumes, where established European houses maintain dossier advantages. Distribution runs through direct formulation partnerships with rapid prototyping firms rather than spot-market chemical traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from bio-based rheology modifiers as sustainability mandates tighten across aerospace and dental procurement specifications. Defense requires locking in certification advantages before alternative chemistries achieve equivalent performance validation.
For Market Incumbents: Consolidate regulatory affairs capacity to navigate simultaneous REACH, TSCA, and FDA dossier requirements, compressing certification timelines that strain mid-tier competitors. Deepen backward integration into polyether polyol feedstocks to defend margin flexibility against BASF's captive supply advantages. Prioritize powder bed fusion additive development to capture emerging rheology modifier demand before specialty chemistry licensors establish platform-specific formulations.
For New Entrants and Emerging Players: Lead with siloxane variant specialization for automotive thermal cycling applications in Michigan's automotive supply basin, where incumbent polyether-only suppliers lack equivalent thermal stability performance. Target research laboratory segments for novel architecture validation before scaling toward production-grade qualification. Pursue joint development agreements with material jetting platform manufacturers to embed flow improvers into qualified material systems.
For Investors and Strategic Acquirers: Capital is best deployed toward regulatory-affairs-heavy formulation houses with existing ISO/ASTM 52900 certification and proven FDA 510(k) navigation experience, as these capabilities create durable moats across the analysis window. Acquisition targets should demonstrate backward integration into specialty methacrylate or acrylate oligomer backbones. Monitor ECHA per- and polyfluoroalkyl substance restriction timelines as inflection indicators for fluorinated chemistry substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Expansion | Full toxicological registration for siloxane chemistries above one-ton thresholds locks out unqualified competitors. |
| Powder Bed Fusion Partnership | Platform-specific rheology modifier development captures emerging demand from specialized additive formulations. |
| FDA 510(k) Pathway Investment | Biocompatibility validation capabilities create defensible positioning in dental and medical device resin segments. |
| Feedstock Backward Integration | Captive polyether polyol production insulates margin flexibility from European chemical conglomerate pricing power. |
| Fluorinated Chemistry Substitution Program | Reformulation investment ahead of ECHA restrictions positions suppliers for regulatory-compliant product transitions. |
Research Methodology
A spread of perspectives from resin formulation chemists, additive manufacturing platform engineers, regulatory affairs directors at dental OEMs, and procurement leads at rapid prototyping firms converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ECHA REACH registration databases, EPA TSCA Section 5 pre-manufacture notifications, FDA 510(k) clearance records, and customs trade data for specialty chemical flows. Bottom-up volume estimates triangulated against top-down market sizing derived from photopolymerization platform deployment statistics and resin consumption metrics.
Segmentation dimensions modeled include chemistry family, additive manufacturing technology platform, end-use application, and customer scale tier across the projection horizon. CAGRs were derived from regression analysis of historical platform adoption curves and forward projections of aerospace prototyping expansion in Germany and the United States. Industry-specific forecast inputs incorporated REACH registration timelines, EPA chemical safety evaluation throughput rates, and ISO/ASTM 52900 qualification protocol durations.
The analysis sits within stated boundaries; outcomes outside sustained aerospace prototyping investment levels or accelerated fluorinated chemistry substitution would require recalibration. Forecasts reflect assumptions regarding regulatory compliance trajectory and platform technology adoption patterns. Practitioners should keep alternative scenarios live as ECHA restriction timelines and EPA evaluation priorities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
3D Printing Iron Powder Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
3D Printing High Performance Plastic Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
3D Printing PLA Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Global 3D Printing Filament Market