
 3D Printing High Performance Plastic Market | 2026-2036
3D Printing High Performance Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing High Performance Plastic Market Analysis
Subscription-based material qualification programs is consolidating how high-performance polymer suppliers monetize repeat aerospace and medical orders. Evonik Industries leverages its captive polyamide 12 production to dominate powder bed fusion feedstock supply. Stratasys Ltd. anchors the filament segment through OEM-locked material ecosystems that limit third-party compatibility. Solvay specializes in sulfone-based resins for autoclave-capable printed tooling in automotive prototyping.
3D printing high performance plastic denotes thermoplastic and thermoset formulations engineered for mechanical strength above 80 MPa tensile, thermal stability beyond 150°C continuous service, and chemical resistance in aggressive environments, produced through additive layer deposition rather than conventional injection or compression molding. FDM technology leads installed base volumes but SLS captures margin pools in aerospace-certified powder recycling protocols. Medical Devices application segments command premium pricing through biocompatibility testing burdens that lock out commodity resin competitors. Nylon formulations sustain the broadest technology cross-compatibility across FDM, SLS, and emerging multi-jet fusion platforms.
FDA 21 CFR Part 820 quality system regulations and EU MDR Class IIa device requirements shape material traceability demands for implantable and surgical guide applications. REACH SVHC candidate list expansions force reformulation of flame-retardant additives in European-sold photopolymer resins. Stakeholders must monitor evolving FAA airworthiness certification pathways for printed flight-critical brackets as powder lot consistency becomes the binding constraint on adoption velocity.
Market Dynamics
Flight-critical certification bottlenecks for powder bed fusion components are compressing adoption timelines across aerospace supply chains, forcing material suppliers to absorb qualification costs ahead of revenue recognition.
Growth Catalysts
- REACH SVHC compliance mandates:European flame-retardant reformulations are locking qualified suppliers into long-term aerospace contracts that commodity resin producers cannot penetrate.
- FDM-to-SLS technology migration:Medical device manufacturers are consolidating around selective laser sintering for surgical guides requiring biocompatibility traceability.
- Munich-Frankfurt industrial cluster concentration:Germany's automotive prototyping ecosystem is pulling sulfone-based resin capacity away from general industrial applications.
Market Restraints
- Polyamide 12 feedstock concentration:Captive production by dominant powder suppliers limits second-source availability for aerospace lot qualification.
- Autoclave tooling thermal requirements:Sulfone resin formulations face performance ceilings below 180°C continuous service that carbon fiber composites satisfy.
- FAA airworthiness pathway uncertainty:Printed flight-critical bracket certification timelines extend 18-36 months beyond conventional machined aluminum equivalents.
Strategic Opportunities
- Multi-jet fusion platform expansion:Nylon formulation cross-compatibility is opening medical device production to lower-cost hardware ecosystems.
- Subscription-based material qualification:Recurring revenue models for aerospace lot certification are capturing lifetime value from fleet maintenance programs.
- India PLI scheme for medical devices:Domestic additive manufacturing incentives are attracting powder bed fusion capacity for export-oriented surgical instrument production.
Industry Challenges
- Powder lot consistency protocols:Aerospace-certified recycling standards require metallurgical traceability that strains quality engineering staffing.
- Biocompatibility testing timelines:FDA 21 CFR Part 820 documentation burdens for implantable grades extend product launch cycles by 12-18 months.
- Legacy ERP integration:Additive workflow data formats lack standardization with conventional injection molding MES systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing High Performance Plastic Market |
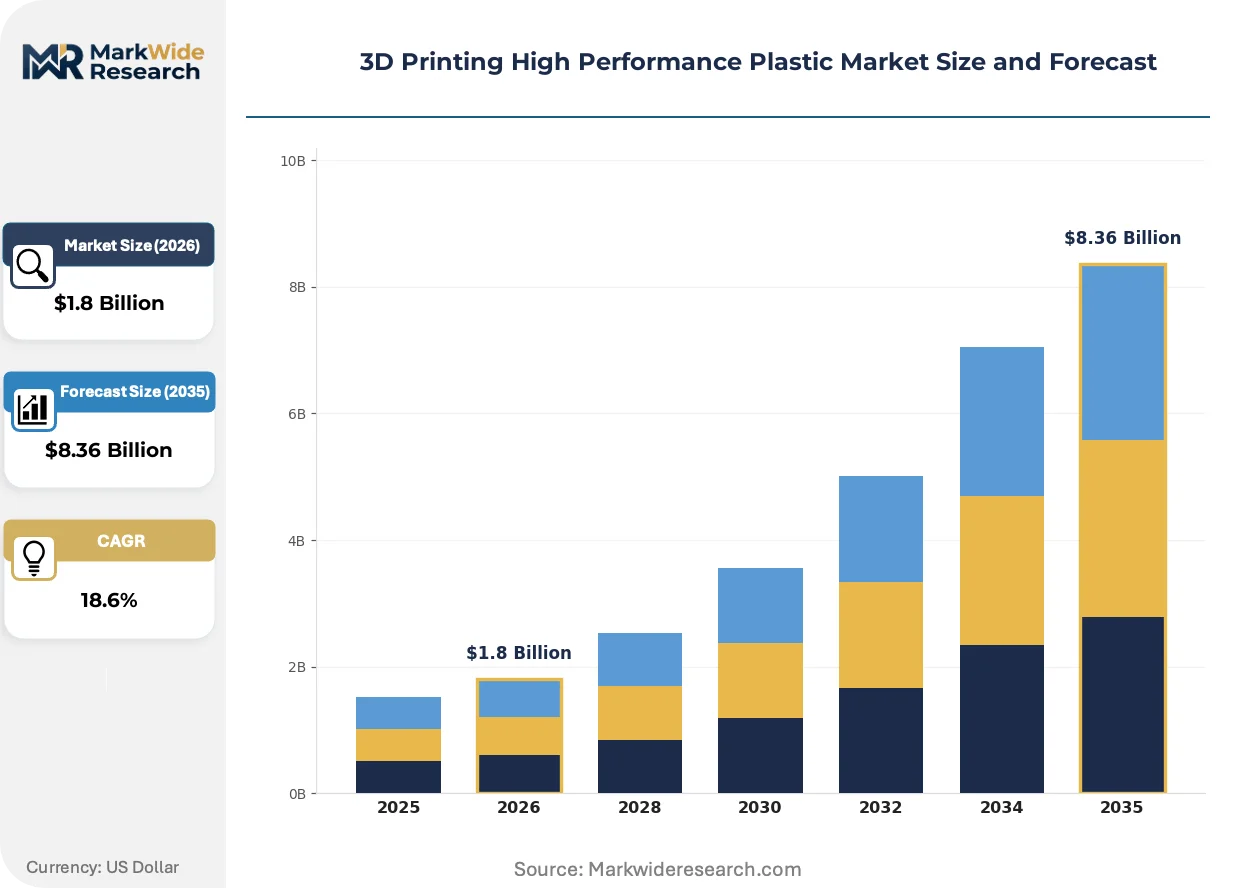
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: ABS, PLA, Nylon, PETG Application: Aerospace, Automotive, Consumer Products, Medical Devices End User: OEMs, R&D Institutions, Prototyping Services, Educational Institutions Technology: FDM, SLS, SLA, DLP |
| Companies Covered | Syensqo, Arkema, Evonik Industries, Stratasys Ltd., 3D Systems Corporation, Markforged, Victrex Plc, Solvay, Oxford Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing High Performance Plastic Market Emerging Trajectories
Process-parameter standardization across hardware OEMs is collapsing material development fragmentation that previously forced suppliers to qualify identical chemistries separately for each printer ecosystem.
Multi-material extrusion heads are unifying structural and soluble support deposition in single-build workflows. Aerospace tooling shops in Germany are adopting these systems for complex duct prototypes that previously required assembled sub-components. The technology is unifying design and manufacturing engineering roles that historically operated in sequential handoffs.
EU MDR Class IIa device requirements are mandating Unique Device Identification traceability down to raw material lots. Surgical guide manufacturers must now maintain batch records linking each printed part to powder production certificates. European notified bodies are backlogging technical file reviews, compressing competitive advantage toward suppliers with established quality system infrastructure.
Hospital procurement departments are consolidating vendor lists around vertically integrated material-to-part suppliers capable of single-source liability. Large health systems in the United States are disqualifying independent 3D printing service bureaus lacking captive resin production. This concentration is visible most acutely in cranial implant contracts where biocompatibility certification costs exceed smaller competitors' annual revenues.
3D Printing High Performance Plastic Market Segmentation
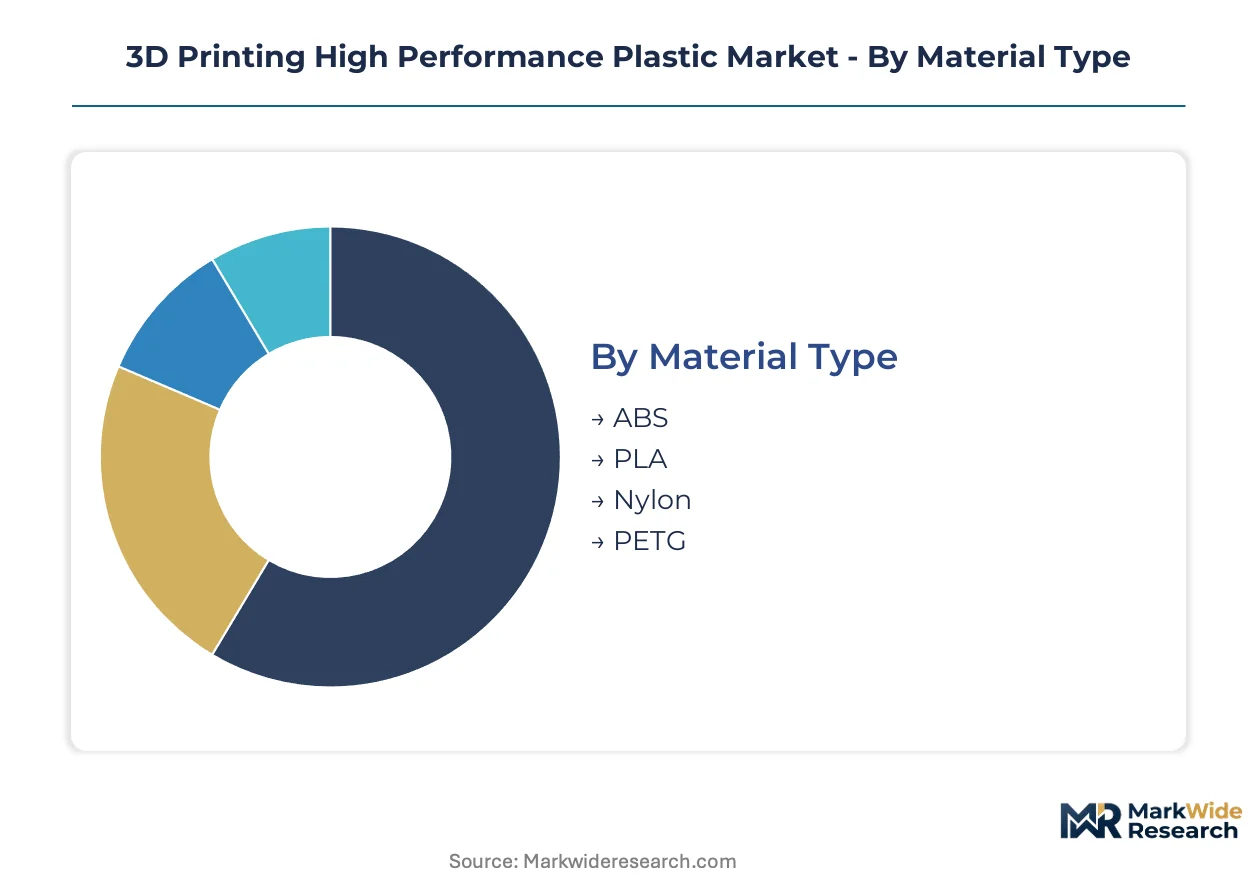
Material qualification protocols and hardware compatibility constraints fragment this market into discrete supply ecosystems. Each segmentation dimension reveals divergent margin structures and certification burdens that reshape supplier competitive positioning.
Material Type:
Volume production concentrates in commodity formulations while premium applications demand engineered thermal and mechanical specifications.
- Nylon:Polyamide formulations deliver the broadest technology cross-compatibility across FDM, SLS, and multi-jet fusion platforms. Medical device manufacturers in Germany's Munich-Frankfurt cluster specify Nylon 12 for surgical guides requiring REACH-compliant lot traceability.
- ABS:Acrylonitrile butadiene styrene serves as the workhorse filament for functional prototyping and end-use parts in automotive ducting applications. Stratasys Ltd. locks ABS formulations into proprietary cartridge systems that limit third-party hardware compatibility.
- PLA:Polylactic acid dominates educational and consumer entry-level printing due to low-temperature processing requirements.
- PETG:Polyethylene terephthalate glycol balances chemical resistance with printability for food-contact and medical packaging prototypes.
Mature deployment sits with ABS across general industrial prototyping. Newer deployment is concentrated in Nylon for aerospace-certified powder bed fusion applications.
Application:
Regulatory certification intensity separates premium-tier segments from volume production categories.
- Medical Devices:Implantable and surgical guide applications command the steepest biocompatibility testing burdens under FDA 21 CFR Part 820 and EU MDR Class IIa requirements. Hospital procurement departments now disqualify vendors lacking captive resin production and raw material lot traceability.
- Aerospace:Flight-critical bracket and duct applications require FAA airworthiness certification pathways extending 18-36 months beyond conventional machined aluminum timelines. Powder lot consistency protocols and metallurgical traceability strain quality engineering staffing across supply chains.
- Automotive:Sulfone-based resin tooling for autoclave-capable prototypes pulls capacity toward Germany's automotive prototyping ecosystem.
- Consumer Products:Non-load-bearing applications tolerate commodity resin specifications with minimal regulatory overhead.
Established revenue concentration resides in Automotive prototyping services. Expanding most quickly is Medical Devices as hospital systems consolidate vendor lists around vertically integrated material-to-part suppliers.
End User:
Procurement authority and technical specification control determine segment access to qualified material supply.
- OEMs:Original equipment manufacturers in aerospace and medical device verticals lock suppliers into long-term material qualification programs with subscription-based recurring revenue structures. Boeing and Airbus tier-1 suppliers now mandate powder bed fusion feedstock from captive polyamide 12 production sources.
- Prototyping Services:Independent service bureaus face disqualification from large health system vendor lists due to liability concentration requirements and lack of in-house resin production.
- R&D Institutions:University and national laboratory research programs drive early-stage material formulation development ahead of commercial qualification.
- Educational Institutions:Technical training programs standardize on FDM hardware and commodity filament for workforce development curricula.
Revenue stability clusters with OEMs through fleet maintenance and production part approval programs. Emerging demand is shifting toward Prototyping Services that achieve vertical integration into captive resin production.
Technology:
Hardware installed base and margin capture diverge between filament deposition and powder fusion ecosystems.
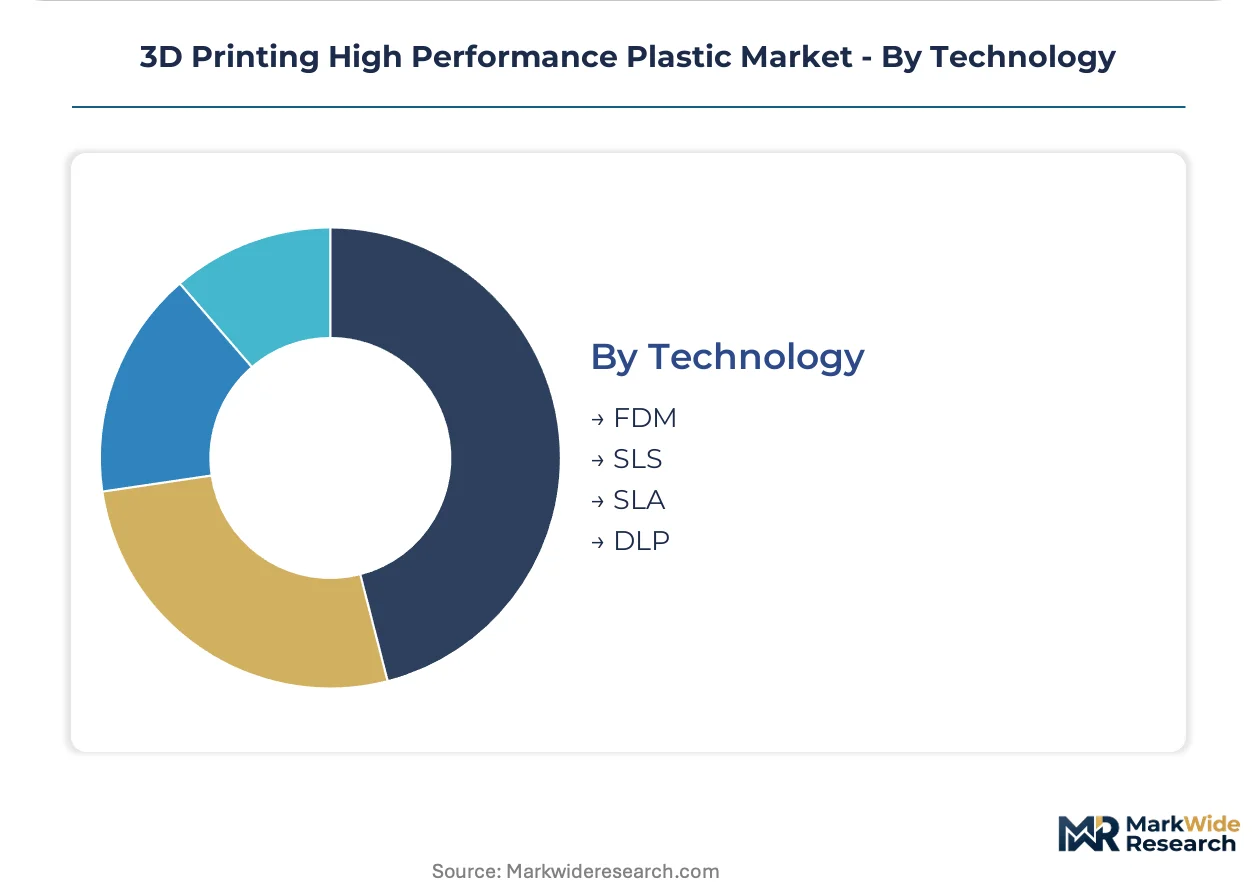
- FDM:Fused deposition modeling leads installed base volumes globally but faces margin compression from commodity filament competition. Stratasys Ltd. anchors this segment through OEM-locked material ecosystems.
- SLS:Selective laser sintering captures premium margin pools in aerospace-certified powder recycling protocols. Medical device manufacturers are consolidating around SLS for surgical guides requiring biocompatibility traceability.
- SLA:Stereolithography photopolymer resins face REACH SVHC-driven reformulation of flame-retardant additives for European market access.
- DLP:Digital light processing offers speed advantages for dental and hearing aid production with specialized acrylate formulations.
Installed capacity dominance remains with FDM across educational and entry-level industrial applications. Climbing the fastest is SLS as powder bed fusion platforms penetrate flight-critical and implantable device production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany's industrial corridor while consumption spreads across aerospace clusters in the United States and medical device manufacturing in India. Powder bed fusion feedstock capacity clusters around captive polyamide 12 producers in Western Europe. Certification timelines stretch longest in North American aviation supply chains.
United States
FAA airworthiness certification for flight-critical brackets drives 18-36 month qualification timelines that lock aerospace OEMs into pre-qualified material suppliers. FDA 21 CFR Part 820 quality system regulations mandate raw material lot traceability for implantable device production. Boeing and Airbus tier-1 suppliers in Washington State and Texas now specify powder bed fusion feedstock from single-source polyamide producers.
Germany
REACH SVHC compliance mandates for flame-retardant reformulations lock qualified suppliers into long-term aerospace contracts unreachable by commodity resin competitors. ECHA substance restrictions force continuous reformulation of photopolymer resins for European market access. The Munich-Frankfurt industrial cluster pulls sulfone-based resin capacity toward automotive prototyping applications.
India
Domestic additive manufacturing incentives under the PLI scheme for medical devices attract powder bed fusion capacity for export-oriented surgical instrument production. CDSCO medical device regulations align with EU MDR traceability requirements for hospital procurement qualification. Maharashtra and Gujarat host emerging service bureaus targeting European surgical guide markets.
China
MIIT industrial additive manufacturing roadmaps prioritize high-performance polymer development for aerospace substitution programs. NMPA medical device registration pathways extend biocompatibility documentation timelines for imported resin grades. Yangtze River Delta manufacturing hubs concentrate filament production for consumer and educational hardware ecosystems.
Japan
METI advanced manufacturing initiatives fund multi-jet fusion platform adoption for precision medical device prototyping. PMDA quality management system inspections enforce batch record standards comparable to FDA 21 CFR Part 820. Kansai region industrial clusters specialize in dental and hearing aid production using specialized acrylate formulations.
3D Printing High Performance Plastic Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures. Polyamide 12 manufacturers with captive powder production command aerospace qualification premiums while filament distributors face commodity pricing pressure. Three archetypes dominate: integrated chemical conglomerates with resin-to-powder pipelines, hardware-locked material ecosystems, and specialized sulfone resin formulators. Consolidation accelerates through subscription-based qualification programs and backward integration into raw material production.
Among European chemical conglomerates, Evonik Industries and Solvay occupy positions anchoring distinct technology vectors. Evonik exemplifies the captive feedstock archetype through polyamide 12 production integration. Solvay represents specialization in high-temperature sulfone formulations. Stratasys Ltd. sits within the hardware-locked ecosystem tier, illustrating filament segment control through OEM-proprietary cartridge systems. These three patterns illustrate how supplier positioning fragments across powder bed fusion and fused deposition modeling technology boundaries.
| Leading Market Players |
|---|
| Syensqo |
| Arkema |
| Evonik Industries |
| Stratasys Ltd. |
| 3D Systems Corporation |
| Markforged |
| Victrex Plc |
| Solvay |
| Oxford Performance Materials |
| Others |
Supply Flow & Price Mechanics
Hospital procurement consolidation around single-source liability suppliers is forcing independent service bureaus to either build captive resin production or exit implantable device contracts, compressing margins for non-integrated players while rewarding backward-integrated material-to-part suppliers with pricing power.
Pricing Analysis
Margin tightening in aerospace-certified powder grades reflects polyamide 12 feedstock concentration and 18-36 month FAA qualification timelines that lock buyers into sole-source contracts. Three-tier pricing structure across flight-critical, medical-grade, and industrial prototyping levels separates segments by certification burden and traceability depth. Cost-down pressure on commodity filament accelerates because Stratasys OEM-locked ecosystems limit third-party hardware compatibility. Medical device OEMs show least price sensitivity due to biocompatibility testing barriers that exclude cheaper alternatives.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale aerospace and medical device demand, while distributor networks serve fragmented prototyping services. Captive polyamide 12 production clusters in Germany, with secondary sulfone resin capacity in Belgium and emerging powder bed fusion feedstock operations in India. Supply chains draw from petrochemical precursors, laser sintering hardware components, and metallurgical testing services. Single-source vulnerability in aerospace lot qualification strains tier-1 supplier resilience. Distribution runs through qualified material programs with subscription-based recurring revenue structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around material qualification infrastructure that smaller competitors cannot replicate, with FDA 21 CFR Part 820 and EU MDR traceability mandates accelerating exits among non-integrated service bureaus.
For Market Incumbents: Hedge against powder lot consistency bottlenecks by securing captive polyamide 12 production in Germany's Munich-Frankfurt corridor and pre-qualifying alternative feedstock sources ahead of REACH SVHC expansions. Absorb upfront aerospace certification costs to lock tier-1 suppliers into long-term subscription programs that capture fleet maintenance lifetime value. For New Entrants and Emerging Players: Begin with India's PLI-subsidized medical device manufacturing zones, where CDSCO-aligned traceability requirements and lower qualification overhead create accessible entry points for export-oriented surgical instrument production. Target sulfone-based resin tooling gaps in automotive prototyping where autoclave-capable formulations face performance ceilings. For Investors and Strategic Acquirers: The window for entry favors vertically integrated material-to-part suppliers with established FDA and EU MDR quality systems, as hospital vendor consolidation disqualifies asset-light competitors. Watch powder bed fusion platform adoption rates in flight-critical applications as the inflection signal for aerospace qualification backlog clearing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide 12 Production | Evonik's captive feedstock model locks tier-1 aerospace suppliers into sole-source powder contracts. |
| Subscription-Based Material Qualification Programs | Recurring revenue structures capture lifetime value from Boeing and Airbus fleet maintenance programs. |
| REACH SVHC Compliance Investment | ECHA-mandated flame-retardant reformulations lock qualified suppliers into long-term aerospace contracts. |
| Multi-Jet Fusion Platform Expansion | Nylon formulation cross-compatibility opens medical device production to lower-cost hardware ecosystems. |
| India PLI Scheme Manufacturing Footprint | Domestic additive incentives attract powder bed fusion capacity for export-oriented surgical instrument production. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with powder bed fusion hardware engineers, aerospace tier-1 procurement leads, medical device quality affairs directors, and hospital GPO contracts managers. Bottom-up modeling of material consumption by technology platform and application segment triangulated against top-down chemical industry production data from ECHA substance registrations and FDA 510(k) submission databases.
Segment-level granularity modeled material type, application regulatory intensity, end-user procurement authority, and technology hardware compatibility across the analysis window. CAGRs derived from production capacity expansion announcements, qualified supplier program wins, and fleet maintenance contract values. Forecast inputs included FAA airworthiness certification pipeline backlogs and EU MDR notified body review timelines.
REACH SVHC list expansions, FAA certification pathway delays, and hospital procurement vendor consolidation are the dominant revision risks to forecast assumptions. Practitioners should monitor powder lot consistency protocol adoption and biocompatibility testing backlog clearing for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Iron Powder Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
Polypropylene in 3D Printing Market
3D Printing Materials
3D Printing PLA Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Thermoformed Plastics for Printing Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
3D Printing Powder Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
3D Printing Materials Market