
 Patterning Materials Market | 2026-2036
Patterning Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Patterning Materials Market Outlook
Market Context
REACH is recalibrating the cost-of-entry calculus for fluorinated photoresist suppliers serving European semiconductor customers. Dow Electronic Materials leverages its integrated monomer-to-resist supply chain to sustain formulation agility under evolving chemical restrictions. Tokyo Ohka Kogyo anchors its competitive position through deep specialization in chemically amplified resists for advanced lithography nodes. JSR Corporation differentiates via its technology leadership in EUV-sensitive polymer platforms.
Technical Definition and Segment Structure
Patterning materials encompass radiation-sensitive formulations that undergo selective solubility changes upon exposure, enabling the transfer of circuit geometries onto silicon wafers and substrates through subsequent development and etch processes. These materials typically comprise photoactive compounds, polymer binders, and solvent carriers engineered for specific wavelengths from i-line through EUV. Photoresists command the dominant value share within material type segmentation, while etch resists represent the fastest-growing category as multi-patterning schemes proliferate at sub-7nm nodes. Semiconductor applications absorb the majority of demand volume, though MEMS patterning requirements are expanding as automotive sensor content rises.
Regulatory Frame and Outlook
EPA oversight of perfluorinated compound emissions, REACH substance restrictions, and Japan's METI chemical management framework collectively reshape formulation roadmaps and supplier qualification protocols. EMA chemical safety assessments and Korea's MFDS manufacturing standards further complicate multi-regional product registration for resist manufacturers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in global wafer fabrication supply chains.
Market Dynamics
EUV lithography maturation at sub-7nm nodes is compressing qualification timelines for photoresist suppliers while simultaneously expanding the performance envelope required of radiation-sensitive formulations. Taiwan Semiconductor Manufacturing and Samsung Foundry procurement specifications now demand sub-1nm line-edge roughness thresholds that strain incumbent polymer architectures.
Growth Catalysts
- EUV infrastructure buildout:Semiconductor foundries in Taiwan and South Korea are commissioning high-NA EUV scanners that require entirely new resist platforms with enhanced photospeed and etch resistance.
- REACH substance restrictions:The EU's phased limitations on per- and polyfluoroalkyl substances are accelerating reformulation investment among suppliers serving European automotive and logic chip customers.
- Multi-patterning proliferation:Self-aligned quadruple patterning schemes at advanced DRAM nodes are expanding consumption of etch resists and hard mask materials beyond traditional photoresist volumes.
Market Restraints
- Fluorinated monomer supply concentration:Three Japanese chemical houses control the majority of perfluorinated building blocks essential for high-NA EUV resists, creating single-source vulnerability.
- Photoresist input cost volatility:Specialty cyclic olefin monomer prices fluctuate with cracker feedstock availability, compressing formulation margins during petrochemical cycle peaks.
- EUV sensitivity-stability tradeoff:Enhanced photospeed requirements degrade resist shelf stability, forcing cold-chain logistics investments that inflate delivered costs.
Strategic Opportunities
- India semiconductor fabrication:Micron Technology's Gujarat assembly and test facility creates qualification pathways for patterning materials suppliers seeking entry into India's emerging wafer ecosystem.
- Automotive sensor MEMS:LiDAR and radar module content expansion is generating demand for thick-film resists capable of patterning high-aspect-ratio microstructures.
- Japan METI domestic production incentives:Subsidies for critical material localization are creating captive demand opportunities for resist manufacturers establishing Japanese manufacturing presence.
Industry Challenges
- EUV resist formulation talent scarcity:The intersection of polymer science, photochemistry, and lithography engineering requires specialists that semiconductor materials programs produce insufficiently.
- Fab qualification timeline compression:Leading-edge foundries now demand 18-month resist qualification cycles versus historical 36-month windows, straining R&D-to-production handoffs.
- Cross-jurisdictional substance registration:Divergent EPA, ECHA, and METI chemical inventories force parallel compliance investments that fragment R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patterning Materials Market |
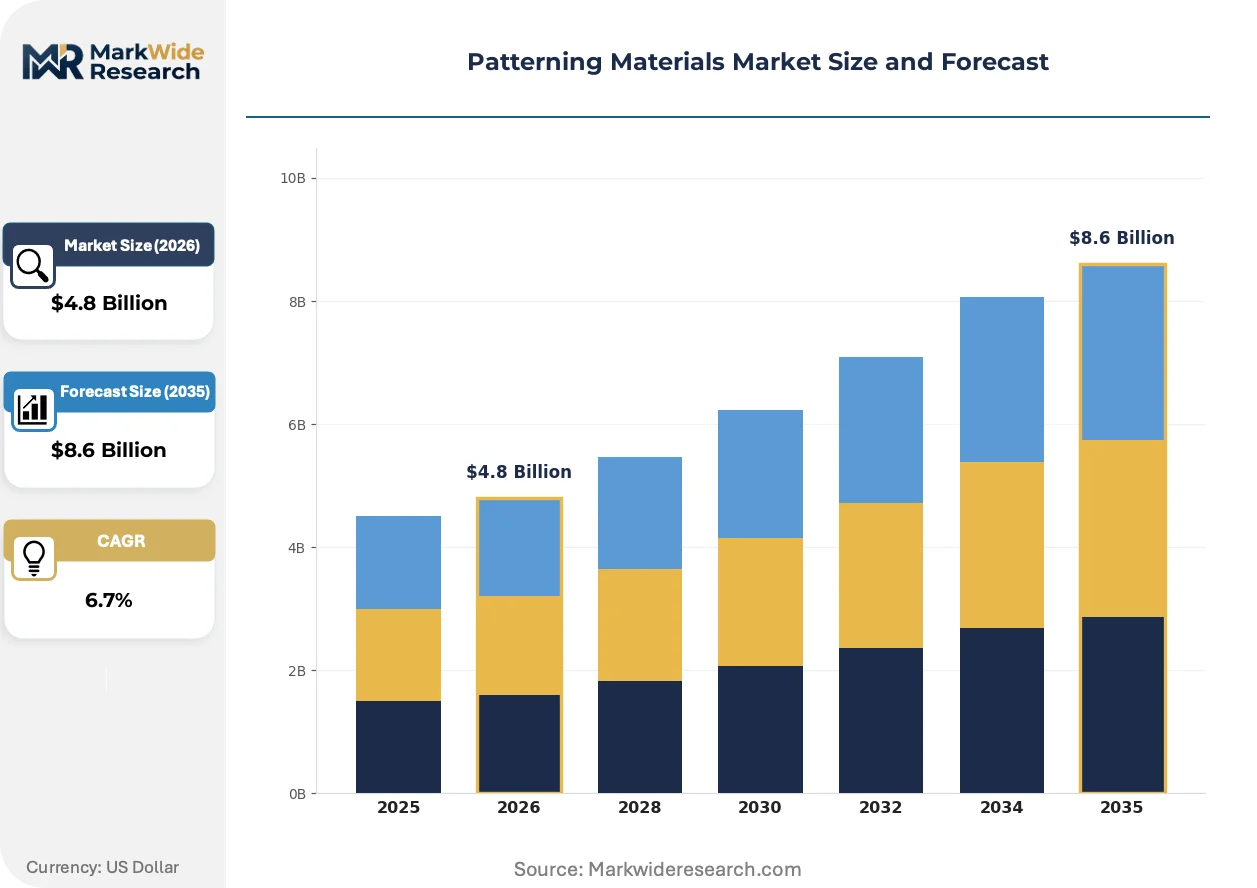
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Photoresists, Etch Resists, Dry Films, Liquid Films Application: Semiconductors, MEMS, Printed Circuit Boards, Solar Cells End User: Electronics Manufacturers, Automotive OEMs, Aerospace Industry, Medical Device Makers Form Factor: Liquid, Solid, Gel, Powder |
| Companies Covered | Dow Electronic Materials, Fujifilm Electronic Materials, Tokyo Ohka Kogyo Co., Ltd., Dongjin Semichem Co., Ltd., DuPont de Nemours, Inc., Shin-Etsu Chemical Co., Ltd., Merck KGaA, Sumitomo Chemical Co., Ltd., JSR Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patterning Materials Market Strategic Shifts
Photoresist chemistry is pivoting from incremental wavelength adaptation toward fundamental architectural reinvention as EUV source power and numerical aperture advance in lockstep. Formulation science now prioritizes stochastic defect suppression alongside traditional resolution metrics.
Metal oxide resists are absorbing the highest-value EUV patterning assignments previously reserved for chemically amplified organic platforms. Memory manufacturers at Samsung and SK Hynix are piloting tin-oxide nanoparticle formulations for 3D NAND string stacking applications. This technology is absorbing market value from incumbent polymer resists by delivering superior etch selectivity and reduced line-edge roughness at sub-30nm pitch.
REACH Annex XVII restrictions on perfluoroalkyl substances are forcing molecular redesign across fluorinated photoresist portfolios. ECHA's 2023 PFAS restriction proposal threatens broad classes of immersion topcoats and antireflective coatings that rely on fluorinated surface energy control. European logic and memory fabs are accelerating qualification of silicone-based alternatives that sacrifice some performance for regulatory compliance certainty.
Consolidated procurement through foundry-level master service agreements is displacing tool-specific resist purchasing. Taiwan Semiconductor Manufacturing and Intel Foundry Services now negotiate enterprise-wide formulation supply contracts that bundle multiple technology nodes. South Korean memory houses are following this model, compressing supplier count from six to three qualified vendors per resist category.
Patterning Materials Market Segmentation
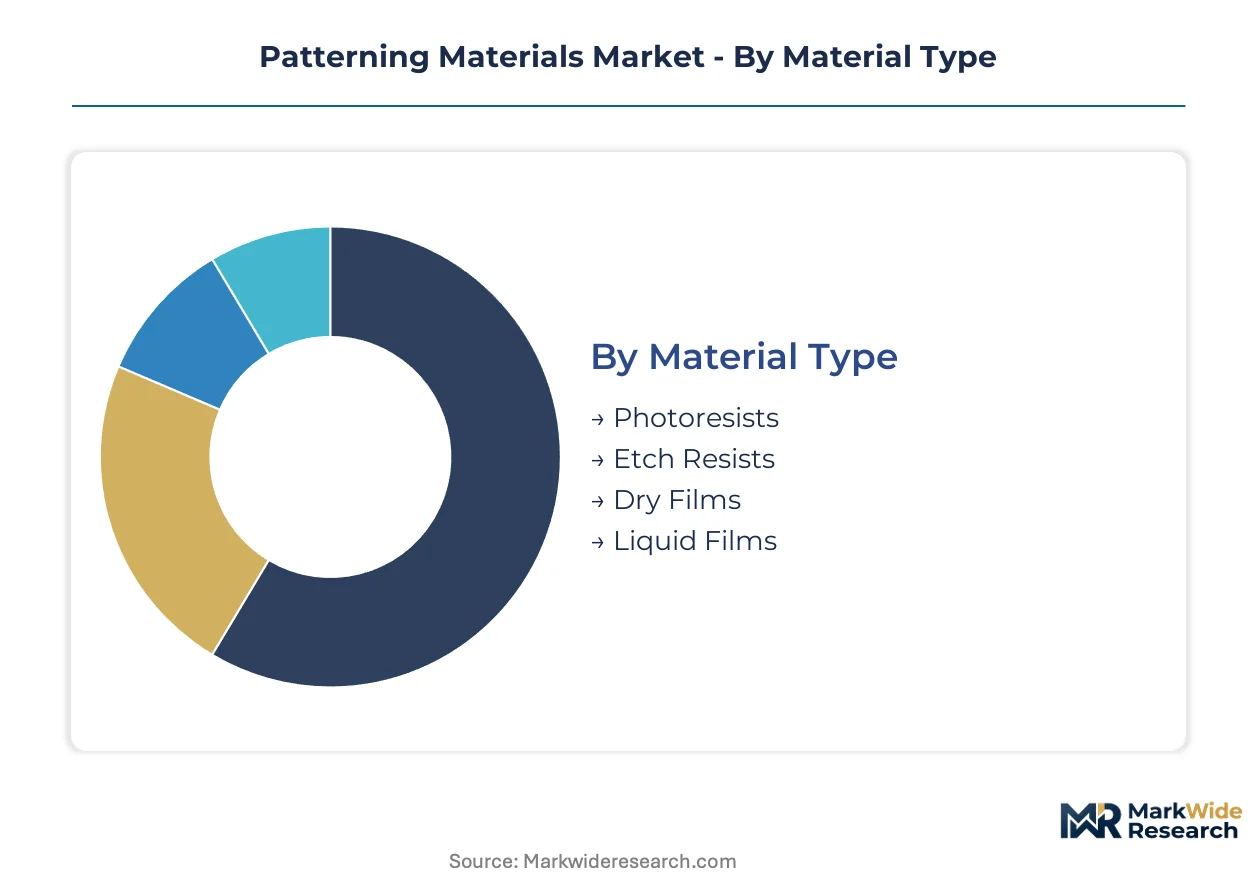
Patterning materials serve distinct process steps across wafer fabrication, packaging, and substrate manufacturing. Segment boundaries reflect formulation chemistry, deposition method, and end-use performance thresholds that resist suppliers must navigate simultaneously.
Material Type:
Standalone photoresist formulations dominate lithography-intensive applications, while etch resists and film formats embed into multi-patterning stacks where integration depth determines value capture.
- Photoresists:Radiation-sensitive polymer systems incorporating photoacid generators and dissolution inhibitors, tuned for wavelengths from i-line through EUV. Taiwan Semiconductor Manufacturing and Samsung Foundry procurement specifications now demand sub-1nm line-edge roughness thresholds that strain incumbent polymer architectures at leading-edge logic nodes.
- Etch Resists:Hard mask and sacrificial layer materials that transfer patterns through subsequent plasma etching rather than direct optical exposure. Self-aligned quadruple patterning schemes at advanced DRAM nodes are expanding consumption of etch resists beyond traditional photoresist volumes at Samsung and SK Hynix.
- Dry Films:Photopolymer sheets laminated onto substrates for printed circuit board and MEMS applications.
- Liquid Films:Spin-coatable formulations for thick-resist requirements in 3D packaging and bump metallization.
Volume placements concentrate in photoresists; the faster expansion belongs to etch resists.
Application:
Cost tiers separate high-value wafer-level patterning from substrate and component applications where throughput economics dominate material selection.
- Semiconductors:Front-end-of-line and back-end-of-line lithography for logic, memory, and power devices. EUV infrastructure buildout at sub-7nm nodes is compressing qualification timelines while expanding the performance envelope required of radiation-sensitive formulations.
- MEMS:Micromechanical structure patterning for sensors, actuators, and microfluidics. LiDAR and radar module content expansion in automotive platforms is generating demand for thick-film resists capable of patterning high-aspect-ratio microstructures.
- Printed Circuit Boards:Trace and via formation in high-density interconnect substrates.
- Solar Cells:Metallization grid patterning for photovoltaic cell efficiency optimization.
Revenue margins peak in semiconductors; MEMS patterning requirements are climbing the fastest as automotive sensor content rises.
End User:
Customer type determines formulation service intensity, with captive foundries demanding co-development partnerships that merchant suppliers cannot replicate.
- Electronics Manufacturers:Integrated device manufacturers and OSATs consuming the majority of patterning material volume. Consolidated procurement through foundry-level master service agreements is displacing tool-specific resist purchasing as Taiwan Semiconductor Manufacturing negotiates enterprise-wide formulation supply contracts.
- Automotive OEMs:Tier-1 and OEM in-house sensor fabrication driving MEMS resist demand. REACH substance restrictions are accelerating reformulation investment among suppliers serving European automotive chip customers.
- Aerospace Industry:Radiation-hardened and high-reliability device fabrication with extended qualification protocols.
- Medical Device Makers:Biocompatible and implantable electronics with specialized cleanliness requirements.
Procurement scale concentrates with electronics manufacturers; automotive OEM direct purchasing is gaining share fastest as sensor verticalization proceeds.
Form Factor:
Maturity curves separate established liquid delivery systems from solid and gel formats emerging in additive manufacturing and specialty deposition contexts.
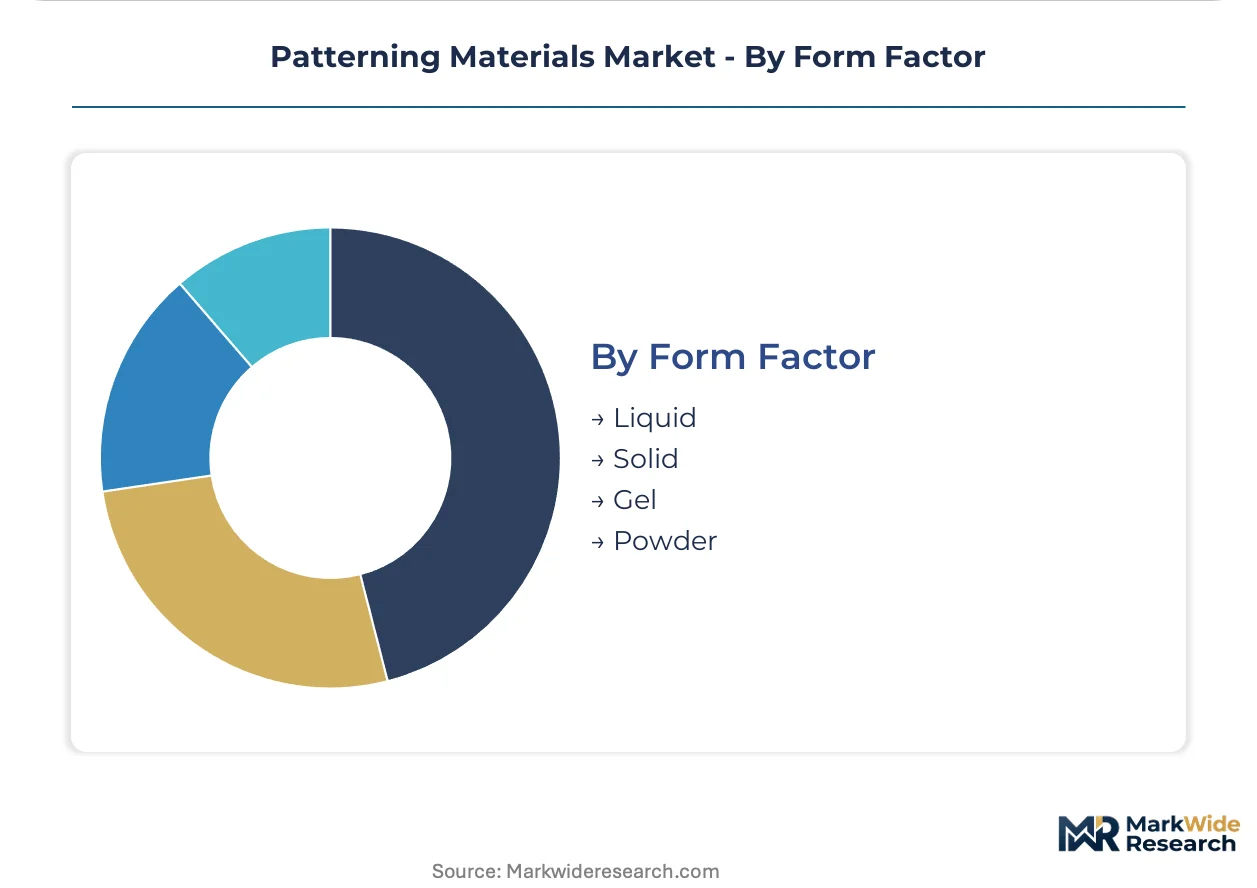
- Liquid:Spin-on and spray-applied formulations comprising the vast majority of semiconductor and PCB consumption. Enhanced photospeed requirements degrade resist shelf stability, forcing cold-chain logistics investments that inflate delivered costs for high-performance liquid resists.
- Solid:Dry film and sheet formats for lamination-based patterning. Dry film photoresists serve PCB and MEMS applications where thickness uniformity across large substrates exceeds liquid coating capabilities.
- Gel:Specialty conformal coatings for 3D structures and non-planar substrates.
- Powder:Additive manufacturing feedstocks and specialty deposition precursors in early commercialization.
Shipments concentrate in liquid formulations; solid format adoption is expanding most quickly in high-density interconnect substrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication clusters in Taiwan and South Korea absorb the dominant share of advanced photoresist consumption, while regulatory divergence across jurisdictions forces suppliers to maintain parallel formulation portfolios.
Taiwan
TSMC's Hsinchu Science Park expansion drives EUV resist qualification at sub-3nm nodes. The island's EPA enforces strict perfluorinated compound emission protocols that exceed baseline international standards. Taichung's Central Taiwan Science Park hosts secondary wafer fabrication capacity where high-NA EUV scanner installation accelerates material demand.
South Korea
Samsung Foundry and SK Hynix procurement specifications compress resist supplier qualification timelines to eighteen months. MFDS manufacturing standards mandate batch-level traceability for photoresist chemistries used in medical-grade semiconductor applications. Pyeongtaek's semiconductor cluster anchors the nation's leading-edge memory fabrication footprint.
Japan
JSR Corporation and Tokyo Ohka Kogyo anchor domestic resist production serving global foundry customers. METI's chemical management framework subsidizes critical material localization to reduce import dependency. Kyushu's Fukuoka Prefecture concentrates specialty monomer manufacturing facilities that feed upstream resist supply chains.
United States
Intel Foundry Services negotiates enterprise-wide formulation contracts bundling multiple technology nodes. EPA oversight of perfluorinated compound emissions forces reformulation investment for suppliers serving Arizona and Oregon fabrication facilities. Greater Phoenix anchors the nation's most significant greenfield wafer fabrication investment this decade.
Germany
Infineon Technologies and Bosch semiconductor operations drive automotive-grade resist demand with extended reliability requirements. ECHA's REACH Annex XVII restrictions on PFAS substances accelerate silicone-based alternative qualification across European logic and memory fabs. Dresden's Silicon Saxony cluster hosts the continent's densest concentration of wafer fabrication capacity.
Patterning Materials Market Competitive Environment
Japanese producers anchor the premium resist tier; American and European chemical conglomerates hold diversified portfolios across adjacent electronic materials. The vendor base stratifies between integrated monomer-to-resist suppliers and formulation specialists dependent on external feedstock. Three strategic archetypes dominate: captive foundry partnerships, multi-node qualification specialists, and regional cost-optimized suppliers. Consolidated procurement through master service agreements and backward integration into specialty monomer production represent the dominant competitive vectors reshaping supplier relationships.
Within the integrated supply chain tier, Dow Electronic Materials exemplifies monomer-to-resist vertical control, while Tokyo Ohka Kogyo Co., Ltd. occupies a position as a chemically amplified resist specialist. JSR Corporation anchors the EUV-sensitive polymer platform segment. These three entities represent distinct strategic postures: diversified chemical conglomerate, deep lithography specialization, and advanced polymer architecture leadership respectively.
| Leading Market Players |
|---|
| Dow Electronic Materials |
| Fujifilm Electronic Materials |
| Tokyo Ohka Kogyo Co., Ltd. |
| Dongjin Semichem Co., Ltd. |
| DuPont de Nemours, Inc. |
| Shin-Etsu Chemical Co., Ltd. |
| Merck KGaA |
| Sumitomo Chemical Co., Ltd. |
| JSR Corporation |
| Others |
Value Chain & Pricing Dynamics
Foundry-level master service agreements at Taiwan Semiconductor Manufacturing and Samsung Foundry compress supplier margins through volume-commitment pricing while rewarding formulation co-development partnerships with premium positioning. Cold-chain logistics investments for EUV resist shelf stability inflate delivered costs, forcing suppliers to absorb logistics premiums or pass through to captive foundry customers.
Pricing Analysis
Short lead-time premiums dominate spot procurement for etch resists and hard mask materials during high-NA EUV scanner ramp phases at leading-edge nodes. Three-tier pricing structure across EUV-sensitive polymer platforms, mature-node chemically amplified resists, and commodity i-line formulations separates performance tiers by line-edge roughness thresholds and qualification status. Cost compression in fluorinated resist portfolios intensifies as ECHA REACH Annex XVII restrictions force parallel silicone-based alternative development. Merchant suppliers serving OSATs and legacy node fabs exhibit highest price sensitivity; integrated monomer-to-resist suppliers with captive foundry partnerships command lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Taichung, Pyeongtaek, and Fukuoka Prefecture anchor hub-and-spoke replenishment patterns for just-in-time resist delivery to wafer fabrication clusters. Manufacturing concentration in Japan, South Korea, and Taiwan draws from specialty cyclic olefin monomer and perfluorinated building block feedstocks controlled by three Japanese chemical houses. Single-source vulnerability in fluorinated monomer supply creates structural risk for high-NA EUV resist qualification timelines. Distribution runs through foundry-approved chemical management systems with batch-level traceability mandated by Korea MFDS and Japan METI frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
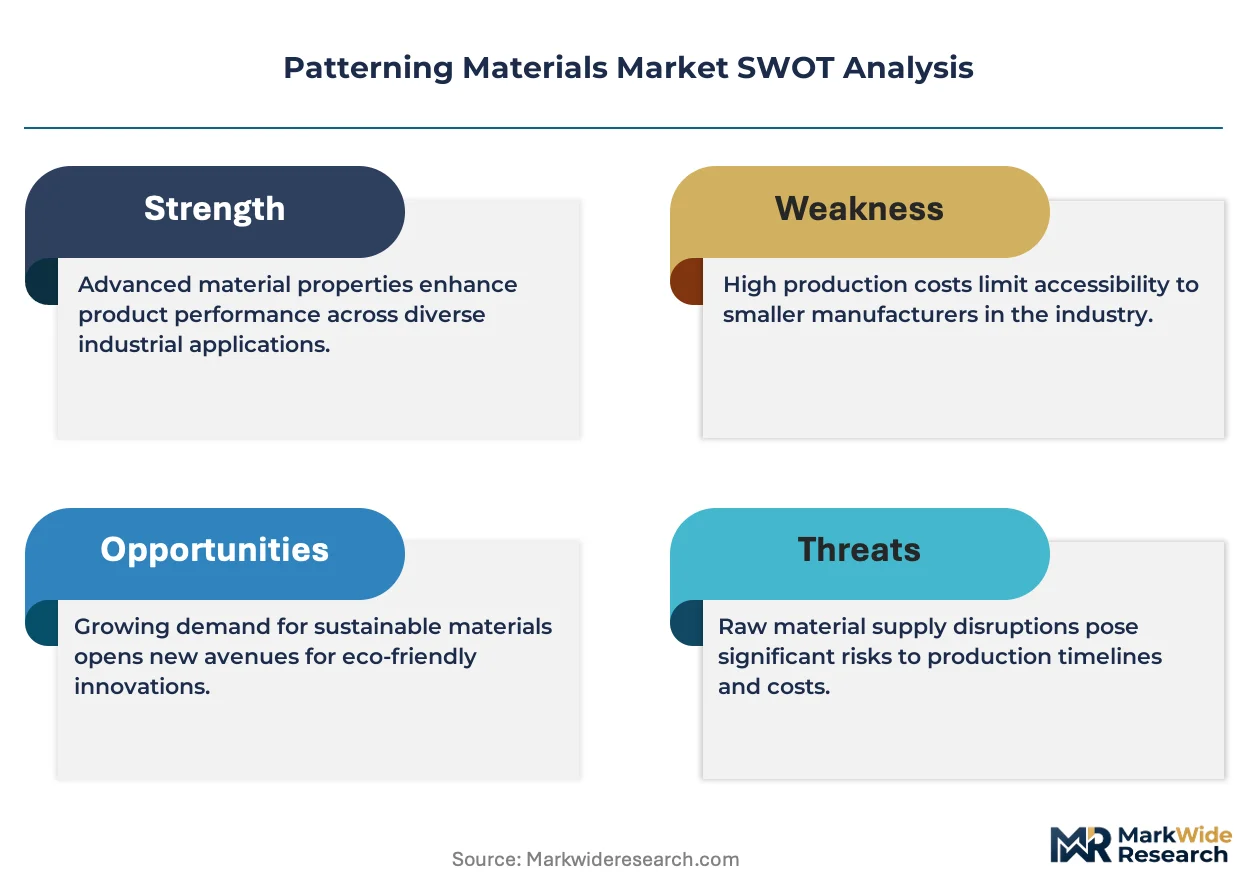
This market functions as a vertical-integration race where backward integration into specialty monomer production and forward integration into foundry co-development partnerships determine margin capture. Players securing captive supply of perfluorinated building blocks or EUV-sensitive polymer architectures gain irreversible positioning advantages.
For Market Incumbents: Cement formulation agility through monomer-to-resist supply chain control as REACH substance restrictions and EPA perfluorinated compound oversight accelerate molecular redesign cycles. Deepen foundry-level master service agreement penetration to lock out merchant competitors during EUV node transitions. Prioritize R&D investment in metal oxide resist platforms to defend against tin-oxide nanoparticle substitution at Samsung and SK Hynix. For New Entrants and Emerging Players: Direct-to-foundry digital qualification portals offer lower-friction entry paths than traditional tool-specific resist procurement channels dominated by incumbent formulation specialists. Target India's emerging semiconductor fabrication ecosystem around Micron Technology's Gujarat facility where supplier qualification pathways remain uncongested. Pursue automotive sensor MEMS applications for thick-film resists as LiDAR and radar content expansion outpaces established supplier capacity. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty monomer manufacturers with captive fluorinated chemistry capabilities in Kyushu's Fukuoka Prefecture during petrochemical feedstock volatility windows. Long-term viability hinges on exposure to EUV infrastructure buildout rather than mature-node commoditization. Monitor high-NA EUV scanner installation announcements at TSMC and Intel Foundry Services as inflection indicators for resist platform refresh demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Captive supply of perfluorinated building blocks insulates margins from Japanese chemical house concentration. |
| Foundry Co-Development Partnerships | TSMC and Samsung Foundry procurement specifications now demand 18-month qualification cycles with embedded formulation collaboration. |
| Metal Oxide Resist Platform Launch | Tin-oxide nanoparticle formulations at Samsung and SK Hynix absorb value from incumbent polymer architectures. |
| Regional Distribution Center Expansion | Taichung and Pyeongtaek hubs reduce cold-chain logistics premiums for EUV resist shelf stability requirements. |
| Silicone-Based Alternative Qualification | ECHA REACH Annex XVII PFAS restrictions force silicone-based immersion topcoat development for European logic fabs. |
Study Parameters
Trade databases, SEC filings from electronic materials suppliers, and ECHA regulatory submission records formed the secondary backbone for supply-side calibration. Primary interviews with photoresist formulation directors, foundry procurement managers at Taiwan Semiconductor Manufacturing and Samsung Foundry, and specialty monomer plant managers in Fukuoka Prefecture provided demand-side validation. Bottom-up and top-down triangulation cross-checked wafer fabrication capacity announcements against resist consumption intensity metrics.
Bottom-up modeling anchored volume projections to named high-NA EUV scanner installations and multi-patterning scheme proliferations at sub-7nm nodes. Segmentation dimensions spanned material type, application node, end-user procurement archetype, and regional regulatory cluster. CAGRs were derived from slope analysis across the projection horizon with cross-validation against foundry capex cycle timing. Industry-specific inputs included EUV source power advancement curves and ECHA PFAS restriction implementation phasing.
The model holds under sustained EUV infrastructure buildout and REACH regulatory implementation schedules; deviation in fluorinated monomer supply disruptions or foundry qualification timeline extensions would shift volume trajectories. Forecasts reflect documented assumptions regarding scanner deployment rates and reformulation investment cycles. Periodic stress-testing of base assumptions is recommended against high-NA EUV yield achievement timelines and alternative lithography technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing High Performance Plastic Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
3D Printing Iron Powder Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
3D Printed Nanocellulose Market
3D Printing Materials
Stainless Steel 3D Printing Market