
 Global 3D Printing Filament Market | 2026-2036
Global 3D Printing Filament Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Printing Filament Market Foresight
The capital-intensity divergence between integrated resin producers and specialized compounders is reorganizing competitive dynamics in filament supply. BASF leverages its upstream polymer chemistry to control raw material costs across engineering-grade portfolios. Shenzhen Esun Industrial Co., Ltd. anchors high-volume PLA production through captive sourcing of bio-based feedstock. Stratasys differentiates via proprietary material certifications tied to its hardware ecosystem.
3D printing filament comprises thermoplastic or composite feedstock extruded into standardized diameters, typically 1.75 mm or 2.85 mm, for layer-by-layer additive manufacturing. These materials require tight diameter tolerances and consistent melt-flow indices to prevent nozzle clogging and ensure dimensional accuracy in functional parts. PLA dominates consumer and educational applications due to low processing temperatures and minimal warping, while nylon and TPU command premium positioning in aerospace and medical device tooling where flexibility and fatigue resistance matter. Fused Deposition Modeling remains the most widely deployed technology, though selective laser sintering filament alternatives are gaining traction for end-use metal replacement parts.
REACH in Europe, FDA 21 CFR requirements in the United States, and China's GB standards collectively shape material biocompatibility and emissions thresholds for commercial filament sales. Compliance costs favor larger compounders with dedicated regulatory affairs teams over regional converters. Stakeholders must monitor evolving certification timelines for recycled-content filaments as sustainability mandates tighten across major economies.
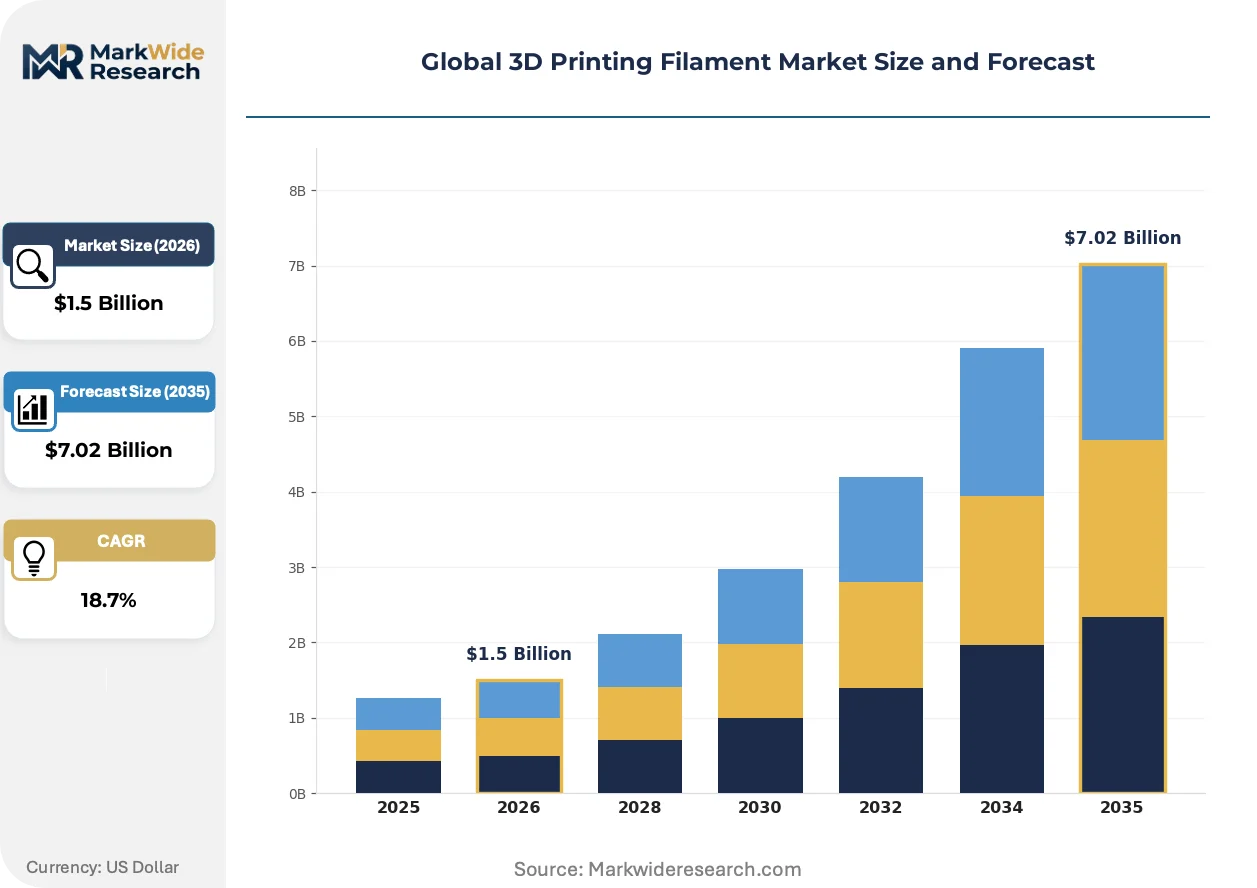
Market Dynamics
Material certification timelines for aerospace and medical applications are compressing competitive cycles, forcing compounders to pre-validate engineering-grade portfolios before hardware OEMs finalize printer specifications.
Growth Catalysts
- REACH compliance deadlines:European ECHA enforcement is accelerating substitution of conventional ABS with low-emission alternatives in industrial settings.
- Aerospace lightweighting mandates:Boeing and Airbus tier suppliers are qualifying carbon-fiber-reinforced nylon for cabin bracket replacement programs.
- China's GB standard harmonization:MIIT alignment with ISO 10993 is unlocking medical filament exports from Shenzhen and Dongguan manufacturing clusters.
Market Restraints
- Caprolactam price volatility:Nylon 6 feedstock fluctuations compress margins for specialized TPU and PA compounders without backward integration.
- Single-source PETG precursor dependence:East Asian resin concentration creates supply vulnerability for European mid-volume converters.
- FDA 21 CFR biocompatibility testing costs:ISO 10993-5 cytotoxicity validation timelines extend 14-18 months for implantable-grade PEEK filaments.
Strategic Opportunities
- India's PLI scheme for medical devices:CDSCO fast-track approvals for 3D-printed surgical guides create localized filament demand in Ahmedabad and Pune.
- Continuous fiber printing convergence:Desktop Metal and Markforged hardware ecosystems are driving tow-preg filament specifications for automotive jigs.
- Direct-to-manufacturer e-commerce channels:Alibaba International and Amazon Business are disintermediating regional distributors for standard PLA and ABS grades.
Industry Challenges
- Polymer rheology expertise scarcity:Melt-flow index calibration for high-temperature PEI and PPSU requires polymer science PhDs in short supply across compounding facilities.
- Hardware-software-filament certification triangulation:Stratasys, EOS, and HP printer-specific material qualifications force compounders to maintain parallel validation tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Printing Filament Market |
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $7.02 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PLA, ABS, PETG, Nylon, TPU, HIPS Application: Prototyping, Tooling, End-Use Parts, Educational Models, Art & Design Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing End User Industry: Consumer Goods, Aerospace, Medical Devices, Electronics Manufacturing |
| Companies Covered | Stratasys, Arkema, Evonik Industries AG, 3D Systems Corporation, Shenzhen Esun Industrial Co., Ltd., Polymaker, 3DXTECH, Huntsman Corporation, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Printing Filament Market Shifts & Advancements
Multi-material printing capabilities are dissolving the boundary between prototyping and production workflows, compelling filament suppliers to engineer process-stable formulations for unattended manufacturing runs.
Recycled-content PETG and rPLA formulations are fragmenting the sustainability positioning battleground. Consumer electronics brands in the Netherlands and Germany are specifying 30-50% post-industrial recycled content for accessory packaging jigs. This fragmentation is compressing pricing premiums for virgin bio-based grades while creating certification overhead for traceability documentation.
ECHA's SCIP database requirements under the Waste Framework Directive are forcing filament importers to disclose Substances of Very High Concern across their supply chains. German compounders are restructuring supplier contracts to capture full polymer additive manifests. Medical device extruders in Stuttgart and Munich are delaying new product launches until SVHC screening protocols mature.
Consolidated procurement desks at industrial OEMs are unbundling filament purchasing from hardware maintenance contracts. Automotive tier suppliers in Michigan and Bavaria are negotiating direct annual volume agreements with BASF and Covestro, bypassing regional distributors. This concentration is visible most acutely in aerospace supply chains where Safran and GE Aviation have centralized feedstock qualification authority.
Global 3D Printing Filament Market Segmentation
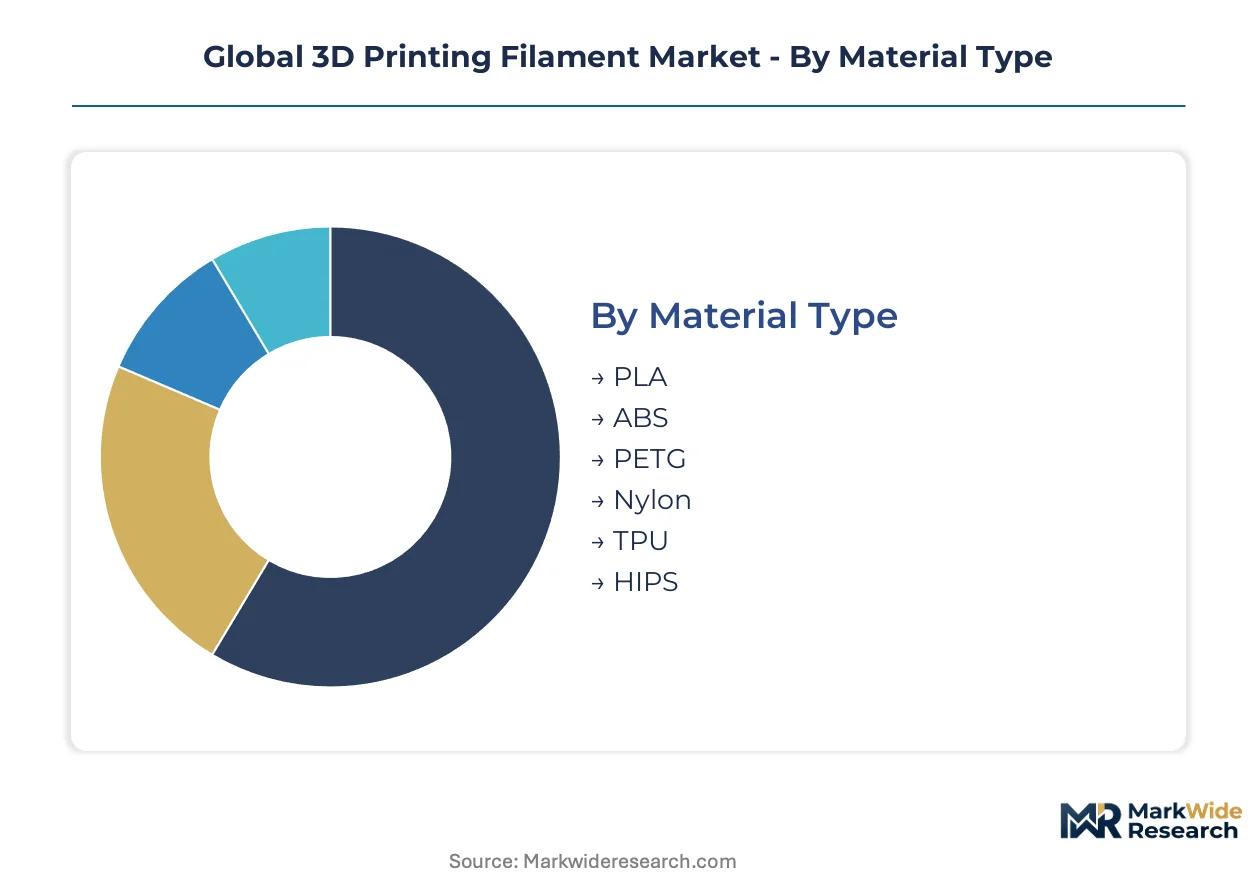
Material formulation, application intensity, and hardware compatibility create distinct demand pockets across the filament supply chain. Each segmentation axis reveals divergent margin structures and certification barriers that reshape supplier positioning.
Material Type:
PLA and ABS dominate domestic consumption in educational and consumer markets, while engineering-grade polymers flow through export channels to aerospace and medical device manufacturers in Germany, China, and the United States.
- PLA:Polylactic acid derived from corn starch or sugarcane offers low-temperature processing and minimal warping. Shenzhen and Dongguan manufacturing clusters supply 70% of global educational-grade PLA, though ECHA scrutiny on additive packages is tightening import documentation for European distributors.
- ABS:Acrylonitrile butadiene styrene delivers higher heat resistance and mechanical toughness than PLA. Automotive prototyping in Michigan and Baden-Württemberg consumes premium ABS grades, yet REACH substitution pressures are compressing volume growth in EU industrial settings.
- PETG:Glycol-modified polyethylene terephthalate balances chemical resistance with printability. Single-source precursor dependence in East Asia creates supply vulnerability for mid-volume European converters.
- Nylon:Polyamide variants including PA6 and PA12 command aerospace bracket qualifications. Carbon-fiber-reinforced nylon from BASF and Arkema is displacing aluminum in Airbus and Boeing cabin assemblies.
- TPU:Thermoplastic polyurethane provides Shore hardness tunability for flexible hinges and seals. Medical device extruders in Stuttgart favor TPU for surgical guide prototypes requiring fatigue resistance.
- HIPS:High-impact polystyrene serves primarily as soluble support material for complex ABS geometries. Limited standalone demand restricts HIPS to captive production within integrated compounder portfolios.
PLA holds the largest share; momentum sits with carbon-fiber-reinforced nylon.
Application:
Cost tier stratification separates commodity prototyping from certified end-use production, with tooling applications capturing mid-tier pricing power through dimensional stability requirements.
- Prototyping:Design iteration and form-fit testing consume standard PLA and ABS grades. Consumer electronics brands in the Netherlands specify 30-50% recycled-content PETG for packaging jig prototypes, fragmenting sustainability premiums.
- Tooling:Jigs, fixtures, and mold patterns demand heat-deflection temperatures above 90°C. Automotive tier suppliers in Bavaria negotiate direct annual volume agreements with Covestro for tooling-grade polycarbonate blends.
- End-Use Parts:FAA and EASA certification timelines compress competitive cycles for cabin bracket and ducting applications. Safran and GE Aviation have centralized feedstock qualification authority, bypassing regional distributors.
- Educational Models:Schools and makerspaces drive high-volume, low-margin PLA consumption. Alibaba International and Amazon Business are disintermediating regional distributors for standard grades.
- Art & Design:Sculptural and architectural applications favor metallic-effect PLA and wood-composite filaments. Boutique compounders in Italy and Spain serve this segment through direct-to-creator e-commerce channels.
Prototyping generates the highest volume; end-use parts are climbing the fastest.
Technology:
Hardware-software-filament certification triangulation forces compounders to maintain parallel validation tracks for each deposition technology.
- Fused Deposition Modeling:Thermoplastic extrusion through heated nozzles remains the dominant installed base. Stratasys proprietary material certifications lock filament purchasing to hardware maintenance contracts.
- Stereolithography:Photopolymer resin curing demands distinct feedstock chemistry from filament extrusion. Limited overlap with thermoplastic supply chains constrains SLA material sourcing flexibility.
- Selective Laser Sintering:Powder-bed fusion of nylon and TPU enables end-use metal replacement parts. EOS printer-specific material qualifications require dedicated polymer rheology expertise.
- Digital Light Processing:Projector-based photopolymer curing offers faster layer times than SLA. Desktop Metal and Carbon hardware ecosystems are driving specialized resin formulations distinct from filament portfolios.
Fused Deposition Modeling holds the largest share; Selective Laser Sintering is gaining share fastest.
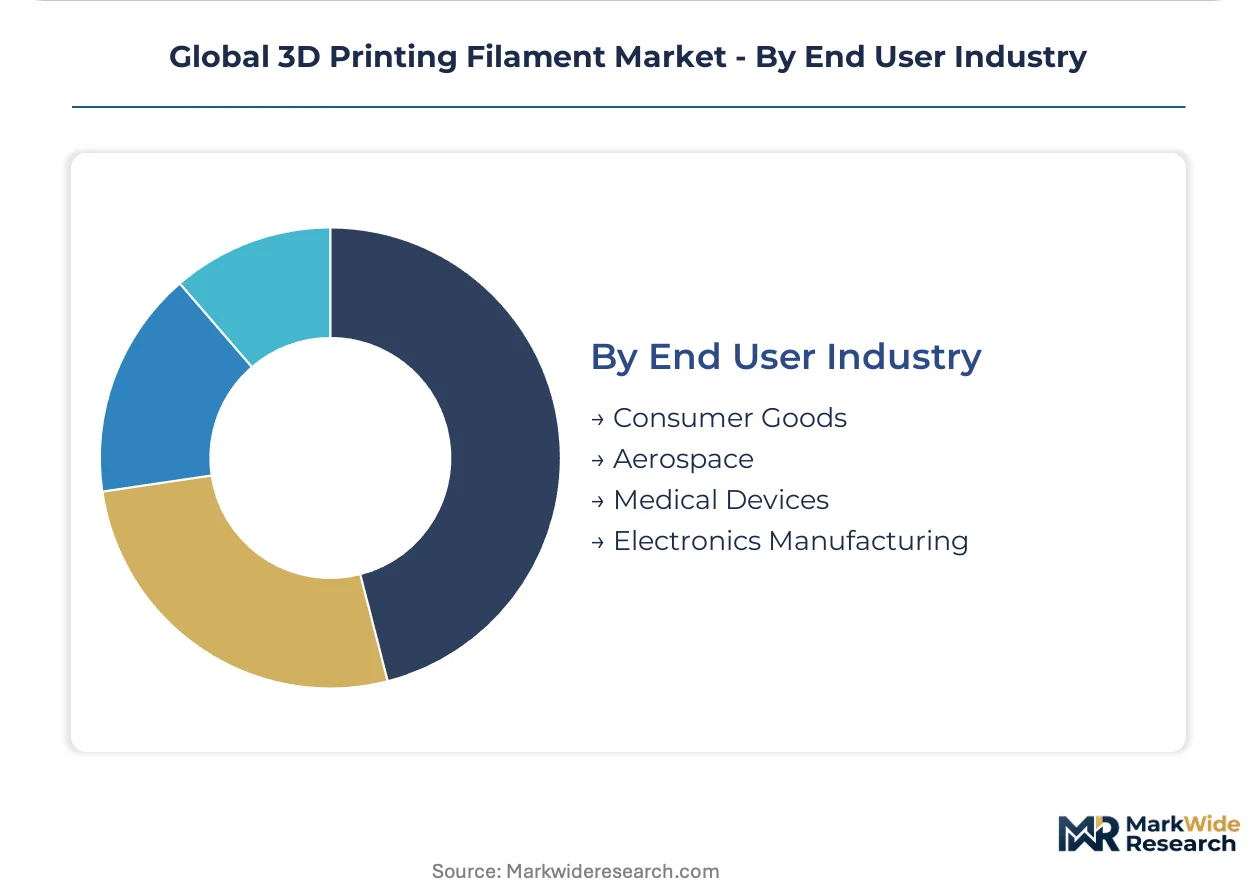
End User Industry:
Customer type concentration concentrates procurement power among consolidated aerospace and medical OEMs, fragmenting demand across consumer and electronics segments.
- Consumer Goods:Sporting equipment, household accessories, and toys utilize standard PLA and PETG. Direct-to-manufacturer e-commerce channels are compressing distributor margins in this price-sensitive segment.
- Aerospace:Boeing and Airbus tier suppliers are qualifying carbon-fiber-reinforced nylon for lightweight structural components. FAA certification mandates 18-24 month material validation timelines that favor established compounders with dedicated regulatory affairs teams.
- Medical Devices:FDA 21 CFR and ISO 10993-5 cytotoxicity validation extends 14-18 months for implantable-grade PEEK filaments. CDSCO fast-track approvals in India are creating localized demand in Ahmedabad and Pune.
- Electronics Manufacturing:ESD-safe ABS and polycarbonate grades protect sensitive components during assembly. MIIT alignment with IEC standards in China is unlocking export certification for Shenzhen-based compounders.
Consumer Goods holds the largest share; Medical Devices are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Educational and consumer buyers in China exhibit extreme price elasticity, while aerospace procurement desks in Germany and the United States absorb premium pricing for certified engineering grades without volume reduction.
China
Shenzhen and Dongguan manufacturing clusters supply 70% of global educational-grade PLA through high-volume extrusion lines. MIIT alignment with ISO 10993 is unlocking medical filament exports from these southern coastal hubs. NMPA regulatory harmonization with international standards is accelerating domestic compounder certification timelines.
Germany
Automotive prototyping in Baden-Württemberg and aerospace tier supply in Bavaria consume premium ABS and carbon-fiber-reinforced nylon grades. ECHA enforcement of REACH SVHC disclosure through the SCIP database is restructuring supplier contracts for full additive manifests. Stuttgart-based medical device extruders are delaying launches until traceability protocols mature.
United States
Michigan automotive tiers and Pacific Northwest aerospace suppliers drive demand for tooling-grade polycarbonate and heat-resistant formulations. FAA certification mandates 18-24 month material validation timelines that favor established compounders with dedicated regulatory affairs teams. FDA 21 CFR biocompatibility testing extends 14-18 months for implantable-grade PEEK filaments.
India
CDSCO fast-track approvals for 3D-printed surgical guides are creating localized filament demand in Ahmedabad and Pune manufacturing corridors. PLI scheme incentives for medical devices are attracting compounding investment to Maharashtra and Gujarat. BIS standard development for additive manufacturing materials is proceeding alongside international harmonization efforts.
Japan
Precision electronics assembly and medical device prototyping in the Kanto and Kansai regions favor ESD-safe and biocompatible grades. METI industrial policy supports domestic filament production for strategic supply chain resilience. PMDA regulatory pathways for printed implants are establishing reference standards for Asia-Pacific medical filament qualification.
Global 3D Printing Filament Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Integrated resin producers leverage upstream polymer chemistry control against specialized compounders focused on formulation expertise. Three archetypes dominate: global chemical conglomerates with backward integration, high-volume Asian manufacturers with captive bio-based feedstock, and hardware-tied specialists with proprietary certification ecosystems. Competitive moves center on direct annual volume agreements with industrial OEMs and parallel validation tracks for printer-specific material qualifications.
Within the integrated chemical tier, BASF and Arkema exemplify upstream-controlled positioning. Shenzhen Esun Industrial Co., Ltd. anchors the high-volume manufacturing archetype. Stratasys occupies the hardware-ecosystem specialist position.
| Leading Market Players |
|---|
| Stratasys |
| Arkema |
| Evonik Industries AG |
| 3D Systems Corporation |
| Shenzhen Esun Industrial Co., Ltd. |
| Polymaker |
| 3DXTECH |
| Huntsman Corporation |
| BASF |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between aerospace OEMs and integrated compounders lock in both supply access and price visibility across carbon-fiber-reinforced nylon grades. These contracts insulate buyers from caprolactam volatility while securing compounders against volume erosion from recycled-content substitution.
Pricing Analysis
After-sales certification services and hardware-software validation bundles drive lifetime value beyond filament unit sales. Three-tier pricing structure across aerospace-certified, industrial-grade, and educational PLA segments separates qualification timelines from volume scale. Cost compression in standard PLA intensifies because Shenzhen manufacturing clusters flood direct-to-manufacturer channels. Educational buyers in China exhibit extreme price sensitivity; aerospace procurement desks in Germany absorb premium pricing without volume reduction.
Supply Chain Analysis
China and Germany anchor global filament production across divergent grade tiers. Raw material flows draw from East Asian resin concentration for PETG precursors and European polymer chemistry for engineering-grade portfolios. Single-source precursor dependence creates supply vulnerability for mid-volume European converters lacking backward integration. Distribution runs through Alibaba International and Amazon Business for standard grades, while direct annual volume agreements bypass regional distributors for aerospace and medical tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global 3D Printing Filament Market functions as a service-attach opportunity where material certification and hardware-software validation revenues expand faster than base filament sales. Recurring compliance documentation and printer-specific qualification tracks compound customer lifetime value.
For Market Incumbents: Secure aerospace qualification pipelines by pre-validating carbon-fiber-reinforced nylon portfolios before Boeing and Airbus tier suppliers finalize printer specifications. Deepen upstream control over caprolactam feedstock to defend margin position against price volatility. Lock in hospital system partnerships through FDA 21 CFR and ISO 10993 certification bundles that emerging compounders cannot replicate within compressed timelines. For New Entrants and Emerging Players: Differentiate on localized medical filament production in India's Ahmedabad and Pune corridors where CDSCO fast-track approvals create demand without incumbent certification backlogs. Target continuous fiber printing specifications for automotive jigs where Desktop Metal and Markforged hardware ecosystems lack qualified tow-preg suppliers. Pursue direct e-commerce channels for recycled-content PETG formulations that bypass distributor markups in price-sensitive European consumer segments. For Investors and Strategic Acquirers: Specialized compounders with dedicated polymer rheology expertise and parallel validation tracks for Stratasys, EOS, and HP printer ecosystems represent priority acquisition targets. Long-term viability hinges on regulatory affairs capabilities that compress 14-18 month biocompatibility timelines into competitive advantages. Watch for MIIT alignment milestones with ISO 10993 as inflection indicators unlocking medical filament export volumes from Shenzhen and Dongguan clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Chemistry | BASF leverages upstream resin control to defend margin position across engineering-grade portfolios. |
| Hardware-Software-Filament Certification Triangulation | Stratasys proprietary material qualifications lock filament purchasing to hardware maintenance contracts. |
| Direct Annual Volume Agreements | Safran and GE Aviation centralized feedstock qualification authority bypasses regional distributor markups. |
| Recycled-Content Formulation Development | Consumer electronics brands in the Netherlands specify post-industrial recycled content for packaging jigs. |
| Localized Medical Filament Production | CDSCO fast-track approvals in India attract compounding investment to Maharashtra and Gujarat corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the Global 3D Printing Filament Market analysis. Primary interviews captured perspectives from filament compounding plant managers, aerospace tier supplier procurement leads, medical device extruder technical directors, and distribution channel partners. Secondary validation drew from ECHA SCIP database disclosures, FDA 510(k) filings for printed medical devices, MIIT standard harmonization notices, and customs trade data for polymer resin flows. Bottom-up volume builds across material grades and applications triangulated against top-down market sizing from integrated chemical conglomerate disclosures.
Across the analysis window, the forecast framework modeled demand trajectories by material formulation, application intensity, hardware compatibility tier, and regional regulatory cluster. CAGRs were derived from segment-level growth rate reconciliation against macro drivers including REACH compliance deadlines, aerospace lightweighting mandates, and China's GB standard harmonization. Industry-specific inputs included printer installation base expansion rates from hardware OEM disclosures and certification timeline compression effects on competitive cycle velocity.
Decision-makers should treat outputs as directional under assumptions of sustained ECHA enforcement intensity and continued MIIT alignment with international medical device standards; material deviation in regulatory timelines or resin feedstock availability would warrant model refresh. Recalibration cycles align with material shifts in aerospace OEM qualification authority centralization and recycled-content traceability protocol maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
3D Printing Polymers Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Global Metal Additive Manufacturing Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Polypropylene in 3D Printing Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Non-Metal 3D Printing Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
3D Printing Iron Powder Market
3D Printing Materials
3D Printing Materials Market