
 3D Printing PLA Market | 2026-2036
3D Printing PLA Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing PLA Market Intelligence
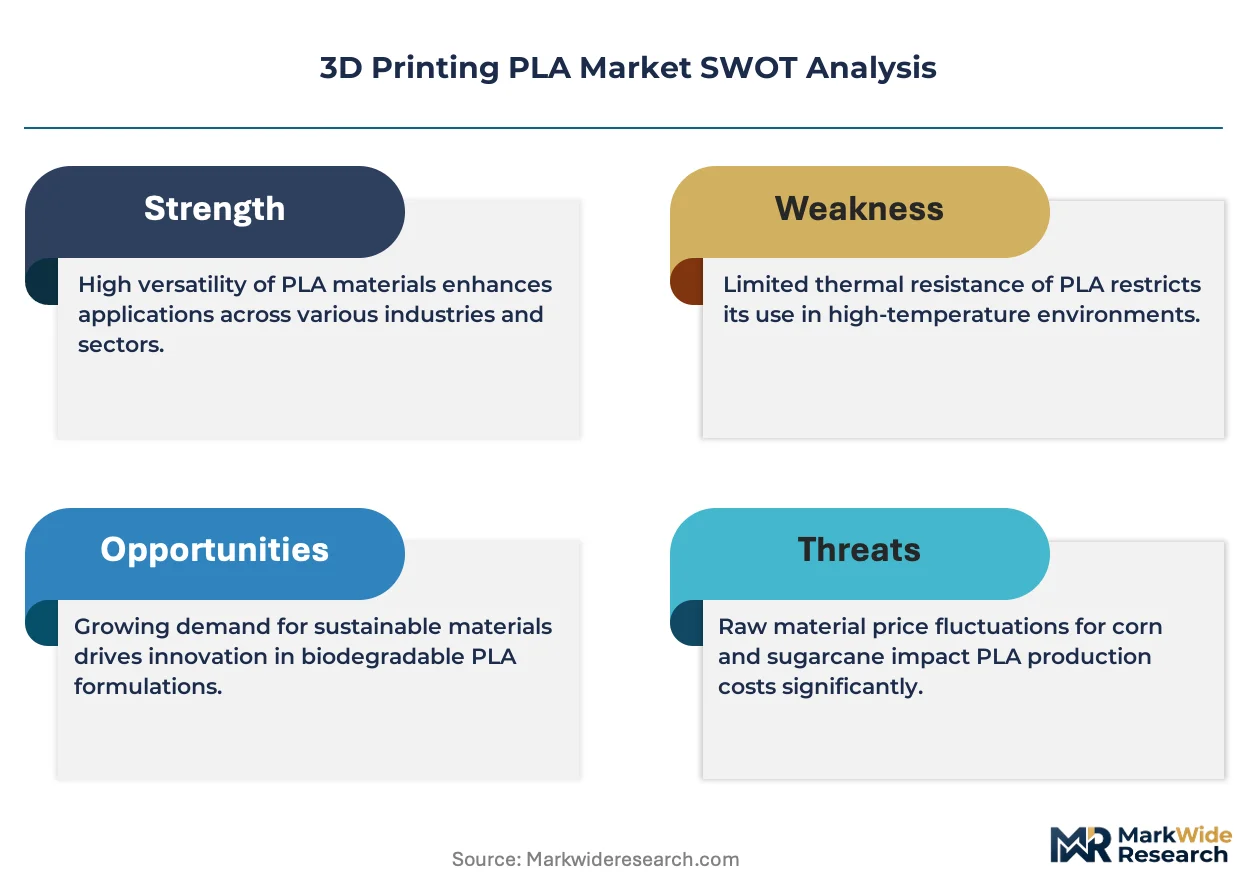
Asset-light leasing models for industrial-grade FDM systems is reconfiguring competitive entry barriers for mid-scale filament suppliers. Proto Labs leverages its digital manufacturing network to anchor high-throughput PLA prototyping services across North America. Polymaker specializes in modified PLA formulations with enhanced thermal resistance for engineering applications. Xometry competes through distributed production nodes that reduce lead times for custom PLA parts.
3D printing PLA consists of polylactic acid polymer extruded into filament with typical diameters of 1.75 mm or 2.85 mm, derived from fermented plant starch such as corn or sugarcane, and serves as a biodegradable thermoplastic for layered additive manufacturing. Standard PLA dominates volume sales due to its cost position and ease of printing, while Carbon Fiber PLA commands premium positioning among automotive suppliers seeking stiff, lightweight jig components. Fused Deposition Modeling anchors installed-base demand, though Selective Laser Sintering of PLA-based powders is gaining traction in research laboratories requiring soluble support structures.
FDA food-contact regulations and EU REACH chemical safety frameworks govern PLA purity standards for consumer-facing applications, while ISO 10993 biocompatibility protocols shape medical prototyping demand. China's SAMR enforces GB standards on plastic product labeling that affect imported filament packaging and traceability. Stakeholders must monitor evolving compostability certifications and regional chemical disclosure rules to secure sustained market access across jurisdictions.
Market Dynamics
Automotive tier suppliers are consolidating filament procurement around modified PLA grades certified for jig-and-fixture thermal loads, compressing supplier margins while elevating material traceability requirements under tightening chemical safety frameworks.
Growth Catalysts
- EU REACH chemical safety mandates:Importers must certify filament purity against Substances of Very High Concern lists, creating compliant supply scarcity that rewards early certifiers with locked automotive contracts.
- Fused Deposition Modeling thermal envelope expansion:High-temperature FDM hardware rated above 100°C enables engineering-grade PLA to replace ABS in functional prototyping, opening aerospace tooling applications.
- German industrial makerspace clustering:Stuttgart and Munich host concentrated automotive R&D facilities that standardize on PLA for rapid iteration, generating regional demand density unmatched elsewhere in Europe.
Market Restraints
- Corn starch feedstock volatility:PLA resin prices track agricultural commodity swings, squeezing filament extruders who lack backward integration into lactic acid fermentation.
- Chinese filament oversupply concentration:Anhui and Jiangsu provinces host capacity that floods export markets with uncertified commodity grades, eroding price floors for quality-compliant producers.
- Glass transition temperature ceiling:Standard PLA softens near 60°C, disqualifying it from under-hood automotive applications regardless of cost advantage over petrochemical thermoplastics.
Strategic Opportunities
- India PLI scheme for advanced manufacturing:Domestic filament production incentives align with import substitution goals, offering tariff-protected positioning for localized extrusion investments.
- Carbon fiber PLA aerospace tooling:Layered stiffness-to-weight ratios enable flight-qualified drill templates and assembly fixtures, displacing machined aluminum in non-structural applications.
- Hospital-based point-of-care printing:ISO 10993-certified medical PLA enables same-day surgical guide fabrication, collapsing traditional dental and orthopedic device supply chains.
Industry Challenges
- Compostability certification timeline fragmentation:Industrial composting standards vary between ASTM D6400, EN 13432, and home compost claims, forcing redundant testing budgets for multi-jurisdictional sellers.
- FDM technician skill scarcity:Calibration expertise for hygroscopic filament handling and annealing protocols remains concentrated among veteran operators, limiting production scaling at contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing PLA Market |
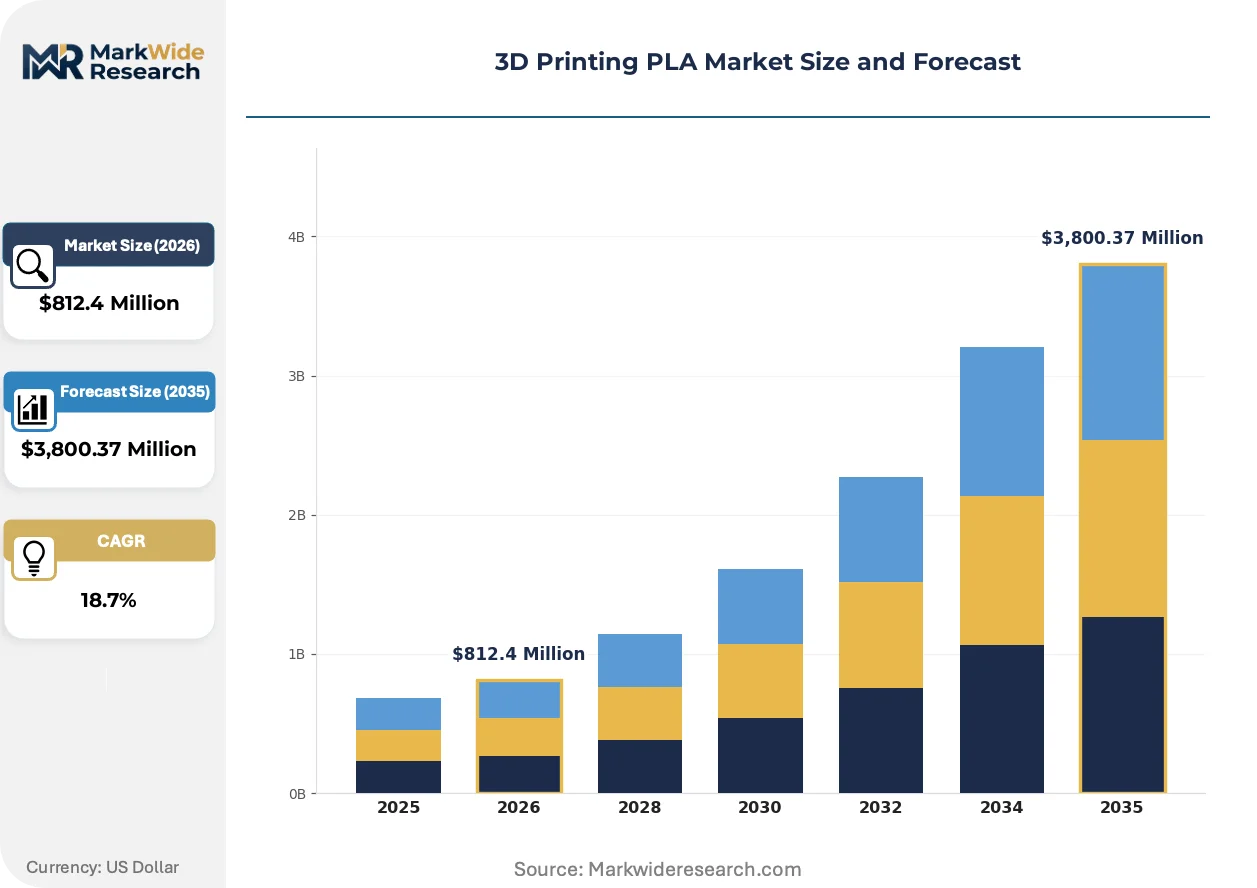
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $3,800.37 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard PLA, Silk PLA, Glow-in-the-Dark PLA, Wood-Filled PLA, Carbon Fiber PLA Technology: Fused Deposition Modeling, Stereolithography, Digital Light Processing, Selective Laser Sintering Application: Prototype Modeling, Educational Projects, Architectural Models, Consumer Goods, Hobbyist Creations End User: Educational Institutions, Automotive Suppliers, Consumer Electronics, Design Studios, Research Laboratories |
| Companies Covered | Proto Labs, Bambu Lab, Farsoon, Elegoo, Prusa Research, Bright Laser, Creality, Polymaker, Xometry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing PLA Market Strategic Shifts & Innovations
Material science advances and regulatory disclosure requirements are compressing product development cycles while fragmenting certification pathways across end-use verticals.
Continuous fiber-reinforced PLA composites are collapsing the stiffness gap between printed polymers and machined metals. Automotive fixture shops in Bavaria now specify carbon fiber PLA for welding jigs that must survive thousands of thermal cycles. The technology enables 40% weight reduction versus aluminum equivalents while maintaining dimensional stability through 80°C shop floor exposure.
REACH Annex XIV authorization requirements are forcing reformulation of colorant packages and processing aids used in decorative filaments. ECHA's 2024 update to Substances of Very High Concern candidate lists triggered recalls of imported filaments containing legacy phthalate plasticizers. European distributors now require full material disclosure documentation upstream of purchase orders, shifting competitive advantage to vertically integrated compounders with polymerization traceability.
Asset-light leasing of industrial FDM systems is displacing capital purchase models among mid-scale contract manufacturers. German automotive suppliers now access Stratasys and Ultimaker hardware through monthly arrangements bundled with certified filament supply, converting fixed equipment costs to variable production expenses. The model concentrates in Stuttgart's tier-one supplier corridor where production volumes fluctuate with OEM launch cycles.
3D Printing PLA Market Segmentation
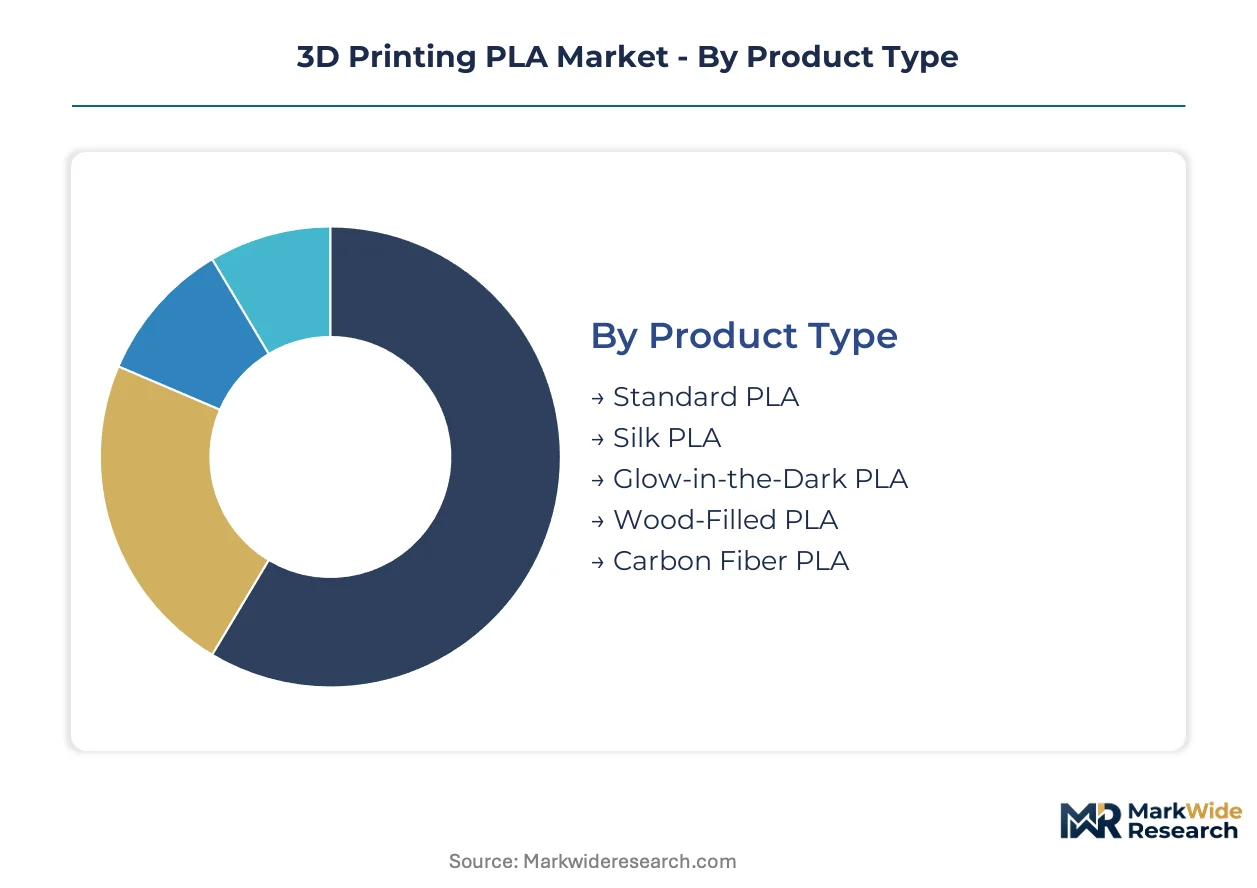
PLA filament segmentation reveals divergent margin structures across product grades, with modified formulations demanding intensive technical support while commodity volumes flow through automated channels. Understanding these service intensity tiers enables suppliers to align extrusion capacity with profit pool capture.
Product Type:
After-sales service intensity escalates sharply from standard grades to fiber-reinforced and filled formulations, with technical support hours per ton ranging from minimal for commodity PLA to substantial for carbon fiber variants requiring print parameter optimization.
- Standard PLA:Virgin polylactic acid polymer with no additives, offering predictable extrusion behavior and minimal nozzle wear. Demand concentrates in educational institutions across Germany and the United States where bulk procurement prioritizes cost stability over performance margins.
- Carbon Fiber PLA:Short carbon fiber reinforcement (typically 15-20% by weight) embedded in PLA matrix, delivering 40% stiffness improvement over unfilled grades. Automotive suppliers in Stuttgart and Munich specify this grade for welding jigs and assembly fixtures that must survive 80°C shop floor exposure.
- Silk PLA:Modified surface finish polymer producing glossy layer lines without post-processing. Decorative consumer applications in design studios drive intermittent demand.
- Glow-in-the-Dark PLA:Strontium aluminate phosphor loading enables luminescence for safety signage and novelty items. Niche hobbyist channels absorb limited volumes.
- Wood-Filled PLA:Cellulose fiber composite simulating timber grain for architectural visualization models. Furniture prototyping studios in Scandinavia represent concentrated demand pockets.
By volume, Standard PLA leads. By growth pace, Carbon Fiber PLA is ahead.
Technology:
Equipment capital requirements and operator skill thresholds fragment the addressable filament market, with powder-bed systems demanding specialized material forms that exclude conventional spooled filament entirely.
- Fused Deposition Modeling:Thermoplastic extrusion through heated nozzle onto build platform, consuming 1.75 mm or 2.85 mm filament on spools. This technology anchors installed-base demand across automotive prototyping centers in Bavaria and industrial makerspaces in Munich.
- Selective Laser Sintering:Powder-bed fusion of PLA-based polymer powders, requiring soluble support structures for complex geometries. Research laboratories in France and the Netherlands adopt this approach for biomedical scaffolding applications where FDM resolution proves insufficient.
- Stereolithography:Photopolymer resin curing with UV laser, incompatible with thermoplastic filament feedstock. Limited PLA relevance restricts market overlap.
- Digital Light Processing:Projected UV image curing of resin vats, similarly excluded from filament-based material supply chains.
FDM commands the installed base. Sintering of PLA powders climbs the fastest among material-compatible technologies.
Application:
End-use validation requirements and liability exposure stratify the application landscape, with medical-adjacent prototyping demanding ISO traceability that consumer hobby projects bypass entirely.
- Prototype Modeling:Functional part iteration for design verification and fit-checking prior to tooling commitment. Automotive tier suppliers in Germany consolidate procurement here, compressing supplier margins while elevating material certification requirements under tightening chemical safety frameworks.
- Consumer Goods:Finished products for retail sale including decorative items and household accessories. FDA food-contact regulations govern PLA purity standards for kitchen utensils and packaging prototypes.
- Educational Projects:Curriculum-integrated printing in secondary and university settings. Bulk purchasing agreements dominate this price-sensitive tier.
- Architectural Models:Scale building representations for client presentations and planning approvals. Wood-Filled PLA penetration is highest here.
- Hobbyist Creations:Non-commercial maker activity through online communities and local clubs. Seasonal demand volatility characterizes this segment.
Prototype Modeling generates the largest revenue pool. Consumer Goods applications are expanding most quickly as retail channels mature.
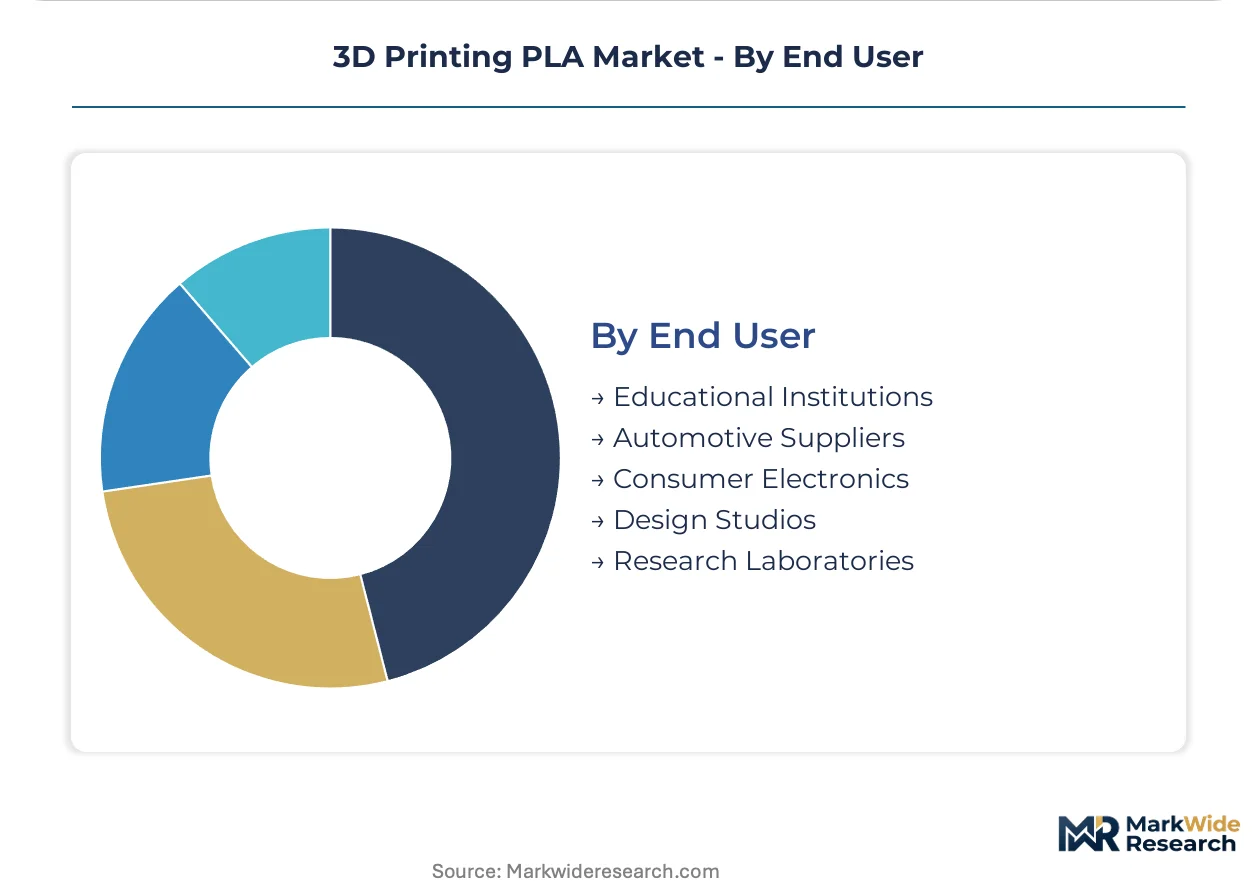
End User:
Procurement sophistication and technical specification rigor vary dramatically across buyer categories, with automotive suppliers imposing material disclosure documentation that educational institutions rarely request.
- Automotive Suppliers:Tier-one and tier-two component manufacturers utilizing PLA for jigs, fixtures, and prototype validation. EU REACH chemical safety mandates force reformulation of colorant packages and processing aids, with ECHA's Substances of Very High Concern lists triggering recalls of non-compliant imported filaments.
- Educational Institutions:Universities and technical colleges training students on additive manufacturing fundamentals. Germany's concentrated industrial makerspace clustering around Stuttgart and Munich generates regional demand density unmatched elsewhere in Europe.
- Research Laboratories:Academic and corporate R&D facilities exploring material properties and novel applications. ISO 10993 biocompatibility protocols shape medical prototyping demand here.
- Design Studios:Creative agencies producing client-facing models and concept pieces. Aesthetic surface quality prioritization elevates Silk PLA specification rates.
- Consumer Electronics:Device manufacturers prototyping enclosures and internal components. Thermal performance limitations restrict PLA penetration versus ABS and PC in this category.
Educational Institutions move the highest filament tonnage. Automotive Suppliers deliver the steepest expansion trajectory as fixture applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for high-purity PLA filament varies sharply across manufacturing hubs, with Germany and the United States running structural deficits in certified engineering grades while Chinese extruders dominate commodity spool exports. Trade flows concentrate around regulatory compliance tiers rather than simple cost arbitrage.
Germany
Automotive fixture demand from Stuttgart and Munich suppliers consumes modified PLA grades certified for thermal cycling. ECHA's REACH Annex XIV authorization requirements force reformulation of colorant packages, triggering recalls of non-compliant imported filaments. Bavaria's industrial makerspace clustering generates regional demand density unmatched elsewhere in Europe.
United States
FDA food-contact regulations govern PLA purity standards for kitchen utensil prototyping and packaging mockups. Proto Labs anchors high-throughput PLA prototyping services through its digital manufacturing network. Midwestern contract manufacturers lease industrial FDM systems through monthly arrangements bundled with certified filament supply.
China
Anhui and Jiangsu provinces host extrusion capacity that floods export markets with uncertified commodity grades. SAMR enforces GB standards on plastic product labeling that affect imported filament packaging and traceability requirements. Pearl River Delta fabricators compete primarily on spool volume rather than material certification depth.
India
The PLI scheme for advanced manufacturing offers domestic filament production incentives aligned with import substitution goals. CDSCO medical device regulations shape ISO 10993 biocompatibility protocol adoption for surgical guide applications. Maharashtra and Gujarat host emerging extrusion investments targeting tariff-protected positioning.
Japan
METI industrial policy supports high-temperature FDM hardware development enabling engineering-grade PLA adoption. JIS standards on thermoplastic material specifications create compliance barriers for imported filament. Kanto region research laboratories drive selective laser sintering of PLA-based powders for biomedical scaffolding.
3D Printing PLA Market Key Industry Players
On the supply side, the industry is bifurcated between commodity spool extruders competing on agricultural feedstock access and specialized compounders commanding premium positioning through modified formulations. Three archetypes dominate: vertically integrated resin producers with fermentation assets, independent filament extruders sourcing polymer externally, and distributed manufacturing platforms aggregating demand across production nodes. Competitive moves center on backward integration into lactic acid fermentation and geographic expansion through certified distribution partnerships.
Among distributed manufacturing platforms, Xometry occupies a position exemplifying demand aggregation through production node networks. Polymaker and Proto Labs represent contrasting archetypes within the specialized tier—Polymaker as a formulation-focused compounder and Proto Labs as a digital manufacturing network operator. These three entities collectively illustrate the strategic divergence between asset-light platform models and captive material development capabilities.
| Leading Market Players |
|---|
| Proto Labs |
| Bambu Lab |
| Farsoon |
| Elegoo |
| Prusa Research |
| Bright Laser |
| Creality |
| Polymaker |
| Xometry |
| Others |
Cost & Logistics Intelligence
Corn starch feedstock volatility determines both the spread between commodity and certified filament tiers and the geographic shape of extrusion investments. Agricultural commodity swings compress margins for non-integrated extruders while rewarding fermentation-anchored producers with pricing power across contract negotiations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under EU REACH chemical safety mandates and volume scale differentiate tiers, with automotive suppliers paying premiums for Substances of Very High Concern documentation. Cost compression in the standard tier intensifies because Chinese uncertified capacity floods export markets. Educational institutions exhibit highest price sensitivity, while aerospace tooling buyers demonstrate lowest elasticity due to performance requirements.
Supply Chain Analysis
Lactic acid fermentation capacity draws from China, Thailand, and the United States, with corn and sugarcane feedstocks dominating regional sourcing patterns. PLA resin, carbon fiber tow, and colorant packages constitute critical input dependencies. Single-source vulnerability concentrates in Anhui and Jiangsu province extrusion clusters that control uncertified spool volume. Distribution runs through certified distributor networks for automotive-grade material, while commodity grades flow through direct e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filament-as-a-service bundling with hardware leasing creates platform-economics inflection, with interoperability between printer OEM ecosystems determining supplier lock-in depth.
For Market Incumbents: Harden material traceability systems against REACH Annex XIV authorization expansion, embedding polymerization documentation into every spool. Deepen backward integration into lactic acid fermentation to neutralize agricultural commodity exposure. Capture channel control through exclusive certified-filament arrangements with Stratasys and Ultimaker leasing programs. For New Entrants and Emerging Players: Hospital-based point-of-care surgical guide printing in Maharashtra and Gujarat represents the most penetrable entry point, with CDSCO regulatory alignment creating tariff-protected positioning. Carbon fiber PLA aerospace tooling for non-structural fixtures offers second white-space target. Pursue ISO 10993 certification as primary go-to-market angle, collapsing traditional supply chain intermediaries. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated compounders with fermentation assets and REACH certification depth. Five-to-ten year viability rests on regulatory compliance moats rather than volume scale. Target acquisition archetype: mid-cap extruders with captive lactic acid supply and automotive contract relationships. Monitor ECHA Substances of Very High Concern list updates as inflection signal for reformulation cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captive lactic acid supply neutralizes corn starch price volatility for German automotive contracts. |
| REACH Certification Investment | Early Substances of Very High Concern compliance locks long-term automotive procurement relationships. |
| Hospital System Partnership | Same-day surgical guide fabrication collapses traditional dental and orthopedic device supply chains. |
| Hardware Leasing Bundling | Stratasys and Ultimaker arrangements convert fixed equipment costs to variable production expenses. |
| Carbon Fiber Composite Scale-Up | Flight-qualified drill templates displace machined aluminum in aerospace non-structural applications. |
Research Approach
The analysis maps standard PLA, carbon fiber reinforced grades, and medical-certified formulations, each validated through filament extruder plant managers, automotive tier supplier procurement leads, and hospital biomedical engineers. Primary interviews with distribution channel partners and technical R&D directors at compounders combined with secondary validation against customs/trade data, ECHA REACH registration databases, and SEC filings. Bottom-up capacity assessments and top-down demand triangulation anchored volume estimates.
Assumptions held fixed include current EU REACH authorization timelines and high-temperature FDM hardware penetration rates, while agricultural commodity price trajectories and Chinese export duty structures were varied across sensitivity scenarios. Segmentation dimensions modeled encompass product grade tier, end-use industry vertical, technology compatibility, and regional regulatory cluster. CAGRs derived from installed base growth, replacement demand, and application expansion coefficients. Industry-specific inputs incorporated automotive fixture thermal cycling requirements and ISO 10993 biocompatibility protocol adoption curves.
Practitioners should monitor ECHA candidate list updates, corn futures price movements, and Indian PLI scheme implementation pace for early signals of forecast revision. Cross-checking against IHS Markit automotive production databases and hospital procurement system adoption rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Stainless Steel 3D Printing Market
3D Printing Materials
3D Printing Materials and Services Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
Global 3D Printing Ceramics Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
Rapid Prototyping Materials Market
3D Printing Materials
Global 3D Printing Filament Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
Global Metal Additive Manufacturing Market