
 Stainless Steel 3D Printing Market | 2026-2036
Stainless Steel 3D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel 3D Printing Market Analytics
Germany is narrowing its lead in stainless steel additive manufacturing capacity through dedicated powder atomization facilities and integrated print service centers. Sandvik leverages captive powder production to control alloy consistency from melt to finished part. EOS GmbH anchors the selective laser melting equipment layer with open-parameter platforms that accommodate third-party powders. Carpenter Technology competes through vacuum induction melted gas atomized powder grades certified for jet engine applications.
Stainless steel 3D printing refers to layer-by-layer fabrication of corrosion-resistant iron-chromium-nickel alloys, typically 316L or 17-4PH compositions, using directed energy or powder bed fusion processes to achieve tensile strengths exceeding 500 MPa and near-full density for functional industrial components. Metal powders command the dominant value share due to stringent sphericity and particle size distribution requirements, while selective laser melting leads technology adoption in medical implant and aerospace segments where surface finish tolerances prove critical. Binder jetting represents the fastest-growing technology category as throughput rates and green part handling protocols mature for automotive tooling volumes.
EMA oversees biocompatibility certification for printed stainless steel implants under the EU MDR framework, while REACH governs nickel release thresholds in powder handling environments. The US FDA applies 21 CFR Part 820 quality system requirements to metal additive manufacturing for surgical instruments. Stakeholders must monitor evolving powder recyclability limits and alloy qualification protocols as binder jetting scales beyond prototyping into certified production environments.
Market Dynamics
Stainless steel 3D printing is consolidating around powder specification tightening as REACH and EU MDR frameworks force atomization upgrades and biocompatibility documentation across the supply chain.
Growth Catalysts
- EU MDR biocompatibility mandates:Medical implant manufacturers must document powder lot traceability and nickel release profiles, accelerating qualification of gas-atomized 316L grades for spinal and dental applications.
- Aerospace turbine blade demand:Engine OEMs are qualifying printed stainless steel brackets and vanes for thermal management systems, driven by weight reduction targets and complex internal cooling geometries.
- Binder jetting throughput maturation:Automotive tooling suppliers are adopting high-speed sintering protocols for stainless steel mold inserts, cutting lead times from weeks to days for injection molding operations.
Market Restraints
- Gas atomization feedstock concentration:Premium spherical powder production clusters in Germany and Sweden, creating single-source vulnerability for North American print service bureaus.
- Nickel volatility under REACH:ECHA's tightening occupational exposure limits for nickel-containing powders are forcing capital-intensive extraction and filtration retrofits at processing facilities.
- CNC machining substitution:Conventional five-axis milling retains cost advantage for simple stainless steel geometries below production thresholds of 500 units annually.
Strategic Opportunities
- India industrial tooling penetration:Die and mold manufacturers in Pune and Chennai are piloting binder-jetted stainless steel conformal cooling channels to reduce injection cycle times.
- FDA 510(k) pathway streamlining:The agency's emerging guidance on additively manufactured surgical instruments creates regulatory clarity for instrument sterilization tray producers.
- Laser powder bed fusion and AI convergence:Real-time melt pool monitoring systems using machine vision are reducing defect rates and enabling first-time-right production of 17-4PH aerospace brackets.
Industry Challenges
- Metallurgical technician scarcity:Powder characterization and parameter development require specialized expertise in electron microscopy and thermal simulation that outpaces vocational training output.
- Multi-alloy qualification timelines:Aerospace OEMs demand 18-month part-specific material property databases, compressing development schedules for new stainless steel compositions.
- Post-processing bottleneck integration:Hot isostatic pressing and CNC finishing capacity constraints create workflow friction between print completion and final dimensional certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel 3D Printing Market |
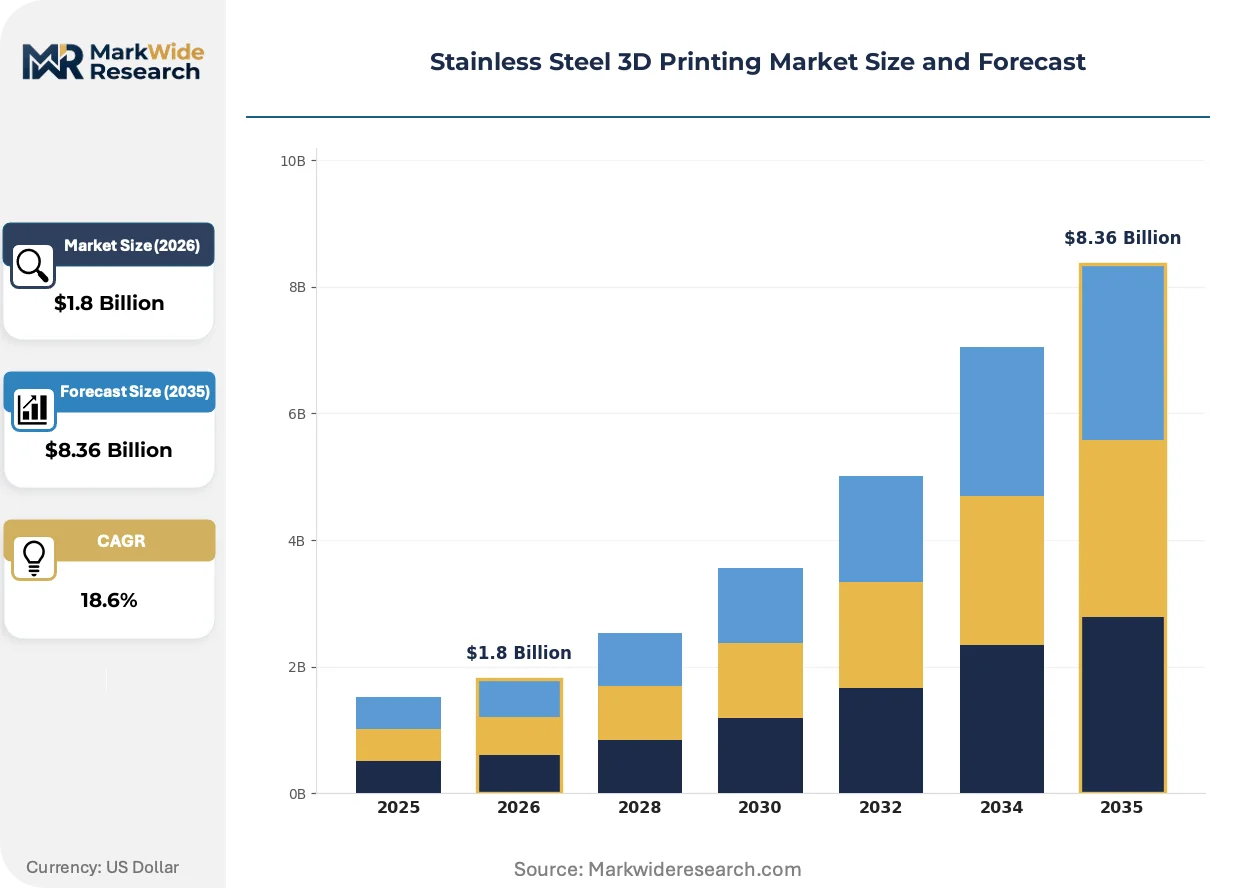
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Powders, Metal Wire, Filament, Sintered Parts Technology: Selective Laser Melting, Electron Beam Melting, Binder Jetting, Direct Energy Deposition End User: Aerospace, Automotive, Healthcare, Tooling Application: Prototyping, Component Manufacturing, Repair, Customized Parts |
| Companies Covered | Sandvik, EOS GmbH, Carpenter Technology, GKN Hoeganaes, Hoganas, Concept Laser, LPW Technology, AMC Powders, Praxair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel 3D Printing Market Evolving Landscape
Digital twin architectures are virtualizing qualification workflows across the stainless steel additive manufacturing value chain, compressing development cycles while tightening process control documentation.
Multi-laser selective laser melting is virtualizing build chamber economics by parallelizing energy delivery across larger powder beds. Aerospace bracket suppliers are adopting 12-laser configurations to consolidate formerly separate builds into single overnight runs. This is virtualizing the traditional trade-off between part size and production economics, enabling mid-volume stainless steel component batches that previously required machining investment.
REACH Annex XVII nickel restrictions are forcing powder producers to document surface oxide chemistry and particle morphology at sub-micron resolution. ECHA's 2023 enforcement guidance requires batch-specific leaching tests for chromium and molybdenum release, adding 6-8 weeks to powder qualification timelines. Medical implant manufacturers in Germany and Switzerland are responding by vertically integrating into captive atomization to control documentation chains.
Consolidated procurement of certified stainless steel powder lots is displacing spot-market purchasing among tier-one automotive tooling suppliers. Buyers are negotiating 24-month offtake agreements with atomizers to secure 316L and 17-4PH grades with guaranteed sphericity and oxygen content, replacing the previous project-by-project sourcing model. This pattern is most pronounced in Baden-Württemberg and Bavaria, where mold-making clusters coordinate volume commitments through regional supplier associations.
Stainless Steel 3D Printing Market Segmentation
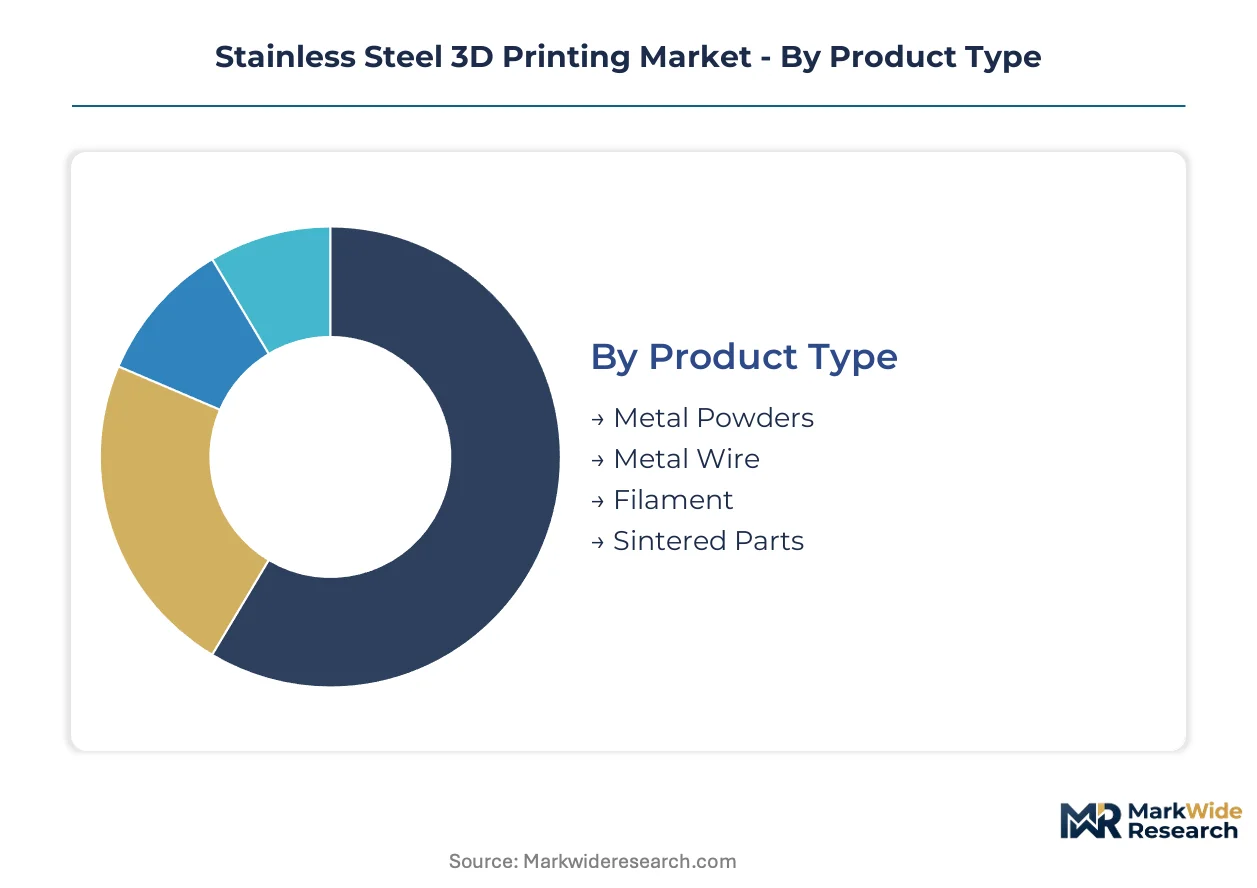
Stainless steel 3D printing segments diverge sharply by material form, energy delivery mechanism, and certification intensity. Each dimension carries distinct margin profiles and qualification burdens that reshape supplier positioning across aerospace, medical, and industrial tooling verticals.
Product Type:
Material form determines powder handling infrastructure, recyclability economics, and regulatory documentation load across the use-case spectrum from medical implants to heavy tooling.
- Metal Powders:Gas-atomized 316L and 17-4PH grades with 15-45 micron particle size distribution and >99.9% sphericity dominate aerospace and medical qualification protocols. Demand concentrates in Germany and Sweden where Sandvik and Carpenter Technology anchor captive atomization capacity, driven by REACH nickel release documentation and EU MDR batch traceability mandates.
- Metal Wire:Solid wire feedstock for directed energy deposition processes offers 100% material utilization and simplified handling versus powder systems. Arc-based DED suppliers in the US and Italy favor wire for repair applications on turbine shafts and forging dies where powder containment proves impractical.
- Filament:Polymer-bound stainless steel feedstock for fused filament fabrication enables low-cost prototyping without inert atmosphere requirements. Desktop Metal and similar platform vendors target design validation workflows where final sintered density of 95-97% suffices for form-and-fit testing.
- Sintered Parts:Near-net-shape components delivered post-debinding and sintering shift capital burden from end-users to specialized service bureaus. Tooling manufacturers in Baden-Württemberg increasingly procure finished mold inserts rather than maintaining captive binder jetting lines.
Established volume favors metal powders; emerging adoption favors sintered parts.
Technology:
Energy delivery architecture separates precision-critical applications from throughput-driven production, with cost tier determining accessibility for mid-market manufacturers.
- Selective Laser Melting:Laser powder bed fusion achieves near-full density (>99.5%) and Ra 6-10 micron surface finish for spinal implants and aerospace brackets. EOS GmbH's open-parameter platforms dominate German medical device manufacturing where EMA biocompatibility certification requires documented laser parameter traceability.
- Binder Jetting:High-speed droplet deposition of binding agent onto stainless steel powder enables build rates 10-100x faster than fusion-based methods. Automotive tooling suppliers in Stuttgart and Munich adopt this technology for conformal cooling mold inserts where surface finish tolerances permit post-sintering machining.
- Electron Beam Melting:Vacuum-based electron beam melting minimizes residual stress in thick-section 316L components for chemical processing equipment. Swedish industrial valve manufacturers leverage EBM for corrosion-resistant manifolds where internal channel complexity defies conventional machining.
- Direct Energy Deposition:Wire or powder-fed directed energy deposition builds large-scale tooling and repair features without powder bed size constraints. US-based job shops apply DED to restore worn forging dies and turbine blades where material deposition rates exceed 5 kg/hour.
Process maturity favors selective laser melting; steepest expansion trajectory favors binder jetting.
End User:
Customer type segmentation reflects divergent certification intensity, volume scale, and supply chain integration patterns across industrial verticals.
- Aerospace:Turbine blade brackets, thermal management vanes, and structural hardware demand 18-month material qualification databases per OEM specification. Pratt & Whitney and Rolls-Royce suppliers in the US and UK drive adoption of 17-4PH grades with documented fatigue performance under FAA airworthiness frameworks.
- Automotive:Injection mold inserts with conformal cooling channels reduce cycle times 20-40% for complex plastic components. Tooling clusters in Bavaria and Baden-Württemberg coordinate powder procurement through regional supplier associations to secure 316L lots with guaranteed oxygen content below 200 ppm.
- Healthcare:Spinal cages, dental copings, and surgical instrument sterilization trays require EMA biocompatibility certification under EU MDR. Swiss and German implant manufacturers respond to REACH nickel restrictions by qualifying low-nickel 316L variants or migrating to cobalt-chrome alternatives.
- Tooling:General industrial dies, jigs, and fixtures represent volume-driven adoption where surface finish and dimensional tolerances permit post-process machining. Indian die manufacturers in Pune pilot binder-jetted stainless steel for conformal cooling applications in injection molding.
Certification intensity favors aerospace; production volume scaling favors automotive tooling.
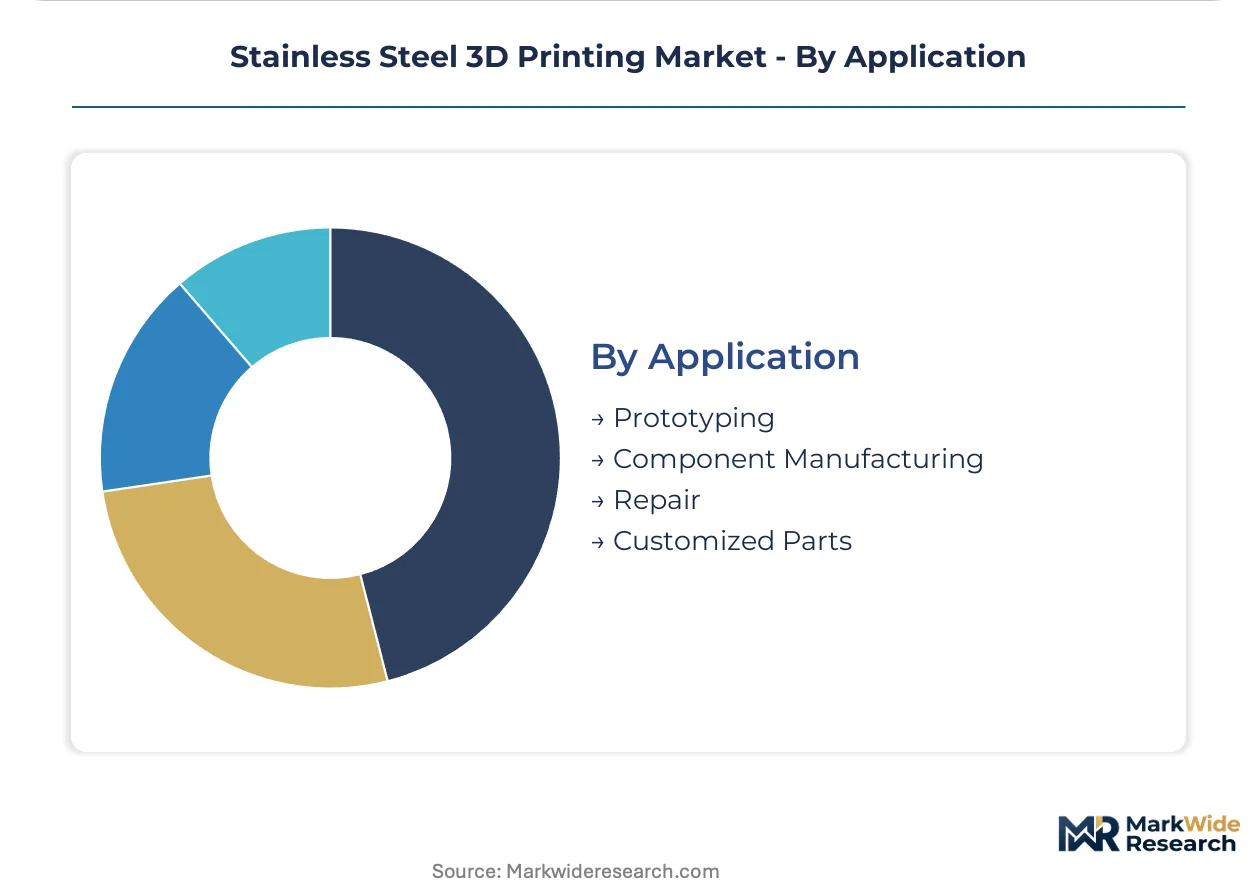
Application:
Functional purpose determines design iteration speed, regulatory burden, and economic viability relative to conventional manufacturing methods.
- Prototyping:Design validation workflows leverage printed stainless steel for functional testing of form, fit, and mechanical performance before tooling investment. Filament-based and binder jetting platforms dominate this segment where 95-98% sintered density suffices for non-critical load verification.
- Component Manufacturing:Certified production of end-use parts demands full density, documented mechanical properties, and lot traceability through atomization to finished component. Medical implant and aerospace bracket suppliers concentrate here, with qualification timelines spanning 12-24 months for new alloy-parameter combinations.
- Repair:Directed energy deposition restores dimensional accuracy to worn turbine blades, forging dies, and chemical processing equipment. Wire-fed DED systems in US job shops deposit 316L and 17-4PH layers onto damaged substrates with metallurgical bonding exceeding parent material strength.
- Customized Parts:Patient-specific spinal implants and low-volume surgical instruments exploit design freedom without amortized tooling costs. Swiss dental laboratories and German orthopedic device manufacturers lead adoption where lot sizes of 1-10 units defy conventional manufacturing economics.
Volume concentration favors component manufacturing; margin expansion favors customized parts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EMA biocompatibility mandates under EU MDR anchor European demand for qualified stainless steel powders, while FAA airworthiness frameworks and FDA 510(k) pathways shape qualification intensity in North American aerospace and medical segments.
Germany
EOS GmbH anchors selective laser melting equipment supply from Krailling, while automotive tooling clusters in Baden-Württemberg and Bavaria coordinate 316L powder procurement through regional supplier associations. REACH nickel release documentation from ECHA forces batch-specific leaching tests that add 6-8 weeks to powder qualification timelines for medical implant manufacturers.
United States
FAA airworthiness certification drives 18-month material property databases for 17-4PH aerospace brackets at Pratt & Whitney and Rolls-Royce suppliers. FDA 21 CFR Part 820 quality system requirements apply to metal additive manufacturing for surgical instruments, creating regulatory clarity for sterilization tray producers in Connecticut and Ohio manufacturing corridors.
Sweden
Sandvik leverages captive gas atomization capacity in Sandviken to control alloy consistency from melt to finished part for industrial valve manufacturers. EBM-based chemical processing equipment producers in Västerås exploit vacuum-based electron beam melting to minimize residual stress in thick-section 316L corrosion-resistant manifolds.
India
Die and mold manufacturers in Pune and Chennai pilot binder-jetted stainless steel conformal cooling channels to reduce injection cycle times for automotive suppliers. BIS standards for metal powder characterization remain under development, creating interim reliance on ISO-certified imported 316L grades from European atomizers.
Switzerland
Swissmedic oversees biocompatibility certification for spinal implants and dental copings produced in the Basel-Zurich medical device corridor. Swiss dental laboratories and orthopedic device manufacturers lead patient-specific customized parts adoption where lot sizes of 1-10 units defy conventional manufacturing economics.
Stainless Steel 3D Printing Market Competitive Landscape
Capability concentration sits with powder atomization specialists; scale advantage sits with equipment platform vendors. The market structures around captive supply chains in Northern Europe and open-parameter equipment ecosystems in Southern Germany. Three archetypes dominate: integrated powder-to-part manufacturers, pure-play atomizers serving third-party qualification protocols, and laser system vendors with parameter development services. Consolidation pressures concentrate in powder recycling technology and multi-laser build chamber scaling.
Among integrated powder-to-part manufacturers, Sandvik anchors Northern European supply chain control through captive atomization capacity. EOS GmbH exemplifies the equipment-centric archetype with open-parameter platforms that accommodate third-party powder qualification. Carpenter Technology occupies a position among specialty alloy producers targeting vacuum induction melted gas atomized grades for jet engine applications.
| Leading Market Players |
|---|
| Sandvik |
| EOS GmbH |
| Carpenter Technology |
| GKN Hoeganaes |
| Hoganas |
| Concept Laser |
| LPW Technology |
| AMC Powders |
| Praxair |
| Others |
Value Network & Pricing Analysis
The Hamburg-Rotterdam freight corridor shapes cost dynamics across the stainless steel additive manufacturing value chain, with container rates amplifying the price spread between German atomizers and North American print service bureaus while reinforcing tiered premiums for REACH-certified powder grades.
Pricing Analysis
Price spreads between German and North American markets reflect the documentation burden of REACH nickel release testing and EU MDR batch traceability. Pricing stratifies across aerospace-qualified, medical-certified, and industrial-grade tiers, with oxygen content below 200 ppm and sphericity guarantees commanding substantial premiums. Cost compression in the industrial tooling segment is intensifying as automotive mold-makers consolidate procurement through regional supplier associations. Tier-one aerospace OEMs exhibit the lowest price sensitivity due to 18-month qualification timelines, while Indian die manufacturers piloting conformal cooling applications show highest sensitivity to powder unit economics.
Supply Chain Analysis
Captive atomization capacity at Sandvik in Sweden and EOS GmbH's powder qualification partnerships in Germany anchor upstream supply. The supply chain draws from nickel and chromium feedstock processed through vacuum induction melting, with argon gas supply for atomization creating secondary dependencies. Single-source vulnerability concentrates in spherical powder production, where gas atomization expertise clusters in Northern Europe. Distribution runs through qualified distributor networks for medical-grade materials and direct mill relationships for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stainless steel 3D printing represents a high-growth disruption as binder jetting throughput maturation and EU MDR biocompatibility mandates simultaneously expand addressable applications and tighten qualification barriers.
For Market Incumbents: Pre-empt margin erosion in industrial tooling by securing captive atomization capacity or exclusive offtake agreements with qualified powder producers. Defend aerospace market position through accelerated 17-4PH fatigue database development to compress OEM qualification timelines. Investment in multi-laser build chamber scaling will consolidate mid-volume batch economics before emerging competitors achieve parameter maturity. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian automotive tooling clusters where BIS standards remain under development and ISO-certified European powder imports create interim cost structures. Target binder-jetted mold insert applications in Pune and Chennai where conformal cooling adoption outpaces domestic supply capability. A powder-recycling technology partnership with established service bureaus offers the most viable go-to-market angle without atomization capital requirements. For Investors and Strategic Acquirers: Powder characterization laboratories with EMA documentation capabilities and electron microscopy expertise represent the most attractive acquisition target archetype in a market where metallurgical technician scarcity constrains scaling. Long-term viability over the next decade hinges on regulatory certification moats rather than equipment hardware differentiation. Monitor ECHA enforcement guidance updates on nickel release thresholds as the critical inflection signal for medical implant vertical integration decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Atomization Investment | Sandvik's integrated powder-to-part model controls REACH documentation chains from melt to finished component. |
| Multi-Laser Platform Scaling | EOS GmbH's 12-laser configurations consolidate aerospace bracket builds into single overnight production runs. |
| Regional Supplier Association Formation | Baden-Württemberg mold-makers coordinate 316L procurement to secure guaranteed oxygen content below 200 ppm. |
| Real-Time Melt Pool Monitoring | Machine vision systems reduce defect rates in 17-4PH aerospace brackets through AI-driven parameter adjustment. |
| Conformal Cooling Channel Patent Portfolio | Automotive tooling suppliers in Stuttgart leverage design freedom to cut injection molding cycle times 20-40 percent. |
Research Methodology
A spread of perspectives from powder metallurgy engineers at atomization facilities, procurement leads at aerospace Tier 1 suppliers, regulatory affairs specialists navigating EU MDR frameworks, and biomedical engineers at orthopedic device manufacturers converged on the working assumptions. Primary interview insights were validated against secondary sources including ECHA enforcement guidance documents, FDA 510(k) submission databases for additively manufactured surgical instruments, SEC filings from specialty alloy producers, and trade flow data for gas-atomized powder shipments. Bottom-up sizing of equipment installations and powder consumption volumes was triangulated with top-down aerospace and medical device production forecasts.
Demand-supply balance modeling across the analysis window incorporated segmentation by material form, energy delivery technology, and certification intensity. The analytical framework projected adoption curves for binder jetting in automotive tooling against selective laser melting saturation in spinal implants and aerospace brackets. CAGRs were derived from equipment shipment trajectories, powder lot qualification timelines, and end-use production ramp schedules. Industry-specific inputs included REACH Annex XVII nickel restriction enforcement patterns and FAA airworthiness certification backlog durations.
Macroeconomic conditions sit as an overlay; deviation in nickel commodity prices, argon gas supply costs, or trans-Atlantic freight rates would shift the trajectory. Forecasts reflect assumptions regarding EMA documentation standardization and multi-laser platform reliability maturation. Quarterly review of ECHA enforcement guidance, OEM qualification pipeline announcements, and Indian BIS standard development progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
LAMEA 3D Graphene Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
Patterning Materials Market
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
Polyamide 12 Powder for High-Performance 3D Printing Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Thermoformed Plastics for Printing Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market