
 Global 3D Printing Metals Market | 2026-2036
Global 3D Printing Metals Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Printing Metals Market Analysis
Project finance for industrial metal additive systems is narrowing the competitive field to well-capitalized operators. EOS GmbH leverages its German engineering base to sustain premium positioning in selective laser melting hardware. Desktop Metal, Inc. competes through binder jetting platforms that lower entry costs for automotive batch production. Velo3D, Inc. differentiates via proprietary support-free geometries that unlock designs previously unmanufacturable.
3D printing metals encompasses powdered or wire-fed metallic feedstocks fused layer-by-layer using directed energy to produce near-net-shape components with densities exceeding 99.5 percent in qualified alloys. The process serves industries requiring complex geometries, material efficiency, and lot-size flexibility that subtractive methods cannot achieve. Titanium alloys command premium positioning in aerospace and medical implant applications where strength-to-weight ratios and biocompatibility justify higher feedstock costs. Selective laser melting leads technology adoption for precision-critical segments, while binder jetting captures volume opportunities in automotive tooling where throughput economics dominate.
FDA device regulations, EASA airworthiness certification requirements, and China's GB standards for additive manufacturing collectively elevate barriers for uncertified suppliers seeking entry into regulated end-use sectors. Compliance investments function as a de facto market filter, concentrating procurement relationships with producers holding multi-jurisdiction qualifications. Stakeholders must monitor evolving alloy qualification protocols and energy-input traceability standards as these criteria increasingly determine contract eligibility across defense and healthcare supply chains.
Market Dynamics
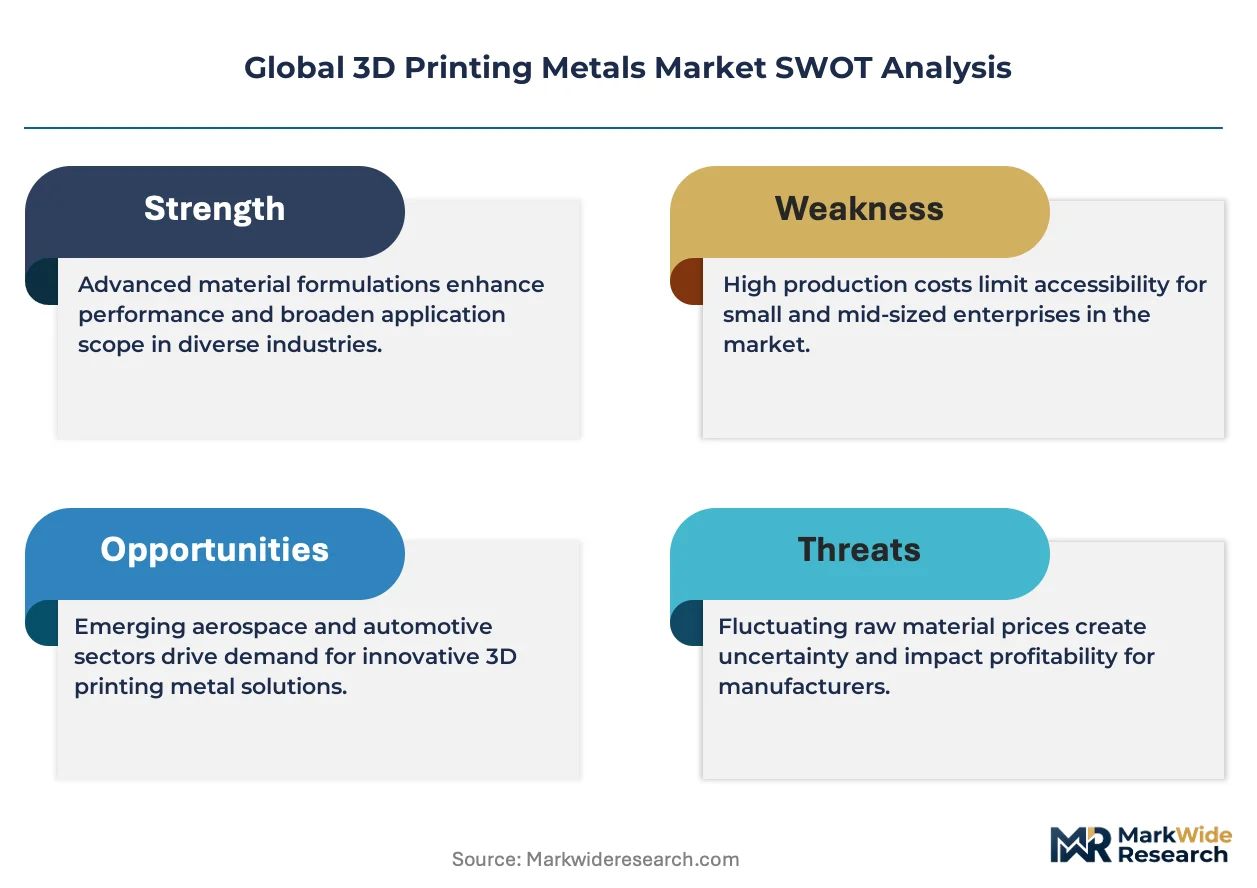
Flight-critical aerospace procurement is consolidating around suppliers capable of dual EASA-FAA certification, compressing the qualified vendor pool while elevating contract values for certified tier-one producers.
Growth Catalysts
- REACH and RoHS material purity mandates:European environmental frameworks are disqualifying uncertified feedstock suppliers, directing procurement toward qualified German and Swiss powder producers.
- Titanium alloy demand in spinal implants:FDA 510(k) pathway refinements for patient-specific devices are accelerating medical adoption of electron beam melted titanium structures.
- China's GB additive manufacturing standards:National standardization is formalizing domestic qualification protocols, enabling certified Chinese producers to supply defense and aviation supply chains.
Market Restraints
- Argon and helium feedstock volatility:Inert gas costs for powder atomization and build chamber atmospheres fluctuate with semiconductor and healthcare demand, compressing margins for high-purity alloy producers.
- Plasma atomization equipment concentration:Specialized powder production hardware is manufactured by a limited base of European and North American suppliers, creating single-source vulnerability for spherical titanium feedstock.
- Support structure geometric limitations:Conventional selective laser melting requires sacrificial supports that constrain internal channel designs, excluding applications requiring complex conformal cooling.
Strategic Opportunities
- India's PLI scheme for precision manufacturing:Production-linked incentives are attracting metal additive investments targeting aerospace MRO and medical device export markets.
- Multi-material deposition convergence:Wire-arc directed energy deposition is integrating with in-situ alloying capabilities, enabling gradient material transitions for rocket engine combustion chambers.
- Automotive tooling refurbishment channels:Binder jetting service bureaus are capturing legacy die-cast mold repair contracts through distributed production networks bypassing centralized foundry capacity.
Industry Challenges
- Non-destructive testing technician scarcity:Industrial computed tomography and ultrasonic inspection for internal defect detection requires specialized certification that outpaces training program output.
- Alloy qualification timeline compression:EASA and FAA concurrent certification pathways demand extensive mechanical testing databases that extend new material introduction cycles.
- Digital thread integration friction:MES and ERP connectivity for build parameter traceability conflicts with legacy quality management systems in tier-two supplier networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Printing Metals Market |
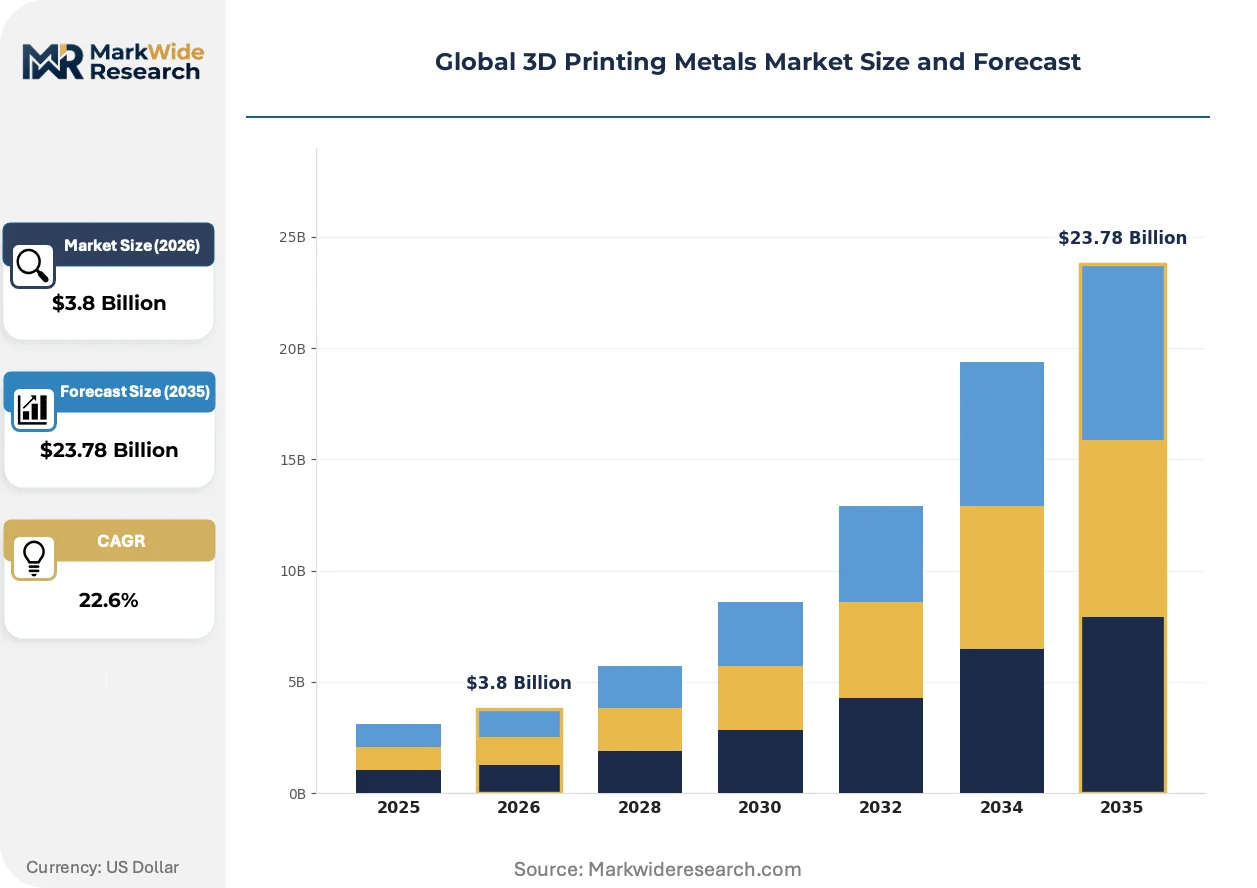
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.78 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Titanium Alloys, Aluminum Alloys, Stainless Steel, Nickel Alloys Technology: Electron Beam Melting, Selective Laser Melting, Binder Jetting, Direct Energy Deposition End User: Aerospace, Automotive, Healthcare, Defense Application: Prototyping, Tooling, Production Parts, Custom Implants |
| Companies Covered | 3D Systems, Inc., EOS GmbH, GE Additive, Renishaw plc, SLM Solutions, Desktop Metal, Inc., Stratasys, Velo3D, Inc., TRUMPF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Printing Metals Market Emerging Trajectories
Process-parameter traceability and real-time melt pool monitoring are becoming contractual prerequisites for defense and medical procurement, forcing hardware vendors to embed sensor architectures as standard configurations rather than optional upgrades.
Multi-laser selective laser melting is migrating from prototyping environments into production-scale aerospace cell manufacturing. Tier-one airframers in Germany and the United States are qualifying these systems for flight-critical titanium brackets. The technology is compressing per-part build times while expanding the addressable market for structural airframe components previously constrained by single-laser throughput economics.
REACH authorization requirements for nickel and cobalt compounds are tightening powder handling and waste recovery protocols across European production facilities. ECHA substance evaluation is extending compliance documentation to recycled feedstock streams. Medical implant producers in Switzerland and Germany are responding by certifying closed-loop powder recovery systems that maintain lot traceability under tightened substance control frameworks.
Buyer consolidation among orthopedic device OEMs is compressing supplier qualification cycles and elevating contract minimums. Smaller additive service bureaus in the United States are losing procurement access to major spine and joint reconstruction manufacturers. This concentration is most visible in the Minneapolis and Warsaw, Indiana medical device clusters, where three OEMs now dictate qualification standards across their captive supplier networks.
Global 3D Printing Metals Market Segmentation
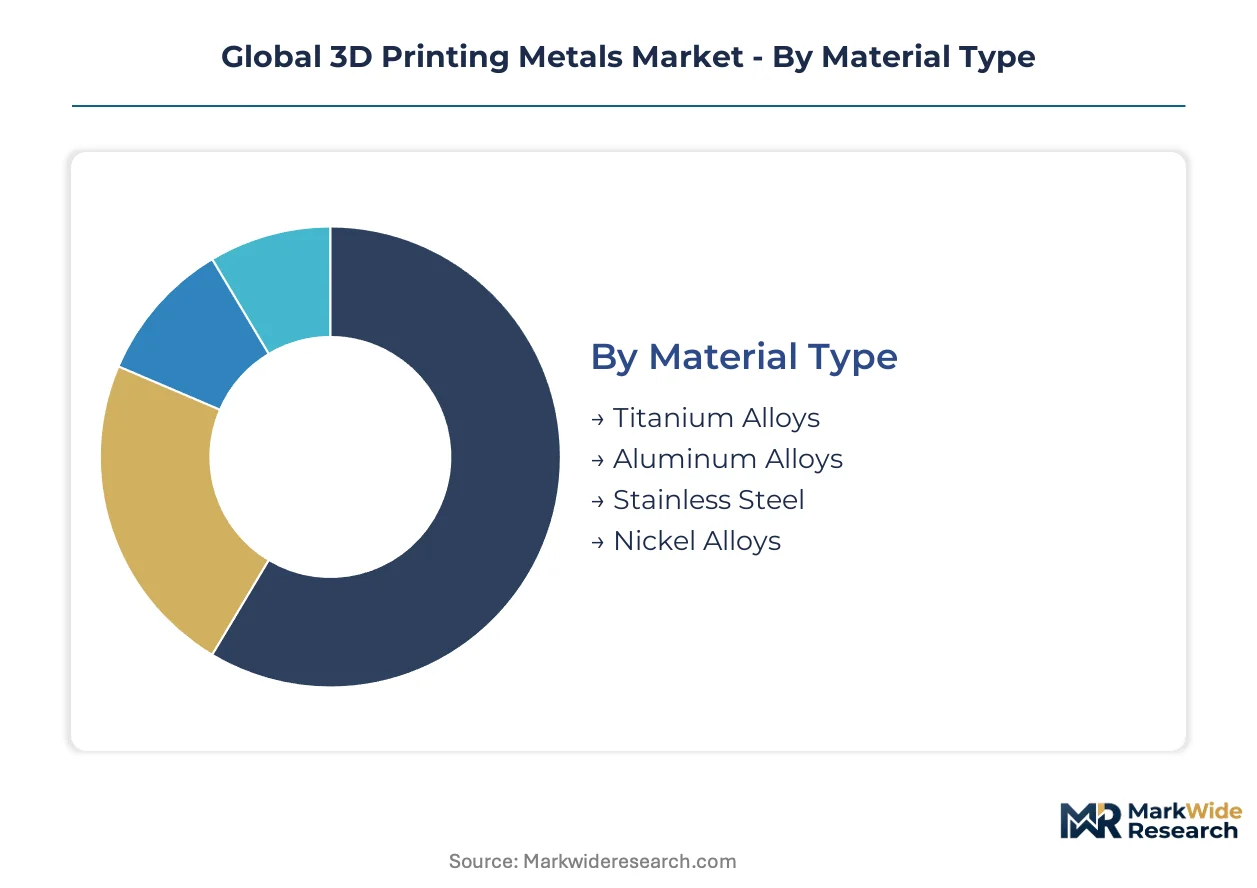
Segmentation in metal additive manufacturing reveals how material properties, process economics, and regulatory requirements partition demand across distinct procurement channels. Each dimension carries implications for supplier qualification, equipment investment, and margin structure that reshape competitive positioning.
Material Type:
Use-case spectrum spans flight-critical aerospace structures to disposable surgical guides, with material selection driven by strength-to-weight requirements, corrosion resistance, and biocompatibility certification pathways.
- Titanium Alloys:Ti-6Al-4V and Ti-6Al-4V ELI grades dominate spinal implant and airframe bracket applications where fatigue strength below 150°C justifies premium feedstock costs. EASA-FAA dual certification requirements concentrate procurement with German and US powder producers holding AS9100 and ISO 13485 credentials.
- Aluminum Alloys:AlSi10Mg and Scalmalloy variants serve automotive heat exchangers and satellite structures demanding 40% weight reduction versus steel. Scandium-modified alloys from Höganäs and AP&C command 3-4x conventional aluminum pricing due to limited scandium oxide supply.
- Stainless Steel:316L and 17-4 PH grades capture industrial tooling and food processing equipment where corrosion resistance outweighs density considerations.
- Nickel Alloys:Inconel 718 and Hastelloy X address gas turbine combustors and chemical processing components requiring creep resistance above 650°C.
The dominant share belongs to titanium alloys, while aluminum alloys are closing the gap fastest.
Technology:
Process selection hinges on resolution requirements, build envelope economics, and post-processing burden, with each technology occupying distinct points on the precision-throughput frontier.
- Selective Laser Melting:Multi-laser configurations from EOS and SLM Solutions achieve 99.5%+ density in nickel superalloys for turbine blades, with build speeds reaching 100 cm³/hour in production-qualified aerospace cells. Germany's Fraunhofer ILT and the US DOE's Oak Ridge National Laboratory anchor parallel qualification pipelines.
- Binder Jetting:ExOne and Desktop Metal platforms eliminate thermal distortion risks through sintering-based consolidation, enabling stainless steel automotive tooling at 10x selective laser melting throughput. Ford and Cummins have qualified binder-jetted injection molds for 100,000+ shot lifespans.
- Electron Beam Melting:Arcam systems from GE Additive produce stress-relieved titanium implants without support structures, though vacuum chamber constraints limit build volumes.
- Direct Energy Deposition:Wire-arc and laser-blown powder systems from Lincoln Electric and Optomec repair turbine blades and fabricate rocket nozzles exceeding 2-meter diameters.
Selective laser melting commands the largest installed base, though binder jetting is expanding most quickly in automotive volume applications.
End User:
Customer concentration reflects certification barriers, with qualified supplier networks narrowing procurement options in regulated sectors.
- Aerospace:Boeing, Airbus, and Safran drive titanium and nickel alloy demand for structural brackets, fuel nozzles, and turbine components. FAA Order 8110.37 and EASA CM-AS-005 establish parallel qualification pathways that extend new material adoption cycles.
- Healthcare:Stryker, Zimmer Biomet, and Johnson & Johnson's DePuy Synthes dominate orthopedic implant procurement, with FDA 510(k) submissions requiring mechanical testing databases exceeding 10,000 data points.
- Automotive:BMW, Porsche, and Mercedes-AMG deploy aluminum and steel tooling for low-volume powertrain components and customized interior trim.
- Defense:Raytheon, Lockheed Martin, and BAE Systems mandate ITAR-compliant supply chains for missile guidance housings and radar components.
Aerospace holds the dominant procurement volume, while healthcare is gaining share fastest through patient-specific device pathways.
Application:
Value capture varies dramatically across the product lifecycle, with production parts commanding 5-10x prototyping margins.
- Production Parts:Flight-critical brackets, spinal cages, and rocket engine injectors carry qualification documentation requirements that lock in multi-year supplier relationships. GE Aviation's LEAP fuel nozzles represent the benchmark, with 30,000+ additively manufactured components in service.
- Tooling:Conformal-cooled injection molds and die-cast inserts reduce cycle times 20-40% versus conventional drilled cooling channels. Hasco and DME standardize additive mold components for automotive tier-one suppliers.
- Prototyping:Design validation and fit-check models in aluminum and steel support iterative development in automotive and consumer electronics.
- Custom Implants:Patient-specific cranial plates and mandibular reconstruction guides leverage CT-to-CAD workflows, with 510(k) exemptions streamlining regulatory pathways for anatomical matching.
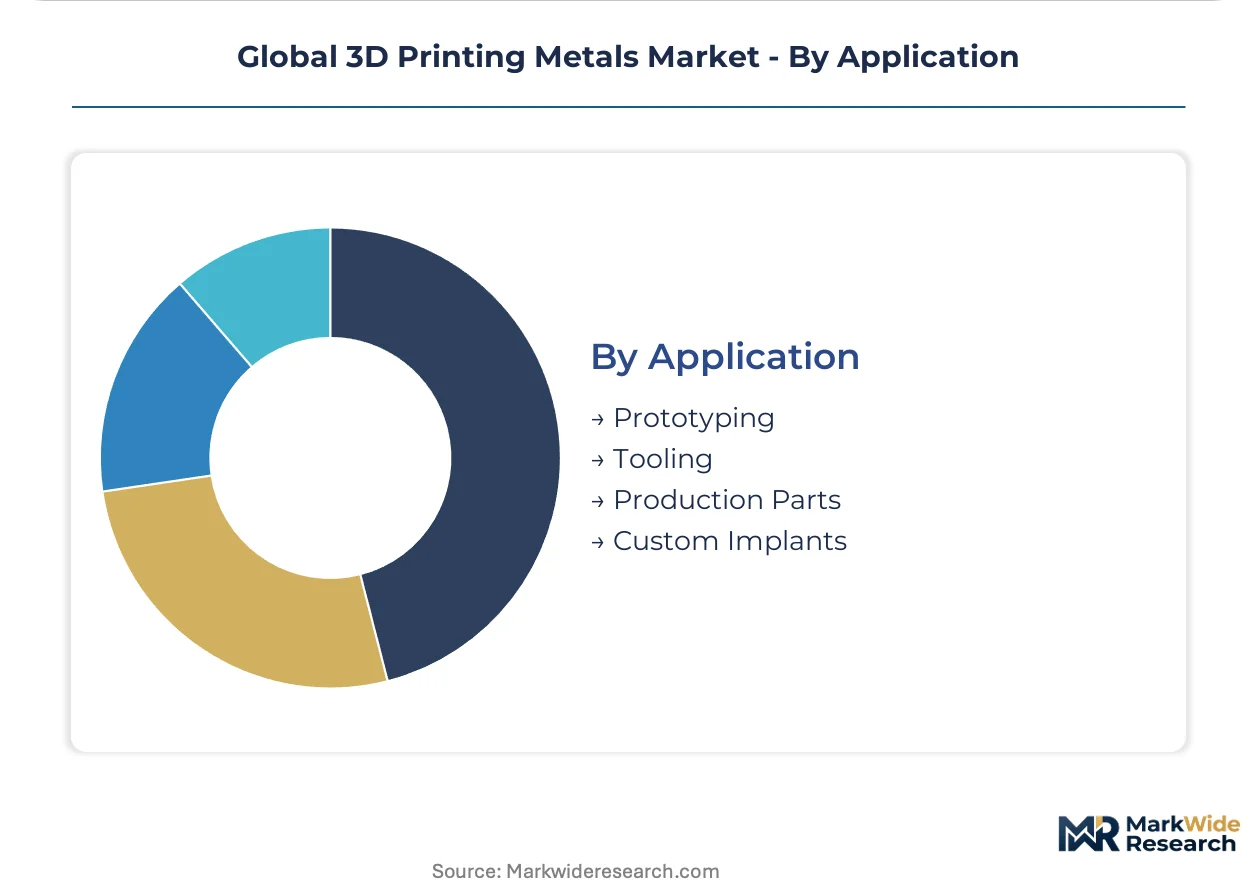
Production parts generate the dominant revenue share, while tooling applications are climbing the fastest as automotive manufacturers retrofit legacy die-cast infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Powder producers in Germany command 15-20% feedstock pricing premiums over Chinese suppliers, though Shenzhen and Ningbo metal additive clusters are compressing this gap through scaled titanium atomization investments.
United States
Defense procurement via Lockheed Martin and Raytheon drives nickel superalloy demand for missile guidance systems. FAA Order 8110.37 mandates dual certification pathways that extend qualification timelines. Greater Cincinnati hosts GE Aviation's LEAP fuel nozzle production, anchoring the country's densest aerospace additive manufacturing cluster.
Germany
EOS GmbH and SLM Solutions anchor selective laser melting hardware supply for European aerospace tier-ones. REACH authorization requirements for nickel and cobalt compounds tighten powder handling protocols across Bavarian and North Rhine-Westphalian facilities. Fraunhofer ILT in Aachen coordinates parallel qualification pipelines with Oak Ridge National Laboratory.
China
Domestic aviation programs through COMAC and AVIC accelerate titanium alloy qualification for structural brackets. GB standards for additive manufacturing formalize national certification protocols enabling defense supply chain entry. Xi'an and Chengdu host the densest concentrations of electron beam melting capacity for aerospace components.
India
Production-linked incentives for precision manufacturing attract metal additive investments targeting aerospace MRO and orthopedic export markets. BIS certification requirements for medical devices elevate barriers for uncertified feedstock suppliers. Bangalore and Hyderabad clusters specialize in titanium spinal implant production for European and North American OEMs.
Switzerland
Medical implant producers dominate patient-specific cranial plate and mandibular reconstruction guide manufacturing. Swissmedic device regulations mandate mechanical testing databases exceeding 10,000 data points for 510(k) equivalence pathways. Zurich and Bern host closed-loop powder recovery systems maintaining lot traceability under ECHA substance control frameworks.
Global 3D Printing Metals Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in powder atomization and post-processing equipment. The vendor base stratifies across three tiers: premium hardware vendors holding dual EASA-FAA certifications, mid-market binder jetting platforms serving automotive volume applications, and regional service bureaus competing on proximity and qualification speed. Dominant competitive moves include backward integration into spherical powder production and strategic partnerships with orthopedic OEMs for implant qualification pipelines.
Within the premium hardware tier, EOS GmbH and SLM Solutions exemplify German engineering-based positioning in selective laser melting systems. Desktop Metal, Inc. occupies a position exemplifying cost-disruptive entry through binder jetting platforms. These three anchors illustrate divergent strategies: premium certification depth versus volume accessibility versus proprietary geometry capabilities.
| Leading Market Players |
|---|
| 3D Systems, Inc. |
| EOS GmbH |
| GE Additive |
| Renishaw plc |
| SLM Solutions |
| Desktop Metal, Inc. |
| Stratasys |
| Velo3D, Inc. |
| TRUMPF |
| Others |
Supply Flow & Price Mechanics
German spherical powder producers command 15-20% feedstock premiums over Chinese suppliers, concentrating margin capture upstream while aerospace tier-ones absorb certification-inflated procurement costs. This geographic bifurcation shapes downstream equipment pricing and service bureau economics across qualified versus emerging supply channels.
Pricing Analysis
Configured-to-order titanium alloy builds carry 40-60% premiums over standard catalog geometries due to EASA-FAA dual certification documentation and lot-specific mechanical testing. Three-tier pricing structure across premium, standard, and economy levels separates flight-critical aerospace brackets from automotive tooling and prototype validation parts. Cost compression in mid-market binder jetting services is intensifying because Desktop Metal and ExOne platforms democratize entry-level stainless steel production. Automotive tier-two suppliers exhibit highest price sensitivity, while orthopedic OEMs prioritize qualification speed over unit economics.
Supply Chain Analysis
ITAR and EAR export controls restrict selective laser melting hardware flows to Chinese end-users, fragmenting global equipment distribution into compliance-segregated channels. Spherical titanium feedstock concentrates in Germany, the United States, and China, with plasma atomization equipment drawing from a limited European and North American supplier base. Argon and helium inert gas sourcing creates single-source vulnerability for high-purity alloy producers. Distribution runs through qualified service bureaus holding AS9100 and ISO 13485 credentials for regulated end-use sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-laser throughput gains and support-free geometry capabilities are disrupting established aerospace procurement patterns, creating asymmetric upside for hardware vendors with embedded sensor architectures. EASA-FAA concurrent certification pathways compress the qualified vendor pool while elevating contract values for certified tier-one producers.
For Market Incumbents: Build certification moats through backward integration into spherical powder production and captive qualification pipelines with orthopedic OEMs. EOS GmbH and SLM Solutions should expand Fraunhofer ILT partnership scope to accelerate alloy qualification timelines. Defend against binder jetting displacement by embedding real-time melt pool monitoring as standard rather than optional configuration.
For New Entrants and Emerging Players: India's aerospace MRO clusters offer underpenetrated entry points for titanium spinal implant production targeting European and North American OEM export markets. Binder jetting service bureaus should target legacy die-cast mold repair contracts through distributed production networks. Go-to-market positioning should emphasize ITAR-compliant supply chains for defense procurement access.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap powder atomization specialists with AS9100 credentials and established aerospace tier-one relationships. Long-term viability hinges on closed-loop powder recovery system adoption under REACH authorization frameworks. Watch ECHA substance evaluation extensions to recycled feedstock streams as inflection indicator for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spherical Powder Production | EOS GmbH secures captive titanium feedstock supply against Chinese pricing pressure. |
| Multi-Laser System Qualification for Flight-Critical Components | Boeing and Airbus tier-ones compress per-part build times for structural brackets. |
| Closed-Loop Powder Recovery System Certification | Swiss and German implant producers maintain lot traceability under ECHA frameworks. |
| Binder Jetting Platform Deployment for Automotive Tooling | Ford and Cummins qualify injection molds exceeding 100,000 shot lifespans. |
| Dual EASA-FAA Certification Pipeline Investment | Velo3D unlocks procurement access to flight-critical aerospace contracts. |
Methodological Framework
A spread of perspectives from aerospace procurement officers, orthopedic device quality managers, powder metallurgy R&D directors, and metal additive service bureau operators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against EASA airworthiness directives, FDA 510(k) submission databases, and China's GB additive manufacturing standards. SEC filings from GE Additive, EOS GmbH, and Desktop Metal anchored financial benchmarking. Bottom-up equipment installation counts and top-down aerospace procurement spend estimates were triangulated to constrain volume assumptions.
Demand-supply balance modeling across the analysis window integrated titanium alloy qualification pipelines, multi-laser system deployment trajectories, and REACH authorization timelines for nickel and cobalt compounds. Segmentation dimensions included material type, technology platform, end-use sector, and application lifecycle stage. CAGRs were derived from fitted growth curves calibrated to historical aerospace adoption patterns and medical device regulatory pathway durations. Forecast inputs incorporated argon and helium feedstock volatility indices and orthopedic OEM buyer consolidation trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-sponsored additive manufacturing consortia would shift outcomes toward accelerated domestic supply chain capture. Material shifts in EASA-FAA concurrent certification pathway requirements or ECHA substance evaluation scope expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
Polypropylene in 3D Printing Market
3D Printing Materials
Vat Photopolymerization 3D Printing Technology Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
Aerospace 3D Printing Materials Market
3D Printing Materials
3D Printing Plastics Market
3D Printing Materials
3D Printing Applications Polymers Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Graphene in 3D Printing Market
3D Printing Materials
3D Printing Resin Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
Advanced Materials for 3D Printing Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
3D Printing Coating Market
3D Printing Materials
3D Printing Materials Market