
 3D Printing Plastics Market | 2026-2036
3D Printing Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Plastics Market Intelligence
Demand for 3D printing plastics from industrial end-use part production is rotating away from a primary focus on prototyping. This shift favors material suppliers with deep application engineering expertise. BASF SE leverages its extensive chemical portfolio to develop specialized filaments and powders for industrial clients. Stratasys Ltd. focuses on integrated systems, pairing its printers with proprietary high-performance materials. Arkema specializes in advanced polymers for demanding applications in aerospace and automotive sectors.
3D printing plastics are thermoplastic or thermoset polymers formulated into filaments, powders, or resins for additive manufacturing processes. These materials are engineered for specific layer-by-layer deposition, requiring precise melt flow, viscosity, and curing characteristics for optimal performance. The primary purpose is the rapid creation of complex three-dimensional objects directly from digital models. Fused Deposition Modeling technology continues to dominate due to its accessibility, while materials for Selective Laser Sintering are seeing increased use for end-use parts. Photopolymers like PLA and PETG see high volume in prototyping, whereas high-performance nylons and polycarbonates capture value in functional applications.
Material safety and performance standards are governed by multiple bodies. In the United States, the FDA scrutinizes biocompatible plastics for medical implants, while Europe's REACH and RoHS directives restrict hazardous substances in electronic components. In Japan, METI oversees standards for industrial-grade polymers. These regulations directly influence material formulation and market access for specific applications. The key decision for material producers is whether to invest in certification for high-margin medical and aerospace grades or to compete on volume in the less-regulated consumer and prototyping segments.
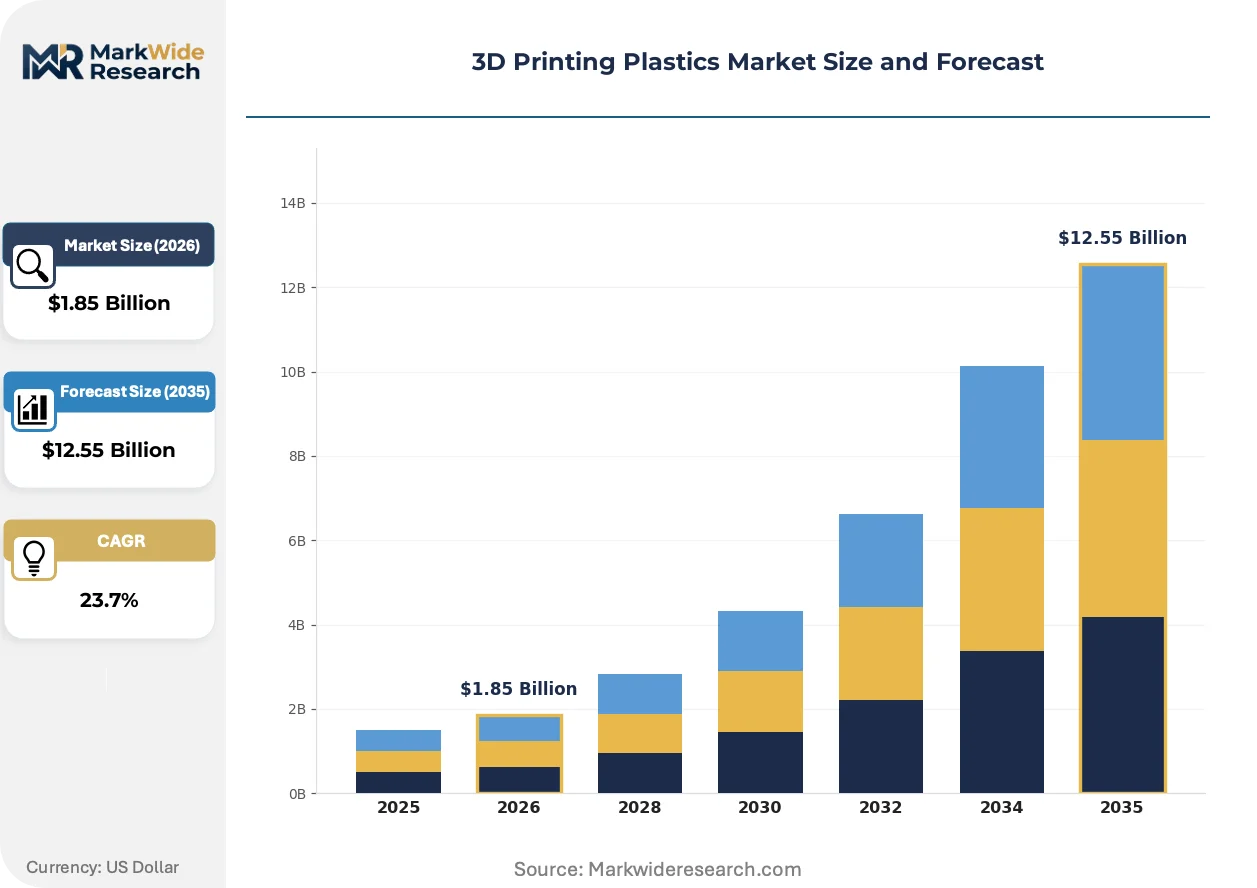
Market Dynamics
The central dynamic shaping the 3D printing plastics market is the pivot from rapid prototyping to qualified, industrial-scale production. This shift elevates the importance of material certification and deep application engineering, favoring materials that meet stringent performance criteria for end-use parts in regulated industries.
Growth Catalysts
- High-Performance Polymers:Innovation in materials like PEEK and PEI with superior thermal and chemical resistance unlocks new applications in the aerospace sector for creating lightweight, complex ducting and interior components.
- Medical Device Personalization:Demand for custom surgical guides, anatomical models, and patient-specific implants is accelerating, driven by regulatory pathways established by the FDA and EMA for biocompatible materials.
- Automotive Sector Adoption:The use of durable and functional plastics for creating jigs, fixtures, and rapid tooling on automotive assembly lines reduces production lead times and costs for major vehicle manufacturers.
Market Restraints
- Material Cost Structure:The high price of engineering and high-performance polymers, such as PEKK, significantly increases the per-part cost compared to traditional injection molding, limiting adoption for high-volume applications.
- Anisotropic Properties:Parts produced via Fused Deposition Modeling often exhibit weaker mechanical properties along the Z-axis (layer lines) compared to the X-Y plane, a technical limitation that complicates use in load-bearing applications.
- Regulatory Certification Hurdles:The extensive time and capital required to achieve certifications for materials, such as biocompatibility under ISO 10993 or flame retardancy for aerospace, act as a barrier to market entry.
Strategic Opportunities
- Functional Material Development:Creating novel polymer composites with embedded properties like electrostatic discharge (ESD) safety, electrical conductivity, or sensing capabilities opens new markets in electronics and smart manufacturing.
- Bio-based and Recyclable Materials:Developing sustainable filaments and powders from renewable sources or recycled plastics aligns with corporate sustainability goals and policies like the EU Green Deal, creating a distinct market segment.
- Expansion in Emerging Economies:Targeting industrial manufacturing sectors in countries like India and Brazil, where the adoption of additive manufacturing for end-use parts is in an earlier growth phase, offers significant expansion potential.
Industry Challenges
- Process and Material Standardization:A lack of universal standards for material properties and printing processes across different machine manufacturers leads to inconsistencies in part quality and complicates supply chain qualification.
- Design for Additive Manufacturing (DfAM) Skill Gap:A persistent shortage of engineers and designers trained to optimize part topology and take full advantage of the geometric freedom offered by 3D printing limits effective implementation.
- Intellectual Property Protection:The ease of distributing and replicating digital design files creates significant challenges in protecting IP for proprietary part designs, deterring some companies from adopting distributed manufacturing models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Plastics Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ABS, PLA, PETG, Nylon, Polycarbonate, TPU Technology: Fused Deposition Modeling, Stereolithography, Selective Laser Sintering, Digital Light Processing, Multi Jet Fusion, Binder Jetting Application: Prototyping, End-Use Parts, Jigs & Fixtures, Tooling, Educational Models, Consumer Products End User: Electronics Manufacturers, Aerospace Fabricators, Educational Institutions, Architectural Firms, Consumer Goods Producers, Medical Equipment Developers |
| Companies Covered | Stratasys Ltd., Arkema, 3D Systems Corporation, BASF SE, Evonik Industries AG, SABIC, HP Inc., Materialise NV, EOS GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Plastics Market Strategic Shifts & Innovations
Material development is specializing to meet the demands of certified industrial applications. The market is moving beyond general-purpose prototyping plastics, with innovation focused on formulations that deliver specific, repeatable, and verifiable performance characteristics required by aerospace, medical, and automotive end-users.
Composite-filled filaments, such as carbon fiber-reinforced nylons or glass-filled polypropylenes, offer enhanced strength-to-weight ratios and stiffness. Automotive and industrial manufacturing sectors are rapidly adopting these materials to produce functional prototypes, custom tooling, and low-volume end-use parts. The growing availability of these advanced composites is fragmenting the material landscape away from a reliance on a few base polymers and toward a diverse portfolio of specialized solutions.
New regulations governing material safety and traceability are influencing product development. In Japan, standards overseen by METI for industrial-grade polymers are compelling material producers to provide more extensive data on performance and consistency. This push for higher quality directly impacts material formulation for robotics and automotive components. Suppliers targeting the Japanese market must invest in rigorous quality control and documentation to comply with these evolving industrial standards.
A shift toward distributed manufacturing models is altering material procurement and logistics. Industrial clients are increasingly using digital inventories and on-demand printing services to produce spare parts locally, reducing warehousing costs and delivery times. This disrupts centralized, high-volume supply chains, creating an advantage for material suppliers who can support a network of geographically dispersed service bureaus. This trend is most prominent within the industrial MRO and defense sectors.
3D Printing Plastics Market Segmentation
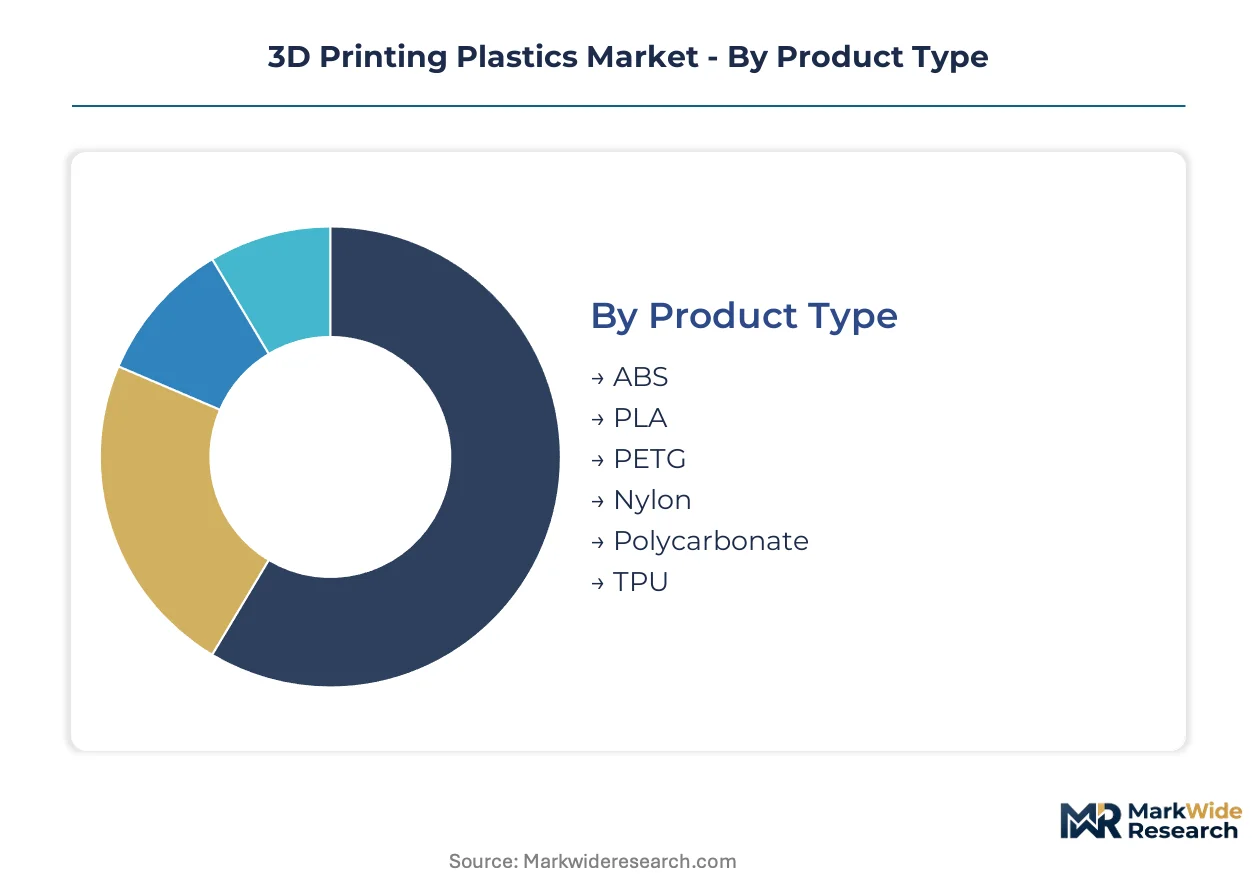
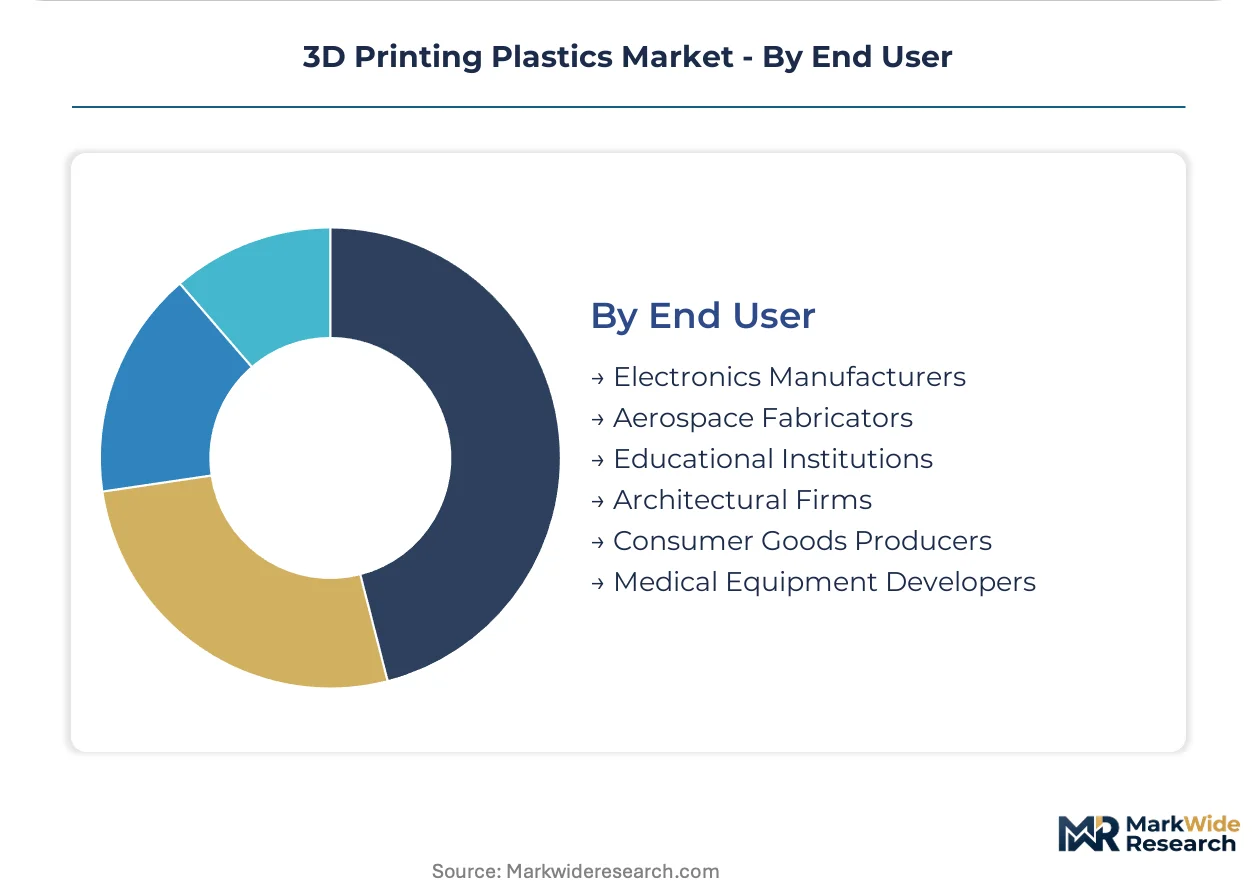
The 3D printing plastics market segments across diverse product types, technologies, applications, and end-users. Understanding these divisions helps clarify material flow, technological adoption patterns, and value chain dynamics within the rapidly evolving additive manufacturing industry.
Product Type:
The distribution of 3D printing plastics across various channels reflects material properties and end-use requirements.
- PLA:Polylactic Acid is a biodegradable thermoplastic polymer derived from renewable resources, widely used in Fused Deposition Modeling (FDM) for its ease of printing. Demand concentrates in educational institutions and prototyping segments due to its low cost and user-friendliness.
- Nylon:Polyamide (Nylon) is a high-strength, flexible, and durable thermoplastic, frequently reinforced with carbon fiber or glass for enhanced mechanical properties. Aerospace fabricators in the United States increasingly adopt nylon composites for producing lightweight, functional components requiring high impact resistance.
- ABS:Acrylonitrile Butadiene Styrene offers good mechanical properties and temperature resistance, making it suitable for functional prototypes and consumer goods.
- PETG:Polyethylene Terephthalate Glycol combines the ease of printing of PLA with the durability of ABS, finding use in mechanical parts and protective components.
- Polycarbonate:This high-performance thermoplastic provides excellent strength, heat resistance, and optical clarity, serving demanding industrial applications.
- TPU:Thermoplastic Polyurethane is known for its elasticity and abrasion resistance, making it ideal for flexible parts, seals, and footwear components.
By volume, PLA leads the market. Nylon exhibits the fastest growth pace for industrial applications.
Technology:
The selection of additive manufacturing technology depends significantly on the desired part complexity and material capabilities.
- Fused Deposition Modeling:This extrusion-based technology melts and deposits thermoplastic filaments layer by layer, offering accessibility and cost-effectiveness for various applications. Prototyping and educational models frequently utilize FDM due to its widespread availability.
- Selective Laser Sintering:SLS uses a laser to selectively fuse powdered polymer materials, creating parts with excellent mechanical properties and geometric freedom. Medical device developers in Germany increasingly rely on SLS for patient-specific implants and surgical guides.
- Stereolithography:SLA employs a UV laser to cure liquid photopolymer resins, producing high-resolution, smooth-surface parts ideal for detailed prototypes.
- Digital Light Processing:DLP technology uses a digital light projector to cure an entire layer of photopolymer resin at once, enabling faster print speeds for small, intricate objects.
- Multi Jet Fusion:MJF technology uses a fusing agent and detailing agent applied by an inkjet array, followed by an infrared lamp to create durable, functional parts.
- Binder Jetting:This technology uses a liquid binding agent to join powdered material, suitable for producing large, complex parts with diverse material options.
Technologies for direct part production are gaining share from prototyping-focused methods.
Application:
Different customer segments leverage 3D printing plastics for distinct application needs, from rapid iteration to final product integration.
- End-Use Parts:This segment involves producing functional components directly for final assembly or consumer use, requiring high-performance plastics with specific certifications. Aerospace fabricators and medical device manufacturers increasingly demand certified materials for end-use components.
- Prototyping:Rapid prototyping uses 3D printing to create physical models for design verification, form, and fit testing before mass production. This application sees high volume in consumer goods and electronics manufacturing.
- Jigs & Fixtures:Manufacturing aids like jigs and fixtures are custom-made tools that position or hold workpieces during machining or assembly operations.
- Tooling:This application involves creating custom molds, dies, and patterns for various manufacturing processes, reducing lead times and costs.
- Educational Models:3D printing creates anatomical models, architectural scale models, and scientific visualizations for teaching and research purposes.
- Consumer Products:This category includes custom footwear, personalized eyewear, and bespoke household items produced directly for individual consumers.
The shift toward industrial end-use applications is redefining value capture across the market.
End User:
End-user industries exhibit varied margin profiles, influencing material specification and supplier engagement strategies.
- Aerospace Fabricators:These manufacturers require ultra-lightweight, high-strength polymers with superior thermal and chemical resistance for aircraft components and interior parts. Companies in the United States and Europe specify materials like PEEK and PEI for demanding structural and environmental conditions.
- Medical Equipment Developers:This sector demands biocompatible and sterilizable plastics for surgical guides, custom implants, prosthetics, and anatomical models. Regulatory bodies like the FDA in the United States scrutinize materials for patient contact applications.
- Electronics Manufacturers:This segment uses 3D printing plastics for enclosures, functional prototypes, and custom jigs, often requiring ESD-safe or electrically conductive materials.
- Educational Institutions:Universities and research centers utilize 3D printing for design education, scientific modeling, and rapid prototyping in various disciplines.
- Architectural Firms:Architects employ 3D printing to create detailed scale models of buildings and urban developments for visualization and client presentations.
- Consumer Goods Producers:This industry leverages 3D printing for product design iteration, custom packaging, and personalized consumer items.
Industries requiring high material performance and stringent certifications drive premium segment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced manufacturing hubs, underpinned by sophisticated research and development infrastructure, drive the global 3D printing plastics market. These interconnected ecosystems facilitate rapid material innovation and technology adoption across key industrial sectors. Demand for specialized polymers is strongest in regions with established aerospace, medical, and automotive industries.
United States
The extensive network of research universities and defense contractors fuels demand for high-performance 3D printing plastics, particularly in aerospace and medical applications. The Food and Drug Administration (FDA) scrutinizes biocompatible plastics for medical implants, establishing rigorous standards for material producers. Medical device manufacturing clusters in states like California and Minnesota lead innovation in patient-specific implants and surgical guides.
Germany
Germany's robust automotive engineering and advanced manufacturing capabilities accelerate the adoption of durable 3D printing plastics for tooling and end-use parts. European regulations like REACH and RoHS directives influence material formulation, restricting hazardous substances in electronic and consumer components. Medical device manufacturing clusters in Bavaria and Baden-Württemberg increasingly rely on Selective Laser Sintering for patient-specific implants.
Japan
Japan's advanced robotics and automotive sectors drive the need for industrial-grade polymers with precise performance characteristics. The Ministry of Economy, Trade and Industry (METI) oversees standards for these materials, compelling suppliers to provide extensive data on consistency. Major manufacturing centers in the Kanto region and Aichi Prefecture are adopting 3D printing for functional prototypes and low-volume production.
India
India's rapidly expanding industrial manufacturing base creates significant potential for 3D printing plastics in prototyping and functional part production. Government initiatives, such as the Production Linked Incentive (PLI) schemes, encourage domestic manufacturing and technology adoption. Emerging industrial hubs in Maharashtra and Gujarat are seeing increased investment in additive manufacturing capabilities for diverse applications.
Brazil
Brazil's growing aerospace and automotive industries are beginning to leverage 3D printing plastics for jigs, fixtures, and specialized components. The country's national health surveillance agency, ANVISA, influences the adoption of medical-grade plastics for custom prosthetics and anatomical models. Manufacturing centers around São Paulo and Minas Gerais are exploring additive manufacturing to reduce lead times and optimize production processes.
3D Printing Plastics Market Key Industry Players
Concentration sits with established chemical conglomerates and specialized additive manufacturing solution providers in the 3D printing plastics market. The market exhibits a tiered structure, with a few large material producers supplying a broad portfolio, alongside niche players focusing on high-performance polymers. Strategic archetypes include integrated system providers, material specialists, and general chemical suppliers. Dominant competitive moves involve portfolio diversification into advanced materials and strategic partnerships for application engineering expertise.
Within the integrated system providers, Stratasys Ltd. exemplifies a strategy of pairing its printers with proprietary high-performance materials to ensure optimal performance and reliability. Arkema, a French specialty chemicals company, occupies a position as a material specialist, focusing on advanced polymers for demanding aerospace and automotive applications requiring superior mechanical properties. BASF SE, a German chemical giant, anchors the market as a broad chemical supplier, leveraging its extensive portfolio to develop specialized filaments and powders for industrial clients globally, emphasizing application engineering.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| Arkema |
| 3D Systems Corporation |
| BASF SE |
| Evonik Industries AG |
| SABIC |
| HP Inc. |
| Materialise NV |
| EOS GmbH |
| Others |
Cost & Logistics Intelligence
The substitution of traditional manufacturing processes with additive manufacturing simultaneously reshapes supply geography and pricing economics in the 3D printing plastics market. This shift elevates the value of specialized materials and localized production capabilities.
Pricing Analysis
Volume-discount tiering structures characterize pricing in the 3D printing plastics market. Pricing stratifies across premium, standard, and economy tiers, driven by certification levels like FDA biocompatibility and specific performance grades. Price differentiation also stems from the volume scale of material procurement. Pricing softness is intensifying in the prototyping segment due to increased competition and material accessibility. Consumer and educational segments exhibit the highest price sensitivity, while aerospace and medical device manufacturers are less sensitive to price fluctuations for certified materials.
Supply Chain Analysis
Shortened inventory cycles and reduced lead times are becoming critical supply chain observations. Supply concentrates in advanced chemical manufacturing hubs like Germany, the United States, and Japan. The market draws from specialized chemical feedstocks and high-performance polymer additives. Regulatory restrictions, such as Europe's REACH directives, pose a structural supply chain risk by influencing material formulation. Downstream distribution runs through direct sales channels to large industrial clients and a network of specialized material distributors for smaller fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a recovery phase that favors innovation-driven specialists, propelled by the accelerating industrial adoption of 3D printing technologies.
For Market Incumbents: Consolidate market position by acquiring niche high-performance polymer developers to expand material portfolios. Invest heavily in application engineering expertise to meet specific industrial client requirements, countering the threat from commodity plastics producers. Secure long-term supply agreements for critical chemical feedstocks to mitigate raw material price volatility.
For New Entrants and Emerging Players: Certification fast-tracks for medical and aerospace applications offer a strategic entry point. Target the underpenetrated industrial manufacturing sectors in emerging economies like India and Brazil. Focus on developing novel polymer composites with embedded functionalities, offering localized technical support to gain market share.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized material science companies with strong intellectual property. Long-term viability is strong, driven by sustained demand for customized end-use parts across regulated industries. Target high-performance polymer developers with established certification pathways. A signal to watch is the increasing number of regulatory approvals for new biocompatible or aerospace-grade materials.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Advanced Materials | Expands market reach by offering specialized solutions for high-value industrial applications. |
| Investment in Application Engineering Expertise | Strengthens customer relationships and enables co-development of tailored material solutions. |
| Strategic Partnerships for Certification | Accelerates market access for new materials in highly regulated sectors like medical and aerospace. |
| Expansion of Bio-based and Recycled Material Lines | Aligns with global sustainability mandates and captures demand from environmentally conscious end-users. |
| Localized Manufacturing and Distribution Hubs | Reduces lead times and enhances responsiveness for industrial clients in key regional markets. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings of this study. The research involved in-depth discussions with R&D directors, aerospace engineers, medical device manufacturers, and material procurement leads. Secondary validation drew from regulatory body publications such as FDA and REACH, industry association reports, academic journals, and company financial filings, triangulating insights through bottom-up and top-down approaches.
Sensitivity analysis framed the quantitative modeling across the projection horizon. The analytical framework integrated market segmentation across product type, technology, application, end-user, and regional regulatory environment. Compound Annual Growth Rates (CAGRs) were derived from historical data and projected growth drivers, utilizing forecast inputs such as R&D spending on new polymers and patent filings for additive manufacturing technologies.
Decision-makers should treat outputs as directional under base assumptions regarding technological maturation and regulatory stability; material deviation would warrant model refresh. Forecasts reflect assumptions on geopolitical trade stability and raw material availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
3D Printing Materials
3D Printing Materials Market
3D Printing Materials
Additive Manufacturing and Materials Market
3D Printing Materials
Europe Polypropylene in 3D Printing Market
3D Printing Materials
3D Printing Consumables Market
3D Printing Materials
Global 3D Printing Construction Material Market
3D Printing Materials
Metal Jet 3D Printing Technology Market
3D Printing Materials
Global 3D Printing Metals Market
3D Printing Materials
Global Arf Dry and Immersion Resist Materials Market
3D Printing Materials
Thermoformed Plastics for Printing Market
3D Printing Materials
Middle East 3D Printing Materials Market
3D Printing Materials
Industrial 3D Printing Plastic Market
3D Printing Materials
Low-Temperature Flow Improver Additives for 3D Printing Resins Market
3D Printing Materials
Medical 3D Printing Plastics Market
3D Printing Materials
3D Printing Elastomers Market
3D Printing Materials
3D Printing Photopolymers Market
3D Printing Materials
Global 3D Printing Filament Market