
 Dishwashing Liquid Market | 2026-2036
Dishwashing Liquid Market Size, Share, and Industry Trends Forecast 2026-2036
Dishwashing Liquid Market Insights
EPA Safer Choice certification is reorganizing competitive access in North America, filtering out legacy formulations that rely on nonylphenol ethoxylates. Procter & Gamble Company leverages its scale to secure multi-retailer shelf placement across club and grocery channels. Henkel AG & Co. KGaA anchors its position through concentrated formats that reduce per-wash plastic intensity. Unilever Plc competes on price-band breadth, spanning premium botanical lines to mass-market variants.
Dishwashing liquid denotes a surfactant-based aqueous cleaning formulation engineered to emulsify food oils and particulate residue from ceramic, glass, and metal tableware, typically operating at alkaline pH with anionic and non-ionic surfactants comprising 15–40% of total composition. The product serves both domestic hand-washing and commercial ware-washing applications where mechanical scrubbing supplements chemical action. Concentrated formats command disproportionate margin contribution as they shift value from water content to active chemistry and smaller packaging. Eco-Friendly variants are gaining fastest among segments, though Non-Concentrated stock-keeping units still dominate volume in emerging retail channels. Households represent the most defended customer tier, while Hotels and Restaurants are diversifying toward bulk-container procurement to manage per-cover cost.
EPA Safer Choice and EU Ecolabel standards are converging on stricter surfactant biodegradability thresholds, forcing reformulation cycles across multinational portfolios. The US FDA and state-level chemical disclosure laws in California and New York add compliance layers that favor producers with centralized toxicology and regulatory affairs functions. India's BIS certification for household cleaning products is expanding from voluntary to mandatory scope, raising entry barriers for unbranded regional suppliers. Stakeholders must monitor how refill-pack adoption rates interact with retailer private-label strategies and extended producer responsibility mandates.
Market Dynamics
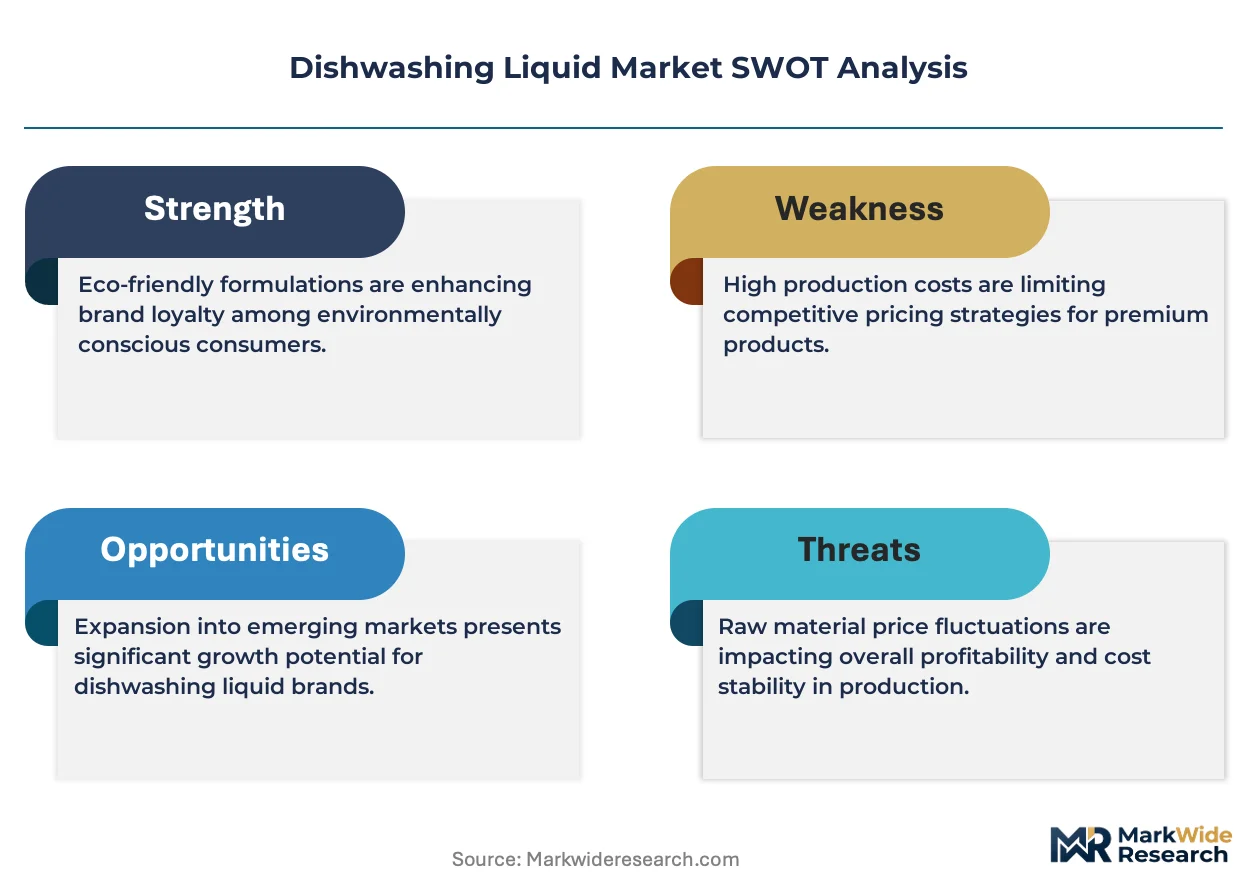
EPA Safer Choice and EU Ecolabel standards are forcing surfactant reformulation cycles across multinational portfolios, compressing legacy chemistry margins while opening certified-product premiums.
Growth Catalysts
- Commercial Hospitality Expansion:Hotels and restaurants in India and Southeast Asia are expanding procurement of professional-grade formulations for ware-washing operations, pulling volume toward bulk-container formats.
- REACH Biodegradability Thresholds:Stricter EU surfactant disclosure requirements under ECHA guidance are accelerating portfolio upgrades among incumbent suppliers.
- Concentrated Format Adoption:Active-chemistry loading above 30% is displacing water-heavy legacy SKUs in club and grocery channels, shifting value toward smaller packaging footprints.
Market Restraints
- Feedstock Volatility:Linear alkylbenzene sulfonate and palm-derived fatty alcohols face price swings tied to oleochemical supply chains concentrated in Malaysia and Indonesia.
- Private-Label Shelf Compression:Retailer-owned brands in European discounters are capturing price-sensitive volume, constraining branded-player margin expansion.
- Regulatory Friction:India's BIS mandatory certification rollout is raising compliance costs for unbranded regional suppliers, slowing informal-channel substitution.
Strategic Opportunities
- Refill-Pack Infrastructure:Concentrate-to-dilute systems in UK and German retail are creating recurring-revenue models that decouple volume from primary packaging.
- Botanical Ingredient Positioning:Coconut-derived surfactants and enzyme blends are opening premium price tiers in North American natural-channel distribution.
- Extended Producer Responsibility:EU packaging-waste directives are mandating post-consumer recycled content thresholds, favoring producers with captive recycling partnerships.
Industry Challenges
- Toxicology Talent Scarcity:Centralized regulatory affairs functions capable of navigating multi-jurisdiction surfactant dossiers command premium compensation, constraining mid-tier supplier expansion.
- Certification Timeline Compression:EPA Safer Choice and EU Ecolabel parallel review cycles are extending product-launch windows by 8-14 months for reformulated SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dishwashing Liquid Market |
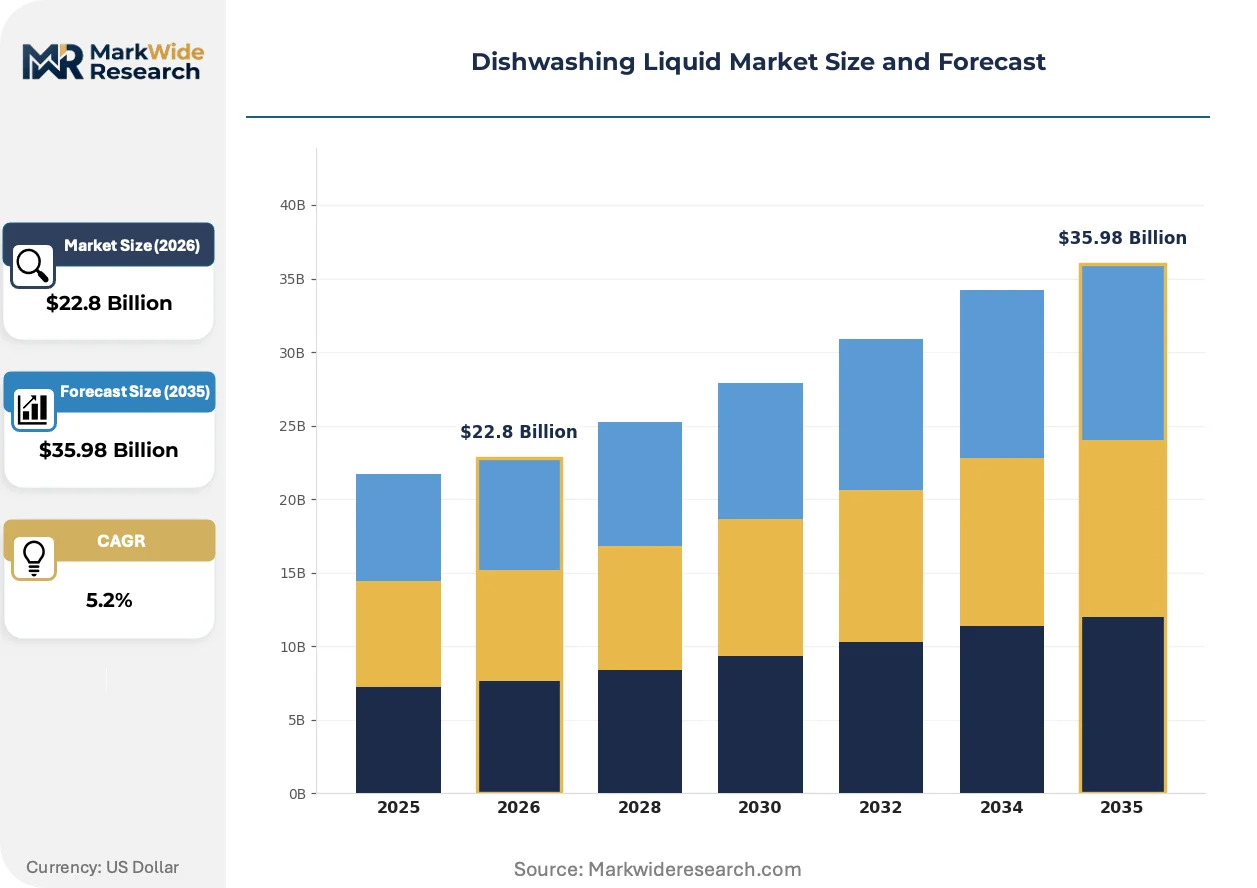
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $35.98 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated, Non-Concentrated, Eco-Friendly, Foaming Form: Liquid, Gel, Powder, Tablet Target Customer: Households, Restaurants, Cafes, Hotels Packaging Type: Bottle, Pouch, Refill Pack, Bulk Container |
| Companies Covered | Henkel AG & Co. KGaA, Kao Corporation, Procter & Gamble Company, Dropps, The Clorox Company, Unilever Plc, Colgate-Palmolive Company, Blueland, Reckitt Benckiser Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dishwashing Liquid Market Trends and Innovations
Formulation science and packaging engineering are diverging along sustainability-performance axes, with chemistry choices now determining channel access and margin structure.
Enzymatic dishwashing formulations are bifurcating competitive positioning in premium tiers. Protease and lipase blends target protein and lipid soils in commercial kitchens. North American hospitality buyers are adopting these formats at accelerating rates. The technology is compressing thermal-energy requirements while enabling cold-water wash claims that command shelf premiums.
REACH Annex XVII restrictions on nonylphenol ethoxylates are forcing surfactant substitutions across European portfolios. Industrial consequence includes accelerated R&D spend on alcohol ethoxylate alternatives. Professional-grade suppliers serving German and French institutional buyers are responding with pre-certified ingredient sourcing to maintain contract eligibility.
Subscription-based refill delivery is disrupting traditional grocery replenishment patterns. Direct-to-consumer channels in US coastal metros are replacing stock-up trips with scheduled concentrate shipments. Urban households with storage constraints represent the most visible adoption cluster, particularly in New York and San Francisco density corridors.
Dishwashing Liquid Market Segmentation
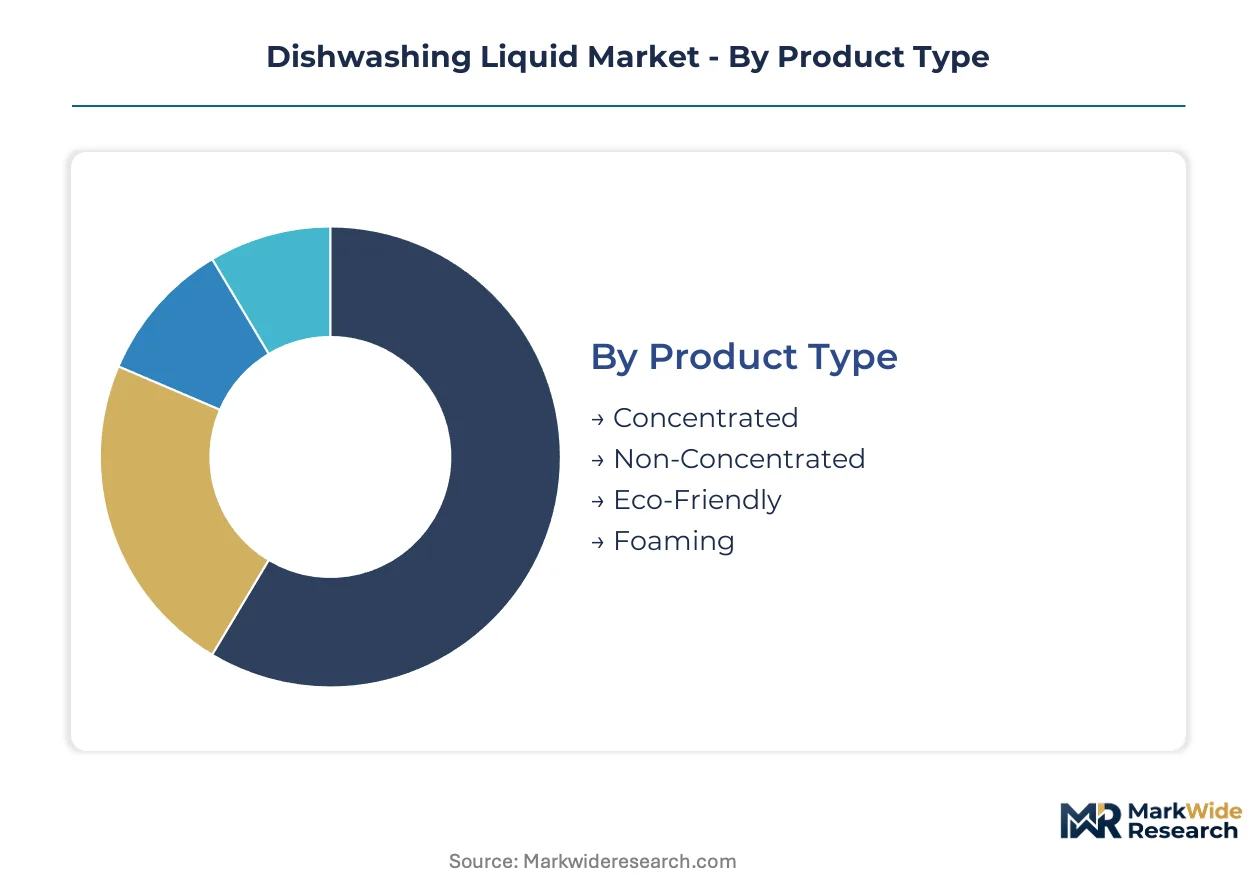
Dishwashing liquid segmentation reveals divergent margin structures across chemistry loading and packaging formats. Concentrated and eco-friendly variants command premium positioning in developed retail channels, while bulk formats dominate commercial procurement in emerging hospitality markets.
Product Type:
Concentrated formulations concentrate value in North American and European club retail, whereas non-concentrated variants retain volume leadership in Indian and Southeast Asian traditional trade channels.
- Concentrated:Surfactant loads exceeding 30% active chemistry displace water-heavy legacy stock-keeping units, shifting margin capture toward smaller packaging footprints and reduced per-wash plastic intensity in US and German grocery channels.
- Eco-Friendly:Coconut-derived surfactants and enzyme blends targeting EPA Safer Choice and EU Ecolabel certification are opening premium price tiers in California and New York metro natural-channel distribution, though certified-ingredient sourcing compresses formulation margins.
- Non-Concentrated:Water-dilute formulations remain dominant in Indian urban household penetration and Southeast Asian price-sensitive retail tiers.
- Foaming:Aerated chemistry variants serve visual-cleaning preference segments in Japanese and South Korean domestic markets.
Non-Concentrated commands the established base. The steepest expansion runs through Eco-Friendly.
Form:
Liquid formats anchor commercial kitchen throughput requirements, while gel and powder alternatives fragment across regional usage preferences and storage constraints.
- Liquid:Pump-dispense aqueous formulations engineered for rapid emulsification of lipid soils dominate US and UK hospitality ware-washing operations where mechanical scrubbing supplements chemical action.
- Gel:Viscous cling formulations extending contact time on vertical surfaces are gaining trial in German and French domestic markets with hard-water mineral content challenges.
- Powder:Granular alkaline builders concentrated for bulk institutional procurement serve Indian and Chinese commercial laundries with cost-per-cover optimization mandates.
- Tablet:Unit-dose compressed formats targeting single-wash convenience are penetrating UK and Dutch subscription-based refill delivery channels.
Liquid retains the volume anchor. Tablet formats are climbing the fastest through direct-to-consumer infrastructure.
Target Customer:
Household demand concentrates in branded retail with high purchase frequency, while commercial buyers in hospitality pursue bulk-container economics and professional-grade performance specifications.
- Households:Hand-washing applications in US, UK, and Indian urban residences drive repeat-purchase velocity through supermarket and hypermarket replenishment cycles, with storage constraints favoring concentrated formats.
- Hotels:Full-service hospitality operations in Dubai, Singapore, and Mumbai are diversifying toward bulk-container procurement to manage per-cover chemical costs in high-throughput banquet and restaurant facilities.
- Restaurants:Independent and chain foodservice establishments across Texas, Florida, and Maharashtra specify professional-grade formulations with grease-cutting surfactant packages for manual pot-and-pan operations.
- Cafes:Limited-menu coffeehouse operators in Seattle, Melbourne, and Berlin prioritize compact-format SKUs with rapid-rinse properties for high-turnover cup and saucer washing.
Households command the established base. Hotels are gaining share fastest through procurement centralization.
Packaging Type:
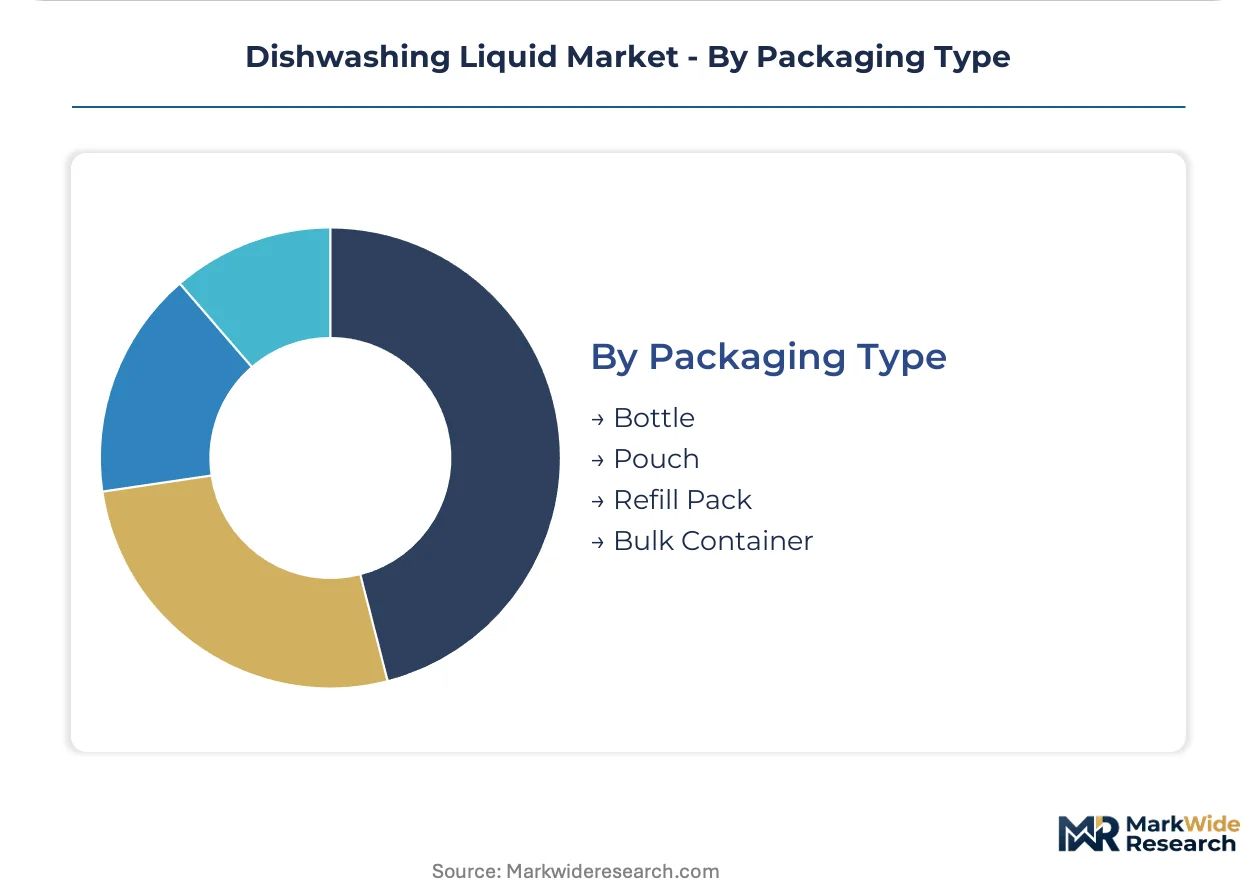
Primary bottle formats face displacement pressure from refill infrastructure and commercial bulk systems that decouple chemistry volume from packaging consumption.
- Refill Pack:Concentrate-to-dilute pouch systems in UK and German retail are creating recurring-revenue models that reduce per-unit primary packaging intensity while locking household replenishment patterns.
- Bulk Container:20-liter and larger polyethylene drums serve Indian and UAE hospitality procurement through institutional distributors, with returnable-container logistics gaining traction in EU circular-economy pilots.
- Bottle:Molded HDPE and PET primary containers retain dominance in US mass-market retail shelf placement despite extended producer responsibility mandates in California and New York.
- Pouch:Flexible laminate stand-up formats are penetrating Southeast Asian traditional trade channels with lower per-unit packaging cost and reduced shipping cube.
Bottle commands the established base. Refill Pack represents the steepest expansion trajectory through sustainability-positioned retail partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Household procurement concentrates in urban clusters with storage constraints and sustainability preferences, while commercial hospitality demand accelerates in high-growth metropolitan corridors with centralized procurement mandates.
United States
Subscription-based refill delivery disrupts traditional replenishment in New York and San Francisco density corridors. EPA Safer Choice certification filters legacy formulations from multi-retailer shelf placement. Procter & Gamble leverages club-channel scale to anchor concentrated-format distribution.
Germany
Concentrate-to-dilute pouch systems lock household replenishment through retail partnerships in UK and German markets. ECHA REACH Annex XVII restrictions on nonylphenol ethoxylates force surfactant substitutions across professional-grade portfolios. Industrial suppliers in the Rhine-Ruhr cluster respond with pre-certified ingredient sourcing.
India
Urban household penetration of branded products accelerates in Mumbai and Delhi-NCR as traditional trade channels formalize. BIS mandatory certification raises compliance costs for unbranded regional suppliers. Maharashtra hospitality procurement diversifies toward bulk-container formats for per-cover cost management.
United Kingdom
Tablet formats penetrate subscription-based direct-to-consumer channels in London and Dutch adjacent markets. EU packaging-waste directives mandate post-consumer recycled content thresholds. Retailer private-label strategies in European discounters capture price-sensitive volume.
Japan
Foaming chemistry variants serve visual-cleaning preference segments in domestic metropolitan markets. METI standards converge with EU biodegradability thresholds for surfactant disclosure. Kanto region warehousing clusters support just-in-time replenishment for high-frequency household purchase patterns.
Dishwashing Liquid Market Competitive Landscape
Player mix skews toward multinational conglomerates with centralized regulatory affairs functions and regional specialists with agile formulation capabilities. Tiered structure separates scale-driven mass-market suppliers from premium-positioned botanical specialists. Strategic archetypes include chemistry-forward innovators, private-label contract manufacturers, and sustainability-certified brand houses. Dominant competitive moves span portfolio diversification into concentrated formats and strategic partnerships with refill-pack retail infrastructure.
Among Germany-based conglomerates, Henkel AG & Co. KGaA anchors the concentrated-format tier through reduced per-wash plastic intensity positioning. US-based Procter & Gamble Company exemplifies scale-driven multi-channel shelf placement across club and grocery vectors. British-Dutch Unilever Plc occupies the price-band breadth archetype, spanning premium botanical lines to mass-market variants without vertical integration dependencies.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Kao Corporation |
| Procter & Gamble Company |
| Dropps |
| The Clorox Company |
| Unilever Plc |
| Colgate-Palmolive Company |
| Blueland |
| Reckitt Benckiser Group PLC |
| Others |
Pricing and Supply Chain Analysis
EPA Safer Choice certification gates both supplier qualification and price-tier access in North American retail, compressing uncertified chemistry margins while enabling premium capture for compliant formulations across club and grocery channels.
Pricing Analysis
Cost-plus contracts with palm-derived fatty alcohol indexation dominate professional-grade procurement for hospitality buyers in India and the UAE. Three-tier pricing structure across premium botanical lines, standard concentrated formats, and economy non-concentrated SKUs reflects certification grade and active-chemistry loading. Cost compression in economy tiers is intensifying because retailer private-label expansion in European discounters constrains branded-player margin expansion. Quick-service restaurants in Texas and Florida exhibit highest price sensitivity, while German institutional buyers with Ecolabel mandates show lowest sensitivity due to compliance-driven specification lock-in.
Supply Chain Analysis
Malaysia and Indonesia anchor oleochemical feedstock production for linear alkylbenzene sulfonate and coconut-derived surfactants. Formulation chemistry draws from palm oil derivatives, petroleum-based sulfonates, and enzyme blends produced in the Rhine-Ruhr cluster. Single-source vulnerability concentrates in Southeast Asian oleochemical processing exposed to El Niño-driven feedstock disruption. Distribution runs through institutional distributors for bulk-container hospitality procurement and direct-to-retail for concentrated household formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits regulatory-entrenchment moats: certification timelines and toxicology dossier requirements create switching costs that protect incumbent positions against agile regional challengers.
For Market Incumbents: Secure pre-certified ingredient sourcing partnerships to compress EPA Safer Choice and EU Ecolabel parallel review cycles that currently extend launch windows. Anchor concentrated-format capacity expansion in Indian and Southeast Asian production hubs to capture hospitality procurement centralization. Vertical integration into captive surfactant production mitigates oleochemical price volatility threatening legacy margin structures. For New Entrants and Emerging Players: Anchor in subscription-based refill delivery infrastructure serving New York and San Francisco density corridors where storage-constrained urban households favor concentrate-to-dilute systems. Target Indian urban household penetration acceleration as the most penetrable geography, where BIS certification rollout is displacing unbranded regional suppliers. Pursue botanical-ingredient positioning through natural-channel distribution partnerships with California and New York metro retailers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic formulation R&D and pre-certified ingredient sourcing infrastructure. Five-to-ten-year viability favors acquiring mid-tier suppliers with centralized regulatory affairs capabilities and existing Ecolabel dossiers. Monitor refill-pack adoption rates in UK and German retail as the critical inflection signal for packaging-light business model displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Pre-Certified Ingredient Sourcing | Compresses EPA Safer Choice and EU Ecolabel parallel review timelines for reformulated SKUs. |
| Concentrated Format Capacity Expansion | Captures value migration from water-heavy legacy SKUs in Indian and Southeast Asian hospitality procurement. |
| Subscription Refill Infrastructure | Locks household replenishment patterns through UK and German retail partnerships reducing packaging intensity. |
| Botanical Surfactant R&D Investment | Opens premium price tiers in California and New York metro natural-channel distribution. |
| Backward Integration into Oleochemical Supply | Mitigates Malaysian and Indonesian feedstock volatility exposure threatening formulation margins. |
Research Methodology
Desk research of customs trade records, SEC 10-K filings, and EPA Safer Choice certified-product databases preceded structured interviews with brand managers, category buyers at club and grocery retailers, formulation chemists, and hospitality procurement directors. Primary fieldwork combined with secondary validation against Nielsen retail audit data and BIS certification registries. Bottom-up volume builds across product type, form, target customer, and packaging type segments were triangulated with top-down market sizing.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects in concentrated versus non-concentrated format adoption. Segmentation dimensions modeled include chemistry loading tier, end-use application, packaging format, and regional regulatory cluster. CAGRs were derived from segment-level growth rate synthesis. Forecast inputs incorporate enzymatic formulation penetration curves and refill-pack infrastructure buildout rates.
Decision-makers should treat outputs as directional under sustained EPA Safer Choice and EU Ecolabel convergence assumptions; material deviation in certification timeline compression or oleochemical supply disruption would warrant model refresh. Specific risk factors include BIS enforcement intensity in India and private-label shelf compression in European discounters. Recalibration cycles align with material shifts in surfactant biodegradability thresholds and extended producer responsibility mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Air Duct Cleaning Chemicals Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
US Specialty Cleaners Market
Cleaning Chemicals
Global Dust Suppression and Control Chemicals Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Soap and Detergent Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Floor Wax Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Descaler Market