
 Global Dust Suppression and Control Chemicals Market | 2026-2036
Global Dust Suppression and Control Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dust Suppression and Control Chemicals Market Foresight
Specialized chemical formulation expertise is reorganizing competitive dynamics as mining companies demand site-specific dust control protocols rather than generic product lines. Borregaard AS leverages its lignosulfonate chemistry heritage to dominate biopolymer-based road stabilization formulations across Nordic and South American mining corridors. Cargill Incorporated anchors its position through backward integration into agricultural feedstock streams that supply raw material for chloride-based dust suppressants. Ecolab Inc. competes on integrated service models bundling chemical supply with application equipment and compliance monitoring.
Dust suppression and control chemicals encompass hygroscopic salts, petroleum-derived binders, synthetic polymer emulsions, and lignin-based biopolymers engineered to agglomerate fine particulate matter or form surface crusts on unpaved roads, stockpiles, and disturbed earth. Calcium chloride and magnesium chloride function through deliquescence, absorbing atmospheric moisture to maintain road surface dampness at application rates typically ranging from 1.5 to 2.5 liters per square meter. Synthetic polymers command premium positioning in high-traffic mining haul roads where durability requirements exceed the performance envelope of commodity chlorides. Lignosulfonates occupy a growing niche as mining operators face Scope 3 emissions scrutiny and seek bio-based alternatives to petroleum-derived binders.
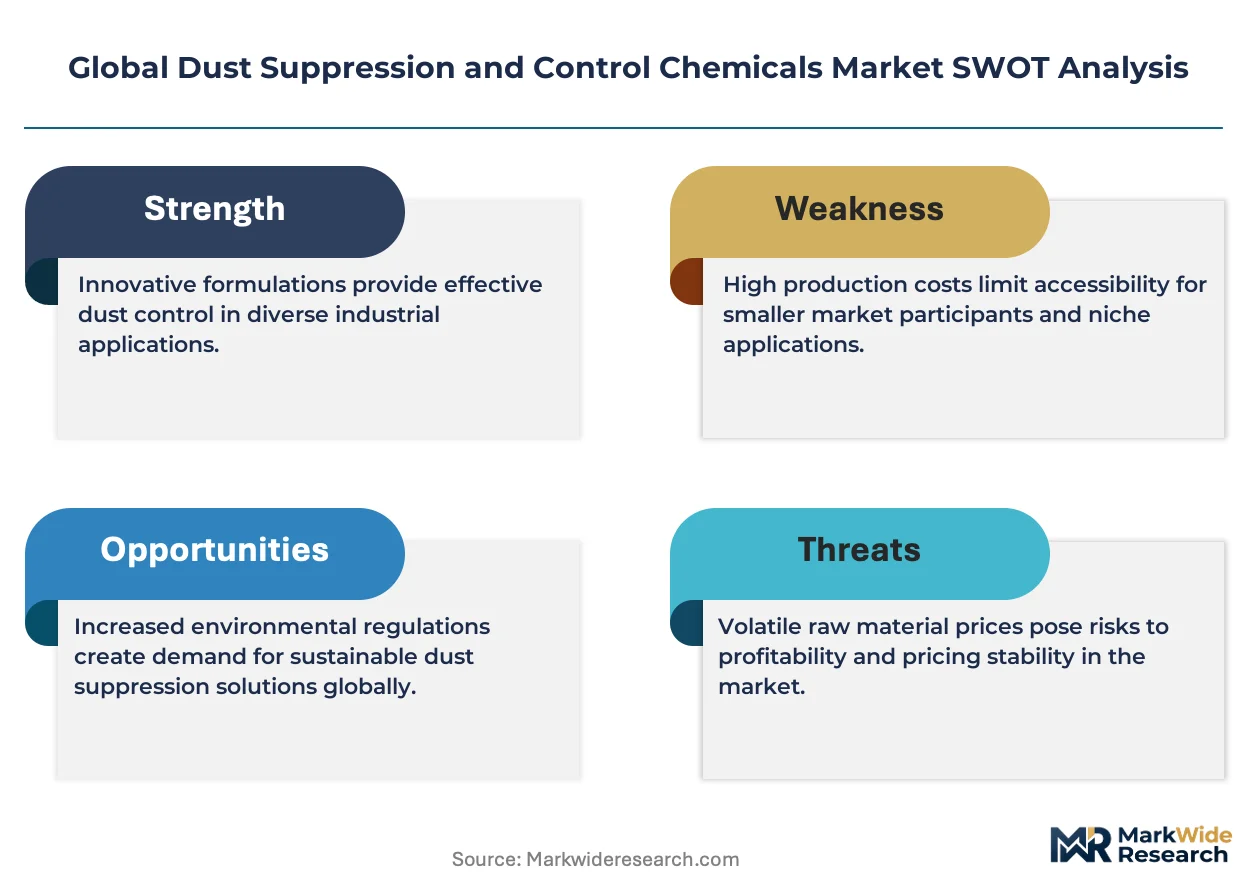
The US EPA enforces PM10 and PM2.5 thresholds under the Clean Air Act, while Australia's state-level environmental protection agencies impose mine-specific dust management plans with real-time monitoring mandates. The EU Green Deal's zero-pollution ambition and associated Industrial Emissions Directive revisions are extending compliance obligations to construction and demolition sites previously exempt from intensive dust regulation. Stakeholders must monitor the divergence between regional regulatory stringency and chemical product registration requirements as this gap determines where formulation innovation investments generate fastest market access returns.
Market Dynamics
Pit deepening at Australian and Chilean copper and iron ore mines is intensifying haul road dust loads, forcing operators to escalate chemical application rates and upgrade from commodity chlorides to polymer-based formulations.
Growth Catalysts
- EPA National Ambient Air Quality Standards:Tightening PM10 and PM2.5 thresholds under the US Clean Air Act are mandating fugitive dust controls at industrial sites previously operating under exemption thresholds.
- Pilbara iron ore expansion:Western Australia's production volume growth directly tracks dust management spend, with major operators standardizing site-specific chemical protocols across their haul road networks.
- Lignosulfonate chemistry:Biopolymer-based road stabilization formulations are capturing share as mining operators face Scope 3 emissions scrutiny and seek alternatives to petroleum-derived binders.
Market Restraints
- Calcium chloride feedstock volatility:Agricultural and oilfield demand for brine-derived salts creates price instability for hygroscopic dust suppressant producers.
- Application equipment capex:Synthetic polymer emulsions require specialized spray systems with automated dosing controls, raising capital barriers for smaller mining contractors.
- EU Green Deal compliance layering:The zero-pollution ambition and Industrial Emissions Directive revisions are extending registration requirements to construction and demolition sites, fragmenting product approval pathways.
Strategic Opportunities
- India's mining corridor expansion:Odisha and Jharkhand iron ore belt development is outpacing domestic dust chemical supply, creating import substitution openings for chloride and polymer suppliers.
- Integrated service bundling:Chemical supply combined with real-time compliance monitoring and application equipment leasing is capturing multi-year contracts from risk-averse operators.
- EU Green Deal tailwinds:The zero-pollution ambition is accelerating bio-based formulation preference in Nordic and German mining operations, favoring lignin chemistry specialists.
Industry Challenges
- Site-specific formulation expertise:Mining companies demand customized dust control protocols calibrated to local ore chemistry, traffic density, and rainfall patterns, stretching technical service capacity.
- Real-time monitoring integration:Australia's state-level environmental protection agencies mandate mine-specific dust management plans with continuous particulate sensors, requiring chemical suppliers to interface with IoT telemetry systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dust Suppression and Control Chemicals Market |
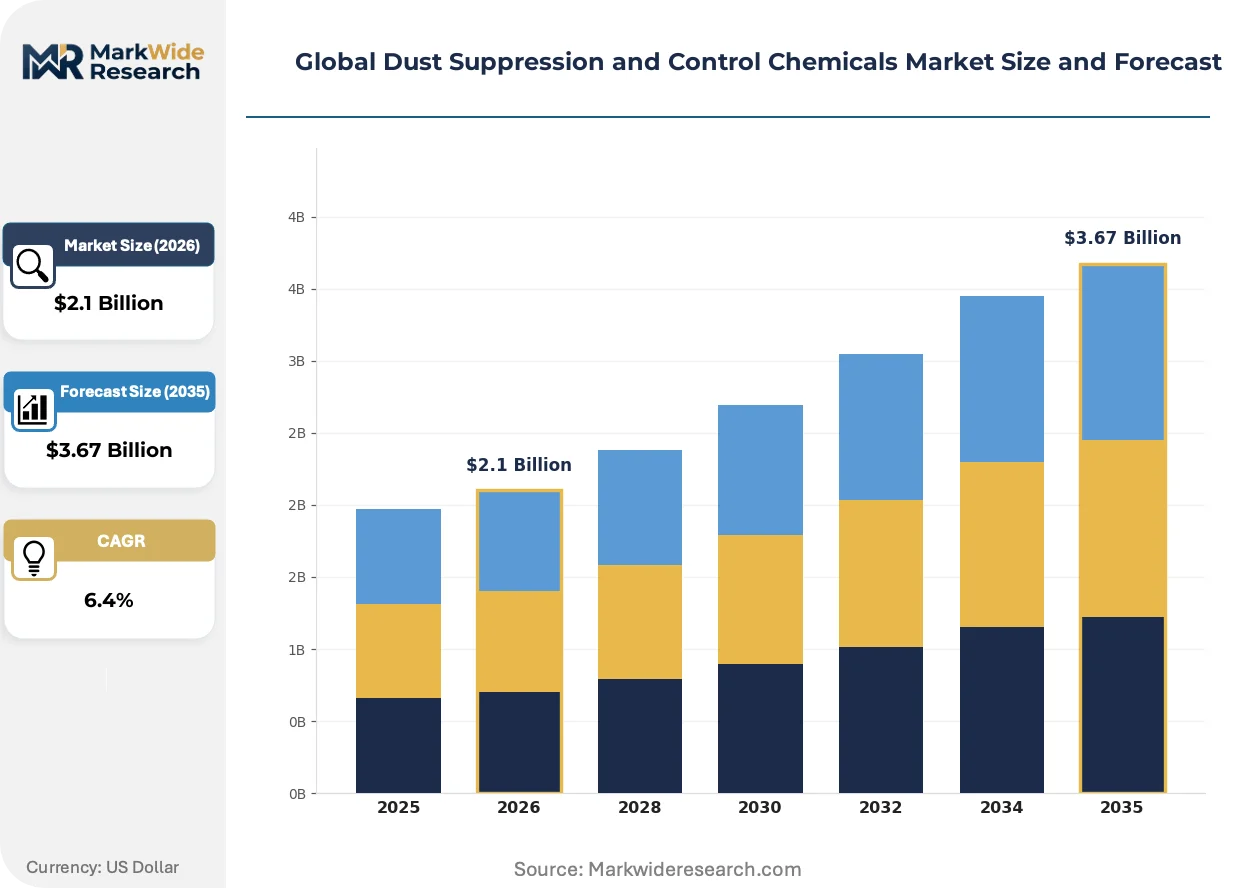
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Chloride, Magnesium Chloride, Lignosulfonates, Synthetic Polymers, Bituminous Emulsions Application: Road Construction, Mining Operations, Industrial Sites, Agricultural Fields, Construction Zones End User: Municipal Authorities, Mining Companies, Construction Firms, Agriculture Producers, Transportation Agencies Deployment: Spraying Systems, Mist Cannons, Water Trucks, Foaming Agents, Surface Coatings |
| Companies Covered | Borregaard AS, Cargill Incorporated, Ecolab Inc., Quaker Chemical Corporation, Solenis LLC, Soilworks LLC, Hexion Inc., Midwest Industrial Supply Inc., Dust-A-Side, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dust Suppression and Control Chemicals Market Shifts & Advancements
Formulation chemistry is bifurcating between high-performance synthetic polymers for deep-pit mining and bio-based alternatives for emissions-conscious operators, while regulatory monitoring mandates are digitizing the entire application workflow.
Synthetic polymer emulsions with enhanced UV stability and traffic resistance are displacing commodity magnesium chloride on high-tonnage haul roads in Western Australia's Pilbara region. Major iron ore operators now specify polymer-only protocols for roads exceeding 50,000 tonne-per-day traffic loads. This displacement is compressing margins for bulk chloride producers while creating premium pricing tiers for formulation specialists with patented emulsion chemistry.
The EU Green Deal's zero-pollution ambition and associated Industrial Emissions Directive revisions are extending compliance obligations to construction and demolition sites previously exempt from intensive dust regulation. Chemical suppliers must now navigate divergent product registration requirements across member states while reformulating legacy petroleum-based binders to meet bio-content thresholds. German and French regulators are leading enforcement, with construction chemical distributors in these markets accelerating lignosulfonate stocking.
Buyer preference is hardening around performance-guaranteed service contracts rather than standalone chemical procurement. Mining operators in Chile's Atacama copper belt now demand outcome-based agreements tying payment to measured PM10 reduction at site perimeters. This unbundling of chemical supply from application liability is favoring integrated service providers with captive equipment fleets and environmental monitoring capabilities over commodity chemical traders.
Global Dust Suppression and Control Chemicals Market Segmentation
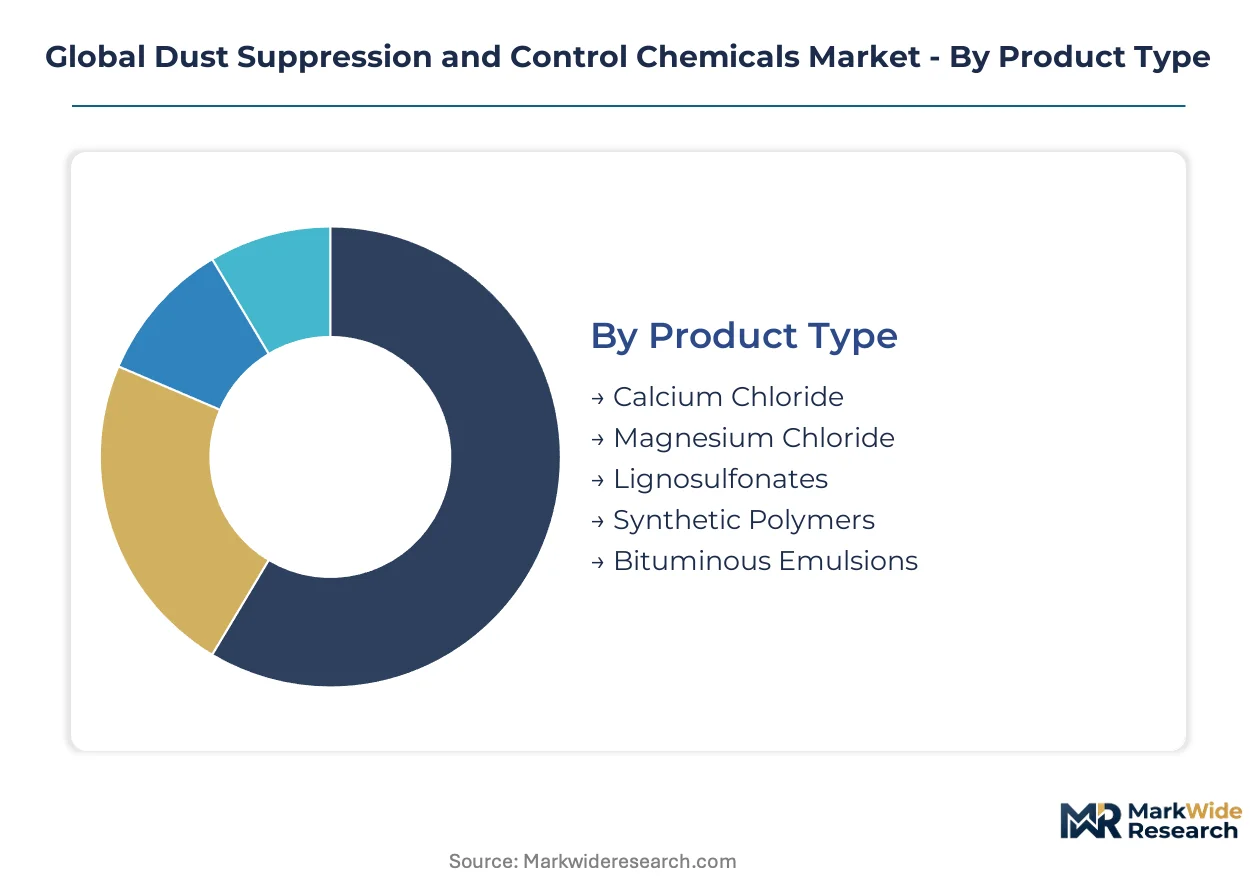
Segmentation in dust suppression chemicals reveals how formulation chemistry, application intensity, and deployment infrastructure create distinct margin architectures. Product type stratification separates commodity chlorides from premium polymers, while deployment mode determines whether suppliers capture equipment-anchored recurring revenue or transactional chemical sales.
Product Type:
Margin pools concentrate in synthetic polymer formulations where patent-protected emulsion chemistry commands pricing premiums over commodity salts.
- Calcium Chloride:Deliquescent salt absorbs atmospheric moisture to maintain surface dampness on unpaved haul roads. Demand concentrates in North American winter maintenance and mining corridors where cost minimization overrides performance optimization, though agricultural and oilfield brine competition destabilizes feedstock pricing.
- Synthetic Polymers:Acrylic and vinyl acetate emulsions form durable surface crusts resistant to high-tonnage traffic and UV degradation. Western Australia's Pilbara iron ore operators specify polymer-only protocols for roads exceeding 50,000 tonne-per-day loads, displacing chlorides and compressing margins for bulk salt producers.
- Magnesium Chloride:Hygroscopic salt with lower effective temperature range than calcium chloride, favored in moderate-climate mining districts.
- Lignosulfonates:Biopolymer binders derived from wood pulping byproducts, gaining preference in EU mining operations under Scope 3 emissions scrutiny.
- Bituminous Emulsions:Petroleum-derived surface sealants with established use in road construction base stabilization.
Calcium chloride holds installed capacity. Synthetic polymers are rotating up the share rankings.
Application:
Volume concentration tracks mining investment cycles, with pit deepening in Australia and Chile intensifying chemical consumption per tonne of ore extracted.
- Mining Operations:Haul road dust suppression consumes the highest application rates as copper and iron ore pit depths increase, forcing operators to escalate from commodity chlorides to polymer-based formulations capable of withstanding extreme traffic loads and arid conditions.
- Road Construction:Unpaved road stabilization during civil infrastructure projects requires intermittent chemical treatment synchronized with grading schedules.
- Industrial Sites:Stockpile and material handling dust control at processing facilities faces tightening EPA PM10 thresholds under Clean Air Act enforcement.
- Construction Zones:EU Green Deal zero-pollution ambition extends Industrial Emissions Directive obligations to demolition and earthmoving sites previously exempt from intensive dust regulation.
- Agricultural Fields:Tillage and harvest dust suppression represents seasonal, price-sensitive demand with limited formulation sophistication.
Mining operations anchor volume demand. Construction zones are expanding the regulatory addressable market.
End User:
Procurement authority fragmentation shapes contract structure, with integrated service bundling capturing multi-year agreements from risk-averse mining operators.
- Mining Companies:Chile's Atacama copper belt operators now demand outcome-based agreements tying payment to measured PM10 reduction at site perimeters, favoring suppliers with captive equipment fleets and environmental monitoring capabilities.
- Municipal Authorities:County and state transportation departments specify hygroscopic salts for unpaved road maintenance within constrained maintenance budgets.
- Construction Firms:Project-based procurement with limited technical expertise drives preference for turnkey dust management service contracts over chemical self-application.
- Agriculture Producers:Seasonal demand from grain handling and livestock operations prioritizes lowest-unit-cost solutions.
- Transportation Agencies:Federal and state highway departments maintain qualified product lists with standardized performance testing protocols.
Mining companies command premium formulation development. Construction firms are shifting toward integrated service procurement.
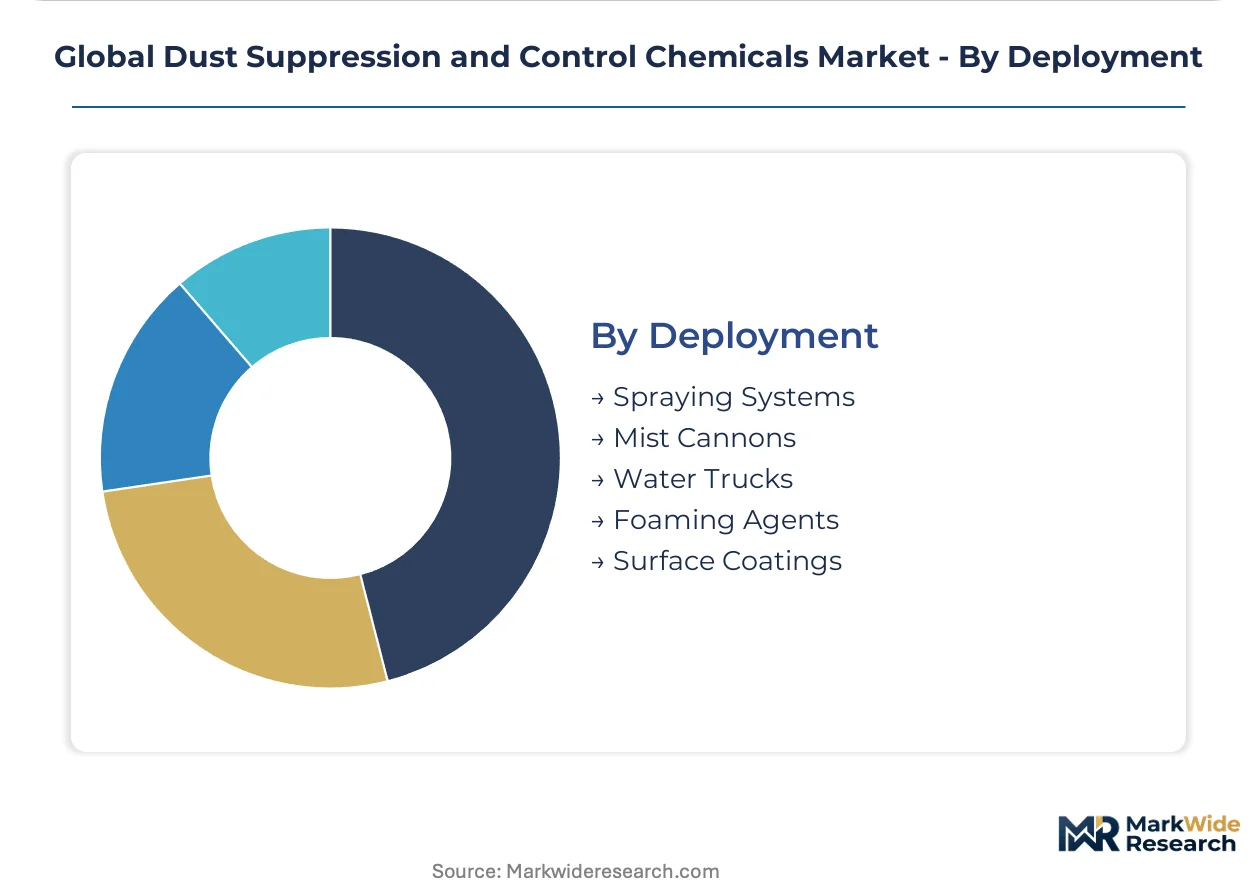
Deployment:
Equipment-anchored deployment modes create recurring revenue streams and raise switching costs through automated dosing system integration.
- Spraying Systems:Truck-mounted or fixed infrastructure spray equipment with automated dosing controls enables precise application rate management, required for synthetic polymer emulsions and mandated by Australian state environmental protection agencies for real-time compliance monitoring.
- Mist Cannons:Mobile particulate suppression for demolition and material handling operations with immediate coverage requirements.
- Water Trucks:Conventional surface wetting with limited chemical addition, prevalent in cost-constrained municipal road maintenance.
- Foaming Agents:Specialized surfactant systems for coal and ore dust suppression during crushing and conveying.
- Surface Coatings:Long-duration crust-forming treatments for stockpile sealing and inactive road segments.
Spraying systems hold installed capacity. Mist cannons are gaining adoption in European construction compliance markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Australian and Chilean mining corridors favor synthetic polymer formulations for extreme haul road conditions, while North American municipalities prioritize cost-minimizing chloride salts for seasonal road maintenance.
Australia
Western Australia's Pilbara iron ore region drives premium formulation demand as pit depths exceed 300 meters and haul road dust loads intensify. The state's environmental protection agencies mandate real-time PM10 monitoring with automated compliance reporting. Major operators in the Newman-Karratha corridor now specify polymer-only protocols for roads handling over 50,000 tonnes daily.
United States
Industrial fugitive dust enforcement is tightening as the EPA revises National Ambient Air Quality Standards for particulate matter. The Clean Air Act's PM10 and PM2.5 thresholds now capture previously exempt construction and demolition sites. Dust management spend concentrates in Arizona's copper belt and Wyoming's Powder River Basin coal operations.
Chile
Atacama copper mines are escalating chemical application rates as open-pit operations descend below historical water table levels. The country's environmental assessment service requires dust management plans with continuous perimeter monitoring. Antofagasta and Calama mining clusters are standardizing outcome-based service contracts tied to measured emissions reduction.
Germany
The EU Green Deal's zero-pollution ambition is accelerating bio-based formulation preference in construction and mining applications. REACH registration requirements and Industrial Emissions Directive revisions are fragmenting product approval pathways for petroleum-derived binders. Lignite mining regions in North Rhine-Westphalia are piloting lignosulfonate road stabilization at scale.
India
Odisha and Jharkhand iron ore belt expansion is outpacing domestic dust chemical manufacturing capacity. The country's central pollution control board is extending particulate emission norms to captive mining operations previously under state jurisdiction. Keonjhar and Sundergarh districts are emerging as import substitution battlegrounds for chloride and polymer suppliers.
Global Dust Suppression and Control Chemicals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in this market's competitive architecture. The upper tier captures multi-year service contracts bundling chemical supply with application equipment and compliance monitoring, while specialists compete on formulation chemistry for site-specific protocols. Three archetypes dominate: backward-integrated agricultural feedstock players, biopolymer chemistry heritage firms, and integrated environmental services conglomerates. Competitive dynamics center on M&A to acquire regional application service capabilities and strategic partnerships to secure lignin feedstock streams for bio-based product lines.
Among Nordic and North American specialists, Borregaard AS exemplifies the biopolymer chemistry archetype with its lignosulfonate heritage positioning. Cargill Incorporated anchors the agricultural feedstock-integrated tier through captive supply chains for chloride-based suppressants. Ecolab Inc. occupies the integrated services position, representing the environmental conglomerate model that bundles chemical supply with compliance infrastructure. Each archetype captures distinct margin pools based on whether buyers prioritize feedstock security, emissions credentials, or risk-transfer contracting.
| Leading Market Players |
|---|
| Borregaard AS |
| Cargill Incorporated |
| Ecolab Inc. |
| Quaker Chemical Corporation |
| Solenis LLC |
| Soilworks LLC |
| Hexion Inc. |
| Midwest Industrial Supply Inc. |
| Dust-A-Side |
| Others |
Supply & Pricing Matrix
Capacity utilization at Australian and Chilean lignosulfonate extraction facilities shapes both regional supply concentration and minimum viable pricing for biopolymer dust suppressants. Scale advantages in these corridors compress unit economics for commodity chloride producers while elevating price floors for specialty polymer formulations.
Pricing Analysis
Long-term offtake contracts dominate procurement in Western Australia's Pilbara iron ore region, locking in polymer supply at volume-scaled rates while spot markets handle chloride replenishment for seasonal municipal programs. Price differentiation separates premium synthetic emulsions with patented UV stabilizers from standard lignosulfonate blends and economy-grade calcium chloride sourced from agricultural brine streams. Cost compression in the chloride tier intensifies as oilfield demand competes for identical brine feedstock. Mining companies with integrated haul road networks exhibit lowest price sensitivity, whereas municipal authorities in North American winter maintenance programs prioritize lowest-unit-cost procurement.
Supply Chain Analysis
Australia and Chile anchor global supply for mining-grade dust suppressants, with Nordic countries commanding biopolymer formulation capacity. Raw material flows draw from agricultural brine deposits for calcium chloride, wood pulping byproduct streams for lignosulfonates, and petroleum refining residuals for bituminous emulsions. Single-source vulnerability concentrates in lignin feedstock, where Borregaard's pulping partnerships control specialty-grade supply. Distribution runs through regional chemical distributors with qualified product lists, though integrated service providers are capturing direct mine-site delivery through equipment-anchored contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as major iron ore and copper operators consolidate dust management spend under single procurement umbrellas, compressing vendor margins and elevating technical service requirements.
For Market Incumbents: Fortify regional application service capabilities through captive equipment fleet expansion in Western Australia and Chile's Atacama corridor. Lignosulfonate specialists should deepen backward integration into pulp mill partnerships to secure bio-based feedstock against emerging biopolymer competitors. Incumbents face substitution threat from integrated environmental services conglomerates bundling compliance monitoring with chemical supply. For New Entrants and Emerging Players: Differentiate on real-time IoT telemetry integration for Australia's state-mandated dust management plans. India's Odisha and Jharkhand iron ore belt presents the most penetrable geography, with domestic supply deficits forcing import dependence. A service-leasing model targeting mid-tier mining contractors bypasses capital barriers that exclude them from polymer spray system ownership. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service providers with multi-year outcome-based contracts tied to measured PM10 reduction. Long-term viability favors suppliers with formulation patents in UV-stable polymer emulsions or exclusive lignin supply agreements. Watch for inflection when EU Green Deal enforcement extends bio-content mandates to construction chemicals, accelerating lignosulfonate preference.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lignin Feedstock | Secures bio-based raw material streams for EU Green Deal-compliant formulation expansion. |
| Equipment Fleet Captive Leasing | Locks in multi-year chemical offtake through automated spray system deployment at mine sites. |
| IoT Telemetry Partnership | Interfaces polymer application systems with Australian state environmental protection agency monitoring mandates. |
| Regional Manufacturing Capacity | Reduces logistics cost exposure for chloride supply into India's expanding Odisha iron ore corridor. |
| Outcome-Based Contract Structuring | Transfers PM10 compliance liability from mining operators to chemical suppliers with monitoring capabilities. |
Research Methodology
Operator-level perspectives from mine site engineers, environmental compliance officers, haul road maintenance supervisors, and procurement directors at major iron ore and copper operators anchored the qualitative base. These primary insights combined with secondary validation from EPA enforcement records, Australian state environmental protection agency compliance databases, SEC 10-K filings of listed chemical suppliers, and trade flow data from Chilean and Australian customs authorities. Bottom-up segment sizing triangulated against top-down market estimates derived from mining production volume correlations with dust management spend intensity.
Sensitivity analysis tested forecast robustness across application rate scenarios, feedstock price volatility bands, and regulatory enforcement intensity variations over the projection horizon. Segmentation dimensions modeled include product chemistry tier, deployment infrastructure type, end-use industry vertical, and regional production hub cluster. CAGRs were derived from trend extrapolation of historical mining investment cycles and dust regulation implementation timelines, with specific inputs from pit deepening rates in Australian and Chilean open-pit operations and EU Green Deal bio-content threshold phase-ins.
Material uncertainties — regulatory enforcement acceleration, lignin feedstock supply disruptions, and mining capex cycle downturns — sit outside the modeled envelope. Forecasts reflect assumptions about sustained commodity pricing support for deep-pit mining economics and gradual bio-based formulation preference shifts. Recalibration cycles align with material shifts in EPA National Ambient Air Quality Standards revisions and EU Industrial Emissions Directive enforcement milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
Acid Coil Cleaner Market
Cleaning Chemicals
Air Duct Cleaning Chemicals Market
Cleaning Chemicals
Purging Compound Market
Cleaning Chemicals
Green Floor Care Chemical Systems for Commercial Facilities Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market
Cleaning Chemicals
Chlorinating Agents Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market