
 Bakery Fats Market | 2026-2036
Bakery Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Fats Market Intelligence
Modular fat blends with tailored functionality for specific dough systems is hardening as the dominant configuration pattern. CSM Ingredients leverages its European R&D network to sustain leadership in specialty margarine formulations. Fuji Oil Co. Ltd anchors its position through integrated tropical oil sourcing and fractionation capabilities across Southeast Asia.
Bakery fats comprise lipid-based formulations designed to provide plasticity, aeration, and shelf stability in dough and batter systems, typically containing 80-85% fat with emulsifiers and antioxidants to control crystallization behavior. Shortening dominates industrial volume due to its versatility across laminated and chemically leavened applications, while butter commands premium positioning in artisan and clean-label segments where fat identity matters to consumers. Margarine competes aggressively in cost-sensitive channels, particularly within food manufacturers seeking standardized performance across high-output lines.
EFSA evaluates novel fat compositions under the EU Novel Food Regulation, while REACH governs additive chemistries in emulsifier systems, together elevating compliance costs for reformulated shortenings and spreads. FDA labeling rules for trans fat disclosure and GRAS determinations for interesterified alternatives shape product development priorities for exporters targeting North America. Stakeholders must monitor evolving palm oil sustainability certification schemes and their intersection with national bioeconomy strategies to secure supply chain continuity and market access.
Market Dynamics
Europe's F-Gas Regulation and REACH standards are forcing accelerated reformulation of bakery fat portfolios, compressing timelines for palm oil substitution while elevating compliance costs across integrated supply chains.
Growth Catalysts
- Clean-label mandates:EFSA evaluations under the EU Novel Food Regulation drive adoption of interesterified alternatives in artisan bakery segments seeking plasticity without hydrogenation.
- Quick-service bakery expansion:Southeast Asian quick-service chains concentrate demand for standardized shortening formulations with extended fry stability.
- Tropical oil processing clusters:Malaysian and Indonesian fractionation infrastructure enables cost-competitive supply of palm mid-fractions for laminated dough applications.
Market Restraints
- Feedstock price volatility:Crude palm oil futures expose margarine producers to margin compression when lauric oil spreads widen unexpectedly.
- Single-origin supply risk:Indonesia's export levy fluctuations and Malaysian sustainability certification backlogs create input uncertainty for European compounders.
- Crystallization control limits:Current enzymatic interesterification cannot fully replicate the polymorphic stability of hydrogenated fats in puff pastry lamination.
Strategic Opportunities
- Underpenetrated African markets:Nigeria and Kenya's informal bakery sectors remain underserved by branded shortening suppliers with technical service capabilities.
- Regulatory tailwinds:France's AGEC anti-waste law and extended producer responsibility frameworks incentivize recyclable packaging for foodservice fat portions.
- Precision fermentation lipids:Convergence of microbial oil production and enzymatic modification opens pathways for custom-tailored triglyceride profiles.
Industry Challenges
- Fat crystallography expertise gap:Formulation chemists with polymorphism control skills are scarce relative to reformulation pipeline demands.
- Multi-certification complexity:Simultaneous RSPO, ISCC, and national bioeconomy compliance extends product qualification timelines by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakery Fats Market |
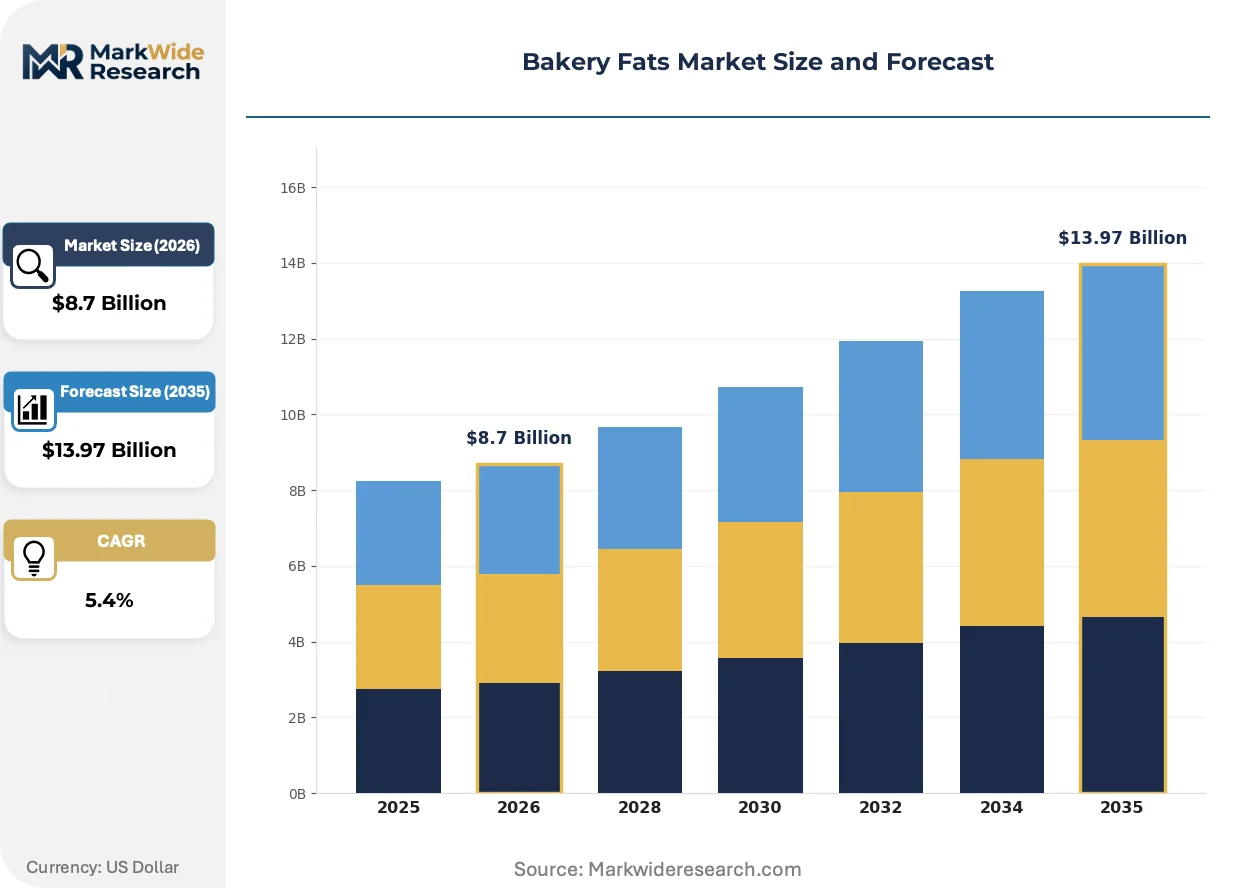
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Shortening, Oils Texture: Soft, Creamy, Spready, Hard Application: Bread, Pastry, Cake, Cookies End User: Bakeries, Restaurants, Home Cooks, Food Manufacturers |
| Companies Covered | CSM Ingredients, Fuji Oil Co. Ltd, AAK International, Wilmar International Ltd, Goodman Fielder, Bunge, Dawn Food Products, Premium Vegetable Oils Sdn Bhd, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Fats Market Strategic Shifts & Innovations
Modular fat systems are displacing commodity shortenings as bakeries demand application-specific functionality rather than one-size-fits-all formulations. This shift rewards suppliers with integrated R&D and fractionation capabilities.
Enzymatic interesterification is integrating into industrial margarine production lines, enabling precise control of triglyceride positioning without trans fat generation. European industrial bakeries are retrofitting plants at pace to secure clean-label positioning. This technology is compressing the performance gap between premium shortenings and modified palm fractions.
REACH registration requirements for emulsifier chemistries are tightening additive approval pathways for bakery fat reformulations. ECHA's expanded substance evaluation list now captures several polyglycerol esters used in cake gels. Compounders serving the EU market are accelerating substitution programs for affected emulsifier grades.
Artisan bakery procurement is consolidating around certified sustainable palm claims as a non-negotiable supplier qualification. Clean-label distributors are displacing traditional broadline foodservice channels for premium fat sourcing. This pattern concentrates in German and French metropolitan markets where consumer-facing transparency requirements are strictest.
Bakery Fats Market Segmentation
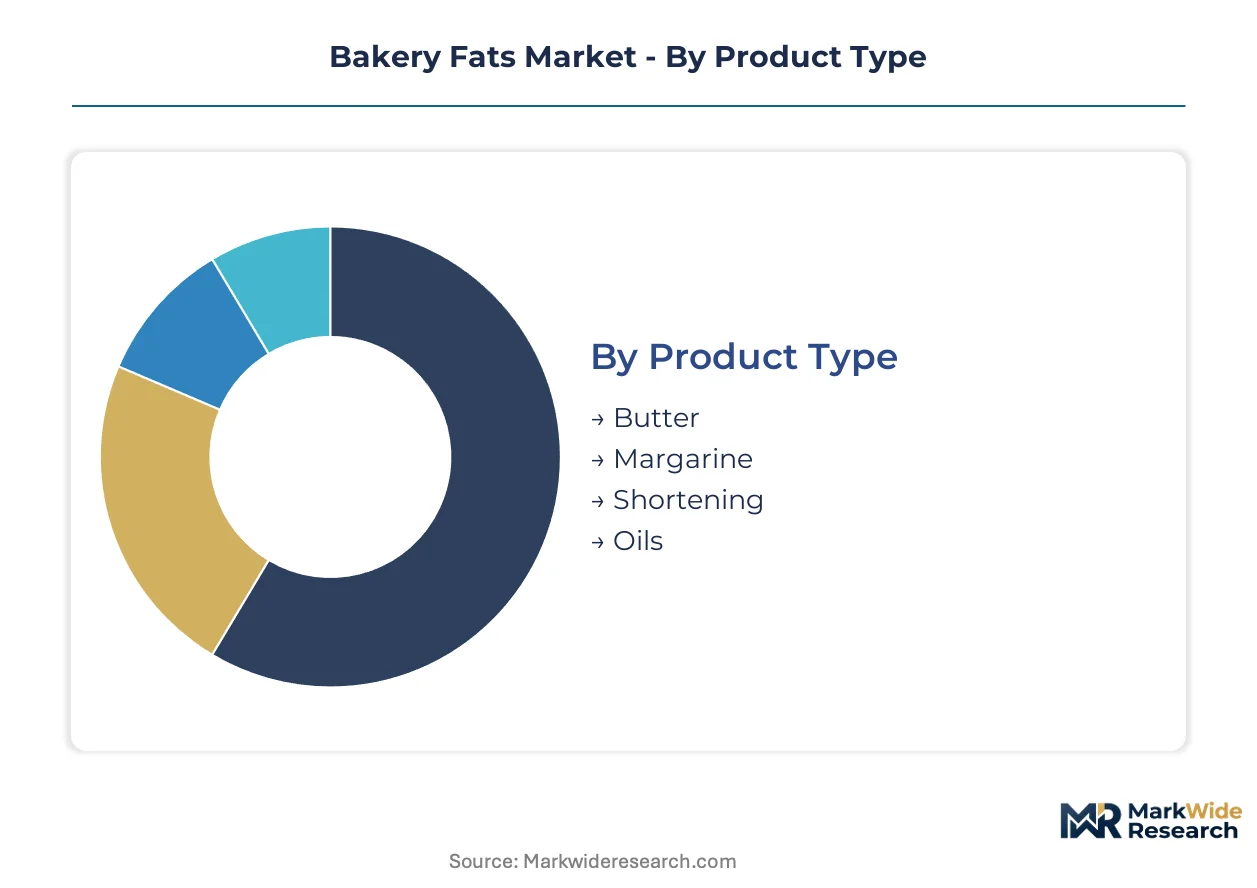
Bakery fat segmentation determines which regulatory pathways apply—EFSA novel food evaluations hit interesterified shortenings hardest, while butter faces simpler dairy-origin documentation. Formulators must map certification burdens to each segment's reformulation timeline and export destination.
Product Type:
EFSA novel food scrutiny falls heaviest on enzymatically modified shortenings and palm-based margarines, whereas butter bypasses additive approval pathways entirely.
- Shortening:Hydrogenated and interesterified triglyceride blends engineered for plasticity and polymorphic stability. Industrial bakeries in Malaysia and Indonesia concentrate demand for high-ratio cake shortenings with extended fry stability, though REACH compliance for emulsifier additives compresses reformulation windows for EU-bound exports.
- Butter:Churned dairy fat with 80-82% milkfat content, prized for clean-label positioning and flavor identity. Artisan bakeries in France and Germany drive premium procurement through certified sustainable channels, displacing traditional foodservice distributors.
- Margarine:Water-in-fat emulsions with 80% fat content, standardized for cost-sensitive industrial lines. Quick-service bakery chains in Southeast Asia specify extended shelf-life variants with tailored crystallization profiles.
- Oils:Liquid vegetable oils requiring fractionation or blending for bakery functionality. Tropical oil processors in Indonesia supply palm olein streams for bread improver applications.
Leading the category by volume: Shortening. Growing fastest: Butter.
Texture:
Texture specification dictates processing equipment compatibility and laminating performance, with hard fats commanding premium margins in laminated dough applications.
- Hard:High-melting-point fats with stable beta-prime crystal polymorphism for puff pastry lamination. European industrial bakeries retrofit lines to accommodate enzymatically interesterified alternatives with equivalent plasticity.
- Soft:Lower-solid-fat-index formulations for cake batters and creaming methods. Malaysian fractionation clusters supply palm mid-fractions optimized for aeration stability.
- Creamy:Intermediate plasticity for all-purpose shortening blends. Food manufacturers specify creamy textures for standardized performance across seasonal temperature variations.
- Spready:Tub-stable emulsions with post-crystallization workability. Home cook demand concentrates in German retail channels with strict palm sustainability labeling.
Hard textures capture the steepest expansion trajectory as laminated pastry demand accelerates. Soft textures anchor current volume.
Application:
Application-specific functionality requirements fragment procurement, with laminated pastry demanding polymorphic precision that chemically leavened categories tolerate less.
- Pastry:Laminated dough systems requiring precise solid fat content for layer integrity. French and German artisan bakeries specify certified sustainable palm shortenings with controlled crystallization kinetics.
- Bread:Fat-included and fat-free improvers for crumb softening and shelf-life extension. Indonesian quick-service chains standardize on palm-based bread fats with extended fry stability.
- Cake:High-ratio shortenings with emulsifier systems for aeration and moisture retention. REACH-registered polyglycerol ester alternatives are displacing legacy emulsifier grades in EU-bound formulations.
- Cookies:Creaming-method fats with controlled spread characteristics. Malaysian processors supply fractionated palm stearin for snap and texture control.
Pastry applications gain share fastest. Bread applications dominate current volume.
End User:
End-user procurement sophistication determines technical service intensity, with food manufacturers demanding formulation customization that home cook channels cannot justify.
- Food Manufacturers:High-volume industrial bakeries requiring standardized performance across multi-site operations. Southeast Asian quick-service chains consolidate procurement around Malaysian-sourced palm fractions with certified sustainability claims.
- Bakeries:Artisan and retail bakery operations prioritizing clean-label positioning and fat identity. French metropolitan markets enforce RSPO certification as a non-negotiable supplier qualification.
- Restaurants:Foodservice operations seeking portion-controlled formats with extended holding stability. France's AGEC anti-waste law incentivizes recyclable packaging for foodservice fat portions.
- Home Cooks:Retail consumers purchasing branded spreads and baking fats. German clean-label distributors displace traditional retail channels for premium positioning.
Food manufacturers lead by volume. Bakeries expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia and Indonesia generate the bulk of tropical oil feedstock, while European compounders and Southeast Asian quick-service chains absorb the processed output. This geographic split concentrates upstream fractionation in equatorial zones and downstream formulation in industrial bakery clusters.
Indonesia
Export levy fluctuations on crude palm oil expose margarine producers to input cost swings. The country's national bioeconomy strategy prioritizes downstream processing incentives. Jambi and North Sumatra host expanding fractionation facilities serving regional quick-service bakery chains.
Malaysia
RSPO certification backlogs create compliance bottlenecks for European-bound exports. REACH registration requirements for emulsifier additives compress reformulation timelines. Port Klang and Pasir Gudang processing clusters supply palm mid-fractions for laminated dough applications across Southeast Asia.
Germany
Artisan bakeries in metropolitan markets enforce certified sustainable palm as a non-negotiable supplier qualification. The F-Gas Regulation accelerates reformulation away from hydrogenated fats. Hamburg and Berlin distribution hubs displace traditional broadline channels for premium fat procurement.
France
Clean-label distributors consolidate procurement around fat identity claims in artisan segments. The AGEC anti-waste law incentivizes recyclable packaging for foodservice fat portions. Paris and Lyon bakery clusters drive premium butter adoption through certified sustainable channels.
United States
FDA labeling rules for trans fat disclosure shape product development priorities for interesterified alternatives. Industrial bakeries retrofit lines to accommodate enzymatically modified shortenings. Chicago and New Jersey processing centers standardize formulations for multi-site food manufacturing operations.
Bakery Fats Market Key Industry Players
The competitive structure tilts toward integrated tropical oil processors with captive fractionation assets. European compounders and Asian palm processors occupy distinct tiers, with mid-cap specialists occupying the interstices. Two archetypes dominate: upstream-integrated feedstock controllers and downstream formulation specialists. Capacity expansion in Southeast Asian fractionation and strategic partnerships for clean-label certification represent the primary competitive moves.
Among European-based compounders, CSM Ingredients and AAK International exemplify the formulation-specialist archetype with R&D networks anchored in regional bakery markets. Fuji Oil Co. Ltd and Wilmar International Ltd represent the upstream-integrated model, with corporate structures reflecting Asian tropical oil processing origins. These four occupy positions across the value chain spectrum from feedstock control to application-specific fat design.
| Leading Market Players |
|---|
| CSM Ingredients |
| Fuji Oil Co. Ltd |
| AAK International |
| Wilmar International Ltd |
| Goodman Fielder |
| Bunge |
| Dawn Food Products |
| Premium Vegetable Oils Sdn Bhd |
| Cargill Incorporated |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap compounders in Germany and France anchor premium butter pricing discipline through direct artisan bakery relationships, while sovereign-backed Malaysian processors enforce contract stability for palm fraction exports to quick-service chains. This ownership split concentrates pricing power upstream with feedstock controllers and downstream with clean-label formulators.
Pricing Analysis
Margin tightening in standard-grade margarine reflects crude palm oil futures volatility and Indonesian export levy fluctuations. Three-tier pricing structure across premium, standard, and economy levels separates certified sustainable palm claims from conventional fractions and commodity shortenings. Food manufacturers exhibit highest price sensitivity due to volume procurement and standardized performance requirements, while artisan bakeries absorb premiums for RSPO-certified butter with fat identity claims.
Supply Chain Analysis
Freight cost escalation on containerized tropical oil shipments from Port Klang and Pasir Gudang compresses margins for European compounders lacking captive fractionation. Supply concentrates in Malaysia, Indonesia, and the Netherlands, with raw material dependencies on crude palm oil, palm kernel oil, and lauric oil streams. Single-origin exposure to Indonesian export policy shifts creates structural vulnerability. Distribution runs through integrated processor-direct channels for industrial buyers and specialized clean-label distributors for artisan segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as formulation specialists acquire fractionation assets and palm processors build European compounding capacity. Captive supply of tropical oil feedstocks has become the decisive competitive lever.
For Market Incumbents: Extend certification coverage beyond RSPO to ISCC and national bioeconomy schemes, compressing qualification timelines for reformulated shortenings. Lock in long-term offtake agreements with Malaysian fractionation clusters before capacity expansion saturates regional supply. Defend against enzymatic interesterification specialists by embedding crystallography expertise within technical service teams.
For New Entrants and Emerging Players: Begin with precision fermentation lipid platforms targeting pastry applications where polymorphic stability gaps persist in enzymatically modified alternatives. Underpenetrated African markets in Nigeria and Kenya offer white-space entry through technical service partnerships with informal bakery clusters. Lead with custom triglyceride profiling capabilities rather than commodity positioning.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European compounders with stranded hydrogenation assets and retrofit-ready infrastructure for enzymatic interesterification. Long-term viability hinges on backward integration into tropical oil sourcing or forward integration into certified sustainable channels. Watch for inflection when REACH substance evaluation lists expand to capture additional emulsifier chemistries, triggering accelerated substitution spending.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Oil Sourcing | CSM Ingredients and AAK International secure captive palm mid-fraction supply against Malaysian export bottlenecks. |
| Enzymatic Interesterification Retrofit | European industrial bakeries retrofit lines to meet F-Gas Regulation timelines and clean-label procurement mandates. |
| Multi-Certification Compliance Investment | Simultaneous RSPO, ISCC, and bioeconomy alignment extends product qualification timelines by 12-18 months. |
| Precision Fermentation Lipid Development | Microbial oil production converges with enzymatic modification for custom pastry-grade triglyceride profiles. |
| African Market Technical Service Expansion | Branded shortening suppliers establish formulation support capabilities in Nigeria and Kenya informal bakery sectors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this bakery fats analysis. Primary interviews with fractionation plant managers, procurement leads at quick-service bakery chains, technical R&D directors at European compounders, and RSPO certification auditors combined with secondary validation from EFSA novel food registers, ECHA substance evaluation lists, and Malaysian Palm Oil Board production statistics. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Granularity-level modeling disaggregated volume and value across the projection horizon by product type, texture specification, application, and end-user procurement sophistication. CAGRs derived from regression analysis of historical feedstock price trajectories, regulatory phase-in schedules, and capacity expansion pipelines. Industry-specific forecast inputs included palm oil futures curve assumptions and enzymatic interesterification adoption rates in European industrial bakeries.
Underlying measurement precision varies by segment; artisan bakery butter volumes carry tighter precision than informal sector shortening estimates in African markets. Forecasts reflect assumptions about REACH implementation timelines and Indonesian export policy continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Vegan Baking Mix Market
Bakery Products
Flour Mixes Market
Bakery Products
Flatbread Market
Bakery Products
Europe Zwieback Market
Bakery Products
Low-Gluten Emmer and Einkorn Flour Blends Market
Bakery Products
Low Fat Oatmeal Cookies Market
Bakery Products
North America Sweet Biscuits Market
Bakery Products
Ice Cream Market
Bakery Products
GCC Frozen Bakery Products Market
Bakery Products
Yeastless Dough Market
Bakery Products
US Frozen Bakery Market
Bakery Products
Specialty Frozen Bakery Market
Bakery Products
Toasted Flour Market
Bakery Products
Low Fat Bran Muffins Market
Bakery Products
Bread Improver Market
Bakery Products
Pizza Crust Mix Market