
 Green Food Supplements Market | 2026-2036
Green Food Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Green Food Supplements Market Analytics
Aftermarket service revenue from subscription-based supplement replenishment programs is fragmenting across direct-to-consumer platforms and traditional retail networks. NOW Foods leverages its vertically integrated manufacturing infrastructure to control raw material quality from organic farms to finished powders. Gaia Herbs anchors its competitive position through certified organic herb cultivation and transparent supply chain documentation. Herbalife Nutrition Ltd. competes through personalized nutrition coaching bundled with product distribution.
Green food supplements comprise concentrated plant-derived formulations containing chlorophyll-rich algae, cereal grasses, and legume extracts standardized for phytonutrient density, typically processed through low-temperature dehydration to preserve enzyme activity and bioactive compounds. Powders dominate current volume due to formulation flexibility and cost efficiency in bulk manufacturing, while gummies represent the fastest-expanding format as palatability improvements attract reluctant adult consumers. Spirulina and chlorella ingredient segments command premium positioning based on established clinical research supporting detoxification and immune modulation claims.
The USDA Organic seal and EFSA health claim authorization frameworks govern product labeling and market access across North America and Europe, with compliance costs rising for novel ingredient introductions. China's SAMR and NMPA enforce stricter import registration for algae-based supplements, creating divergent approval pathways for multinational suppliers. Stakeholders must monitor evolving probiotic-algae combination regulations and adapt certification strategies accordingly.
Market Dynamics
Clean-label certification mandates from the USDA and EFSA are compressing formulation flexibility while fragmenting supply chains into certified and non-certified tiers. This regulatory divergence is forcing manufacturers to maintain parallel inventory systems and dual-sourcing strategies.
Growth Catalysts
- USDA Organic certification expansion:Retailers in the United States now require organic documentation for shelf placement, pulling mid-tier manufacturers toward certified sourcing. This creates volume guarantees for organic algae farms.
- Fitness sector demand concentration:CrossFit and functional fitness communities standardize greens supplementation protocols, creating predictable bulk purchasing cycles. Gym-affiliated distributors now carry dedicated green food SKUs.
- Low-temperature dehydration advances:New spray-drying technologies preserve heat-sensitive phytoenzymes, enabling clinical-grade potency claims. Equipment manufacturers report order backlogs from supplement processors.
Market Restraints
- Organic spirulina supply concentration:Over 60% of certified organic algae biomass originates from farms in California and Hawaii, creating geographic vulnerability to drought and climate disruption.
- EFSA novel food authorization timelines:New algae strains or extraction methods face 18-24 month safety assessment windows, freezing product pipeline development for European market entry.
- Plant protein substitution threat:Pea and rice protein isolates capture similar wellness-oriented consumers at lower price points, pressuring greens powders on value-per-serving metrics.
Strategic Opportunities
- Germany's pharmacy channel expansion:Apotheken chains increasingly stock preventive wellness supplements, creating a high-trust distribution channel unavailable to unverified brands. Regulatory alignment with BfArM guidelines opens this pathway.
- Probiotic-algae combination formats:Synbiotic formulations combining spore-forming probiotics with chlorella extracts address gut health and detoxification simultaneously. This convergence commands premium positioning.
- China's cross-border e-commerce channels:Tmall Global and JD Worldwide reduce SAMR registration burdens for direct-to-consumer import models. Australian and New Zealand brands exploit this pathway ahead of full NMPA approval.
Industry Challenges
- Phytochemical standardization expertise:Laboratories capable of validating chlorophyll and carotenoid content across batch variations remain scarce. Manufacturers face certification backlogs from third-party testing facilities.
- Legacy ERP integration with traceability systems:Blockchain-enabled supply chain documentation requires middleware development to connect with existing inventory management platforms. Implementation costs strain mid-sized processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Food Supplements Market |
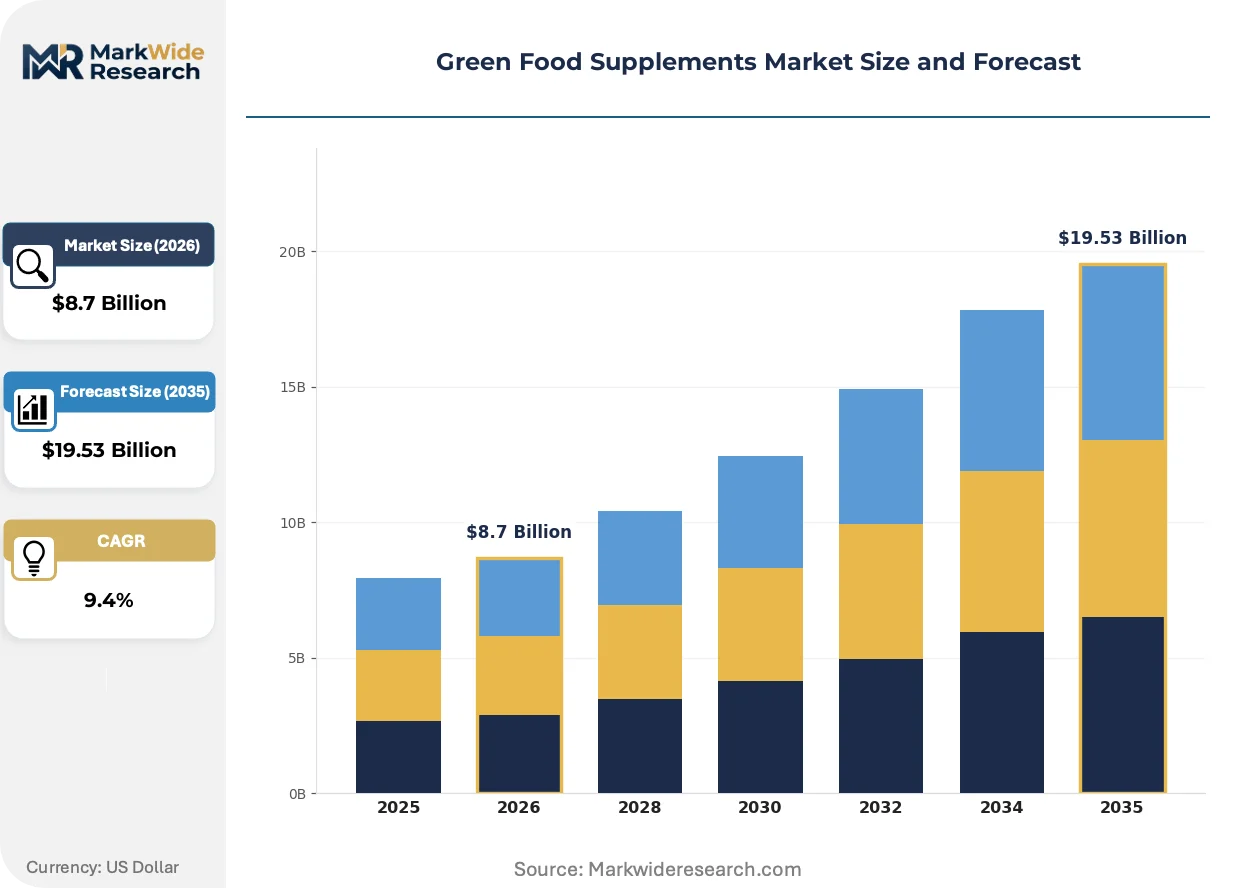
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powders, Capsules, Gummies, Liquids Ingredient Type: Spirulina, Chlorella, Wheatgrass, Alfalfa End User: Fitness Enthusiasts, Health-Conscious Consumers, Vegans, Athletes Distribution Channel: Online Retail, Health Food Stores, Pharmacies, Supermarkets |
| Companies Covered | GNC Holdings Inc., Herbalife Nutrition Ltd., Amway Corporation, NOW Foods, Garden of Life, Amazing Grass, Nature's Bounty, Gaia Herbs, Vega, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Food Supplements Market Evolving Landscape
Formulation science is converging with digital health infrastructure, creating measurable outcome linkages between supplement intake and biometric feedback. This integration is compressing the traditional efficacy demonstration cycle.
Encapsulation technology using liposomal delivery systems is virtualizing the bioavailability advantage previously held by liquid extracts. Sports nutrition brands in Germany and Australia are adopting these formats for pre-workout stacks. The technology is virtualizing the premium positioning of cold-pressed juices by delivering equivalent nutrient density in shelf-stable powders.
EFSA's evolving position on algae-derived novel food ingredients is tightening contaminant thresholds for heavy metals and microcystins. Finished product manufacturers must now demonstrate batch-level testing rather than relying on supplier certificates. Chinese exporters to Europe are investing in in-house ICP-MS equipment to maintain market access.
Subscription-based replenishment models are displacing traditional retail purchasing for core users. Direct-to-consumer platforms capture recurring revenue while traditional supplement stores pivot toward sampling and education. This behavioral shift concentrates most visibly in United States urban markets where delivery logistics infrastructure supports same-day fulfillment expectations.
Green Food Supplements Market Segmentation
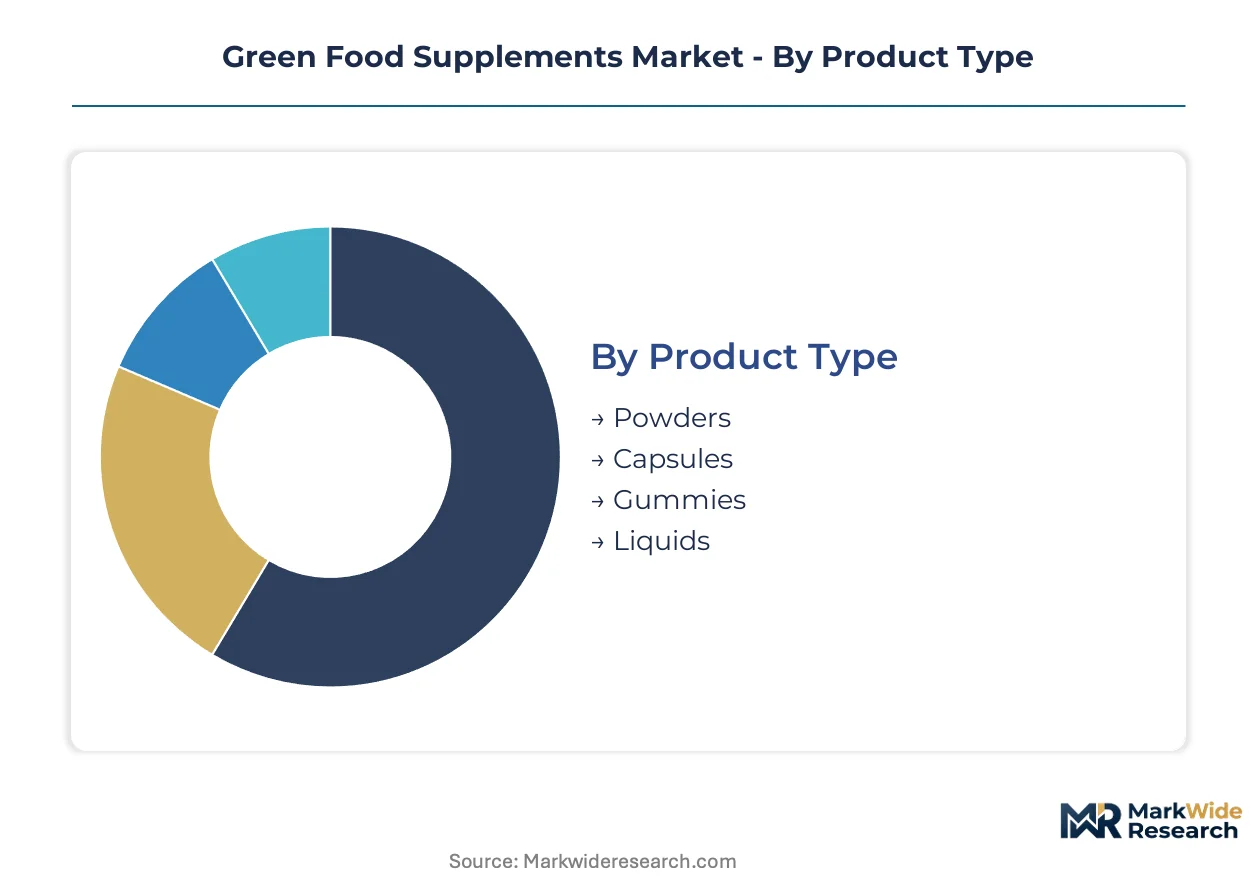
Green food supplement manufacturers structure their portfolios around four intersecting dimensions that determine formulation investment, channel economics, and customer lifetime value. Each segmentation axis carries distinct margin profiles and replenishment cadences that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across formats, with subscription replenishment programs driving higher touch requirements for powder users versus impulse-driven gummy purchases.
- Powders:Bulk formulations deliver cost efficiency at scale and enable precise dosing customization. CrossFit affiliates and functional fitness gyms in the United States standardize greens powder protocols, creating predictable institutional purchasing cycles with quarterly replenishment schedules.
- Gummies:Palatability engineering has narrowed the efficacy gap with traditional formats. Adult consumers reluctant to tolerate grassy flavors in Germany's pharmacy channel are migrating to this format fastest, though per-serving cost premiums limit penetration in price-sensitive segments.
- Capsules:Portable unit-dose convenience serves traveling professionals and precise regimen adherents.
- Liquids:Cold-pressed and liposomal delivery variants command shelf space in premium health food retail.
By volume, powders lead. By growth pace, gummies are ahead.
Ingredient Type:
Raw material sourcing costs stratify sharply based on organic certification requirements and cultivation infrastructure intensity.
- Spirulina:Arthrospira platensis biomass concentrates phycocyanin and gamma-linolenic acid at clinical-grade potencies. California and Hawaii farms supply over sixty percent of certified organic feedstock, exposing finished goods manufacturers to drought-driven supply interruptions.
- Chlorella:Broken-cell-wall processing releases intracellular nutrients for bioavailable detoxification support. EFSA's tightening heavy metal thresholds are forcing European-market suppliers to install in-house ICP-MS testing equipment, raising compliance barriers for Chinese exporters.
- Wheatgrass:Triticum aestivum juvenile grass delivers concentrated chlorophyll at lower cultivation cost than algae alternatives.
- Alfalfa:Medicago sativa leaf extracts provide phytoestrogen and vitamin K density for targeted wellness applications.
Spirulina commands the highest price tier. Chlorella shows the steepest regulatory-driven quality investment curve.
End User:
Customer acquisition economics diverge based on education requirements and community-based validation patterns.
- Fitness Enthusiasts:CrossFit and functional training communities normalize greens supplementation as recovery protocol. Gym-affiliated distributors in the United States now carry dedicated SKUs with bulk pricing tiers tied to affiliate membership verification.
- Health-Conscious Consumers:Preventive wellness orientation drives subscription loyalty and willingness to pay organic premiums. Germany's Apotheken channel captures this segment through pharmacist consultation, creating trust barriers for unverified direct-to-consumer brands.
- Vegans:Micronutrient gap concerns—particularly B12, iron, and omega-3—motivate targeted formulation purchases.
- Athletes:Drug-tested certification requirements from NSF and Informed Sport constrain ingredient selection and supplier qualification.
Fitness enthusiasts generate the highest repurchase frequency. Health-conscious consumers deliver the strongest subscription retention.
Distribution Channel:
Channel selection determines margin capture, data access, and regulatory exposure simultaneously.
- Online Retail:Direct-to-consumer platforms capture recurring revenue through subscription models while generating biometric feedback data for personalization. Tmall Global and JD Worldwide reduce China's SAMR registration burdens for Australian and New Zealand brands seeking market entry ahead of full NMPA approval.
- Health Food Stores:Staff expertise and sampling infrastructure support premium positioning and new product trial. Same-day delivery expectations in United States urban markets are compressing the advantage of physical proximity.
- Pharmacies:Regulatory alignment with BfArM guidelines opens Germany's Apotheken channel, unavailable to brands lacking pharmaceutical-grade documentation.
- Supermarkets:Mass-market placement requires price compression and simplified messaging for unassisted purchase decisions.
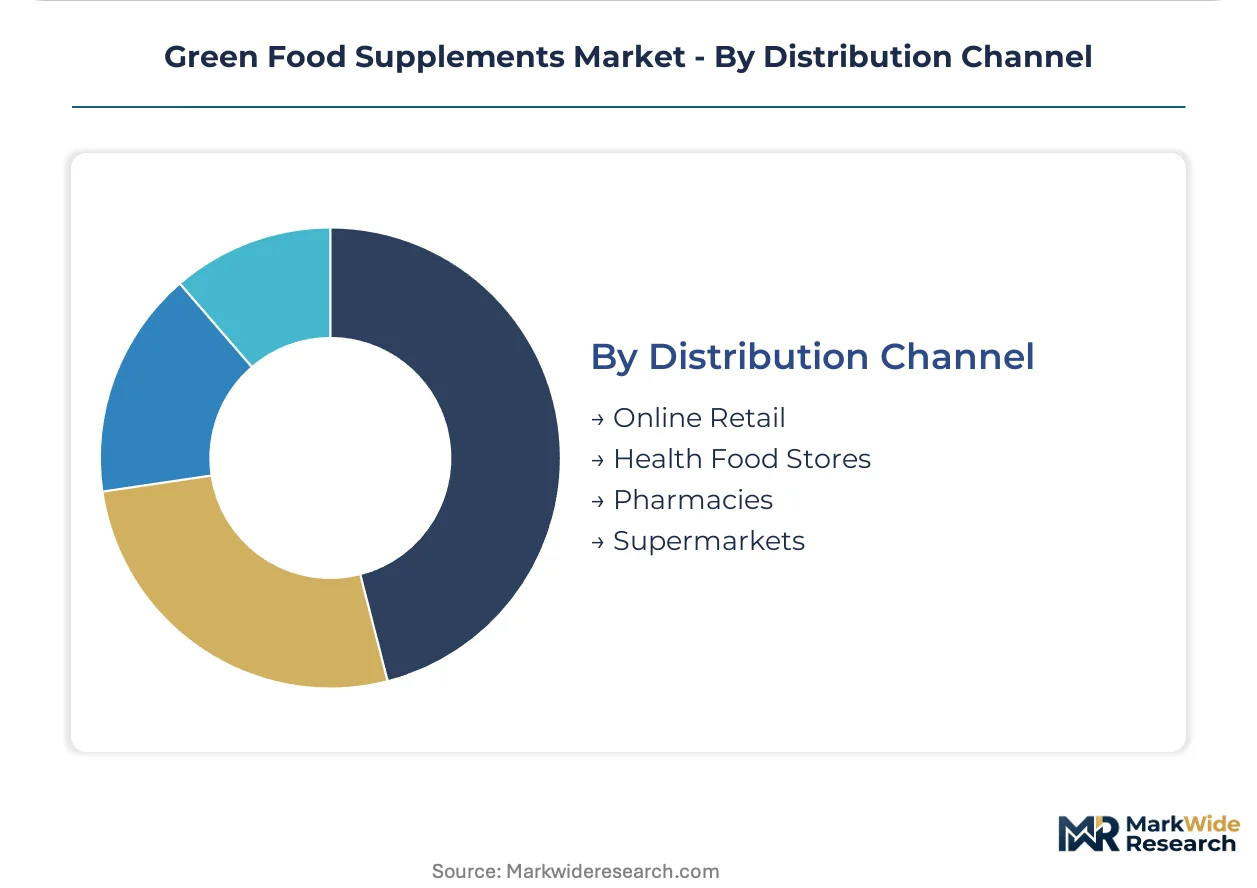
Online retail leads volume contribution. Pharmacies show the fastest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across major markets. United States consumers absorb organic premiums through subscription models, while Chinese buyers remain highly sensitive to per-serving costs despite rising health consciousness.
United States
Fitness communities and CrossFit affiliates normalize greens supplementation as recovery protocol. USDA Organic certification now functions as a de facto shelf-placement requirement at major retailers. California and Hawaii host over sixty percent of certified organic algae cultivation, exposing supply chains to drought-driven interruptions.
Germany
Preventive wellness orientation drives pharmacy channel expansion through Apotheken chains. BfArM guidelines govern pharmaceutical-grade documentation requirements for shelf placement. Munich and Hamburg clusters concentrate distribution infrastructure serving Central European markets.
China
Cross-border e-commerce through Tmall Global and JD Worldwide reduces SAMR registration burdens for direct import models. NMPA maintains stricter approval pathways for algae-based supplements than conventional botanicals. Shanghai and Shenzhen function as primary entry hubs for Australian and New Zealand brands.
Australia
Domestic brands exploit regulatory arbitrage through China's cross-border channels ahead of full NMPA approval. TGA certification provides quality signaling for export markets. Sydney and Melbourne host formulation R&D clusters serving Asia-Pacific demand.
United Kingdom
Health food retail consolidation drives premium positioning for certified organic formats. EFSA health claim frameworks constrain marketing language for detoxification and immune modulation claims. London concentrates direct-to-consumer platform headquarters and influencer marketing infrastructure.
Green Food Supplements Market Competitive Landscape
Capability concentration sits with vertically integrated manufacturers controlling organic cultivation through finished goods; scale advantage sits with direct-selling networks leveraging personalized coaching infrastructure. The market structures around three tiers: organic cultivation specialists, multi-level distribution platforms, and mass-market private label suppliers. Dominant competitive moves include backward integration into certified algae farming and subscription-based customer lock-in through replenishment algorithms.
Within the cultivation-integrated tier, NOW Foods and Gaia Herbs exemplify quality-control archetypes through captive supply chains. Herbalife Nutrition Ltd. occupies a distinct position bundling personalized coaching with product distribution. Among these, the California-based limited liability companies represent regulatory compliance excellence, while the Cayman Islands-incorporated nutrition platform demonstrates channel diversification strategy.
| Leading Market Players |
|---|
| GNC Holdings Inc. |
| Herbalife Nutrition Ltd. |
| Amway Corporation |
| NOW Foods |
| Garden of Life |
| Amazing Grass |
| Nature's Bounty |
| Gaia Herbs |
| Vega |
| Others |
Value Network & Pricing Analysis
Overcapacity in California's certified organic algae farms is compressing spot pricing for spirulina biomass while simultaneously pressuring mid-tier processors to absorb certification costs rather than pass them downstream. This utilization imbalance rewards vertically integrated manufacturers with captive supply and squeezes contract-dependent brands facing dual-sourcing mandates from USDA and EFSA compliance requirements.
Pricing Analysis
Subscription replenishment revenue drives lifetime value for direct-to-consumer platforms, with pricing stratifying across premium organic tiers, standard certified formats, and economy private-label SKUs. Price differentiation rests on USDA Organic seal possession and cold-chain logistics investment, with cost compression in the economy tier intensifying because of pea protein substitution. Fitness enthusiasts show lowest price sensitivity; mass-market supermarket buyers absorb highest relative cost pressure.
Supply Chain Analysis
Contract manufacturing concentration sits with NOW Foods' vertically integrated facilities and Garden of Life's dedicated organic processing lines. Geographic supply concentration centers on California, Hawaii, and China's Jiangsu province for algae biomass, with raw material dependencies on certified organic fertilizer inputs, glass packaging from Mexico, and liposomal encapsulation equipment from Germany. Single-source vulnerability from California drought exposure threatens feedstock security. Distribution runs through pharmacy chains in Germany, CrossFit affiliates in the United States, and Tmall Global for Chinese cross-border access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green food supplements function as a service-attach business where subscription algorithms and personalized coaching layers expand faster than product manufacturing margins. Recurring revenue from replenishment programs now exceeds hardware economics for established platforms.
For Market Incumbents: Build certification moats through captive organic algae cultivation and in-house ICP-MS testing infrastructure. Secure shelf placement at Apotheken chains by aligning with BfArM documentation requirements. Defend against plant protein substitution by emphasizing phytoenzyme preservation claims validated through low-temperature processing investments.
For New Entrants and Emerging Players: Germany's pharmacy channel shows geographic underpenetration by direct-to-consumer brands lacking pharmaceutical-grade documentation. Target white-space opportunities in synbiotic formulations combining spore-forming probiotics with chlorella extracts. Exploit Australia's TGA certification as quality signaling for Chinese cross-border entry ahead of full NMPA approval.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liposomal delivery manufacturing and blockchain-enabled traceability systems. Long-term viability favors cultivation-integrated specialists with California land positions and established organic certification. Monitor EFSA novel food authorization timelines as inflection signal for European market pipeline velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Algae Farming | Captive supply from California and Hawaii farms insulates against drought-driven price volatility and secures USDA Organic volume guarantees. |
| Subscription Algorithm Development | Replenishment algorithms at direct-to-consumer platforms lock in fitness enthusiast segments with predictable quarterly purchasing cycles. |
| Synbiotic Formulation Launch | Probiotic-algae combinations command premium positioning in Germany's Apotheken channel while addressing gut health and detoxification simultaneously. |
| Blockchain Traceability Implementation | Batch-level documentation satisfies EFSA's evolving heavy metal testing requirements and opens pharmacy distribution pathways. |
| Cross-Border E-Commerce Expansion | Tmall Global and JD Worldwide reduce SAMR registration burdens for Australian brands seeking Chinese market entry ahead of NMPA approval. |
Research Methodology
The analysis maps powders, gummies, capsules, and liquid formats, each validated through procurement managers at health food retailers, regulatory affairs leads at supplement manufacturers, organic certification auditors, and gym-affiliate distributors. Primary interviews with these stakeholders combined with secondary validation from USDA organic certification databases, EFSA novel food submission records, SAMR import registration filings, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation cross-checked segment estimates.
Assumptions held fixed include EFSA authorization timelines, USDA organic certification cost structures, and CrossFit affiliate network density; variables tested included drought frequency in California cultivation zones and Chinese cross-border e-commerce policy shifts. The projection horizon spans product type, ingredient category, end-user archetype, and distribution channel dimensions, with CAGRs derived from regression against historical fitness sector supplement penetration curves and organic food price elasticity coefficients.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-selling networks or pharmaceutical entrants would shift outcomes beyond modeled ranges. Quarterly review of EFSA submission backlogs, California reservoir levels, and Tmall Global policy adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Older Adults Health Supplements Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
North America Insoluble Dietary Fibers Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
North America Protein Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Global Corn Germs Supplements Market
Nutritional Supplements
Stress Relief Supplements Market
Nutritional Supplements
Green Tea Supplements Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Algae Omega 3 Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Policosanol Market