
 Omega-3 Products Market | 2026-2036
Omega-3 Products Market Size, Share, and Industry Trends Forecast 2026-2036
Omega-3 Products Market Outlook
Peru's marine ingredient processing corridor is fragmenting as new extraction facilities compete for anchovy quota access. DSM leverages backward integration into Antarctic krill supply through its Aker BioMarine partnership to secure phospholipid-bound EPA and DHA streams. Nordic Naturals differentiates through pharmaceutical-grade distillation protocols that exceed GOED voluntary limits for oxidation markers. Corbion anchors algal fermentation capacity in Brazil, competing with fish-derived omega-3 on vegetarian positioning and supply stability.
Omega-3 products comprise concentrated eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA) lipids extracted via molecular distillation, winterization, or enzymatic transesterification, formulated for triglyceride reduction, neural membrane support, and inflammatory modulation. Softgel formats dominate volume due to oxidation protection and consumer familiarity, while algal oil sources represent the fastest-growing input category as pharmaceutical and pet nutrition buyers seek marine-independent DHA. Dietary supplements absorb the majority of value, though pharmaceutical applications command premium pricing through prescription Lovaza equivalents and FDA-approved hypertriglyceridemia therapies.
GOED sets voluntary limits on peroxide and anisidine values that most retailers now enforce as de facto entry requirements, while EFSA health claim authorizations determine permissible cardiovascular marketing language across European markets. The FDA's qualified health claims for coronary heart disease and EPA-specific prescription approvals create a dual-track regulatory environment where supplement and drug pathways diverge sharply. Stakeholders must monitor algal oil yield improvements and Antarctic krill fishery certification disputes to assess long-term input cost trajectories and ESG compliance positioning.
Market Dynamics
Pharmaceutical-grade distillation protocols are splitting the competitive landscape into prescription-track and supplement-track supply chains, with EFSA health claim authorizations now determining which European entrants can access cardiovascular marketing channels.
Growth Catalysts
- Prescription API Sourcing:Pharmaceutical manufacturers are expanding omega-3 active pharmaceutical ingredient procurement for Lovaza-equivalent hypertriglyceridemia therapies, creating dual-revenue streams beyond dietary supplements.
- EFSA Health Claim Pathways:The European Food Safety Authority's cardiovascular benefit authorizations enable compliant entrants to command premium positioning in European retail and clinical channels.
- Antarctic Krill Phospholipid Streams:Norway's harvesting corridor is securing phospholipid-bound EPA and DHA inputs that bypass traditional fish oil oxidation vulnerabilities for high-stability formulations.
Market Restraints
- Anchovy Quota Fragmentation:Peru's marine ingredient processing corridor faces supply concentration risk as new extraction facilities compete for finite anchovy reduction quotas, compressing margin structures for ethyl ester producers.
- GOED Voluntary Enforcement:The Global Organization for EPA and DHA Omega-3s' peroxide and anisidine limits, now enforced as de facto entry requirements by major retailers, erect compliance barriers for smaller processors lacking analytical infrastructure.
- Algal Oil Yield Ceilings:Fermentation-based DHA production remains constrained by lipid extraction efficiency limits, preventing cost parity with marine-derived alternatives despite supply stability advantages.
Strategic Opportunities
- Pet Nutrition Formulation:Veterinary channel DHA supplementation for cognitive development in companion animals represents an underpenetrated application with premium pricing tolerance and lower regulatory friction than human pharmaceuticals.
- Brazilian Algal Fermentation Scale:Tropical fermentation infrastructure can displace temperature-dependent marine harvesting cycles, offering pharmaceutical buyers supply continuity independent of Antarctic fishery certification disputes.
- FDA Qualified Health Claim Expansion:The agency's coronary heart disease qualified claims framework creates regulatory runway for supplement manufacturers to access cardiovascular positioning without full drug approval timelines.
Industry Challenges
- Pharmaceutical-Grade Distillation Talent:Molecular distillation and winterization expertise for oxidation marker suppression resides with a narrow specialist workforce, constraining capacity expansion for prescription-track entrants.
- Dual-Track Compliance Architecture:Manufacturers serving both supplement and pharmaceutical segments must maintain parallel quality systems for FDA dietary supplement GMPs and drug cGMPs, doubling validation overhead.
- Antarctic Krill ESG Certification Lag:Marine Stewardship Council and Friend of the Sea disputes over Antarctic krill harvesting create procurement uncertainty for brands dependent on sustainability credentials for European and North American positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omega-3 Products Market |
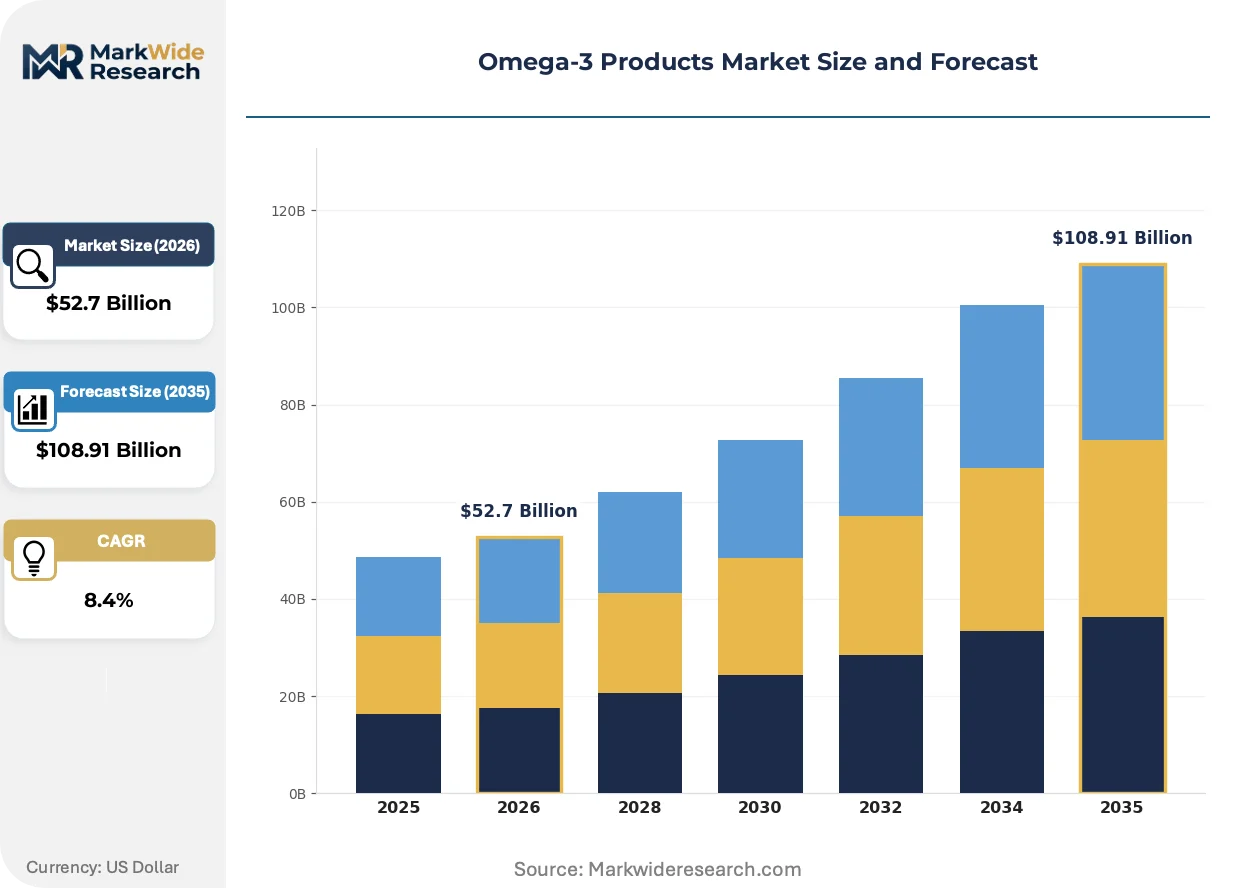
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $108.91 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Liquid, Capsules, Gummies End User: Personal Care, Pharmaceutical, Dietary Supplements, Pet Nutrition Source: Fish Oil, Algal Oil, Krill Oil, Flaxseed Oil Application: Heart Health, Cognitive Function, Joint Health, Immune Support |
| Companies Covered | DSM, BASF, Aker BioMarine, Nordic Naturals, Pharma Marine, Corbion, GC Rieber Oils, Omega Protein Corporation, Epax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omega-3 Products Market Strategic Shifts
Enzymatic transesterification and algal fermentation are compressing the traditional dominance of molecular distillation, while regulatory divergence between prescription and supplement pathways forces manufacturers into parallel compliance investments.
Enzymatic transesterification enables selective EPA-DHA ratio tailoring for condition-specific formulations without thermal degradation. Pharmaceutical contract manufacturers are adopting this biocatalytic approach for pediatric and geriatric delivery systems requiring precise lipid profiles. The technology is migrating from niche custom synthesis toward mainstream capacity as equipment costs decline and enzyme immobilization protocols stabilize.
REACH registration requirements for novel omega-3 concentrates are tightening substance identity documentation across European import channels. ECHA's enforcement of analytical characterization standards for ethyl ester versus triglyceride forms is forcing reformulation investments from Asian exporters. Supplement brands targeting European pharmacy distribution are consolidating supply relationships with REACH-registered processors to preempt customs detention risks.
Veterinary channel buyers are consolidating omega-3 procurement around certified-sustainable krill and algal sources, displacing commodity fish oil in premium pet nutrition. Distributors serving specialty pet retail are demanding batch-level oxidation testing and species-of-origin documentation that mirrors pharmaceutical standards. This specification escalation is most visible in North American and Western European markets where pet humanization trends command ingredient cost premiums exceeding human supplement categories.
Omega-3 Products Market Segmentation
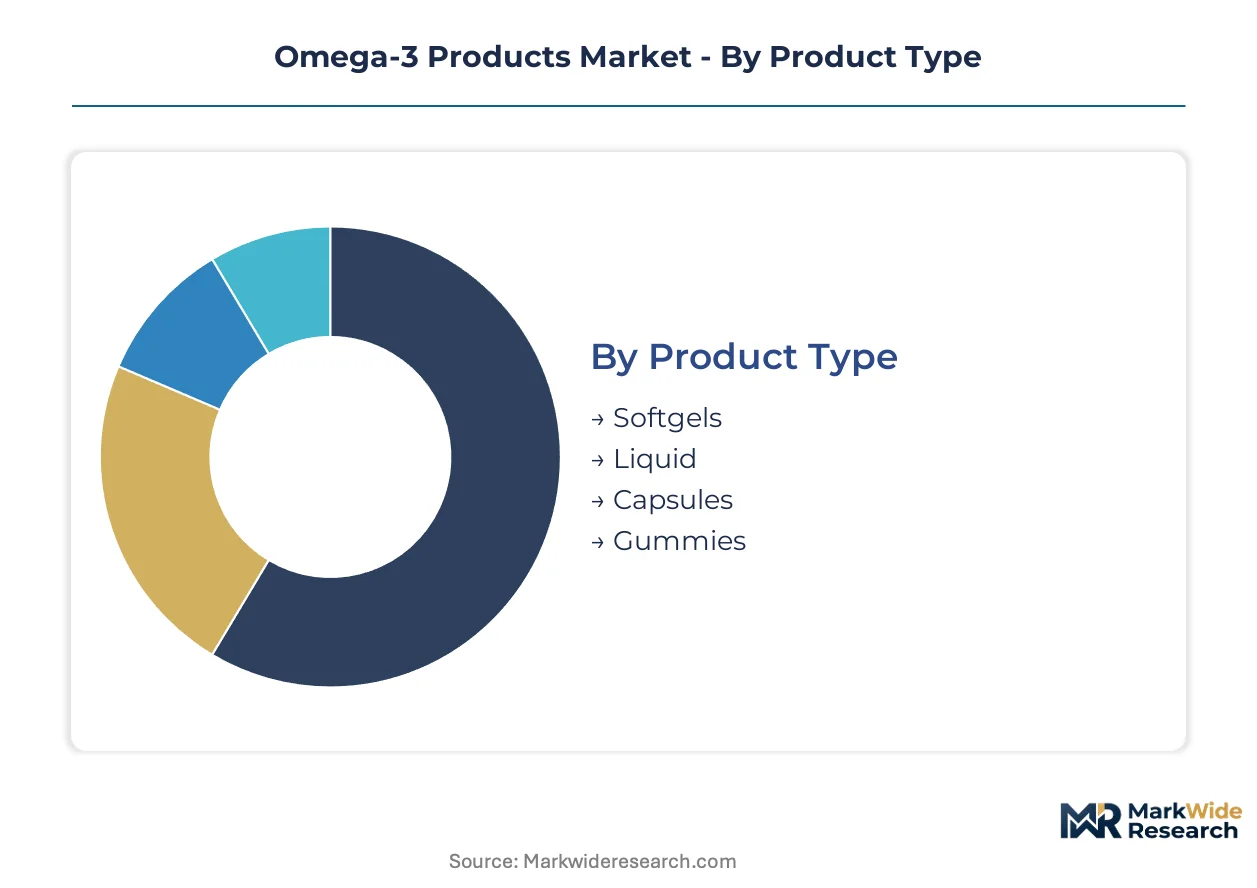
Omega-3 product segmentation reveals divergent margin structures across delivery formats and regulatory pathways. Format choice determines oxidation stability requirements, while end-use selection dictates whether manufacturers pursue pharmaceutical cGMP or dietary supplement GMP compliance.
Product Type:
Cost tier stratification separates premium oxidation-protected formats from economy bulk liquids.
- Softgels:Gelatin or plant-based shells encapsulate oil to prevent peroxide formation, commanding premium shelf positioning in pharmacy and clinical channels. Demand concentrates in North American retail where GOED-compliant oxidation limits are enforced as entry requirements.
- Liquid:Bulk oil presentations in amber glass or PET containers serve institutional buyers and high-volume consumers, with flavor masking systems determining palatability-driven repeat purchase rates.
- Capsules:Hard-shell two-piece formats accommodate powder or beadlet omega-3 delivery, finding traction in combination formulations with multivitamins or condition-specific stacks.
- Gummies:Pectin or gelatin-based chewable matrices mask fish taste through flavor systems, expanding fastest in pediatric and senior compliance-driven segments where swallowing difficulty limits traditional softgel adoption.
Softgels hold installed capacity. Gummies are rotating up the share rankings.
End User:
Application context determines whether EPA-DHA positioning emphasizes clinical endpoints or general wellness claims.
- Pharmaceutical:Prescription-grade ethyl ester concentrates for hypertriglyceridemia therapy require FDA drug approval and cGMP manufacturing, with Lovaza-equivalent formulations capturing premium pricing through managed care reimbursement.
- Dietary Supplements:Triglyceride and ethyl ester formats dominate mass-market and specialty retail, with EFSA health claim authorization determining permissible cardiovascular marketing language in European pharmacy distribution.
- Pet Nutrition:Veterinary channel DHA supplementation for canine cognitive development commands ingredient premiums exceeding human supplement categories, with batch-level oxidation documentation now standard in North American specialty retail.
- Personal Care:Topical omega-3 incorporation into dermatological formulations leverages anti-inflammatory positioning, though epidermal penetration limitations constrain efficacy claims compared to oral delivery routes.
Dietary Supplements maintains volume leadership. Pet Nutrition is climbing the fastest among application contexts.
Source:
Supply geography and extraction technology create distinct purity and sustainability credential profiles.
- Fish Oil:Anchovy, sardine, and mackerel reduction fisheries in Peru and Morocco supply triglyceride and ethyl ester concentrates, with seasonal El Niño fluctuations introducing volume uncertainty for processors.
- Algal Oil:Fermentation-based DHA production in Brazilian and North American facilities offers marine-independent supply continuity, though lipid extraction efficiency constraints prevent full cost parity with fish-derived alternatives.
- Krill Oil:Antarctic harvesting corridors deliver phospholipid-bound EPA and DHA with superior oxidative stability, though Marine Stewardship Council certification disputes create procurement uncertainty for sustainability-positioned brands.
- Flaxseed Oil:Alpha-linolenic acid precursor sourced from Canadian and Ukrainian agriculture provides vegetarian positioning, yet conversion inefficiency to EPA and DHA limits clinical efficacy equivalence.
Fish Oil holds installed capacity. Algal Oil is gaining share fastest among input categories.
Application:
Condition-specific formulation development targets measurable biomarker endpoints versus general wellness positioning.
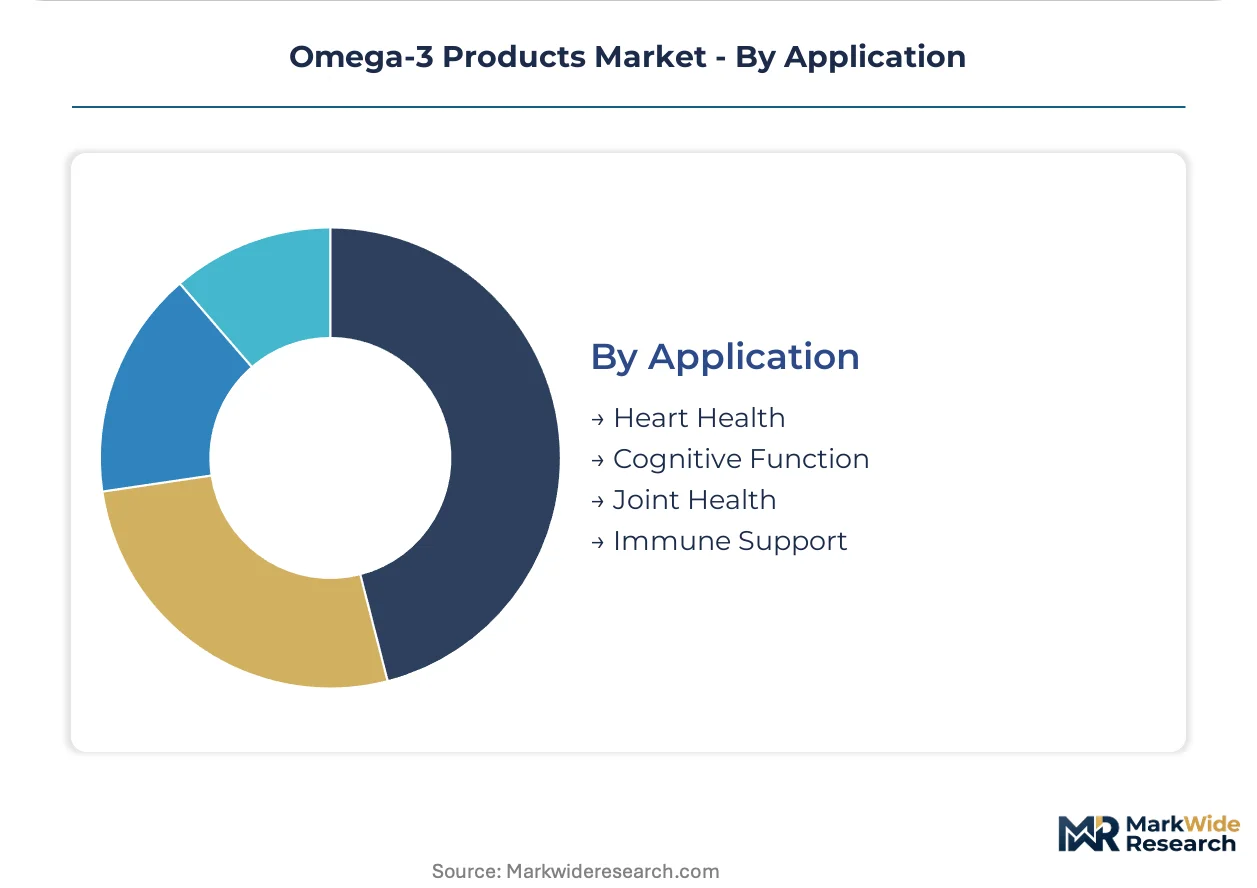
- Heart Health:Triglyceride reduction claims supported by FDA qualified health claims and EFSA Article 13.5 authorizations, with prescription and supplement pathways diverging sharply on evidentiary requirements.
- Cognitive Function:DHA neural membrane support targets prenatal, pediatric, and geriatric segments, with algal oil sourcing preferred for mercury-free positioning in pregnancy-focused formulations.
- Joint Health:Anti-inflammatory EPA positioning competes with glucosamine-chondroitin combinations in osteoarthritis symptom management, with clinical trial investment determining practitioner recommendation rates.
- Immune Support:Resolution mediator specialization represents emerging science with limited regulatory authorization, constraining marketing language to structure-function claims in most jurisdictions.
Heart Health holds installed capacity. Cognitive Function is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peru's anchovy reduction fisheries and Norway's Antarctic krill harvesting corridor anchor marine-derived supply, while Brazil's algal fermentation infrastructure offers land-based alternatives. Regulatory divergence between FDA prescription pathways and EFSA health claim frameworks fragments demand geography.
United States
FDA-qualified health claims for coronary heart disease drive supplement channel cardiovascular positioning, while prescription Lovaza-equivalent therapies command managed care reimbursement. The agency's drug cGMP requirements split manufacturing compliance between pharmaceutical and dietary supplement tracks. Greater Boston anchors pharmaceutical-grade distillation expertise for hypertriglyceridemia API production.
Norway
Antarctic krill phospholipid extraction through the Aker BioMarine partnership secures high-stability EPA-DHA streams for premium formulations. The country's Novel Food compliance infrastructure supports EFSA-aligned export positioning across European pharmacy channels. Bergen and Tromsø concentrate marine biotechnology R&D for next-generation lipid delivery systems.
Germany
REACH registration requirements for ethyl ester concentrates tighten substance identity documentation for omega-3 importers. ECHA enforcement of analytical characterization standards forces reformulation investments from Asian suppliers. Hamburg's port infrastructure handles bulk fish oil consolidation for Central European processing redistribution.
Brazil
Tropical algal fermentation capacity in São Paulo state displaces temperature-dependent marine harvesting cycles for pharmaceutical buyers seeking supply continuity. The country's national pharmaceutical regulator, ANVISA, governs import licensing for prescription-grade concentrates. Campinas anchors Corbion's DHA production infrastructure for vegetarian-positioned formulations.
China
Domestic omega-3 consumption concentrates in prenatal DHA supplementation for cognitive development claims. NMPA oversight of imported health food registrations creates compliance barriers for non-domestic brands. Qingdao's marine ingredient processing cluster competes for Peruvian anchovy oil supply contracts amid quota fragmentation.
Omega-3 Products Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in extraction and concentration. The competitive field stratifies across three tiers: multinational nutrition conglomerates with backward integration into marine supply, mid-cap pharmaceutical-grade distillers serving prescription channels, and regional processors competing on commodity bulk oils. Strategic moves concentrate on Antarctic fishery certification partnerships and algal fermentation capacity expansion to bypass marine supply volatility.
Within the pharmaceutical-grade distiller tier, Nordic Naturals and Epax exemplify oxidation-marker suppression expertise that exceeds GOED voluntary limits for premium positioning. DSM anchors the integrated nutrition platform archetype through its Aker BioMarine krill supply partnership, securing phospholipid-bound streams. Corbion occupies a distinct position as the algal fermentation scale leader, competing on marine-independent vegetarian sourcing. These three represent divergent supply archetypes—marine phospholipid, fish-derived distillation, and fermentation-based—each commanding different ESG credential profiles and regulatory pathway access.
| Leading Market Players |
|---|
| DSM |
| BASF |
| Aker BioMarine |
| Nordic Naturals |
| Pharma Marine |
| Corbion |
| GC Rieber Oils |
| Omega Protein Corporation |
| Epax |
| Others |
Value Chain & Pricing Dynamics
Peru's Pisco-Paracas marine ingredient processing corridor anchors global fish oil concentrate supply, with anchovy quota fragmentation between competing extraction facilities compressing margin structures and eroding pricing power for ethyl ester producers downstream.
Pricing Analysis
GOED voluntary limits on peroxide and anisidine values dictate the pricing tier structure across pharmaceutical and supplement channels. Three-tier pricing separates prescription-grade concentrates from pharmacy-positioned softgels and commodity bulk liquids, with FDA drug cGMP certification commanding substantial premiums over dietary supplement GMP compliance. Pricing pressure stems from algal oil yield improvements narrowing the cost gap with marine-derived alternatives. Mass-market retailers exhibit highest price sensitivity, while pharmaceutical buyers prioritize oxidation marker suppression over unit economics.
Supply Chain Analysis
El Niño-driven quota volatility between Peru and Morocco dominates supply chain risk for triglyceride and ethyl ester producers. Antarctic krill harvesting corridors in Norway, Peruvian anchovy reduction fisheries, and Brazilian algal fermentation facilities constitute the tripartite sourcing base. Raw material dependencies center on marine biomass availability, phospholipid extraction efficiency, and fermentation lipid yields. Single-source vulnerability concentrates in Antarctic krill MSC certification disputes. Distribution runs through pharmaceutical contract manufacturers, specialty retail pharmacy channels, and veterinary wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Molecular distillation expertise for oxidation marker suppression resides with a narrow specialist workforce, constraining capacity expansion and creating acquisition premiums for prescription-track manufacturing capabilities.
For Market Incumbents: Harden pharmaceutical-grade distillation protocols against emerging algal oil competitors by exceeding GOED voluntary limits for premium positioning. Secure backward integration into Antarctic krill supply through fishery certification partnerships to preempt ESG-driven procurement shifts. Expand Campinas-area algal fermentation capacity to capture vegetarian-positioned demand from pregnancy-focused formulations. For New Entrants and Emerging Players: Pursue veterinary channel DHA supplementation for canine cognitive development, where batch-level oxidation documentation requirements have kept commodity fish oil suppliers out. Target pet nutrition distributors in North American specialty retail as the most penetrable entry point. Lead with certified-sustainable krill or algal sourcing credentials that mirror pharmaceutical standards. For Investors and Strategic Acquirers: Long-term, this sits as a supply security play because marine-independent fermentation capacity commands scarcity premiums amid Antarctic fishery certification uncertainty. Acquisition candidates include mid-cap pharmaceutical-grade distillers with REACH-registered European infrastructure. Watch algal oil lipid extraction efficiency breakthroughs as the inflection signal for cost parity displacement of fish-derived alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Distillation Capacity Expansion | Captures prescription Lovaza-equivalent API demand from hypertriglyceridemia therapy manufacturers. |
| Antarctic Krill Fishery Certification Partnership | Secures phospholipid-bound EPA-DHA streams with MSC-aligned sustainability credentials for European pharmacy channels. |
| Brazilian Algal Fermentation Scale-Up | Displaces temperature-dependent marine harvesting cycles for pharmaceutical buyers seeking supply continuity. |
| REACH Registration Investment for European Import | Prevents customs detention risks for ethyl ester concentrates targeting EFSA health claim authorization pathways. |
| Veterinary Channel DHA Formulation Development | Accesses premium pricing tolerance in pet nutrition with lower regulatory friction than human pharmaceuticals. |
Study Parameters
Operator-level perspectives from pharmaceutical distillation specialists, marine ingredient procurement directors, veterinary channel distributors, and EFSA regulatory consultants anchored the qualitative base. Primary interviews combined with secondary validation from FDA drug approval filings, EMA Novel Food registrations, GOED technical guidelines, and Peruvian fisheries ministry quota announcements. Bottom-up volume modeling across extraction facilities and top-down demand triangulation from pharmaceutical API contracts and supplement retail audits ensured cross-verification.
Scenario-bracketing around El Niño frequency, algal oil yield trajectories, and Antarctic krill MSC certification outcomes bounded the projection range. Segmentation dimensions spanned delivery format, regulatory pathway, source type, and end-use application. CAGRs derived from fitted growth curves applied to normalized baseline volumes, with pharmaceutical prescription penetration rates and pet nutrition premiumization trends as key forecast inputs across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in marine biomass commodity indices, fermentation input energy costs, or European pharmacy reimbursement policies would shift the trajectory. Forecasts embed assumptions on EFSA health claim authorization timelines and FDA qualified health claim expansion scope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Grass-Fed Collagen Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Europe Vegan Supplements Market
Nutritional Supplements
Energy Gums Market
Nutritional Supplements
Europe Collagen Supplements Market
Nutritional Supplements
Mood Support Supplements Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
Biotin Supplement Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Whey Protein Powder Market
Nutritional Supplements
Sea Moss Supplements Market
Nutritional Supplements
China Collagen Peptides Market