
 Mexico Packaged Food Products Market | 2026-2036
Mexico Packaged Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Packaged Food Products Market Insights
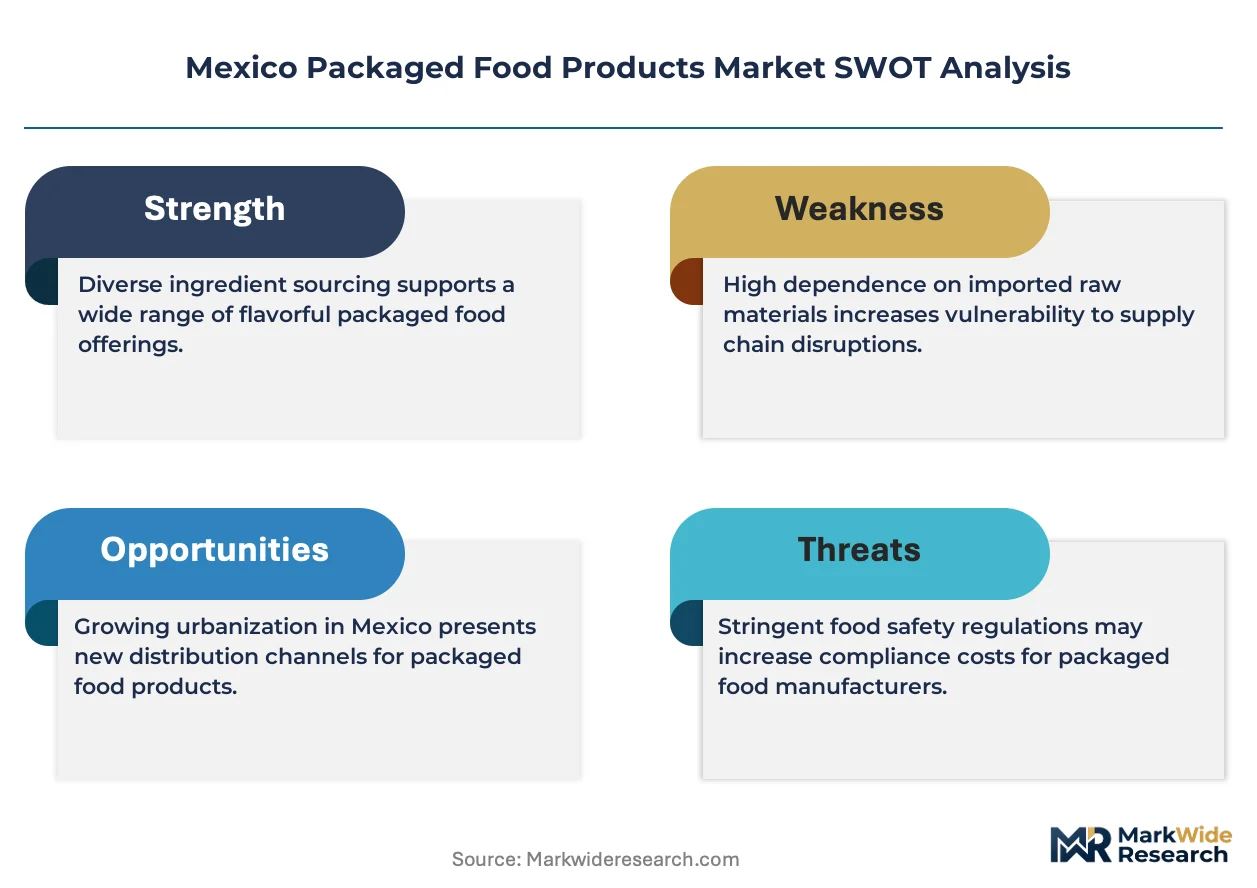
Urban professional households is bifurcating from traditional family bulk buyers as time-scarcity reshapes purchasing patterns. Grupo Bimbo SAB de CV leverages its national bakery distribution network to dominate the snack and bread categories. Sigma Alimentos anchors refrigerated protein and prepared meals through vertically integrated cold-chain assets. Grupo Herdez competes in sauces and canned goods by controlling iconic Mexican flavor brands.
Packaged food products encompass shelf-stable and refrigerated consumables processed, sealed, and labeled for retail sale, with specifications governing water activity below 0.85 for ambient stability or frozen storage below minus 18 degrees Celsius for meal preservation, serving industrial and commercial buyers seeking consistent quality, traceable safety, and extended distribution reach. Snacks and frozen meals capture the fastest expansion as convenience-seeking households shift from scratch cooking, while canned goods remains a mature margin pool sustained by institutional food service procurement. Supermarkets and online retail channels are restructuring shelf-space negotiations as e-commerce fulfillment centers demand case-lot efficiency distinct from traditional pallet economics.
COFEPRIS enforces NOM-051 front-of-package warning labels and NOM-130 nutritional specifications that compel reformulation across sodium, sugar, and saturated fat content. PROFECO monitors unit pricing and net content accuracy, creating compliance costs that favor scaled manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor pending modifications to NOM-051 warning octagon thresholds and assess whether captive distribution investments in the Bajío and northern border states justify capital allocation against third-party logistics alternatives.
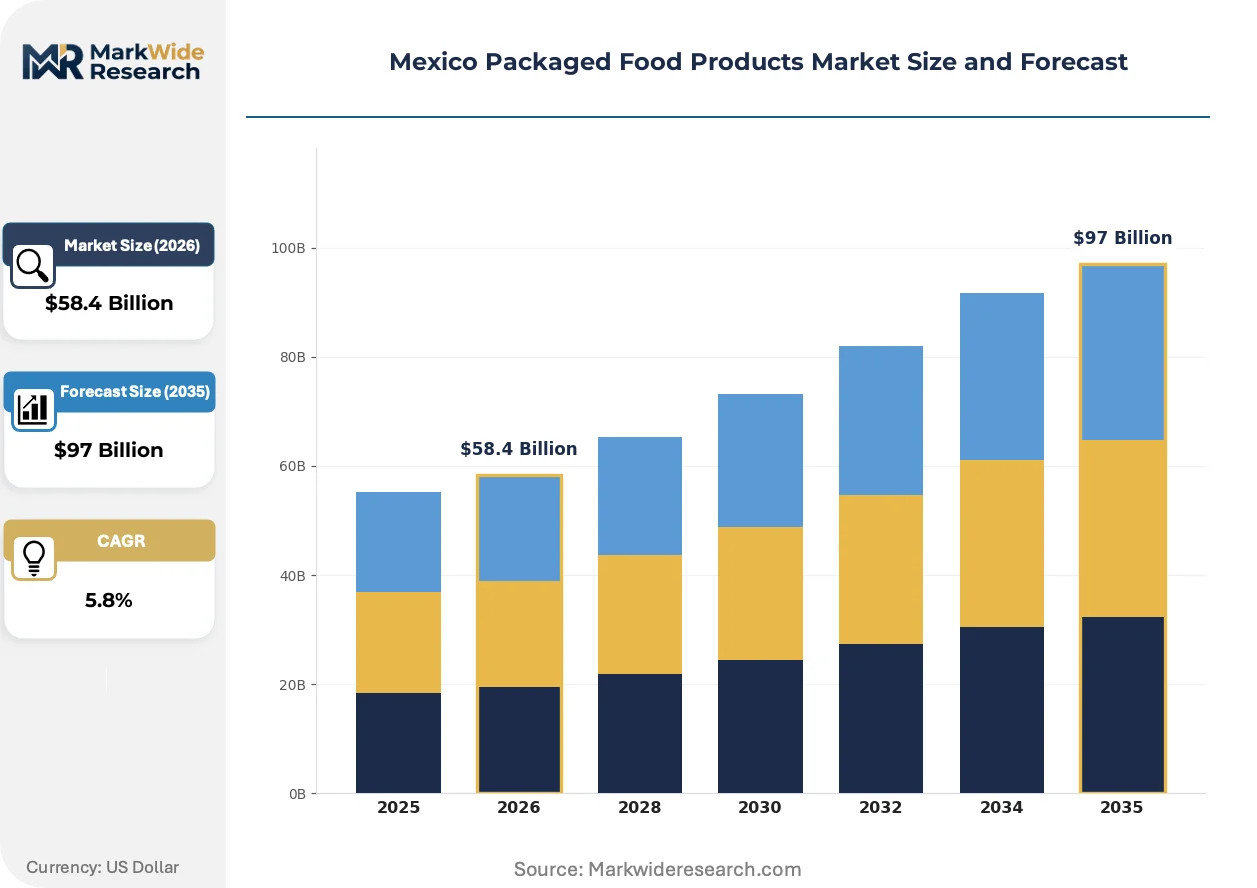
Market Dynamics
Urban household time-scarcity in Mexico City and Monterrey is bifurcating purchasing patterns away from traditional family bulk buyers toward convenience-oriented ready-to-eat formats. COFEPRIS mandates are simultaneously forcing sodium and sugar reformulation across portfolios, creating compliance costs that favor scaled manufacturers.
Growth Catalysts
- Cold-chain infrastructure:Refrigerated logistics expansion in the Bajío industrial corridor enables frozen meal distribution reach previously limited to shelf-stable formats. Urban professional households now access extended product variety through temperature-controlled last-mile networks.
- NOM-051 nutritional transparency:Front-of-package warning labels from COFEPRIS accelerate clean-label product development. Manufacturers reformulating portfolios capture preference shifts among health-conscious buyers seeking reduced sodium and sugar content.
- Industrial corridor concentration:Manufacturing gravity in Querétaro and Guanajuato creates supplier clustering effects. Proximity to processing facilities shortens distribution lead times for refrigerated protein and prepared meal categories.
Market Restraints
- Input cost volatility:Wheat and corn price fluctuations squeeze bakery and snack margins. Grupo Bimbo's national distribution network partially offsets this through volume purchasing power unavailable to regional competitors.
- Regulatory friction:PROFECO unit pricing enforcement and net content accuracy monitoring create recurring compliance audit burdens. Smaller manufacturers lack dedicated regulatory affairs teams to manage inspection cycles.
- Substitution threat:Fresh food delivery platforms and meal-kit services displace frozen ready-to-eat purchases in affluent urban zip codes. Time-scarce households increasingly bypass retail entirely for direct-to-door alternatives.
Strategic Opportunities
- E-commerce fulfillment innovation:Case-lot efficiency requirements from online retail channels favor manufacturers with automated packaging lines. Sigma Alimentos leverages vertically refrigerated assets to serve fulfillment centers with pallet-to-case flexibility.
- Northern border state penetration:Underdeveloped cold-chain density in Chihuahua and Nuevo León outside Monterrey metro areas presents first-mover expansion potential. Captive distribution investments here preempt third-party logistics alternatives.
- Institutional food service pivot:Hotel and corporate cafeteria procurement is consolidating toward traceable safety certification. Grupo Herdez controls iconic flavor brands that anchor sauce and canned goods specifications in contract negotiations.
Industry Challenges
- Reformulation R&D timelines:NOM-051 threshold modifications pending from COFEPRIS force parallel product development tracks. Manufacturers must maintain multiple formulation variants pending final regulatory certainty.
- Cold-chain capex intensity:Frozen meal preservation below minus 18 degrees Celsius requires continuous refrigeration infrastructure. Asset-heavy balance sheets constrain working capital flexibility for mid-tier competitors.
- Legacy system integration:Traceability software for NOM-130 compliance must interface with existing ERP platforms. Data architecture gaps between production floor sensors and regulatory reporting systems create implementation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Packaged Food Products Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $97 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Sauces, Frozen Meals, Canned Goods Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale Customer Type: Households, Restaurants, Cafes, Food Service Packaging Type: Bottles, Tins, Pouches, Cartons |
| Companies Covered | Sigma Alimentos, Pepsico Alimentos México, Grupo Bimbo SAB de CV, Grupo Herdez, Nestlé México, Gruma, Grupo Bafar, Industrias Bachoco, Grupo Lala, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Packaged Food Products Market Trends and Innovations
Reformulation technologies and channel restructuring are compressing traditional competitive advantages in Mexican packaged food. Three developments dominate the current transformation cycle.
Modified-atmosphere packaging is fragmenting shelf-life extension capabilities across smaller manufacturers. Vacuum-sealing and nitrogen-flush systems previously required capital-scale investment now deploy at mid-tier throughput levels. Regional sauce and prepared meal producers in Jalisco and Puebla adopt these systems to compete with national brands on ambient stability claims.
COFEPRIS is tightening NOM-051 warning octagon thresholds for sodium and saturated fat content. Reformulation mandates compress profit margins on legacy product lines while creating R&D differentiation opportunities. Bakery and snack categories face the most acute compliance pressure given existing portfolio composition.
Households are consolidating weekly purchasing into fewer, larger online orders. Supermarket shelf-space negotiations now compete with case-lot pricing demands from e-commerce fulfillment centers. Mexico City and Monterrey urban professionals drive this channel rotation, accepting next-day delivery windows in exchange for assortment breadth unavailable in physical retail.
Mexico Packaged Food Products Market Segmentation
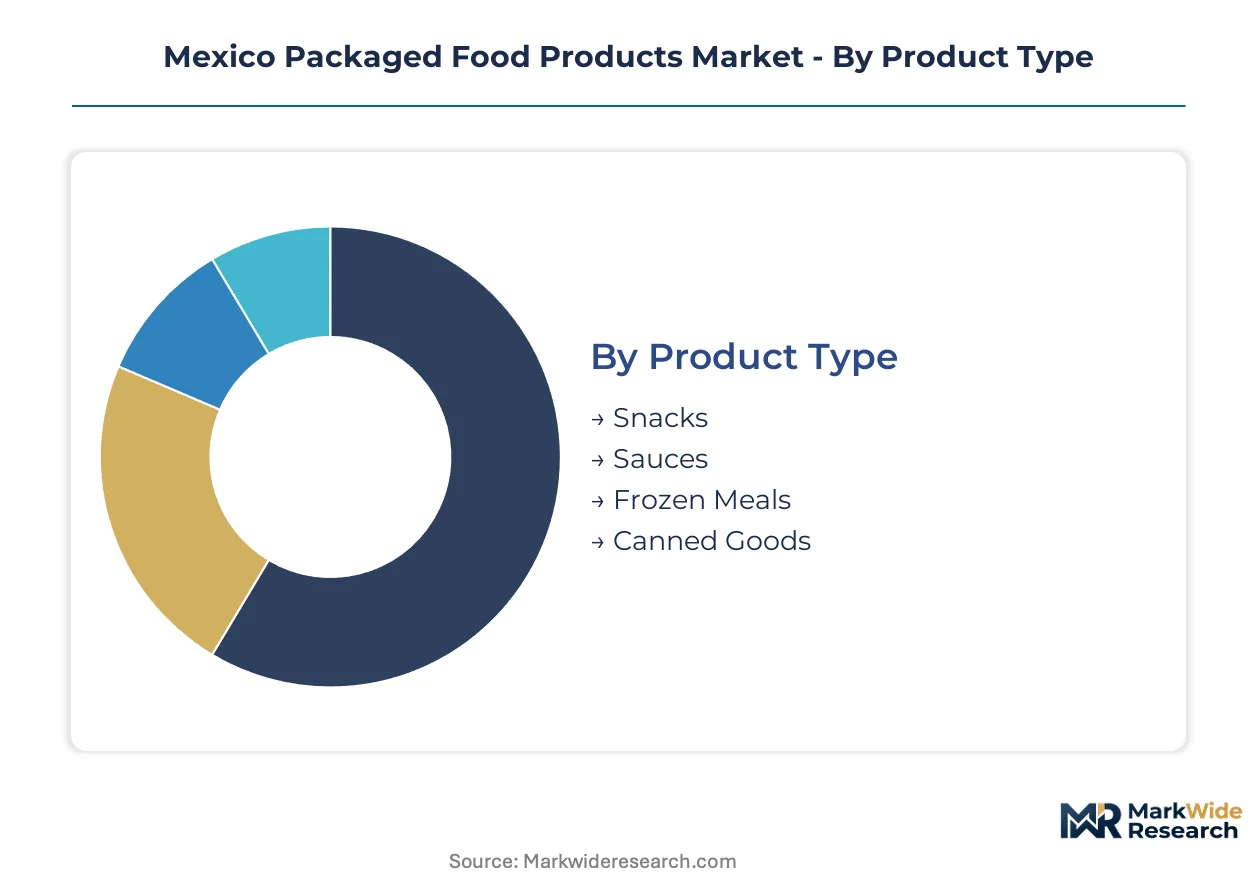
Segmentation in Mexico's packaged food market reveals how COFEPRIS regulations and cold-chain infrastructure reshape competitive boundaries across product formats. Understanding these divisions exposes where reformulation costs concentrate and which channels capture urban household spending shifts.
Product Type:
Domestic consumption dominates snacks and sauces while frozen meals increasingly serve northern border export corridors into the United States.
- Frozen Meals:Temperature-controlled preservation below minus 18 degrees Celsius enables extended shelf stability for protein-based preparations. Demand clusters in Mexico City and Monterrey where dual-income households trade scratch cooking for convenience; COFEPRIS NOM-130 traceability mandates add compliance layers that favor scaled manufacturers with dedicated food safety teams.
- Snacks:Modified-atmosphere packaging extends ambient stability for bakery and savory categories without refrigeration dependency. Bajío industrial corridor production facilities supply national distribution networks; NOM-051 front-of-package warning label thresholds force sodium and sugar reformulation across legacy portfolios.
- Sauces:Shelf-stable formulations with water activity below 0.85 anchor procurement for institutional food service buyers seeking consistent flavor profiles.
- Canned Goods:Retort processing delivers extended ambient stability for vegetable and protein preservation, sustaining margin pools through hotel and cafeteria contract specifications.
Frozen meals holds the largest share; momentum sits with snacks as reformulation technologies compress R&D timelines for clean-label variants.
Distribution Channel:
Channel selection determines case-lot economics and temperature control requirements, with refrigerated categories demanding fundamentally different fulfillment infrastructure than ambient-stable formats.
- Supermarkets:Traditional pallet-based shelf-space negotiations face pressure from e-commerce fulfillment centers demanding case-lot efficiency. Monterrey and Mexico City urban professionals consolidate weekly purchasing into fewer, larger trips; retailers respond with expanded ready-to-eat meal assortments.
- Online Retail:Automated packaging lines and next-day delivery windows reshape procurement patterns for time-scarce households. Sigma Alimentos leverages vertically integrated refrigerated assets to serve fulfillment centers with pallet-to-case flexibility; delivery density challenges persist outside capital region zip codes.
- Convenience Stores:Impulse-oriented snacking purchases concentrate in urban corridors with high foot traffic density.
- Wholesale:Institutional buyers consolidate procurement through traceable safety certification requirements.
Supermarkets retains volume leadership; online retail climbs fastest as urban household consolidation accelerates.
Customer Type:
End-user differentiation separates price-sensitive bulk procurement from premium convenience positioning across reformulated and legacy product lines.
- Households:Urban professional segments in Mexico City and Monterrey drive clean-label preference shifts, accepting price premiums for reduced sodium and sugar content. Traditional family bulk buyers sustain volume for economy-tier canned goods and staple sauces; bifurcation forces parallel portfolio maintenance.
- Food Service:Hotel and corporate cafeteria procurement consolidates toward suppliers with COFEPRIS certification and batch traceability systems. Grupo Herdez anchors sauce specifications through iconic Mexican flavor brand control; contract terms increasingly mandate reformulated ingredient profiles.
- Restaurants:Mid-tier dining establishments balance menu consistency against input cost volatility for wheat and corn derivatives.
- Cafes:Limited-service formats prioritize portion-controlled packaging and rapid preparation compatibility.
Households commands the greatest revenue concentration; food service delivers the steepest expansion trajectory as institutional safety certification requirements tighten.
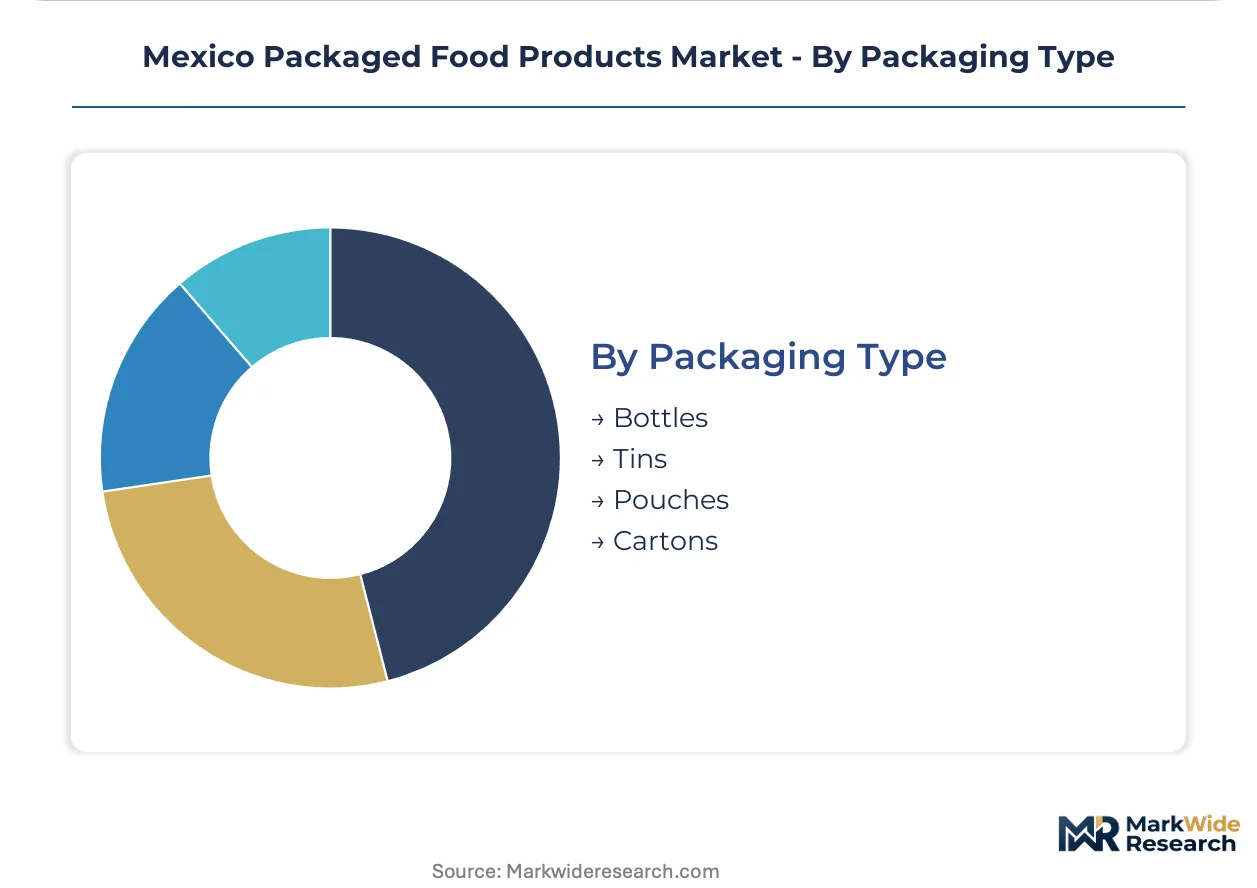
Packaging Type:
Material selection governs barrier properties, shelf-life extension, and compliance with NOM-051 nutritional labeling placement mandates.
- Pouches:Flexible film structures with high barrier layers enable lightweight distribution for sauces and prepared meal components. Jalisco and Puebla regional producers adopt nitrogen-flush systems previously requiring capital-scale investment; modified-atmosphere capabilities fragment across mid-tier manufacturers.
- Cartons:Aseptic filling technology supports ambient-stable liquid and semi-liquid products without refrigeration dependency. Querétaro processing proximity shortens distribution lead times for refrigerated protein categories; shelf-stable extensions compete with tin formats on sustainability positioning.
- Bottles:PET and glass formats dominate sauce and condiment categories requiring resealability.
- Tins:Metal can integrity sustains retort processing for vegetable and protein preservation with multi-year ambient stability.
Cartons captures the greatest installed base; pouches gains share fastest as flexible packaging lines reduce minimum efficient scale thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity clusters along Mexico's industrial spine, with refrigerated distribution networks dictating market reach for temperature-sensitive categories. Cold-chain density separates competitive positions across sub-regional markets.
Mexico City Metro
Dual-income professional households drive ready-to-eat meal demand through e-commerce consolidation and supermarket premium assortments. COFEPRIS NOM-051 enforcement tightest here, accelerating clean-label reformulation timelines. Last-mile refrigerated logistics in the capital region enable frozen meal penetration previously limited to shelf-stable formats.
Nuevo León
Monterrey anchors northern consumption with proximity to US border export corridors and corporate cafeteria procurement concentration. PROFECO unit pricing audits intensify in this high-income metro, favoring manufacturers with dedicated compliance infrastructure. Cold-chain gaps persist outside the capital zone, constraining frozen category distribution.
Bajío Region
Querétaro and Guanajuato processing facilities generate supplier clustering effects for refrigerated protein and prepared meals. Manufacturing proximity shortens distribution lead times to central Mexico consumption centers. Industrial real estate expansion here supports automated packaging lines serving e-commerce fulfillment centers.
Jalisco
Guadalajara metro and surrounding municipalities host mid-tier sauce and prepared meal producers adopting modified-atmosphere packaging systems. Regional players compete with national brands on ambient stability claims through nitrogen-flush technology. Food service procurement from hotel chains concentrates traceability requirements here.
Northern Border States
Chihuahua and Tamaulipas present underdeveloped cold-chain density with first-mover expansion potential for captive distribution investments. Cross-border supply chain integration with Texas processing facilities creates dual-market sourcing flexibility. Institutional buyers here increasingly mandate COFEPRIS certification for contract eligibility.
Mexico Packaged Food Products Market Competitive Landscape
Concentration sits with diversified food conglomerates controlling vertically integrated cold-chain assets and national distribution networks. National bakery and refrigerated protein specialists occupy tier-one positions through scale advantages in procurement and compliance. Three archetypes dominate: integrated conglomerates with captive logistics, regional specialists leveraging proximity to industrial corridors, and multinational subsidiaries importing formulation expertise. Competitive dynamics center on portfolio reformulation speed and e-commerce fulfillment center penetration.
Among integrated Mexican food conglomerates, Sigma Alimentos and Grupo Bimbo SAB de CV exemplify scale-driven archetypes with captive refrigerated distribution infrastructure. Grupo Herdez occupies a position within the branded staples tier, anchoring sauce and canned goods specifications through flavor portfolio control. Pepsico Alimentos México represents multinational subsidiary positioning, leveraging global R&D resources for NOM-051 reformulation compliance.
| Leading Market Players |
|---|
| Sigma Alimentos |
| Pepsico Alimentos México |
| Grupo Bimbo SAB de CV |
| Grupo Herdez |
| Nestlé México |
| Gruma |
| Grupo Bafar |
| Industrias Bachoco |
| Grupo Lala |
| Others |
Pricing and Supply Chain Analysis
COFEPRIS NOM-051 certification tiers simultaneously gate supplier qualification and enable price stratification across reformulated clean-label portfolios and legacy formulations. Manufacturers achieving front-of-package warning exemption through sodium and sugar reduction command shelf-space premiums in Mexico City and Monterrey supermarkets, while uncertified competitors absorb margin compression or exit premium channels entirely.
Pricing Analysis
NOM-051 dictates the pricing tier structure by penalizing high-sodium and high-sugar formulations with mandatory octagon warnings that suppress price realization in retail negotiations. Three-tier pricing separates reformulated clean-label premium lines from standard transitional products and economy legacy formulations without certification investment. Price differentiation rests on COFEPRIS compliance status and cold-chain certification depth, with refrigerated protein categories sustaining wider spreads than ambient-stable snacks. Pricing pressure intensifies in bakery and snack segments as wheat input volatility squeezes manufacturers lacking Grupo Bimbo's volume purchasing power. Traditional family bulk buyers exhibit highest price sensitivity, while urban professional households in the capital region accept premiums for traceable safety credentials.
Supply Chain Analysis
Inbound logistics costs through Lázaro Cárdenas and Manzanillo port congestion periodically disrupt corn and wheat flour availability for Bajío processing facilities. Mexico draws grain supply from the United States and Canada, with secondary sourcing from Argentina and Brazil during North American harvest shortfalls. Cold-chain infrastructure for frozen meals hinges on continuous refrigeration below minus 18 degrees Celsius, creating asset-heavy balance sheet constraints that favor Sigma Alimentos' vertically integrated captive logistics over third-party alternatives. Single-source vulnerability concentrates in refrigerated last-mile networks outside Monterrey and Mexico City metro zones. Distribution runs through supermarket pallet economics competing with e-commerce fulfillment center case-lot efficiency requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's packaged food sector is recovering from reformulation cost absorption as NOM-051 compliance investments mature into shelf-space advantages and pricing power restoration.
For Market Incumbents: Fortify cold-chain density in Chihuahua and Nuevo León through captive distribution investments that preempt third-party logistics alternatives in underpenetrated northern border corridors. Deepen backward integration into refrigerated protein processing to offset input cost volatility and secure traceability certification for institutional food service procurement consolidation. Sigma Alimentos' vertically integrated model demonstrates how captive logistics constrain competitor expansion. For New Entrants and Emerging Players: COFEPRIS certification fast-tracks through Jalisco and Puebla regional production clusters enable modified-atmosphere packaging adoption at mid-tier scale previously requiring capital-intensive national infrastructure. Target sauce and prepared meal white space where Grupo Herdez' brand control remains incomplete in hotel and corporate cafeteria channels. Go-to-market execution should leverage nitrogen-flush technology partnerships with Querétaro equipment suppliers to compress time-to-certification. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates seeking portfolio rationalization of non-core ambient-stable categories amid reformulation cost pressure. Long-term viability favors manufacturers with demonstrated NOM-051 compliance velocity and e-commerce fulfillment center penetration density. Watch pending COFEPRIS threshold modifications for sodium and saturated fat as the signal indicating which reformulation investments will sustain competitive moats versus stranded legacy assets.| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation R&D Acceleration | COFEPRIS NOM-051 compliance velocity determines shelf-space access in Mexico City retail negotiations. |
| Cold-Chain Capacity Expansion | Captive refrigerated logistics in northern border states preempts third-party distribution alternatives. |
| E-Commerce Fulfillment Integration | Automated packaging lines serving Sigma Alimentos' pallet-to-case flexibility capture urban household consolidation. |
| Institutional Certification Investment | Traceable safety credentials anchor Grupo Herdez' sauce specifications in hotel procurement contracts. |
| Regional Production Clustering | Querétaro and Guanajuato proximity shortens distribution lead times for refrigerated protein categories. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with category buyers at supermarket chains, regulatory affairs directors at scaled manufacturers, cold-chain logistics operators, and institutional food service procurement managers. Secondary validation incorporated COFEPRIS regulatory filings, PROFECO pricing audit records, customs trade data for grain and packaging material flows, and Nielsen retail audit information for channel share movements. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Across the projection horizon, the analytical framework modeled volume and value outputs through simultaneous equations incorporating product type segmentation by temperature requirement, distribution channel economics by case-lot efficiency, customer type differentiation by certification sensitivity, and packaging format by barrier technology adoption. CAGRs derived from regression analysis against urban household formation rates, cold-chain infrastructure investment flows, and regulatory compliance cost curves specific to NOM-051 reformulation timelines.
Underlying assumptions cover continued COFEPRIS enforcement intensity, grain input price normalization, and e-commerce penetration ceilings in secondary metro markets, with deviation risk concentrated in pending NOM-051 threshold modifications and northern border trade policy shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
Ready Meals Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
South America Canned Fruits Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
Burritos Market
Packaged Foods
Canned Goods Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Tortilla Market
Packaged Foods
Instant Ramen Market