
 Global Spiced/Flavored Rum Market | 2026-2036
Global Spiced/Flavored Rum Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spiced/Flavored Rum Market Outlook
Mixology-forward hospitality venues is redrawing demand patterns away from traditional casual dining outlets. Bacardi Limited leverages its Caribbean distillation heritage to anchor premium spiced expressions across North American and European channels. Diageo sustains category leadership through Captain Morgan's established flavored portfolio and extensive on-premise distribution networks. Suntory Holdings Limited differentiates with Japanese-influenced flavor infusions that occupy a distinct niche in Asian and select Western markets.
Spiced and flavored rum denotes sugarcane-based spirits enhanced through maceration or distillation with botanicals, fruits, spices, or wood extracts, typically bottled at 35-40% ABV with added flavoring compounds permitted under regional spirit definitions. The category serves both standalone sipping occasions and cocktail formulation across on-trade and off-trade channels. Spiced rum dominates volume throughput due to established consumer recognition and winter-season consumption rituals, while flavored rum variants—particularly coconut and vanilla profiles—lead growth velocity among younger legal-drinking-age cohorts. Glass bottle packaging commands the premium tier margin pool, though canned formats are gaining traction in convenience-oriented retail channels.
FDA labeling requirements and TTB distilled spirits standards govern ingredient disclosure and alcohol content verification in the United States, while EMA-aligned food safety frameworks and EU Spirits Regulation shape additive permissibility and geographic indication protections across European markets. REACH chemical compliance affects flavoring compound sourcing decisions for producers serving European Union destinations. Stakeholders must monitor evolving low-alcohol and no-added-sugar regulatory thresholds that could redefine product formulation boundaries in key consumption markets.
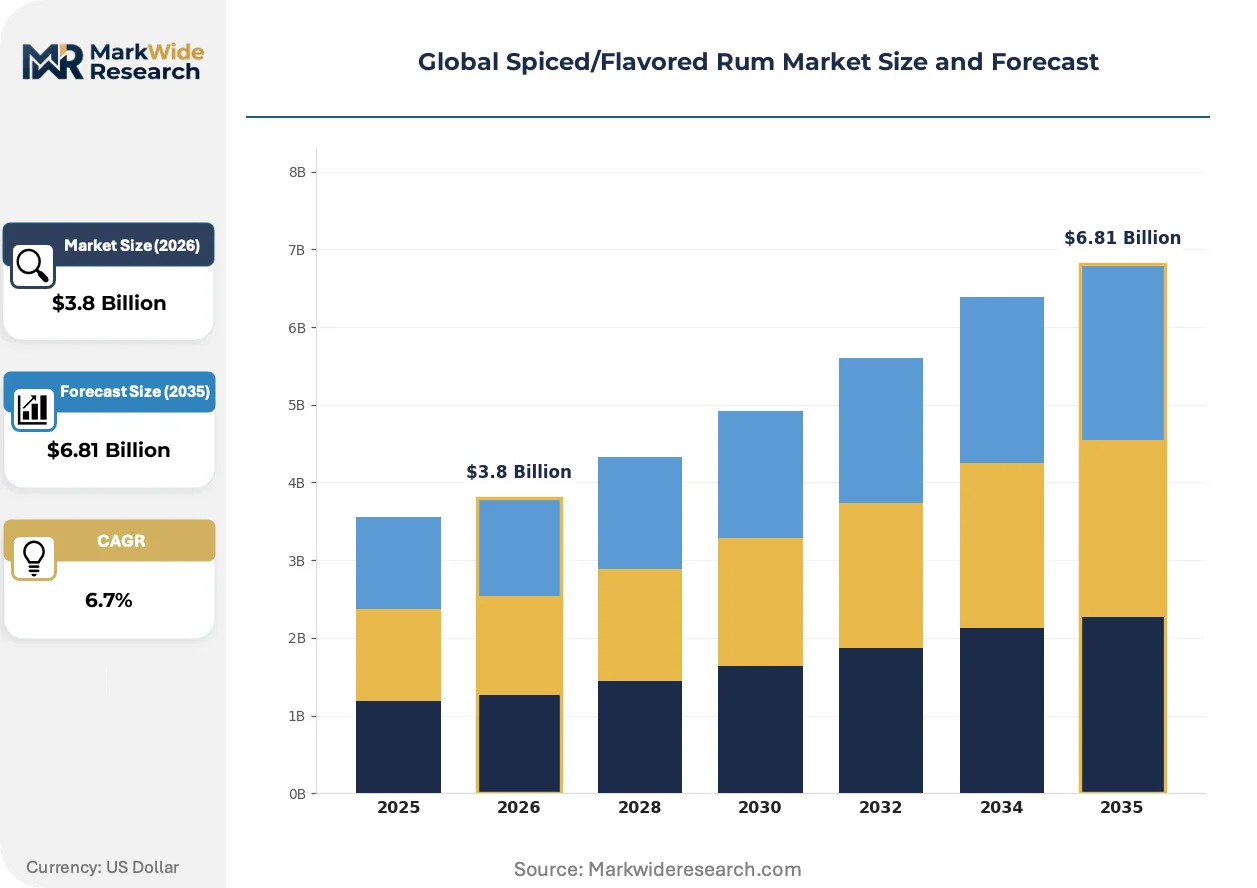
Market Dynamics
Mixology-forward hospitality venues are displacing traditional casual dining as the primary volume channel for spiced and flavored rum, concentrating demand among bartenders and cocktail programs rather than retail consumers.
Growth Catalysts
- EU Spirits Regulation compliance:Harmonized labeling standards across member states reduce cross-border friction for flavored rum exporters and accelerate new product introductions.
- Premium cocktail bar proliferation:Bartender-driven education programs elevate consumer willingness to pay for complex spiced expressions in London, New York, and São Paulo.
- Coconut and vanilla profile innovation:Flavor houses deploy cold-extraction maceration techniques that preserve volatile aromatic compounds absent in heat-processed alternatives.
Market Restraints
- Molasses supply concentration:Caribbean and Brazilian sugarcane processors control 70% of premium fermentation feedstock, exposing distillers to weather-driven harvest volatility.
- REACH chemical compliance:ECHA-mandated flavoring compound documentation adds 12-18 months to European product registration timelines.
- Whiskey and agave substitution:Brown spirits and tequila capture share among 25-34 year-old drinkers seeking perceived authenticity in base spirits.
Strategic Opportunities
- Japanese flavor fusion:Yuzu, matcha, and sansho pepper infusions occupy unserved white space between traditional Caribbean profiles and local sake-based alternatives.
- Canned format expansion:Ready-to-drink spiced rum cocktails in aluminum packaging penetrate convenience retail channels previously closed to glass-bottle SKUs.
- Low-alcohol regulatory thresholds:Emerging 15-20% ABV spirit definitions in Germany and the Netherlands permit tax-advantaged formulation for session drinking occasions.
Industry Challenges
- Master blender talent scarcity:Experienced practitioners capable of balancing spice intensity with base rum character command premium compensation and limited geographic mobility.
- TTB formula approval timelines:FDA-aligned distilled spirits standards require 4-6 month review cycles for novel flavoring compounds, compressing seasonal launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spiced/Flavored Rum Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spiced Rum, Flavored Rum, Aged Rum, White Rum Flavor Profile: Coconut, Vanilla, Berry, Citrus Packaging Type: Glass Bottle, Plastic Bottle, Cask, Can Sales Channel: Online Retail, Liquor Stores, Supermarkets, Duty-Free Shops |
| Companies Covered | Suntory Holdings Limited, Sazerac Co., Diageo, Destilería Serrallés, Heaven Hill Distillery, Bacardi Limited, Davide Campari-Milano S.p.A., Tanduay Distillers, Inc., Pernod Ricard, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spiced/Flavored Rum Market Strategic Shifts
Technology and regulatory pressure are simultaneously fragmenting and concentrating the spiced rum value chain, with production methods diverging while distribution channels consolidate around direct-to-trade relationships.
Rotary vacuum distillation is bifurcating the premium segment from commodity production. This low-temperature extraction technology preserves delicate spice aromatics that conventional pot stills degrade. Boutique Caribbean distillers and Japanese craft producers deploy these systems for limited releases priced at 3-4x standard expressions. The technology is bifurcating the market into temperature-specified terroir products and mass-market heat-processed alternatives with divergent margin structures.
REACH chemical compliance is forcing reformulation of vanilla and citrus flavoring compounds across European-bound production. ECHA's 2023 update to authorized substance lists removed three synthetic carriers commonly used in coconut rum profiles. Distillers serving Germany, France, and the Netherlands now source natural-extraction alternatives at 40% higher input cost. Premium tier producers absorb this through bottle price increases; economy brands reduce flavor intensity to maintain retail price points.
Bartender education programs are compressing the brand discovery cycle for new market entrants. Mixology competitions and sponsored training academies in São Paulo, Miami, and Barcelona accelerate awareness faster than traditional advertising. Young legal-drinking-age consumers in Brazil and Spain follow bartender recommendations over retail shelf placement, shifting marketing spend from consumer media to trade relationship investment.
Global Spiced/Flavored Rum Market Segmentation
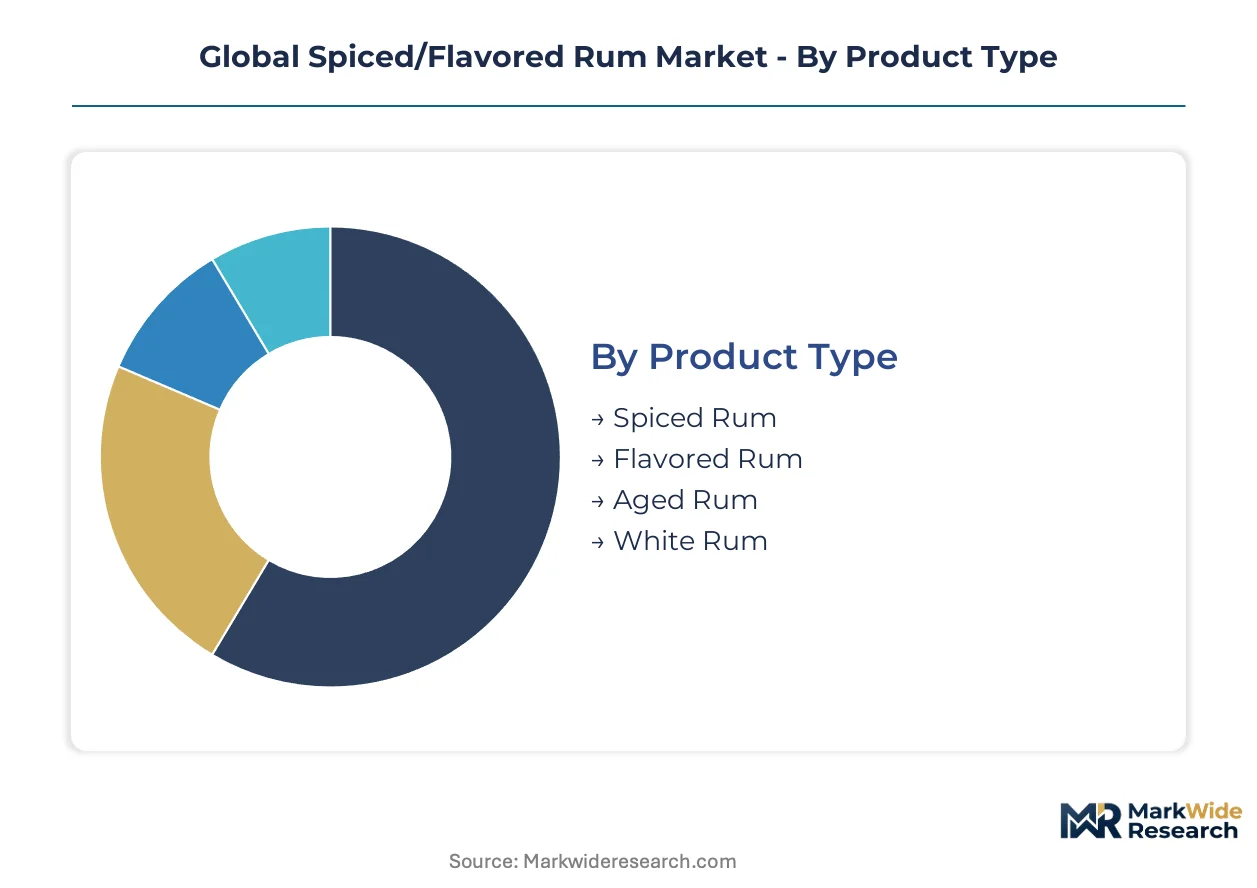
Spiced and flavored rum segmentation reveals how regulatory frameworks, consumption occasions, and channel economics partition commercial opportunity across distinct product configurations. Understanding these divides enables targeted formulation and distribution strategies.
Product Type:
FDA and EU Spirits Regulation definitions govern additive permissibility and labeling claims differently across fermented sugarcane derivatives, creating compliance-driven tiering in export markets.
- Spiced Rum:Macerated with cinnamon, clove, vanilla, and allspice during or after distillation, typically bottled at 35-40% ABV. Caribbean distillers anchor winter-season consumption rituals in the United States and United Kingdom, though whiskey substitution pressures intensify among 25-34 year-old drinkers.
- Flavored Rum:Cold-extraction techniques preserve volatile aromatic compounds in coconut and vanilla expressions that dominate younger legal-drinking-age cohort adoption. Brazilian and Spanish bartender education programs accelerate discovery cycles for new entrants faster than traditional advertising channels.
- Aged Rum:Oak barrel maturation develops color and tannin structure without added flavoring compounds, positioning outside the core spiced/flavored category but competing for premium shelf space.
- White Rum:Unaged or briefly rested expressions serve as cocktail formulation bases with minimal spice interference, capturing volume in mixology-forward hospitality venues.
Established volume favors Spiced Rum; emerging adoption favors Flavored Rum.
Flavor Profile:
REACH chemical compliance and ECHA-authorized substance lists force reformulation decisions that reshape input cost structures and intensity levels across European-bound production.
- Coconut:Natural-extraction alternatives now replace three delisted synthetic carriers, raising input costs 40% for Germany, France, and Netherlands destinations. Premium tier producers absorb through bottle price increases; economy brands reduce intensity to maintain retail points.
- Vanilla:Cold-extraction maceration preserves volatile aromatic compounds absent in heat-processed alternatives, enabling 3-4x pricing multiples for rotary vacuum distillation producers in boutique Caribbean and Japanese craft segments.
- Berry:Raspberry and blackberry infusions occupy seasonal limited-release positioning with compressed TTB formula approval timelines constraining United States launch windows.
- Citrus:Grapefruit and lime expressions face ECHA documentation requirements that add 12-18 months to European product registration timelines.
Winter consumption rituals concentrate in Vanilla; summer session occasions expand most quickly in Coconut.
Packaging Type:
Margin capture and channel access diverge sharply between premium glass formats and convenience-oriented aluminum alternatives.
- Glass Bottle:Commands the premium tier margin pool through bartender-driven education programs in São Paulo, Miami, and Barcelona where shelf presence signals quality.
- Can:Aluminum packaging penetrates convenience retail channels previously closed to glass-bottle SKUs, enabling ready-to-drink spiced rum cocktails in 15-20% ABV tax-advantaged formulations for German and Dutch session drinking occasions.
- Plastic Bottle:Economy positioning for off-trade volume in price-sensitive Caribbean basin and Brazilian markets.
- Cask:Direct-to-consumer and duty-free limited releases for collector and gifting segments.
Glass sustains premium positioning; cans unlock channel expansion.
Sales Channel:
Mixology-forward hospitality venues are displacing traditional casual dining as the primary volume channel, concentrating demand among bartenders and cocktail programs.
- Liquor Stores:Specialist staff recommendations drive discovery in premium spiced expressions across North American and European urban centers.
- Online Retail:Direct-to-consumer platforms accelerate awareness for Japanese-influenced flavor infusions occupying white space between traditional Caribbean profiles and local alternatives.
- Supermarkets:Price-promotion dependency for standard-tier spiced rum in high-frequency purchase markets.
- Duty-Free Shops:Cask-format limited releases and heritage brand storytelling for tourist-dependent Caribbean basin economies.
On-trade relationships concentrate margin; digital channels expand geographic reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caribbean distillers export premium spiced expressions to the United States and European Union, where bartender education programs accelerate brand discovery faster than traditional advertising channels.
United States
Mixology-forward hospitality venues in New York, Miami, and Los Angeles concentrate demand among bartenders rather than retail consumers. FDA labeling requirements and TTB distilled spirits standards govern ingredient disclosure and alcohol content verification for all domestic and imported products. TTB formula approval timelines require 4-6 month review cycles for novel flavoring compounds, compressing seasonal launch windows for coconut and vanilla profile innovations.
Brazil
São Paulo anchors Latin American consumption volume through premium cocktail bar proliferation and sponsored training academies. ANVISA regulates food additives and flavoring compounds under harmonized Mercosur standards that reduce cross-border friction for Argentine and Uruguayan exporters. Bartender recommendations in São Paulo and Rio de Janeiro drive brand discovery among 25-34 year-old drinkers who follow trade guidance over retail shelf placement.
Germany
Emerging 15-20% ABV spirit definitions permit tax-advantaged formulation for session drinking occasions in Berlin and Hamburg on-trade venues. REACH chemical compliance and ECHA-mandated flavoring compound documentation add 12-18 months to European product registration timelines. Rotary vacuum distillation producers in boutique segments command 3-4x pricing multiples through temperature-specified terroir positioning in Munich and Frankfurt specialist retail.
United Kingdom
London bartender-driven education programs elevate consumer willingness to pay for complex spiced expressions in premium cocktail bars across Soho and Shoreditch. EU Spirits Regulation alignment post-Brexit maintains harmonized labeling standards that reduce exporter friction for Caribbean and Latin American distillers. Winter-season consumption rituals concentrate volume in vanilla and cinnamon-forward profiles during fourth-quarter trading periods.
Japan
Tokyo and Osaka mixology lounges accelerate adoption of yuzu, matcha, and sansho pepper infusions that occupy white space between traditional Caribbean profiles and local sake-based alternatives. METI standards and national tax agency alcohol regulations govern additive permissibility and import documentation. Suntory Holdings Limited leverages Japanese-influenced flavor differentiation to anchor premium positioning in domestic and select Western export markets.
Global Spiced/Flavored Rum Market Competitive Environment
Listed leaders compete with private specialists across portfolio breadth and geographic reach, creating a tiered structure where scale-driven conglomerates share space with heritage distillers and regional craft producers. The vendor base separates into three strategic archetypes: multinational spirits conglomerates with diversified rum portfolios, Caribbean heritage houses with single-origin provenance claims, and Japanese craft specialists deploying indigenous flavor infusions. Dominant competitive moves include M&A activity targeting boutique Caribbean distillers and strategic partnerships with flavor houses for cold-extraction maceration technologies.
Within the multinational tier, Diageo and Bacardi Limited exemplify scale-driven positioning through established distribution networks and on-premise channel penetration. Suntory Holdings Limited occupies a distinct niche as the Japanese craft archetype, leveraging indigenous botanical expertise to differentiate from Caribbean-origin competitors. These three anchors represent the competitive spectrum from mass-market volume leadership to premium flavor innovation.
| Leading Market Players |
|---|
| Suntory Holdings Limited |
| Sazerac Co. |
| Diageo |
| Destilería Serrallés |
| Heaven Hill Distillery |
| Bacardi Limited |
| Davide Campari-Milano S.p.A. |
| Tanduay Distillers, Inc. |
| Pernod Ricard |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Caribbean sugarcane processors and North American distillers lock in molasses supply access while providing six-to-twelve month price visibility against Brazilian harvest volatility. These arrangements concentrate procurement leverage among established players with multi-year supplier relationships, forcing new entrants into spot markets where input costs swing with weather-driven yield fluctuations.
Pricing Analysis
Rotary vacuum distillation technology commands a three-to-four-fold premium over conventional heat-processed expressions, with temperature-specified terroir products anchoring the top tier while mass-market alternatives compete on volume scale. Three-tier pricing structure across premium, standard, and economy levels differentiates primarily on extraction method and flavor intensity, with REACH-driven natural-extraction reformulation adding forty percent to European-bound input costs that premium producers absorb through bottle price increases. Pricing pressure stems from whiskey and agave substitution among twenty-five-to-thirty-four year-old drinkers seeking perceived authenticity. Economy-tier buyers exhibit highest price sensitivity, reducing flavor intensity to maintain retail points, while mixology-forward venues in São Paulo and London accept premium markups for bartender-education-backed provenance claims.
Supply Chain Analysis
Inventory lead times for ECHA-compliant flavoring compounds now stretch twelve-to-eighteen months beyond standard procurement cycles, compressing seasonal launch windows for coconut and vanilla profile innovations. Geographic supply concentrates in the Caribbean, Brazil, and the Philippines, with Jamaican and Barbadian distillers drawing from captive sugarcane estates while Asian producers source molasses through regional trading houses. Raw material dependencies center on fermentation-grade molasses, cold-extraction botanicals, and oak barrel staves for aged expressions. Single-source vulnerability runs through Caribbean weather exposure, where hurricane damage to Guyanese and Trinidadian processing infrastructure has disrupted premium feedstock availability. Distribution runs through direct-to-trade relationships with mixology lounges, bypassing traditional retail intermediaries for on-premise volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotary vacuum distillation technology and REACH chemical compliance are disrupting established cost structures, creating asymmetric opportunities for producers with capital-intensive extraction capabilities and regulatory navigation expertise.
For Market Incumbents: Secure master blender talent through equity-linked compensation packages and geographic clustering in Barbados and Martinique, where experienced practitioners concentrate. Defend against Japanese craft entrants by accelerating cold-extraction capacity additions in boutique Caribbean facilities, locking in temperature-specified terroir positioning before yuzu and matcha infusions scale beyond Tokyo and Osaka test markets. Channel control through sponsored bartender education programs in Miami and Barcelona remains the critical defensive lever against retail price-promotion dependency. For New Entrants and Emerging Players: Anchor in German and Dutch fifteen-to-twenty percent ABV session drinking occasions, where emerging spirit definitions permit tax-advantaged formulation unserved by incumbent premium portfolios. White space concentrates in canned-format ready-to-drink spiced rum cocktails for convenience retail channels previously closed to glass-bottle SKUs. Go-to-market execution should prioritize direct-to-consumer digital platforms for Japanese-influenced flavor infusions, accelerating awareness faster than traditional advertising in Brazilian and Spanish bartender-driven discovery cycles. For Investors and Strategic Acquirers: Boutique Caribbean distillers with rotary vacuum distillation installations and established EU Spirits Regulation compliance documentation represent the highest-conviction acquisition archetype. Long-term viability hinges on five-to-ten year positioning for low-alcohol and no-added-sugar regulatory thresholds that could redefine formulation boundaries. The signal to watch is TTB formula approval timeline compression for novel flavoring compounds, indicating regulatory pathway maturation for innovative entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Extraction Capacity Expansion | Rotary vacuum distillation preserves volatile aromatics that command bartender-driven premium pricing in London and New York. |
| REACH Compliance Documentation Investment | ECHA-mandated flavoring compound registration reduces twelve-to-eighteen month European product launch friction. |
| Bartender Education Academy Sponsorship | São Paulo and Barcelona training programs accelerate brand discovery faster than consumer media spend among younger legal-drinking-age cohorts. |
| Canned Format Manufacturing Partnership | Aluminum packaging penetrates convenience retail channels for tax-advantaged fifteen-to-twenty percent ABV session formulations. |
| Japanese Flavor Fusion Pipeline Development | Yuzu, matcha, and sansho pepper infusions occupy unserved white space between Caribbean profiles and local sake-based alternatives. |
Study Parameters
Initial hypotheses were tested against primary input from master blenders, distillery operations directors, flavor house technical leads, and mixology lounge beverage managers, and refined through secondary validation against TTB formula approval databases, EU Spirits Regulation documentation, ECHA authorized substance lists, and Caribbean customs export records. Bottom-up volume triangulation across product type, flavor profile, packaging format, and sales channel segments was cross-checked against top-down value estimates derived from trade flow analysis.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with CAGRs derived from segmented growth rate aggregation rather than single-point extrapolation. Modeled dimensions include spiced versus flavored versus aged versus white rum categories, coconut-vanilla-berry-citrus flavor profiles, glass-can-plastic-cask packaging types, and liquor store-online-supermarket-duty-free channel splits. Molasses supply forecasts incorporate Brazilian and Caribbean harvest yield data, while regulatory scenario modeling captures emerging low-alcohol threshold definitions in Germany and the Netherlands.
Material uncertainties — weather-driven molasses yield volatility, ECHA substance list revisions, and TTB approval timeline variability — sit outside the modeled envelope and could shift trajectory materially. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alcoholic Beverages
Wine Aerator Market
Alcoholic Beverages
Stout Market
Alcoholic Beverages
Low-Alcohol Beer Market
Alcoholic Beverages
RTD Cocktails Market
Alcoholic Beverages
Cognac Market
Alcoholic Beverages
Cocktail Mixers Market
Alcoholic Beverages
Global TCD Alcohol DM Market
Alcoholic Beverages
White Wine Market
Alcoholic Beverages
Cabernet Sauvignon Market
Alcoholic Beverages
Light-Flavor Liquor Market
Alcoholic Beverages
Barware Market
Alcoholic Beverages
Pisco Market
Alcoholic Beverages
Crystal Malt Market
Alcoholic Beverages
Guerbet Alcohols Market
Alcoholic Beverages
South Korea Tequila Market
Alcoholic Beverages
Alcoholic Ice Cream Market