
 Indexable Inserts Market | 2026-2036
Indexable Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Indexable Inserts Market Insights
East Asian carbide substrate producers is broadening output capacity to serve precision machining supply chains. Sandvik Coromant leverages integrated powder metallurgy capabilities to anchor its position in coated carbide systems. Kennametal Inc. competes through specialized insert geometries for difficult-to-machine materials. Iscar Ltd. differentiates via advanced chip-breaker designs that extend tool life in high-feed milling.
Indexable inserts are replaceable cutting tips, typically sintered from tungsten carbide or advanced ceramics with CVD/PVD coatings, designed to seat in reusable toolholders for turning, milling, and drilling operations. Carbide-based inserts dominate volume shipments due to their balance of hardness and toughness across steel and cast iron applications, while polycrystalline diamond variants command premium positioning in non-ferrous and composite machining. Turning applications generate the largest share of current demand, though milling inserts capture expanding share as five-axis machining centers proliferate in aerospace and mold production.
EPA metalworking effluent rules and OSHA silica exposure limits shape insert formulation and coating chemistry requirements in the US, while REACH and RoHS frameworks in Europe restrict certain binder phase constituents. ISO 1832 classification standards govern insert designation systems, enabling cross-manufacturer interchangeability that influences procurement patterns. Stakeholders must monitor evolving dual carbon goals in China and Japan's METI efficiency mandates, as these will redirect R&D investment toward low-energy coating processes and recyclable substrate architectures.
Market Dynamics
Coated carbide substrate technology is consolidating procurement power among aerospace and medical device manufacturers who now specify multi-layer CVD coatings as baseline requirements for heat-resistant superalloy machining contracts.
Growth Catalysts
- Aerospace Superalloy Demand:Heat-resistant superalloy components in next-generation turbine engines require advanced chip-breaker geometries that extend tool life under extreme thermal loads.
- REACH Compliance:ECHA restrictions on cobalt and nickel binder phases are accelerating reformulation of substrate chemistries toward tungsten-heavy compositions with reduced environmental liability.
- Five-Axis Machining Centers:Mold production facilities in Germany's precision engineering corridor are expanding milling insert consumption as complex geometries demand multi-directional cutting capability.
Market Restraints
- Tungsten Supply Concentration:China controls approximately 80% of global tungsten ore processing, exposing substrate producers to export quota volatility and geopolitical supply risk.
- High-Volume Low-Margin Segments:Standard-grade turning inserts for general steel applications face persistent price pressure from uncoated carbide substitutes and regrind services.
- Technical Limitation:Polycrystalline diamond inserts remain unsuitable for ferrous materials above 700°C due to carbon dissolution into iron, restricting premium positioning to non-ferrous applications.
Strategic Opportunities
- India Manufacturing Expansion:PLI scheme incentives for precision engineering and medical device production are creating first-mover advantages for coated insert suppliers establishing local technical service presence.
- Battery Housing Machining:Aluminum-intensive electric vehicle battery trays require high-feed milling strategies that favor advanced chip-breaker designs with extended flute engagement.
- Japan METI Efficiency Mandates:Energy consumption targets for metalworking processes are redirecting R&D investment toward low-temperature PVD coating technologies that reduce thermal processing loads.
Industry Challenges
- Coating Technician Scarcity:CVD reactor operation and thin-film characterization expertise remains concentrated among aging workforces in Germany and Japan, constraining capacity expansion.
- ISO 1832 Certification Timelines:Cross-manufacturer interchangeability testing for new insert geometries extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indexable Inserts Market |
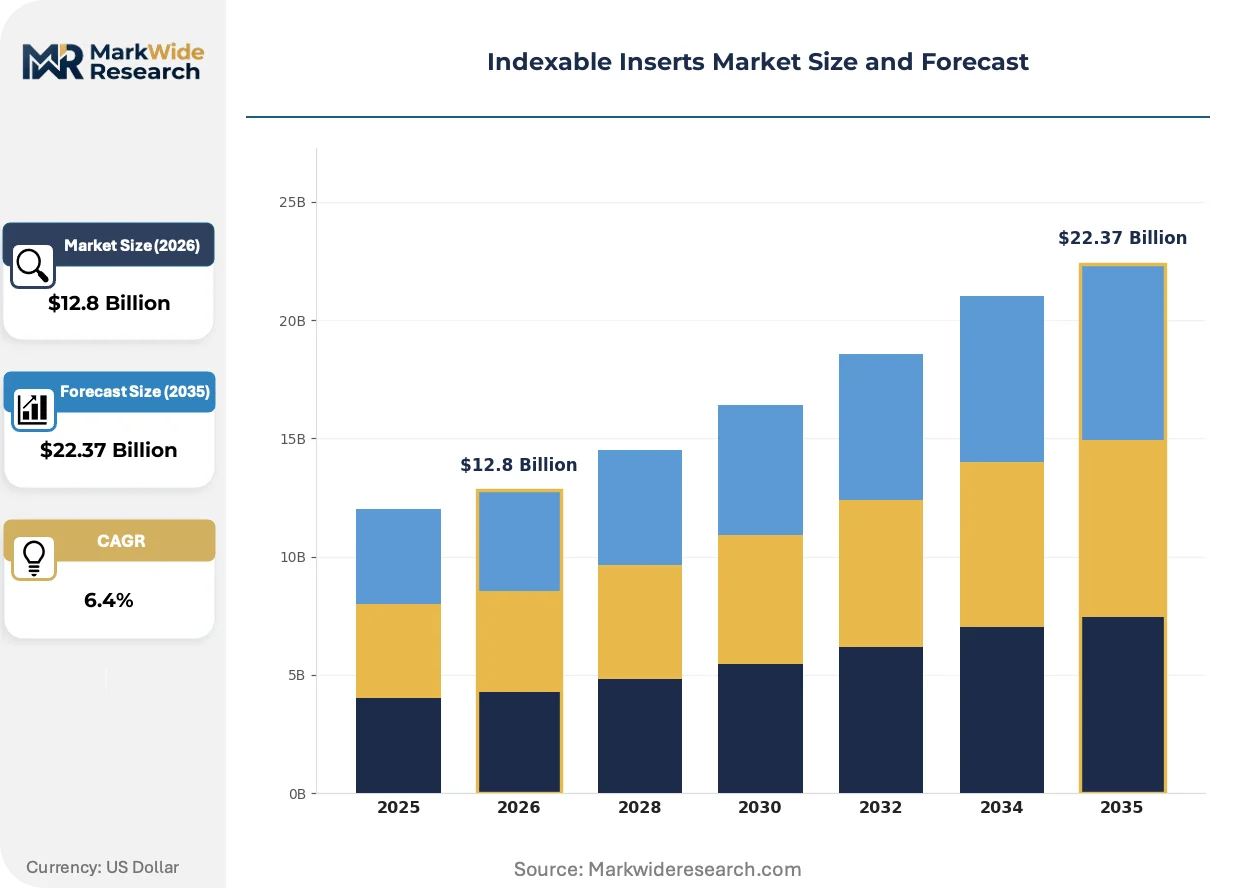
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carbide, Ceramics, Cubic Boron Nitride, Cermet, Polycrystalline Diamond Insert Shape: Square, Triangle, Diamond, Round, Octagonal Application: Turning, Milling, Drilling, Grooving, Threading End User Industry: Metal Fabricators, Aerospace Components, Machine Shops, Oilfield Equipment, Mold & Die Makers |
| Companies Covered | Sandvik Coromant, Kennametal Inc., Iscar Ltd., Mitsubishi Materials Corporation, Seco Tools, Walter AG, Sumitomo Electric Industries, Ltd., Tungaloy Corporation, Kyocera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indexable Inserts Market Trends and Innovations
Multi-layer coating architectures and digital tool management systems are compressing traditional procurement cycles while elevating technical service requirements across precision machining supply chains.
Physical vapor deposition with aluminum-chromium-nitride compositions is consolidating market positioning for high-speed steel and cast iron applications. Tier-one automotive suppliers in Germany and Japan have adopted PVD-coated inserts as standard for powertrain component machining. This technology is consolidating supplier relationships around integrated coating-to-substrate capabilities that smaller competitors cannot replicate.
EPA metalworking effluent rules under the Clean Water Act are restricting discharge of cobalt and nickel compounds from grinding and honing operations. Coated insert producers must reformulate binder phases or invest in closed-loop coolant systems to maintain US market access. Precision job shops in Michigan and Ohio report compliance costs driving consolidation toward larger integrated manufacturers with captive waste treatment.
Tool life guarantee contracts are displacing traditional per-insert pricing in aerospace supply chains. Tier-one manufacturers now demand outcome-based agreements where suppliers bear downtime risk for insert failure. This model concentrates in Germany's automotive and medical device clusters where unplanned spindle stops carry six-figure hourly costs.
Indexable Inserts Market Segmentation
Insert specification directly determines machining economics across precision engineering supply chains. Material composition, geometry, and coating architecture create tiered performance boundaries that aerospace and medical device manufacturers now codify in procurement contracts.
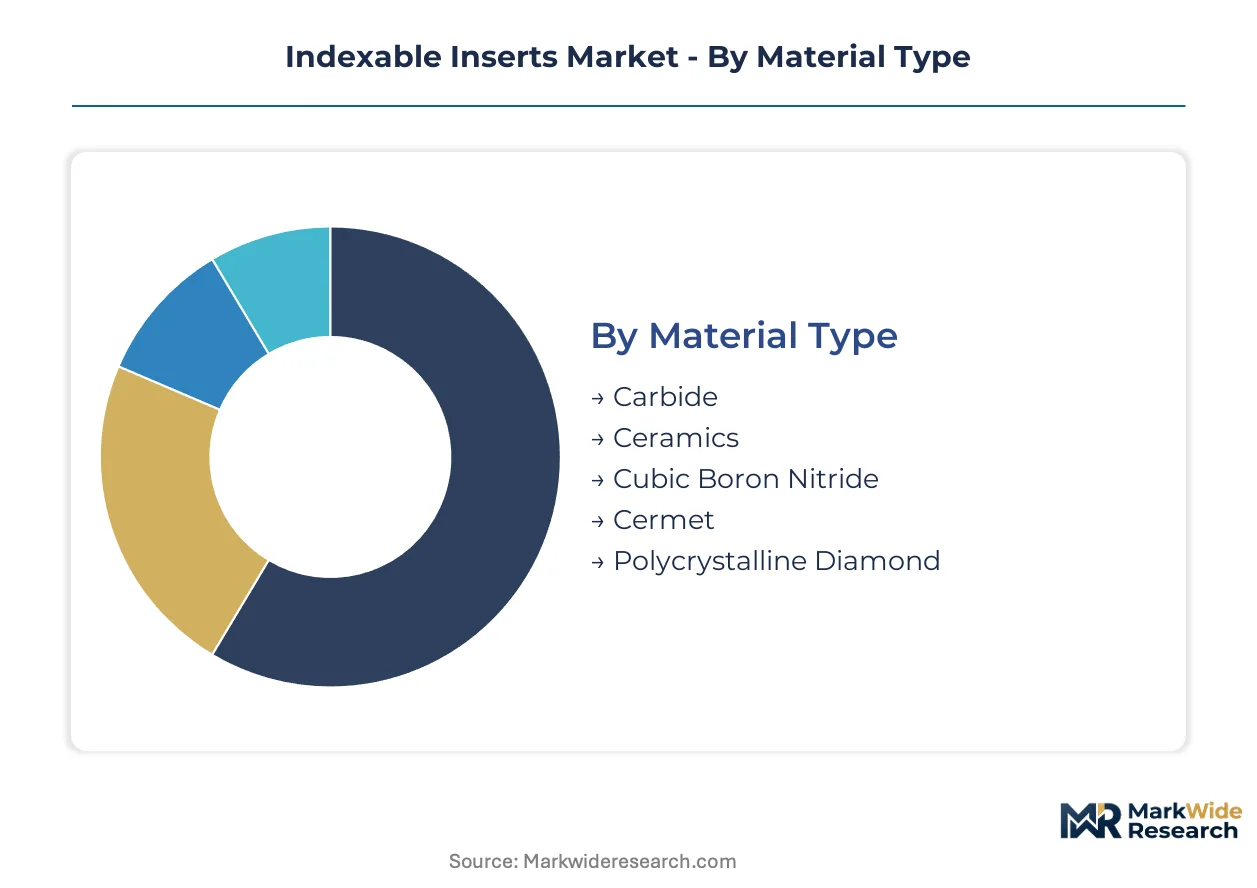
Material Type:
Capital intensity concentrates in coating infrastructure rather than substrate sintering alone, with multi-layer CVD systems requiring eight-figure reactor investments that constrain supplier entry.
- Carbide:Tungsten carbide substrates with cobalt or nickel binder phases dominate volume production. German automotive powertrain manufacturers specify coated carbide as baseline for steel machining contracts.
- Ceramics:Aluminum oxide and silicon nitride compositions withstand cutting temperatures exceeding 1200°C. Japanese METI efficiency mandates are redirecting R&D toward ceramic inserts that reduce coolant dependency in high-speed turning.
- Cubic Boron Nitride:Second-hardest known material after diamond; excels in hardened steel finishing above 45 HRC.
- Cermet:Titanium carbonitride-based composites offering intermediate hardness between carbide and ceramics.
- Polycrystalline Diamond:Sintered diamond particles on carbide substrates; restricted to non-ferrous applications due to carbon dissolution above 700°C.
Carbide absorbs the bulk of installed capacity; ceramics is expanding most quickly as dry machining protocols eliminate coolant costs.
Insert Shape:
Geometry selection governs tool life and chip evacuation in specific cutting kinematics, with corner radius and clearance angle specifications now digitized in CAM libraries.
- Square:Maximum cutting edge length per insert enables aggressive depth-of-cut strategies. Mold and die makers in Germany's precision engineering corridor favor square geometries for roughing operations.
- Triangle:Three usable edges deliver cost efficiency in high-volume turning. Automotive tier-one suppliers specify triangular inserts for crankshaft and camshaft production lines.
- Diamond:Acute and obtuse angle variants suit profiling and facing operations.
- Round:Continuous cutting edge distributes thermal load; preferred for contouring.
- Octagonal:Eight indexed edges maximize economy in heavy roughing applications.
Square and triangle geometries command equivalent volume share; diamond variants are climbing the fastest as five-axis machining centers proliferate.
Application:
Process-specific insert designs reflect divergent mechanical loading — continuous cutting in turning versus interrupted cuts in milling.
- Turning:Continuous chip formation enables predictable thermal management. Aerospace superalloy turbine disk machining demands advanced chip-breaker geometries that Kennametal and Iscar have patented.
- Milling:Periodic engagement generates thermal shock requiring tougher substrates. Complex mold geometries in Germany and Japan drive demand for multi-directional cutting capability.
- Drilling:Axial feed forces concentrate at chisel edge; specialized point geometries required.
- Grooving:Narrow width-to-depth ratios demand precision-ground peripheries.
- Threading:Profile accuracy requirements favor ground inserts over pressed geometries.
Turning retains the largest installed base; milling is gaining share fastest as machining center density rises.
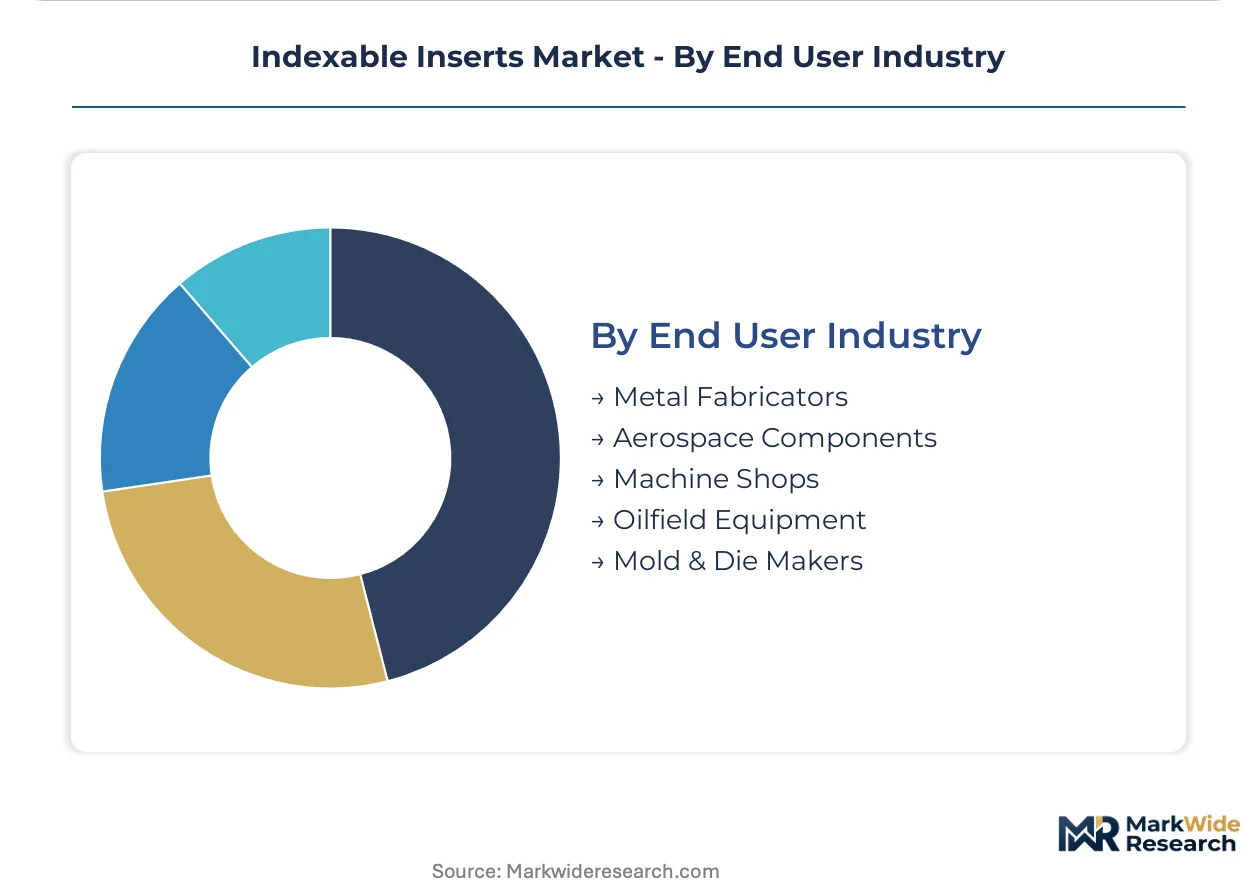
End User Industry:
Customer technical sophistication spans commodity job shops to specification-driven aerospace OEMs, creating tiered service requirements.
- Aerospace Components:Heat-resistant superalloy machining mandates coated carbide with multi-layer CVD architectures. Tool life guarantee contracts now displace per-insert pricing in turbine engine supply chains.
- Mold & Die Makers:Hardened tool steel and complex freeform surfaces require premium insert grades. Germany's automotive tooling cluster specifies PVD-coated variants for high-speed hard milling.
- Metal Fabricators:General steel and aluminum applications; price-sensitive procurement.
- Machine Shops:Diverse job mix favors versatile insert geometries and rapid changeover.
- Oilfield Equipment:Corrosion-resistant alloy threading and grooving in downhole components.
Aerospace and mold makers concentrate premium-grade consumption; metal fabricators represent the steepest expansion trajectory as reshoring initiatives rebuild domestic capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tungsten ore processing concentrates in China's Jiangxi and Hunan provinces, anchoring substrate supply chains that feed precision machining clusters across three continents. This geographic reality shapes procurement risk profiles and coating technology investments worldwide.
China
Domestic aerospace turbine production and electric vehicle battery housing machining drive coated carbide consumption. MIIT efficiency mandates and dual carbon goals redirect investment toward low-energy PVD coating processes. Precision engineering corridors in Jiangsu and Zhejiang provinces host expanding five-axis machining center fleets serving automotive tooling contracts.
Germany
Automotive powertrain manufacturers and medical device makers specify multi-layer CVD coatings as baseline procurement requirements. REACH compliance through ECHA restricts cobalt binder phases, accelerating tungsten-heavy substrate reformulation. The precision engineering corridor spanning Stuttgart, Munich, and Aachen concentrates premium-grade insert consumption for mold and die production.
United States
Aerospace superalloy machining for next-generation turbine engines demands advanced chip-breaker geometries. EPA metalworking effluent rules under the Clean Water Act restrict cobalt compound discharge, forcing coolant system upgrades. Michigan and Ohio precision job shops report compliance costs driving consolidation toward integrated manufacturers with captive waste treatment.
Japan
METI energy consumption targets for metalworking processes redirect R&D toward low-temperature coating technologies. Ceramic insert development accelerates as dry machining protocols eliminate coolant dependency. Nagoya and Osaka industrial clusters anchor domestic demand for high-speed hard milling applications in automotive tooling.
India
PLI scheme incentives for precision engineering and medical device production create first-mover advantages for technical service presence. Domestic automotive component machining expands coated carbide consumption beyond traditional general engineering. Gujarat and Maharashtra industrial corridors attract initial coating facility investments from multinational suppliers.
Indexable Inserts Market Competitive Landscape
Global majors compete with regional champions across coating technology and substrate integration capabilities. The vendor base separates into integrated powder metallurgy operators, specialized geometry designers, and regional substrate fabricators serving price-sensitive segments. Three archetypes dominate: captive tungsten carbide producers with in-house CVD reactors, independent coating specialists licensing substrate supply, and precision grinding houses focusing on complex chip-breaker geometries. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Within the integrated metallurgy tier, Sandvik Coromant and Kennametal Inc. occupy positions anchored by captive powder production and multi-layer coating infrastructure. Iscar Ltd. exemplifies the geometry-specialist archetype, with advanced chip-breaker designs serving high-feed milling applications. These three represent distinct strategic postures: full vertical control, substrate-coating integration, and precision geometry differentiation.
| Leading Market Players |
|---|
| Sandvik Coromant |
| Kennametal Inc. |
| Iscar Ltd. |
| Mitsubishi Materials Corporation |
| Seco Tools |
| Walter AG |
| Sumitomo Electric Industries, Ltd. |
| Tungaloy Corporation |
| Kyocera Corporation |
| Others |
Pricing and Supply Chain Analysis
REACH compliance through ECHA gates qualified supply for European automotive and medical device contracts, restricting cobalt-bearing substrates and elevating certified tungsten-heavy formulations to premium-tier pricing access while disqualifying uncertified competitors from specification-driven procurement.
Pricing Analysis
Tool life guarantee contracts bundle technical service and downtime risk transfer into aerospace procurement, displacing per-insert transactional pricing. Three-tier pricing structure across premium, standard, and economy levels separates multi-layer CVD-coated superalloy grades from single-layer PVD variants and uncoated carbide substitutes. Cost compression in standard-grade turning inserts intensifies because regrind services and Chinese substrate imports erode margins. Metal fabricators exhibit highest price sensitivity; aerospace tier-one manufacturers accept premium positioning for guaranteed throughput.
Supply Chain Analysis
Single-source vulnerability sits with China's Jiangxi and Hunan provinces, which control approximately four-fifths of global tungsten ore processing. Substrate production draws from tungsten concentrate, cobalt and nickel binder phases, and aluminum oxide ceramic precursors. Export quota volatility from Beijing's resource nationalism exposes European and Japanese coating facilities to feedstock disruption. Distribution runs through authorized distributor networks serving precision engineering clusters, with direct technical service relationships dominating aerospace and medical device accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Coating infrastructure capital requirements and REACH-driven substrate reformulation are consolidating the vendor base, forcing smaller geometry specialists and independent coaters toward acquisition or exit.
For Market Incumbents: Extend captive powder metallurgy capabilities into low-temperature PVD coating processes to meet Japan METI efficiency mandates and preempt ceramic insert competitors. Secure long-term tungsten concentrate offtake from secondary suppliers outside China to mitigate Jiangxi export quota exposure. Deepen technical service presence in India's Gujarat and Maharashtra corridors before PLI scheme incentives attract multinational coating facility investments. For New Entrants and Emerging Players: The price-point gap between premium multi-layer CVD grades and economy uncoated carbide creates white-space opportunity in mid-tier PVD-coated inserts for general steel machining. Target India's expanding automotive component sector through local technical partnerships that bypass ISO 1832 certification timeline disadvantages. Establish coating service bureau models serving precision job shops in Michigan and Ohio facing EPA compliance cost consolidation. For Investors and Strategic Acquirers: Japan METI low-temperature coating technology licensing announcements are the leading indicator that ceramic insert development is reaching commercial inflection. Five-to-ten-year viability favors acquiring geometry-specialist firms with patented chip-breaker designs rather than capital-intensive CVD reactor operators. Watch for ECHA cobalt restriction expansion signals that would accelerate tungsten-heavy substrate reformulation and reward early movers with qualified supply positions.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Temperature PVD Coating Investment | Reduces thermal processing energy to satisfy Japan METI efficiency mandates. |
| Tungsten Supply Diversification | Mitigates Jiangxi export quota volatility through Vietnam and Russian concentrate sourcing. |
| Technical Service Localization | Captures PLI scheme incentives in India's Gujarat precision engineering corridor. |
| Ceramic Insert R&D Acceleration | Eliminates coolant dependency for dry machining protocols under EPA effluent rules. |
| Tool Life Guarantee Contract Expansion | Locks aerospace tier-one relationships through outcome-based risk transfer pricing. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating reactor operators, precision engineering procurement managers, and aftermarket service directors. USITC trade databases, ECHA restriction dossiers, and Japan METI technology roadmaps provided cross-validation. Bottom-up insert shipment estimates from regional machining center fleet data reconciled with top-down tungsten carbide powder consumption figures.
Data-stream reconciliation across material type, insert geometry, application process, and end-user industry dimensions shaped the analytical framework over the projection horizon. CAGRs derived from fitted growth curves incorporating aerospace superalloy machining intensity, five-axis machining center penetration rates, and electric vehicle battery housing production forecasts. Coating technology substitution elasticities and REACH compliance cost pass-through assumptions informed segment-level trajectories.
Inputs from ECHA regulatory filings and Japan METI efficiency mandate disclosures were available through the study window; gaps in Chinese provincial tungsten export quota transparency introduce uncertainty bands around substrate supply assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Belt File Sander Market
Tools
Core Shooter Machine Market
Tools
Multi-Tasking Machine Tools Market
Tools
Cordless Long Neck Grinder Market
Tools
Sanding Machine Market
Tools
Edging Tool Market
Tools
Gear Cutting Machines Market
Tools
DIY Ball Mill Market
Tools
Construction Anchors Market
Tools
Rivet Gun Market
Tools
Foam Cutting Machine Market
Tools
Portable Rolling Toolbox Market
Tools
Portable Tools Market
Tools
Caulking Gun Market
Tools
US Chalk Reel and Line Market
Tools
Water Pump Pliers Market