
 Micronutrient Powders (Mnps) Market | 2026-2036
Micronutrient Powders (Mnps) Market Size, Share, and Industry Trends Forecast 2026-2036
Micronutrient Powders (Mnps) Market Insights
EU Green Deal compliance is hardening requirements for sustainable micronutrient sourcing, pushing food manufacturers toward certified supply chains. DSM leverages its backward integration into fermentation-based vitamin production to secure stable feedstock access. BASF SE anchors its position through geographic dominance in European premix manufacturing. Maternova specializes in maternal health formulations, differentiating within a narrow clinical niche.
Micronutrient powders are dry, homogeneous blends of vitamins, minerals, trace elements, and bioactive compounds, typically manufactured through spray-drying, microencapsulation, or direct compression to achieve particle sizes between 50 and 200 microns for uniform dispersion in food matrices or direct consumption. Their primary purpose is to correct or prevent nutritional deficiencies in human populations and livestock by delivering precise, stable doses of essential nutrients in shelf-stable formats. The vitamins segment leads in revenue contribution due to established clinical validation and broad fortification mandates, while the amino acids category represents the fastest-growing structural pocket as sports nutrition and clinical recovery formulations expand. Food fortification applications occupy the largest volume share, though nutritional supplements command superior margins through direct-to-consumer pricing power.
The FDA governs micronutrient powders as dietary ingredients under DSHEA, requiring current Good Manufacturing Practice compliance that elevates barrier costs for new entrants. REACH and EFSA frameworks in Europe impose full substance registration and novel food authorization, shaping reformulation decisions and cross-border trade patterns. India's FSSAI fortification standards and CDSCO oversight of clinical nutrition products are tightening quality benchmarks for both domestic producers and importers. Stakeholders must monitor evolving bioequivalence requirements between synthetic and naturally derived micronutrient forms as regulatory divergence across jurisdictions complicates global formulation strategies.
Market Dynamics
EU Green Deal compliance is hardening sustainability requirements across the entire micronutrient sourcing value chain, forcing manufacturers to reconfigure supply networks and certification protocols.
Growth Catalysts
- EU Green Deal mandates:REACH and EFSA frameworks impose full substance registration and novel food authorization, elevating compliance barriers that favor established producers with certified supply chains.
- India fortification mandates:FSSAI fortification standards and CDSCO oversight of clinical nutrition products are tightening quality benchmarks and pulling procurement volume toward South Asian manufacturing clusters.
- Fermentation-based vitamin production:Biotechnology advances in microbial synthesis are securing stable feedstock access and reducing dependency on petrochemical-derived precursors.
Market Restraints
- Input cost volatility:Raw material prices for vitamin precursors and mineral salts fluctuate with energy markets and agricultural commodity cycles, compressing margin predictability for premix manufacturers.
- Supply concentration risk:European premix manufacturing capacity clusters in Germany and the Netherlands, creating geographic vulnerability to logistics disruptions and regulatory enforcement variance.
- Regulatory friction:Divergent bioequivalence requirements between synthetic and naturally derived micronutrient forms across FDA, EFSA, and CDSCO jurisdictions complicate global formulation strategies.
Strategic Opportunities
- Underpenetrated maternal health segments:Clinical nutrition protocols for prenatal and postnatal care remain underserved in sub-Saharan African and South Asian markets, creating white space for specialized formulations.
- Sports nutrition expansion:Amino acid-enriched powders for athletic recovery and muscle preservation represent an emerging application category with direct-to-consumer pricing power.
- India PLI scheme incentives:Production-linked incentive schemes for pharmaceutical and nutraceutical manufacturing are attracting capital toward domestic micronutrient production capacity.
Industry Challenges
- Microencapsulation expertise scarcity:Formulation scientists with specialized knowledge of spray-drying parameters and particle engineering for 50-200 micron uniformity remain concentrated in European and North American technical centers.
- Certification timeline compression:Novel food authorization under EFSA and GRAS self-affirmation under FDA require 18-36 month validation cycles that delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micronutrient Powders (Mnps) Market |
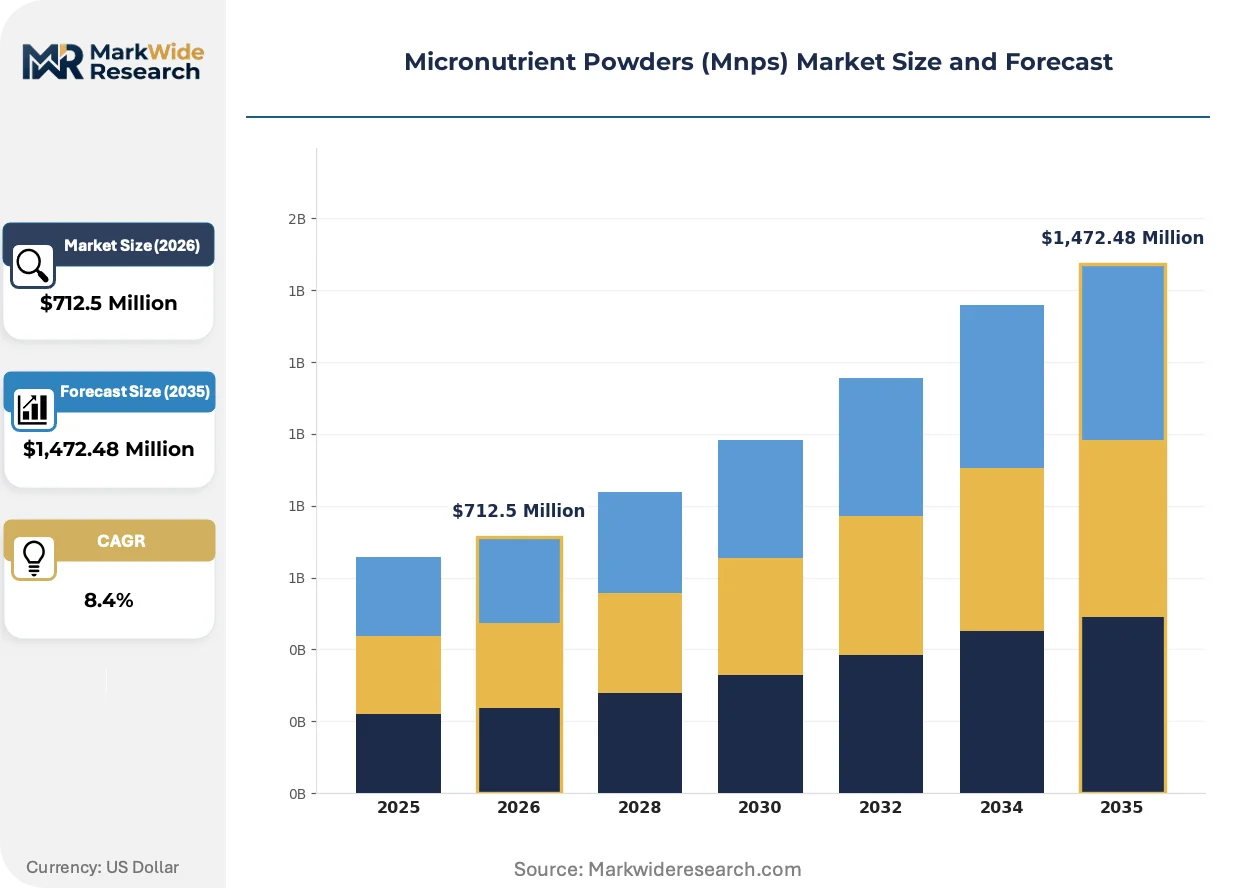
| Market Size in 2026 | $712.5 Million |
| Market Size in 2035 | $1,472.48 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
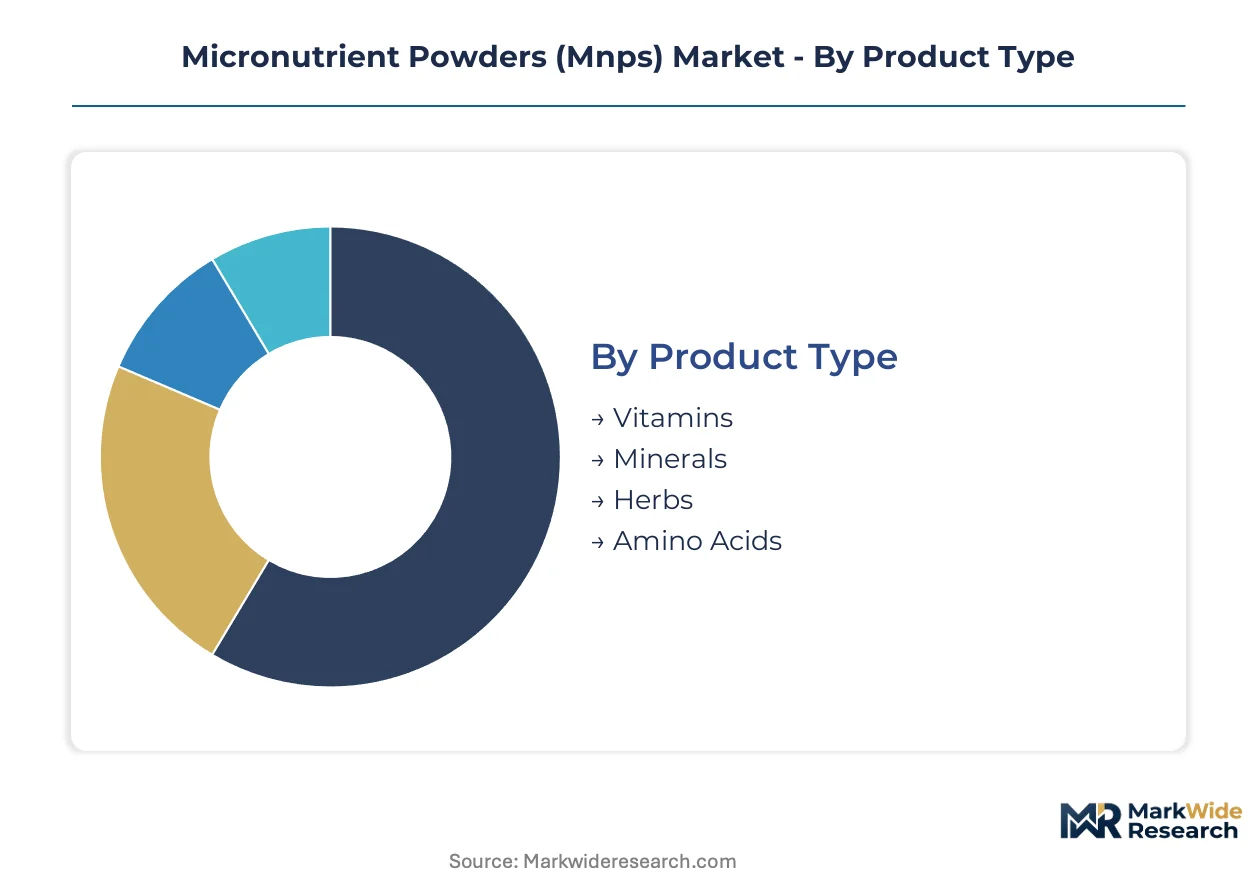
| Segmentation | Product Type: Vitamins, Minerals, Herbs, Amino Acids Application: Food Fortification, Nutritional Supplements, Animal Feed, Cosmetics End User: Healthcare Institutions, Nutraceutical Companies, Food Manufacturers, Cosmetic Brands Distribution Channel: Online Retail, Supermarkets, Pharmacies, Direct Sales |
| Companies Covered | DSM, BASF SE, Maternova, Piramal Pharma Solutions, Amway, Herbalife Nutrition, Nature's Bounty, GNC, USANA Health Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micronutrient Powders (Mnps) Market Trends and Innovations
Active reformulation of micronutrient delivery systems is reshaping competitive positioning, with biotechnology and regulatory convergence driving structural change across manufacturing and procurement patterns.
Microencapsulation technology is expanding into high-margin clinical nutrition applications. Spray-drying and lipid-coating processes now enable 50-200 micron particle uniformity with enhanced shelf stability for temperature-variable distribution environments. Hospital and long-term care procurement teams are adopting these formats for enteral feeding protocols, compressing the addressable market for conventional uncoated premixes.
REACH substance registration requirements are tightening cross-border trade patterns for vitamin and mineral premixes. Full dossier submission for novel micronutrient forms now precedes market access, extending lead times and elevating barrier costs. European food manufacturers are responding by consolidating supplier relationships toward vertically integrated producers with captive fermentation capacity.
Direct-to-consumer channel development is fragmenting traditional distribution hierarchies. Nutritional supplement brands now bypass institutional procurement through e-commerce platforms and subscription models, capturing margin that previously accrued to distributors. This pattern concentrates in North American and Western European markets where regulatory clarity under DSHEA and food supplement directives enables rapid product iteration.
Micronutrient Powders (Mnps) Market Segmentation
Micronutrient powder specifications vary dramatically across end-use contexts, from hospital-grade enteral formulations requiring 50-200 micron uniformity to cosmetic-grade mineral blends prioritizing sensory texture. Segmentation reveals how formulation complexity, regulatory burden, and margin structure diverge across procurement channels.
Product Type:
Particle engineering specifications and bioavailability requirements differentiate product categories, with spray-drying parameters and encapsulation technology driving functional performance.
- Vitamins:Dry homogeneous blends of fat-soluble and water-soluble compounds manufactured through spray-drying or microencapsulation to achieve thermal stability. Demand concentrates in food fortification programs across India, where FSSAI mandates for wheat flour and rice fortification are pulling procurement volume toward domestic manufacturing clusters.
- Minerals:Trace element salts and chelated compounds engineered for dispersion uniformity in food matrices. Healthcare institutions in Germany and the Netherlands are expanding procurement of mineral-enriched clinical nutrition protocols, compressing lead times for premix suppliers with EFSA-registered dossiers.
- Herbs:Standardized botanical extracts with defined marker compound concentrations for nutraceutical applications.
- Amino Acids:Fermentation-derived or synthetic protein building blocks for sports nutrition and clinical recovery formulations.
Vitamins lead on scale; amino acids lead on momentum.
Application:
Regulatory pathway complexity and margin capture potential fragment the application landscape, with institutional procurement contrasting sharply with direct-to-consumer channels.
- Food Fortification:Large-volume blending of micronutrients into staple commodities to address population-level deficiency. India's government-mandated rice and wheat fortification programs are absorbing substantial premix capacity, with CDSCO oversight tightening quality benchmarks for both domestic producers and importers.
- Nutritional Supplements:Precision-dosed powders for direct consumption or reconstitution, commanding superior margins through subscription e-commerce models. North American brands are bypassing traditional distribution hierarchies, capturing value that previously accrued to pharmacy and supermarket intermediaries.
- Animal Feed:Species-specific premixes for livestock productivity optimization, governed by veterinary feed directive compliance.
- Cosmetics:Mineral and vitamin powders for topical formulation, where particle size distribution affects sensory performance and shelf stability.
Food fortification dominates volume throughput; nutritional supplements dominate margin extraction.
End User:
Procurement sophistication and technical specification rigor vary sharply across buyer categories, from hospital pharmacy committees to cosmetic formulators.
- Healthcare Institutions:Hospital and long-term care facilities requiring enteral feeding protocols with documented bioequivalence. European procurement teams are consolidating supplier relationships toward vertically integrated producers with captive fermentation capacity and REACH-registered substance dossiers.
- Nutraceutical Companies:Brands developing direct-to-consumer supplement lines, prioritizing rapid product iteration under DSHEA framework clarity.
- Food Manufacturers:Industrial buyers integrating fortification into processed food production, subject to FSSAI or FDA compliance verification.
- Cosmetic Brands:Formulators sourcing mineral powders for color cosmetics and skincare, where particle morphology determines product aesthetics.
Healthcare institutions anchor contract stability; nutraceutical companies anchor growth velocity.
Distribution Channel:
Channel selection determines margin retention, customer data access, and regulatory exposure for micronutrient powder brands.
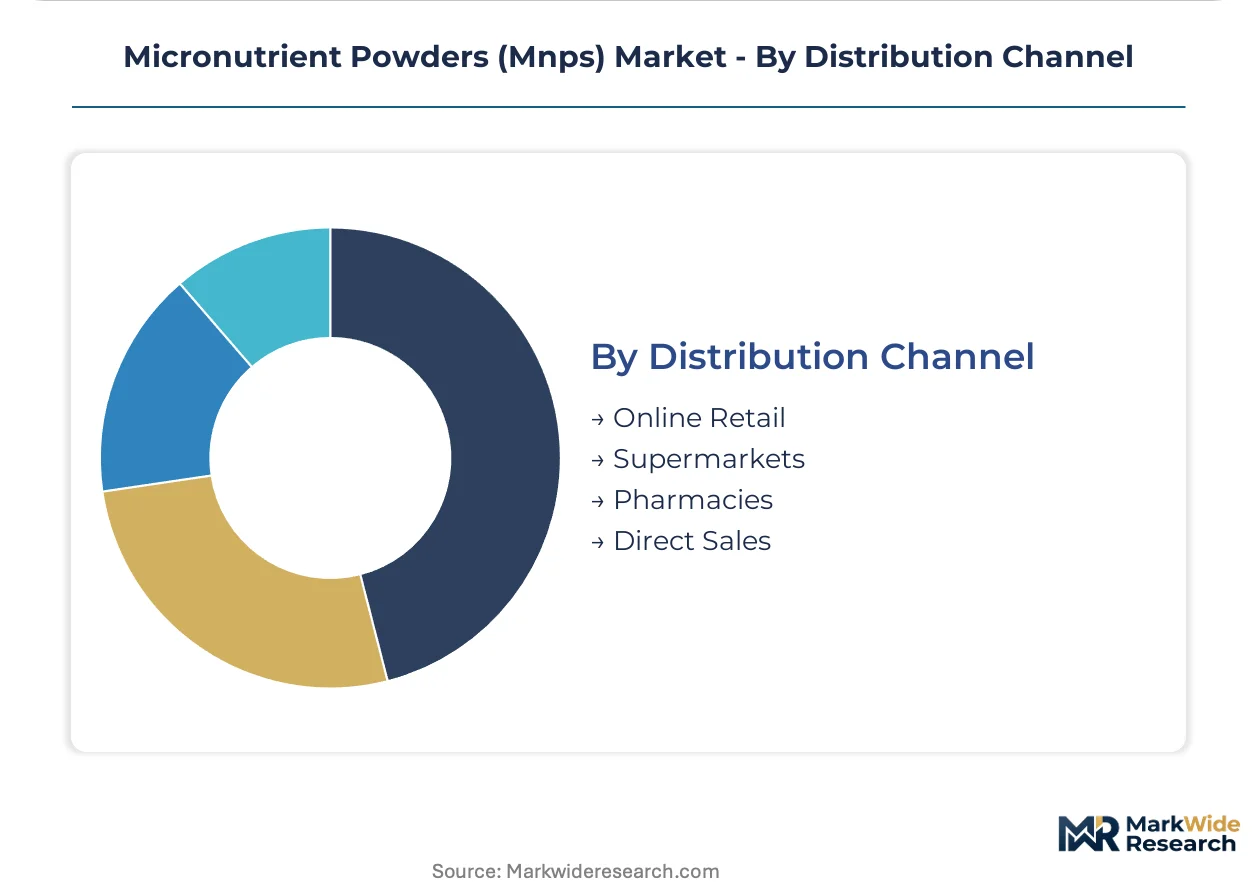
- Online Retail:Direct-to-consumer platforms and subscription models enabling rapid product iteration and pricing power. North American and Western European markets concentrate here, where regulatory clarity under DSHEA and food supplement directives supports digital-native brand building.
- Supermarkets:Mass-market retail placement for fortified food products and consumer supplement lines.
- Pharmacies:Professional recommendation channel for clinical-grade formulations, particularly in European markets with pharmacist-controlled distribution traditions.
- Direct Sales:B2B supply relationships for industrial food manufacturers and healthcare institutional procurement.
Direct sales capture institutional volume; online retail captures margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial micronutrient fortification originated in post-war Europe and North America, where government-mandated food enrichment programs established the technical and regulatory foundations that now govern global trade in vitamin and mineral premixes.
India
FSSAI fortification mandates for wheat flour and rice are absorbing substantial domestic premix capacity, while CDSCO oversight tightens quality benchmarks for clinical nutrition imports. The PLI scheme for pharmaceutical and nutraceutical manufacturing attracts capital toward domestic micronutrient production clusters in Gujarat and Maharashtra.
Germany
Healthcare institutions in Bavaria and North Rhine-Westphalia expand procurement of mineral-enriched clinical nutrition protocols, compressing lead times for suppliers with EFSA-registered dossiers. REACH substance registration requirements harden cross-border trade patterns, favoring vertically integrated producers with captive fermentation capacity.
United States
DSHEA regulatory clarity enables rapid product iteration for direct-to-consumer nutritional supplement brands, with subscription e-commerce models capturing margin previously accruing to pharmacy intermediaries. FDA cGMP compliance elevates barrier costs for new entrants in the premix manufacturing segment.
Netherlands
European premix manufacturing capacity clusters around Rotterdam and Amsterdam, creating geographic concentration risk for logistics disruptions. EFSA novel food authorization timelines extend lead times for innovative micronutrient forms, pushing food manufacturers toward consolidated supplier relationships.
Brazil
ANVISA oversight of nutritional supplements tightens import quality benchmarks, while domestic food fortification programs expand procurement of vitamin premixes for wheat and corn flour. São Paulo-based nutraceutical manufacturers develop regional distribution networks serving Latin American markets.
Micronutrient Powders (Mnps) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and captive fermentation capacity, with REACH-registered dossiers and EFSA novel food approvals serving as the primary tiering mechanism. The vendor base organizes into three strategic archetypes: multinational chemical conglomerates with backward integration into vitamin synthesis, specialized clinical nutrition formulators, and direct-to-consumer supplement brands leveraging digital distribution. Dominant competitive moves include geographic expansion into Indian manufacturing clusters and technology licensing for microencapsulation processes.
Within the multinational chemical tier, DSM and BASF SE exemplify archetypes built on fermentation-based production and European premix manufacturing dominance. Maternova occupies a distinct position as a specialist in maternal health formulations, differentiating within narrow clinical niches where regulatory compliance and formulation precision command pricing power. These three anchors illustrate how competitive positioning fragments across scale-driven supply security and indication-specific clinical validation.
| Leading Market Players |
|---|
| DSM |
| BASF SE |
| Maternova |
| Piramal Pharma Solutions |
| Amway |
| Herbalife Nutrition |
| Nature's Bounty |
| GNC |
| USANA Health Sciences |
| Others |
Pricing and Supply Chain Analysis
Backward integration into fermentation-based vitamin production anchors supply security and pricing power for European and North American premix manufacturers. DSM and BASF SE leverage captive feedstock access to buffer margin compression from volatile petrochemical-derived precursor markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade enteral formulations from food fortification premixes and commodity mineral blends. Price differentiation hinges on EFSA novel food authorization status and REACH-registered dossier completeness. Cost compression in standard-tier food fortification premixes is intensifying because Indian domestic manufacturing capacity expansion under PLI schemes introduces volume competition. Healthcare institutions exhibit lowest price sensitivity due to enteral feeding protocol compliance requirements, while commodity food manufacturers face acute margin pressure.
Supply Chain Analysis
Formulation scientists with microencapsulation expertise concentrate in German technical centers around Frankfurt and Swiss pharmaceutical clusters near Basel. Manufacturing capacity draws from vitamin precursor supply anchored in Chinese fermentation facilities and Indian mineral salt processing hubs. Single-source vulnerability runs through Rotterdam-Amsterdam logistics corridors for European premix distribution. Distribution runs through direct B2B relationships for institutional procurement and subscription e-commerce platforms for nutritional supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Micronutrient Powders Market functions as a stable compounder, with government fortification mandates in India and EU Green Deal compliance requirements generating predictable procurement volume.
For Market Incumbents: Deploy certification depth as the primary defensive lever. Deepen EFSA novel food authorization portfolios and REACH-registered substance dossiers to extend lead times for challenger brands. Expand captive fermentation capacity in Gujarat and Maharashtra manufacturing clusters to neutralize Indian PLI scheme incentives attracting new domestic entrants. Channel control through hospital system partnerships compresses substitution risk for clinical nutrition protocols. For New Entrants and Emerging Players: Begin with maternal health formulations for sub-Saharan African markets, where clinical nutrition protocols remain underpenetrated and regulatory barriers favor specialized indication expertise over scale economics. Target sports nutrition amino acid powders for direct-to-consumer subscription models in North American markets, where DSHEA framework clarity enables rapid product iteration without lengthy FDA pre-approval cycles. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap clinical nutrition formulators because EFSA authorization timelines and microencapsulation expertise scarcity create durable moats against commoditization. Focus acquisition screening on targets with REACH-registered vitamin portfolios and established hospital procurement relationships. Watch for Indian PLI scheme capacity absorption rates as the signal indicating inflection in regional pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Authorization | REACH-registered dossier completion precedes European market access for innovative micronutrient forms. |
| Backward Integration into Fermentation | Captive vitamin synthesis capacity insulates margin from petrochemical precursor volatility. |
| India Manufacturing Cluster Expansion | PLI scheme incentives attract capital toward Gujarat and Maharashtra premix production facilities. |
| Microencapsulation Technology Licensing | Spray-drying expertise for 50-200 micron uniformity commands premium in clinical nutrition applications. |
| Direct-to-Consumer Channel Development | Subscription e-commerce models capture margin previously accruing to pharmacy and supermarket intermediaries. |
Research Methodology
Coverage spans India, Germany, the United States, the Netherlands, and Brazil, with primary inputs from each market informing demand segmentation and regulatory pathway analysis. The research combines structured interviews with premix manufacturing plant managers, hospital procurement committee members, FSSAI regulatory affairs leads, and nutraceutical brand development executives with secondary validation from CDSCO filing databases, EFSA novel food authorization registers, FDA cGMP inspection records, and customs trade flow data. Bottom-up volume triangulation across application segments and top-down value reconciliation anchor the analytical framework.
Rate-of-change decomposition separates volume growth from price evolution and mix shift effects across the projection horizon. The forecast framework models micronutrient powder demand across product type, application, end user, and distribution channel dimensions, with additional segmentation by regional regulatory cluster and bioequivalence requirement tier. CAGRs derive from regression analysis of historical procurement patterns against fortification mandate implementation timelines and fermentation capacity expansion schedules.
Several conditions sit outside the modeled scope, including abrupt regulatory reclassification of synthetic versus naturally derived micronutrient forms, trade restriction imposition on vitamin precursor imports, and bioequivalence standard harmonization across FDA, EFSA, and CDSCO jurisdictions. Forecasts reflect documented assumptions regarding PLI scheme continuation and EU Green Deal enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Enteral Nutrition Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Omega 3 Supplements Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Global Collagen Peptides Market
Nutritional Supplements
Melatonin Supplements Market
Nutritional Supplements
Camu Camu Extract Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Global Nutraceuticals Product Market
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Natural Immune Booster Market
Nutritional Supplements
Europe Feed Prebiotics Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
United States Vitamin D Supplements Market