
 Lithuania E-Commerce Market | 2026-2036
Lithuania E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Lithuania E-Commerce Market Foresight
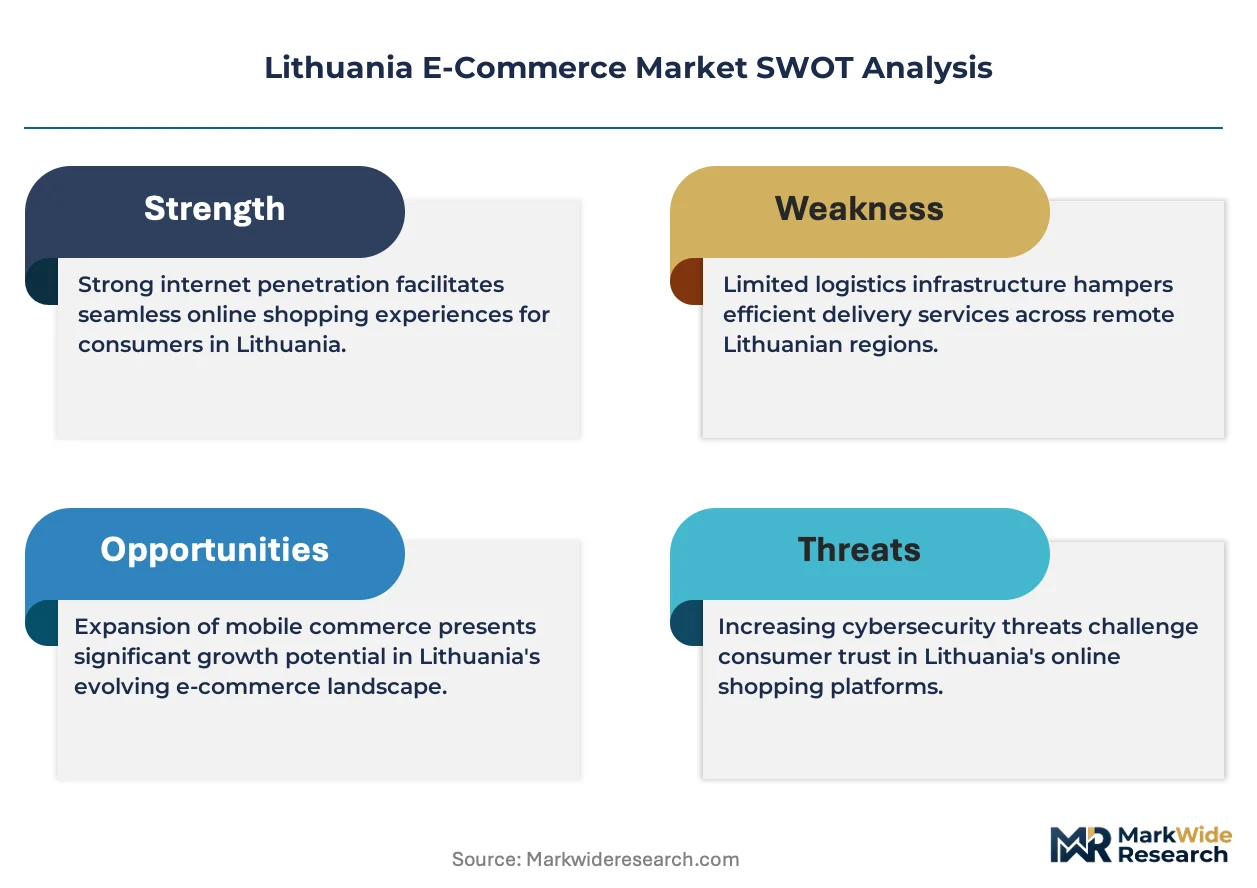
Multi-source platform strategies is repositioning how Lithuanian retailers build digital inventory networks. UAB Pigu leverages its domestic fulfillment footprint to compete on delivery speed against pan-European entrants. Vinted UAB anchors the secondhand fashion segment with peer-to-peer logistics infrastructure that sustains low operational overhead. Kesko Senukai Digital UAB specializes in home improvement SKUs, occupying a defensible niche against generalist marketplaces.
Lithuania e-commerce encompasses digitally mediated transactions for goods and services executed through web-based interfaces and mobile applications, relying on encrypted payment gateways and API-integrated inventory management systems to coordinate order fulfillment. Its primary commercial purpose is to reduce friction between distributed suppliers and geographically dispersed buyers through automated checkout, real-time stock visibility, and last-mile routing algorithms. Electronics and fashion command the dominant transaction volumes, with electronics benefiting from higher average order values and fashion driven by return-rate optimization challenges that shape margin structures. Online marketplaces aggregate demand most efficiently, while mobile apps represent the fastest-growing sales channel as smartphone penetration deepens across age cohorts.
The Bank of Lithuania supervises payment service compliance under EU PSD2 frameworks, while the State Data Protection Inspectorate enforces GDPR-aligned consumer privacy standards that constrain data-driven personalization tactics. National tax administration rules on cross-border VAT collection create compliance thresholds that filter smaller cross-border sellers from sustained market participation. Stakeholders must monitor how forthcoming EU digital platform regulations reshape liability distributions between marketplace operators and third-party vendors.
Market Dynamics
PSD2-mandated open banking infrastructure is restructuring payment flows across Lithuanian digital commerce, forcing marketplace operators to rebuild checkout architectures around third-party provider APIs rather than proprietary gateways.
Growth Catalysts
- EU Payment Services Directive:Open banking APIs reduce transaction friction for cross-border purchases, expanding merchant access to EU-wide consumer bases without proprietary payment infrastructure investments.
- Vilnius logistics clustering:Concentrated last-mile fulfillment networks in the capital region compress delivery windows to under 24 hours for electronics and fashion categories.
- Mobile wallet penetration:Smartphone-native payment adoption among 25-34 year-old cohorts is displacing card-on-file checkout, reducing cart abandonment at payment gateways.
Market Restraints
- Cross-border VAT compliance:Lithuanian State Tax Inspectorate thresholds for distance selling create administrative burdens that filter sub-scale merchants from sustained EU market participation.
- Warehouse labor scarcity:Fulfillment center staffing in Kaunas County faces competition from manufacturing and shared service centers, inflating per-unit picking costs.
- Return logistics density:Fashion category return rates of 25-35 percent strain reverse logistics networks, compressing net margins on apparel SKUs below electronics benchmarks.
Strategic Opportunities
- Klaipėda port corridor:Underutilized Baltic Sea logistics infrastructure offers cross-border fulfillment arbitrage for merchants targeting Scandinavian consumer bases with shorter maritime transit than road freight through Poland.
- GDPR-compliant personalization:First-party data architectures built around explicit consent mechanisms enable recommendation engines that bypass third-party cookie deprecation.
- Live commerce integration:Real-time video shopping formats on TikTok and Instagram are converging with native checkout, opening direct-to-consumer channels outside marketplace commission structures.
Industry Challenges
- API integration complexity:Legacy inventory management systems in mid-market retail require middleware development to synchronize stock visibility across marketplace, own-site, and social commerce channels.
- Data localization compliance:State Data Protection Inspectorate enforcement of GDPR Article 44 transfer mechanisms creates architectural constraints for merchants using non-EU cloud infrastructure for customer analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithuania E-Commerce Market |
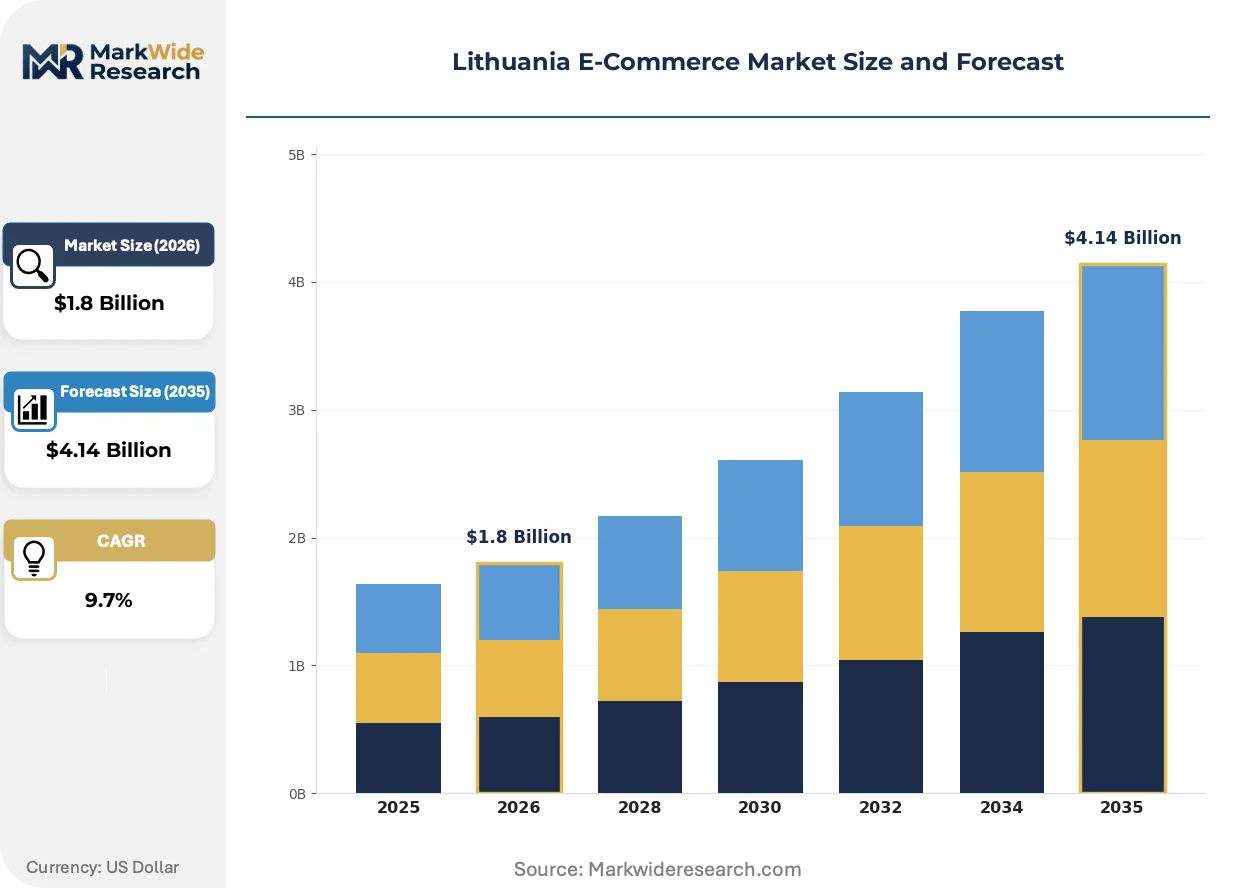
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Fashion, Home Goods, Beauty Customer Type: Individual Consumers, Small Businesses, Corporates, Non-Profits Sales Channel: Online Marketplaces, Brand Websites, Social Media, Mobile Apps Payment Method: Credit Cards, E-Wallets, Bank Transfers, Cash on Delivery |
| Companies Covered | UAB Pigu, Kesko Senukai Digital UAB, UAB Varle, UAB Barbora, Vinted UAB, Maxima LT UAB, Rimi Lietuva UAB, IKEA Lithuania, Zalando SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithuania E-Commerce Market Shifts & Advancements
Artificial intelligence is restructuring three operational layers of Lithuanian e-commerce: payment authentication, inventory forecasting, and customer service automation. These shifts compress decision cycles and alter competitive positioning between domestic operators and pan-European entrants.
Machine learning-based fraud detection is converging with behavioral biometrics at checkout, analyzing typing cadence and device interaction patterns to authenticate transactions without SMS one-time passwords. Lithuanian fintech integrators are deploying these stacks for marketplace clients seeking PSD2 Strong Customer Authentication compliance with reduced friction. The technology is compressing false-decline rates on cross-border purchases, directly recovering revenue previously lost to conservative risk scoring.
The EU Digital Services Act creates new liability frameworks for marketplace operators hosting third-party vendors, requiring algorithmic transparency in product ranking and expanded consumer redress mechanisms. Lithuanian platforms must restructure vendor onboarding to document product safety compliance and establish in-country legal representatives. Fashion and electronics aggregators face the steepest operational reconfiguration, as these categories concentrate the highest third-party seller volumes and associated dispute exposure.
Subscription-based replenishment models are displacing one-off purchasing in household consumables and pet care categories, locking consumer lifetime value through automated reorder cycles. Lithuanian grocery and specialty retailers are piloting these formats through mobile apps with flexible pause mechanisms. Kaunas and Vilnius urban districts show the highest adoption density, correlating with dual-income household penetration and delivery subscription willingness.
Lithuania E-Commerce Market Segmentation
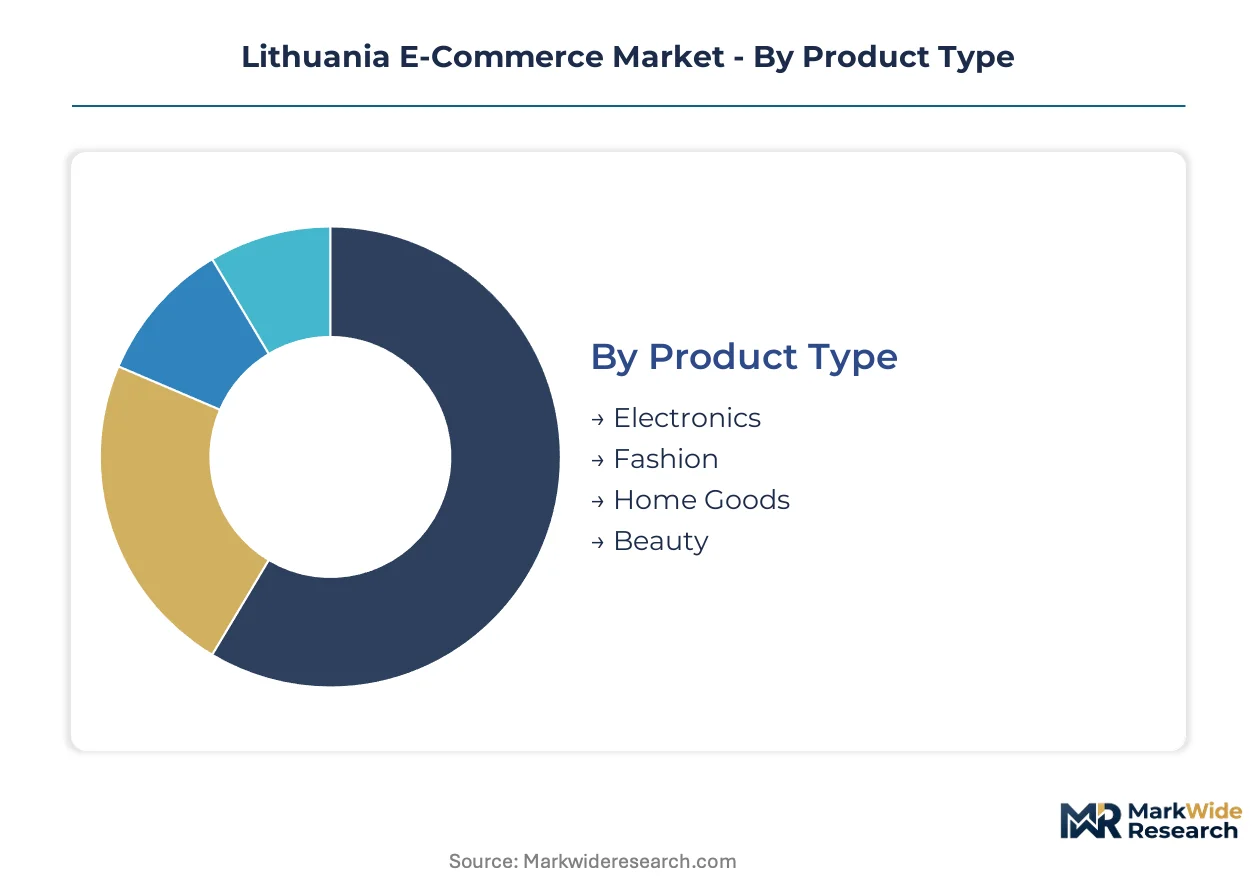
Lithuanian e-commerce operators configure inventory and fulfillment infrastructure around distinct demand profiles. Segment boundaries determine warehouse location, payment gateway selection, and last-mile routing priorities across Vilnius and Kaunas logistics clusters.
Product Type:
Technology specifications and SKU complexity differentiate fulfillment requirements across merchandise categories.
- Electronics:High-value inventory with serialized warranty tracking demands secure storage protocols and insured last-mile delivery. Demand concentrates in Vilnius urban districts where disposable income supports premium average order values and same-day fulfillment willingness.
- Fashion:Size-variant SKUs with elevated return rates require flexible reverse logistics infrastructure and size-exchange processing capabilities. Kaunas County fulfillment centers handle the densest return volumes as fashion merchants optimize for 24-hour replacement cycles.
- Home Goods:Bulky dimensional freight necessitates specialized last-mile carriers with lift-gate capability.
- Beauty:Temperature-sensitive formulations and expiration-date tracking constrain warehouse climate control investments.
Mature deployment sits with Electronics. Newer deployment is concentrated in Beauty.
Customer Type:
Procurement volume and decision-cycle length reshape platform interface design and account management resourcing.
- Individual Consumers:Single-transaction purchasing with mobile-first discovery patterns drives app-native checkout optimization. Vilnius and Kaunas metropolitan areas generate the highest transaction frequency as smartphone penetration deepens across age cohorts.
- Small Businesses:Recurring procurement with negotiated terms requires B2B portal functionality including invoice generation and volume-tiered pricing. Regional cities show accelerating adoption as entrepreneurs seek operational efficiency through digital sourcing.
- Corporates:Multi-approval workflows and consolidated billing demand ERP integration and dedicated account management.
- Non-Profits:Grant-compliant purchasing documentation and tax-exemption handling require specialized checkout modules.
Individual Consumers anchor current infrastructure investment. Small Businesses are expanding most quickly.
Sales Channel:
Traffic acquisition economics and commission structures determine merchant channel mix and inventory allocation.
- Online Marketplaces:Aggregated demand with standardized fulfillment SLAs enables smaller merchants to access national reach without proprietary logistics. Domestic operators leverage local fulfillment footprints to compete on delivery speed against pan-European entrants.
- Brand Websites:Direct consumer relationships with full margin retention require independent traffic generation and customer service investment. Vilnius-based retailers concentrate proprietary site development to build first-party data assets.
- Social Media:Influencer-driven discovery with in-platform checkout reduces friction for impulse categories.
- Mobile Apps:Push-notification re-engagement and biometric payment authentication support subscription and replenishment models.
Online Marketplaces dominate transaction volume. Mobile Apps are gaining share fastest.
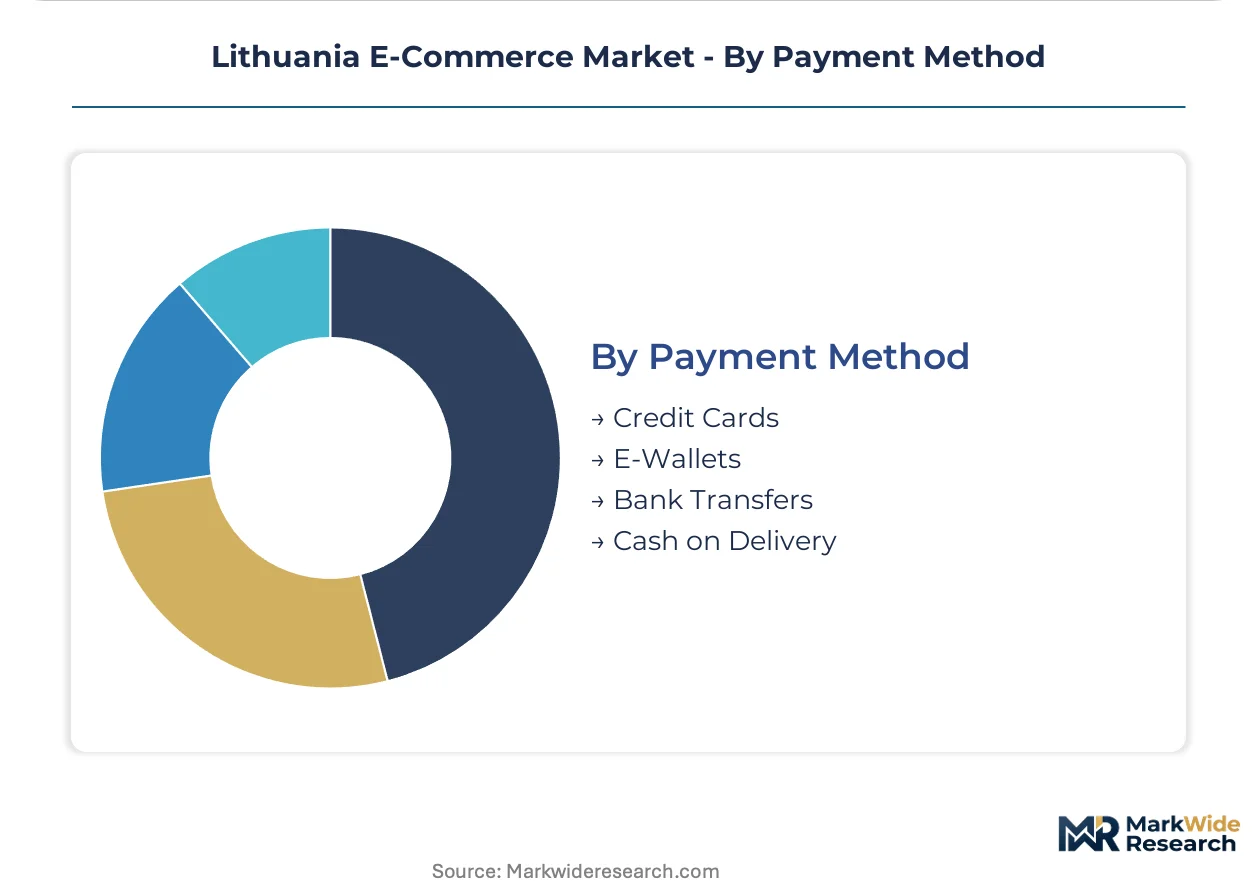
Payment Method:
Settlement speed and fraud exposure influence merchant acceptance preferences and checkout architecture.
- Credit Cards:Chargeback-protected transactions with established dispute resolution dominate cross-border purchases. PSD2-mandated Strong Customer Authentication compliance has forced checkout rebuilds around 3D Secure protocols.
- E-Wallets:Tokenized credentials with one-tap authentication reduce cart abandonment among 25-34 year-old cohorts. Smartphone-native payment adoption is displacing card-on-file storage across urban consumer bases.
- Bank Transfers:Lower interchange costs appeal to high-value B2B transactions with invoice settlement cycles.
- Cash on Delivery:Trust-building mechanism for first-time purchasers in peripheral regions with lower card penetration.
Credit Cards retain the largest transaction share. E-Wallets show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in Lithuania e-commerce clusters around Vilnius and Kaunas metropolitan corridors, where logistics density and disposable income alignment create self-reinforcing fulfillment network effects that compress delivery windows below 24 hours for priority categories.
Vilnius County
Electronics and fashion transaction volumes concentrate in Vilnius urban districts, where premium average order values sustain same-day fulfillment infrastructure investments. The State Data Protection Inspectorate enforces GDPR-aligned consent mechanisms for data-driven personalization engines deployed by domestic marketplace operators. Tech talent pools in the capital region support in-house development of API-integrated inventory management systems that synchronize stock visibility across channels.
Kaunas County
Fashion category return volumes peak in Kaunas fulfillment centers, where 24-hour replacement cycle optimization drives warehouse location decisions for apparel merchants. Warehouse labor scarcity here intensifies competition with manufacturing and shared service centers, inflating per-unit picking costs relative to Vilnius benchmarks. The Kaunas logistics cluster specializes in reverse logistics infrastructure for size-variant SKU processing.
Klaipėda County
Cross-border fulfillment arbitrage opportunities target Scandinavian consumer bases through underutilized Baltic Sea port infrastructure, offering shorter maritime transit than road freight routing through Poland. The Bank of Lithuania supervises payment service compliance for merchants leveraging this corridor for EU-wide consumer access. Klaipėda's maritime connectivity remains underdeveloped relative to its theoretical transit time advantages.
Šiauliai County
Peripheral region demand exhibits lower card penetration and higher cash-on-delivery preference, requiring trust-building checkout mechanisms for first-time purchaser conversion. State Tax Inspectorate distance selling thresholds filter sub-scale cross-border sellers from sustained market participation in these lower-density postal codes. Local entrepreneurs accelerate small business procurement through digital channels as operational efficiency seeking displaces traditional sourcing patterns.
Lithuania E-Commerce Market Competitive Landscape
Delivery speed investment dominates the current landscape as domestic operators rebuild fulfillment architectures to compete with pan-European entrants. The market structures around a consolidated tier of multi-category marketplaces and a fragmented long tail of specialized vertical players. Three archetypes anchor competitive positioning: domestic fulfillment-heavy generalists, peer-to-peer logistics-native secondhand platforms, and defensible niche specialists in home improvement SKUs. M&A activity and proprietary logistics network expansion constitute the dominant competitive moves, with smaller operators seeking scale through strategic partnerships rather than capital-intensive capacity builds.
Within the domestic fulfillment archetype, UAB Pigu and Kesko Senukai Digital UAB exemplify operators leveraging local warehouse footprints to compress delivery windows against international competitors. Vinted UAB occupies a distinct position in the peer-to-peer logistics tier, where low operational overhead structures sustain margin profiles unavailable to inventory-heavy models. These three entities collectively represent the strategic diversity through which Lithuanian e-commerce operators defend market position against pan-European marketplace entrants with superior technology stacks but inferior last-mile density.
| Leading Market Players |
|---|
| UAB Pigu |
| Kesko Senukai Digital UAB |
| UAB Varle |
| UAB Barbora |
| Vinted UAB |
| Maxima LT UAB |
| Rimi Lietuva UAB |
| IKEA Lithuania |
| Zalando SE |
| Others |
Supply & Pricing Matrix
Last-mile fulfillment labor costs in Kaunas County flow downstream into three distinct pricing tiers for Lithuanian e-commerce consumers. Electronics merchants absorb premium same-day delivery premiums through higher average order values, while fashion retailers offset elevated return-processing costs through dynamic pricing algorithms that adjust for reverse logistics density.
Pricing Analysis
Volume concentration in electronics and fashion splits margin structures across the Lithuanian market. Three-tier pricing separates premium same-day delivery from standard 24-48 hour windows and economy 3-5 day postal options, with Vilnius urban consumers showing lowest price sensitivity for speed guarantees. Price differentiation hinges on delivery velocity and return-policy flexibility, with fashion category margins compressing under 25-35 percent return rates. Cost compression in apparel fulfillment is intensifying because warehouse labor scarcity in Kaunas inflates per-unit picking costs relative to electronics benchmarks. Small business procurement segments exhibit highest price sensitivity, while individual consumers in metropolitan corridors prioritize convenience over absolute cost minimization.
Supply Chain Analysis
EU Digital Services Act compliance requirements are reshaping vendor onboarding costs for marketplace operators sourcing inventory across Lithuanian fulfillment networks. Geographic supply concentration draws from Poland, Germany, and domestic Vilnius-Kaunas logistics clusters for last-mile capacity, with cross-border electronics inventory resting on centralized EU distribution hubs. Raw material dependencies include packaging materials, temperature-controlled warehousing infrastructure, and API-integrated inventory management systems. Single-source vulnerability concentrates in Kaunas County fulfillment labor pools competing with manufacturing and shared service centers. Distribution runs through hub-and-spoke models anchored in Vilnius with Kaunas return-processing satellites and Klaipėda maritime corridor access for Scandinavian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warehouse labor scarcity in Kaunas County functions as the binding capacity constraint sustaining fulfillment pricing power across the Lithuanian e-commerce market. This bottleneck limits same-day delivery expansion and protects margin structures for operators with secured staffing pools.
For Market Incumbents: Hedge against pan-European marketplace entrants by deepening proprietary logistics density in Vilnius and Kaunas corridors before labor competition intensifies. Secure long-term warehouse staffing contracts to lock in per-unit picking costs against manufacturing sector wage pressure. Invest in automated sorting infrastructure to reduce dependency on scarce fulfillment labor pools. For New Entrants and Emerging Players: Begin with underpenetrated small business procurement segments in Šiauliai County and peripheral regions where cash-on-delivery trust-building mechanisms still dominate. Target B2B portal functionality gaps left by consumer-focused incumbents. Deploy mobile-first discovery with invoice-generation capabilities to capture entrepreneur operational efficiency demand. For Investors and Strategic Acquirers: Klaipėda port corridor utilization rates crossing threshold maritime volume is the leading indicator that cross-border fulfillment arbitrage strategies are achieving scale. Long-term viability favors operators with integrated domestic warehousing and GDPR-compliant first-party data architectures. Acquisition target archetype: niche vertical specialists in home improvement or beauty with defensible SKU complexity and established vendor compliance documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Fulfillment Network Expansion | Same-day delivery density in Vilnius locks consumer preference against pan-European entrants with inferior last-mile coverage. |
| GDPR-Compliant Personalization Engine | First-party consent architectures enable recommendation systems that bypass third-party cookie deprecation under State Data Protection Inspectorate oversight. |
| Live Commerce Platform Integration | TikTok and Instagram native checkout opens direct-to-consumer channels outside marketplace commission structures for impulse categories. |
| Automated Return Processing Infrastructure | Kaunas-based reverse logistics specialization compresses 24-hour replacement cycles for fashion category margin recovery. |
| Klaipėda Maritime Corridor Development | Baltic Sea freight optimization reduces Scandinavian market transit times below Polish road routing alternatives. |
Research Methodology
EU regulatory filings, Bank of Lithuania payment service reports, and State Data Protection Inspectorate enforcement records formed the secondary backbone for compliance and infrastructure assessment. Primary interviews with marketplace operations directors, logistics warehouse managers, fintech integration specialists, and retail procurement officers supplied operational ground-truth on fulfillment cost structures and labor market dynamics. Bottom-up and top-down triangulation reconciled merchant transaction data with national payment flow aggregates.
Bottom-up modeling of SKU-level transaction economics across product categories was cross-checked against top-down national e-commerce value estimates. Segmentation dimensions included product type, customer archetype, sales channel, and payment method across the modeling period. CAGRs were derived from trend extrapolation of mobile wallet penetration curves and logistics capacity expansion timelines. Forecast inputs incorporated PSD2 open banking adoption rates and EU Digital Services Act implementation phasing.
Underlying measurement precision varies by segment; electronics and fashion carry tighter precision than emerging beauty and home goods categories due to established reporting conventions. Forecasts reflect assumptions on regulatory enforcement intensity and cross-border VAT threshold stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
B2C E-Commerce Market
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
North America B2B E-Commerce Market
E-Commerce Solutions
India E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
Malaysia E-Commerce Market
E-Commerce Solutions
Europe Dropshipping Market
E-Commerce Solutions
T-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market
E-Commerce Solutions
Estonia E-Commerce Market