
 B2C E-Commerce Market | 2026-2036
B2C E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
B2C E-Commerce Market Intelligence
Subscription-based replenishment services is rebalancing what consumers purchase repeatedly versus what they discover episodically. Amazon.com, Inc. leverages its Prime ecosystem to lock in recurring grocery and personal care purchases. Alibaba Group Holding Limited anchors its growth through integrated membership tiers spanning entertainment, logistics, and financial services. JD.com, Inc. differentiates via captive warehouse networks that guarantee same-day delivery for subscribers.
B2C E-Commerce denotes the digital retailing of finished goods directly to individual end consumers through web-based storefronts, mobile applications, and social commerce interfaces, typically requiring encrypted payment gateways, inventory management systems, and last-mile fulfillment orchestration to complete transactions. Its primary commercial purpose is to disintermediate traditional wholesale and physical retail layers, compressing margin capture into platform operators and brand owners while expanding consumer choice beyond geographic constraints. Clothing and electronics dominate transaction volumes, though margin pools are deepest in direct-to-consumer channels where brands bypass marketplace fees. Social media commerce represents the fastest-growing sales channel, particularly among Gen Z and millennial cohorts who discover products through algorithmic feeds rather than search-driven intent.
The US FTC scrutinizes subscription cancellation friction and dark pattern design, compelling platforms to simplify termination flows. China's SAMR enforces anti-monopoly provisions against dominant platforms, reshaping how marketplaces structure merchant exclusivity and promotional pricing. The EU Digital Services Act imposes transparency obligations on algorithmic recommendation systems, affecting how products surface to European consumers. Stakeholders must monitor whether regulatory divergence between Washington, Brussels, and Beijing fragments platform operating models into geography-specific compliance architectures.
Market Dynamics
Algorithmic personalization engines are compressing the path from product discovery to purchase, reconfiguring how inventory turns and customer lifetime value accrues across digital storefronts.
Growth Catalysts
- Generative AI product staging:Automated image generation and description optimization reduce content production costs for marketplace sellers, accelerating SKU velocity.
- India's ONDC protocol:The open network for digital commerce breaks platform lock-in, enabling direct seller-buyer transactions outside walled-garden marketplaces.
- Embedded finance integration:Buy-now-pay-later rails from Brazil to Indonesia convert browsing intent into completed transactions at checkout.
Market Restraints
- Cross-border logistics cost volatility:Container rate fluctuations and fuel surcharges erode margin on international shipments, particularly for low-weight, high-cube goods.
- Payment processor concentration:Three providers dominate card-not-present transaction rails in North America, extracting fixed-percentage fees that scale with gross merchandise value.
- Data localization mandates:Indonesia's GR 71/2019 and Vietnam's Cybersecurity Law require domestic server placement, fragmenting cloud infrastructure spend.
Strategic Opportunities
- Vietnam's emerging middle-class corridors:Ho Chi Minh City and Hanoi show underpenetrated apparel and electronics categories relative to regional peers.
- Live-stream commerce infrastructure:Converging short-form video and real-time payment settlement creates new conversion funnels outside traditional search.
- EU Digital Product Passport mandate:Circularity disclosure requirements favor platforms with pre-built supply chain traceability, creating compliance-based differentiation.
Industry Challenges
- Last-mile labor scarcity:Gig-economy delivery pools face retention pressure as alternative service-sector wages rise in urban logistics corridors.
- Legacy ERP integration friction:Merchants operating on decades-old inventory systems struggle to synchronize stock levels across multiple marketplace APIs in real time.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | B2C E-Commerce Market |
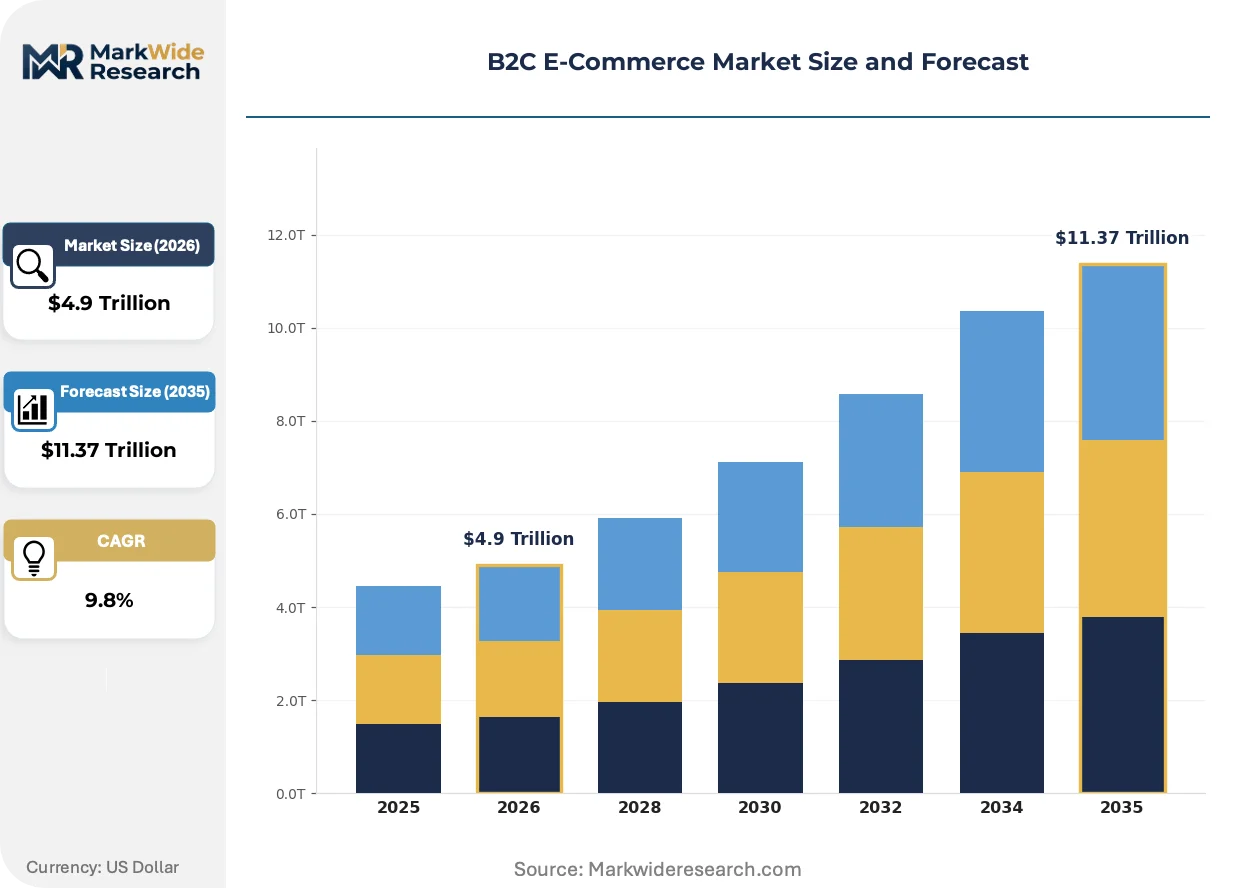
| Market Size in 2026 | $4.9 Trillion |
| Market Size in 2035 | $11.37 Trillion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Electronics, Home Goods, Personal Care Sales Channel: Direct-to-Consumer, Marketplaces, Social Media, Mobile Apps Payment Method: Credit Card, PayPal, Mobile Wallets, Bank Transfer Customer Type: Millennials, Gen Z, Baby Boomers, Professionals |
| Companies Covered | Amazon.com, Inc., Alibaba Group Holding Limited, Walmart, eBay Inc., JD.com, Inc., Rakuten Group, Inc., Shopee, MercadoLibre SRL, Zalando, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
B2C E-Commerce Market Strategic Shifts & Innovations
Commerce interfaces are migrating from destination websites to ambient discovery layers embedded in social feeds, messaging apps, and connected devices.
Conversational commerce interfaces are absorbing routine purchase decisions through voice and chat modalities. Households with smart speakers now reorder consumables through natural-language prompts rather than visual browsing. This interface shift is compressing brand consideration cycles and privileging private-label goods with simple phonetic signatures.
The EU Digital Services Act imposes transparency obligations on algorithmic recommendation systems, forcing platforms to disclose ranking parameters to European sellers. Merchants must now optimize for explainable signals rather than opaque engagement metrics. Fashion and electronics categories face the steepest compliance adaptation curves.
Subscription fatigue is triggering unbundling behaviors among millennial cohorts who audit recurring charges quarterly. Single-purpose memberships face cancellation pressure while bundled super-apps retain stickiness through cross-category lock-in. This pattern concentrates in Southeast Asian urban markets where mobile wallet ecosystems bundle transport, food, and retail.
B2C E-Commerce Market Segmentation
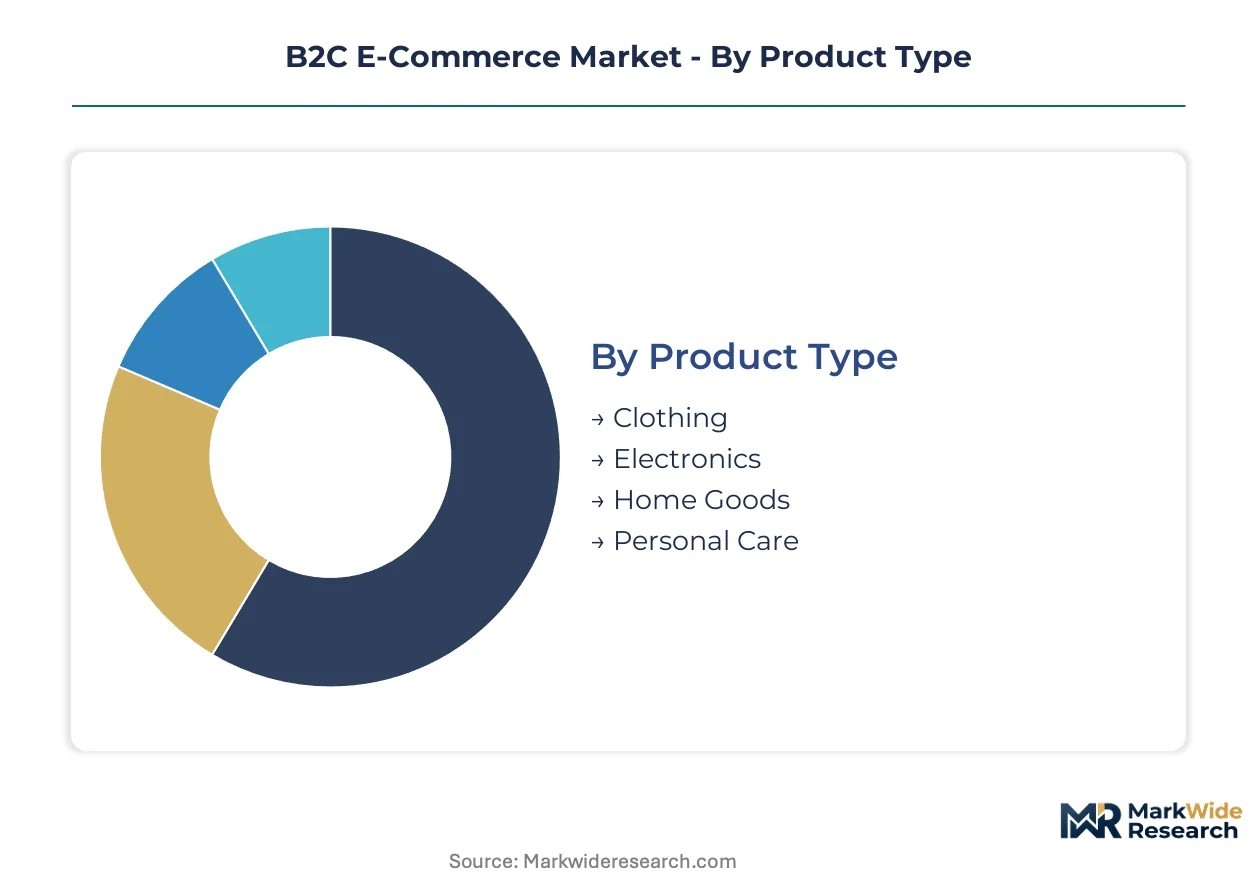
Segmentation in B2C E-Commerce reveals how transaction value pools shift across interface types and demographic cohorts. Understanding these divisions exposes where margin capture concentrates versus where volume scales.
Product Type:
Electronics commands premium pricing while clothing drives transaction frequency across mobile interfaces.
- Clothing:Apparel SKUs exhibit the highest return rates in digital commerce, averaging 30-40% of purchases. Demand clusters in Southeast Asian urban corridors where flash-sale mechanics and live-stream try-ons compress decision cycles. Fast-fashion cycles and size inconsistency create persistent logistics friction.
- Electronics:Smartphones, laptops, and accessories carry thin margins but anchor customer acquisition through warranty attachments and financing bundles. China's SAMR enforces strict after-sales service mandates for cross-border sellers, elevating compliance costs for warranty fulfillment.
- Home Goods:Furniture and décor face last-mile delivery constraints due to dimensional weight pricing.
- Personal Care:Replenishment subscriptions lock in recurring revenue with minimal marketing spend.
Today's leader: Electronics. Tomorrow's challenger: Personal Care.
Sales Channel:
Marketplaces aggregate demand while direct channels reclaim margin from platform fees.
- Direct-to-Consumer:Brand-operated storefronts bypass marketplace commissions, capturing full customer data for retention marketing. The US FTC scrutinizes subscription cancellation flows, compelling DTC brands to simplify termination mechanics. First-party data ownership enables predictive replenishment timing.
- Marketplaces:Aggregated traffic and fulfillment infrastructure reduce customer acquisition costs for emerging sellers. China's SAMR anti-monopoly enforcement has dismantled merchant exclusivity clauses, opening multi-homing opportunities. Commission rates of 15-30% erode profitability in commoditized categories.
- Social Media:Algorithmic discovery layers convert browsing into purchase without search intent.
- Mobile Apps:Native applications retain highest session duration through push-notification re-engagement.
Marketplaces dominate transaction volume. Social Media shows steepest expansion trajectory.
Payment Method:
Mobile wallets displace card rails in emerging markets where banking infrastructure lags smartphone penetration.
- Credit Card:North American and European transactions still favor card networks, though interchange fees pressure merchant margins. Three processors dominate card-not-present rails, extracting fixed-percentage cuts that scale with gross merchandise value. Chargeback liability concentrates risk with sellers in cross-border transactions.
- Mobile Wallets:Alipay, GCash, and similar platforms embed credit, loyalty, and identity verification in single interfaces. Indonesia's GR 71/2019 mandates domestic data localization, fragmenting wallet infrastructure across regulatory boundaries. QR-code interoperability is accelerating merchant adoption.
- PayPal:Buyer protection policies reduce conversion friction for first-time cross-border purchases.
- Bank Transfer:Real-time settlement rails gain traction in India through UPI protocol integration.
Credit Card retains checkout dominance. Mobile Wallets are gaining share fastest in Southeast Asia.
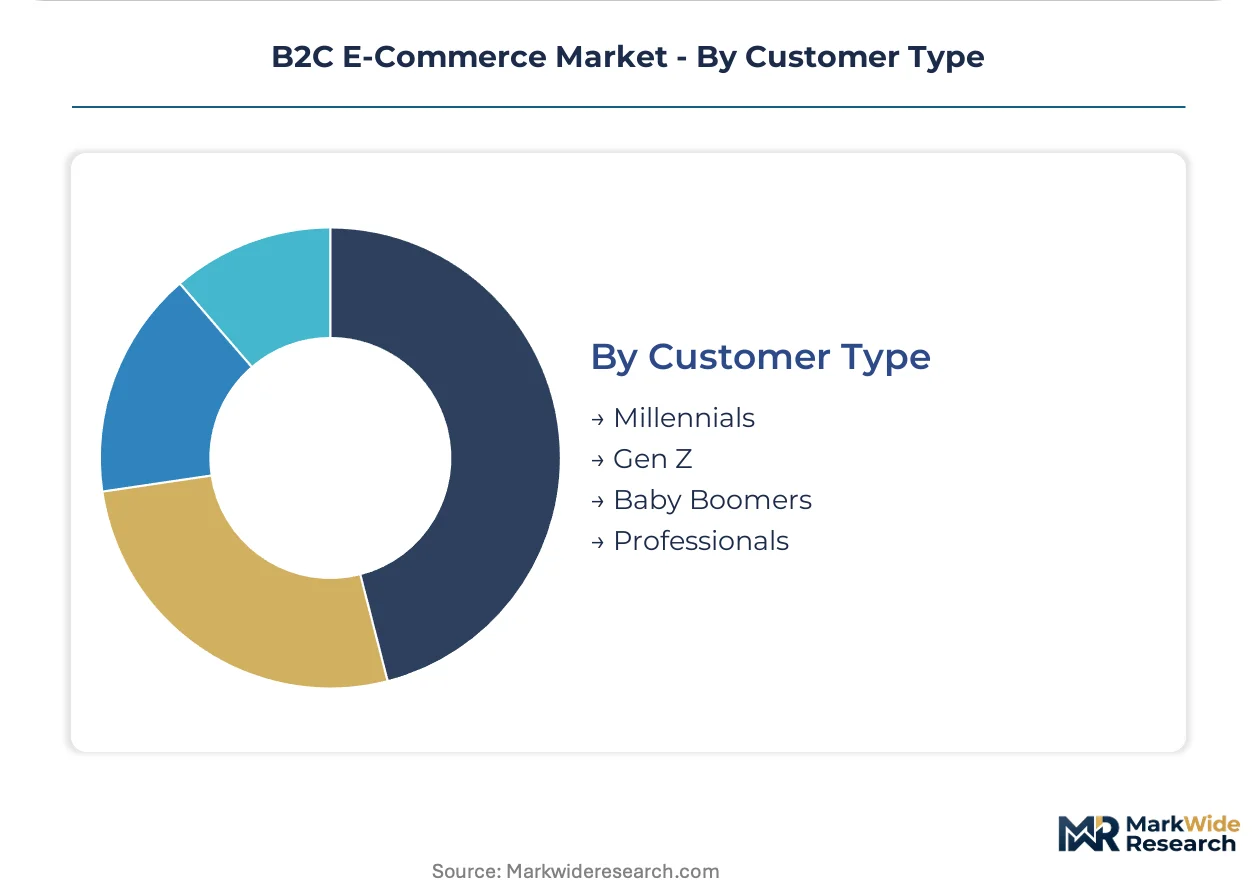
Customer Type:
Generational cohorts diverge sharply in discovery modality and subscription tolerance.
- Gen Z:Native to algorithmic feeds, this cohort discovers products through TikTok and Instagram rather than search engines. Ephemeral content formats drive impulse purchases with minimal comparison shopping. Subscription fatigue manifests earliest here, with quarterly audits of recurring charges.
- Millennials:Balancing career ascent with household formation, this segment concentrates spending in replenishment subscriptions and premium private labels. Southeast Asian urban millennials exhibit highest super-app bundling rates, integrating transport, food, and retail in single wallet ecosystems.
- Baby Boomers:Desktop preference and customer service expectations elevate support costs per transaction.
- Professionals:Time scarcity drives premium positioning for convenience-oriented fulfillment promises.
Millennials anchor current revenue. Gen Z defines emerging interface standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's mobile wallet penetration outpaces Germany's card-based infrastructure by a factor of three, yet both markets face converging regulatory pressure on algorithmic transparency. Subscription fatigue manifests differently across jurisdictions, with Southeast Asian super-apps retaining users through cross-category bundling while North American consumers audit standalone memberships quarterly. The analysis window reveals divergent compliance architectures emerging from Washington, Brussels, and Beijing.
United States
Prime ecosystem lock-in and same-day delivery infrastructure drive replenishment subscription density. The FTC enforces simplified cancellation flows under revived Section 5 authority, compelling platforms to reduce termination friction. Seattle and San Francisco Bay Area logistics corridors face acute last-mile labor scarcity as gig-economy wage floors rise.
China
Live-stream commerce conversion rates exceed traditional search-driven discovery by multiples in apparel and electronics categories. SAMR anti-monopoly enforcement dismantled merchant exclusivity clauses, opening multi-homing opportunities for cross-border sellers. Yangtze River Delta warehouse clusters guarantee same-day fulfillment for tier-one city subscribers.
Germany
Direct-to-consumer brand penetration runs deepest in personal care and sustainable fashion verticals. The EU Digital Services Act imposes algorithmic ranking transparency obligations, forcing merchants to optimize for explainable signals. Berlin and Munich urban corridors show highest super-app bundling tolerance among millennial households.
Vietnam
Ho Chi Minh City and Hanoi exhibit underpenetrated electronics and apparel categories relative to regional peers. Cybersecurity Law data localization mandates fragment cloud infrastructure spend for cross-border platforms. Mobile wallet QR interoperability accelerates merchant adoption in emerging middle-class corridors.
India
UPI real-time settlement rails displace card-not-present dominance in tier-two and tier-three urban centers. ONDC protocol breaks platform lock-in, enabling direct seller-buyer transactions outside walled-garden marketplaces. Bangalore and Delhi-NCR logistics networks face inventory synchronization friction from legacy ERP systems.
B2C E-Commerce Market Key Industry Players
Top-tier vendors anchor marketplace aggregation, while mid-tier specialists occupy vertical niches and regional super-apps capture mobile-first emerging markets. The vendor base stratifies across three tiers: integrated ecosystem operators, category-specific direct-to-consumer platforms, and social commerce infrastructure providers. Two dominant competitive moves are reshaping positioning: captive fulfillment network expansion to guarantee delivery velocity, and embedded finance integration to reduce checkout abandonment. Geographic licensing partnerships and algorithmic personalization licensing represent secondary vectors.
Within the ecosystem-operator tier, Amazon.com, Inc. and Alibaba Group Holding Limited exemplify divergent geographic anchoring strategies, with the former concentrating North American and European Prime density and the latter integrating entertainment, logistics, and financial services across Asian membership tiers. JD.com, Inc. occupies a position emphasizing captive warehouse networks over third-party marketplace aggregation. These three entities represent the dominant archetypes against which regional specialists and emerging super-apps calibrate their competitive responses.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Alibaba Group Holding Limited |
| Walmart |
| eBay Inc. |
| JD.com, Inc. |
| Rakuten Group, Inc. |
| Shopee |
| MercadoLibre SRL |
| Zalando |
| Others |
Cost & Logistics Intelligence
Container freight index volatility cascades through fulfillment economics, compressing margin pools for cross-border sellers while amplifying pricing power for captive warehouse operators in tier-one urban corridors.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for apparel and electronics categories. Three-tier pricing structure across premium, standard, and economy levels segments buyers by delivery velocity and return flexibility. Cost compression in standard tiers stems from payment processor concentration extracting fixed-percentage fees. Small marketplace sellers exhibit highest price sensitivity; Prime-equivalent subscribers show lowest.
Supply Chain Analysis
Regional distribution centers in China's Yangtze River Delta, Germany's Rhine-Ruhr corridor, and India's Delhi-NCR form hub-and-spoke patterns radiating toward dense urban consumption zones. Inventory management systems draw from cloud infrastructure subject to Indonesia's GR 71/2019 data localization mandates. Single-source vulnerability concentrates in last-mile gig-economy labor pools facing retention pressure. Distribution runs through marketplace-operated fulfillment networks and direct-to-consumer captive logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
B2C E-Commerce functions as a stable compounder anchored by subscription renewal mechanics that lock in recurring revenue with minimal marginal acquisition spend.
For Market Incumbents: Extend same-day delivery guarantees into tier-two urban corridors to preempt regional specialists. Build backward integration into warehouse automation to offset last-mile labor scarcity. SAMR anti-monopoly enforcement on merchant exclusivity clauses demands flexible multi-homing strategies. For New Entrants and Emerging Players: Social commerce infrastructure partners offer lowest-friction entry vectors for algorithmic-native Gen Z cohorts. Vietnam's underpenetrated electronics and apparel categories present immediate white-space opportunity. Live-stream commerce tooling enables differentiation without competing on fulfillment velocity. For Investors and Strategic Acquirers: Asymmetric upside sits with vertical logistics specialists possessing pre-built supply chain traceability for EU Digital Product Passport compliance. Five-to-ten-year viability favors platforms with embedded finance integration reducing checkout abandonment. Watch India's ONDC protocol adoption rates as inflection indicator for platform lock-in erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fulfillment Network Expansion | Same-day delivery guarantees in tier-one cities anchor Prime-equivalent subscriber retention against regional challengers. |
| Embedded Finance Integration | Buy-now-pay-later rails from Brazil to Indonesia convert browsing intent into completed transactions at checkout. |
| Algorithmic Personalization Licensing | Transparency obligations under EU Digital Services Act favor explainable recommendation engines over opaque engagement metrics. |
| Geographic Licensing Partnerships | Cross-border seller compliance with China's SAMR after-sales mandates requires localized warranty fulfillment infrastructure. |
| Live-Stream Commerce Infrastructure | Converging short-form video and real-time payment settlement creates conversion funnels outside traditional search discovery. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions engaged marketplace operations executives, logistics network planners, merchant category managers, and mobile wallet product leads. Secondary validation drew from customs trade databases, SEC 10-K filings, SAMR regulatory bulletins, and EU Digital Services Act implementation guidance. Bottom-up SKU velocity analysis and top-down macro consumption trends underwent iterative reconciliation.
Segment-weighting applied differential growth assumptions across product type, sales channel, payment method, and generational cohort dimensions. Modeled variables included subscription renewal rates, cross-border shipment volumes, and mobile wallet penetration curves. CAGRs derived from logistic curve fitting against historical adoption patterns. Inventory synchronization friction from legacy ERP systems and gig-economy wage trajectories informed fulfillment cost projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between Washington, Brussels, and Beijing. Container rate volatility, data localization mandate expansion, and algorithmic transparency enforcement represent primary forecast revision triggers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Chile E-Commerce Market
E-Commerce Solutions
Croatia E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
Asia-Pacific Cross-Border B2C E-Commerce Market
E-Commerce Solutions
India Digital Gift Card Market
E-Commerce Solutions
Norway E-Commerce Market
E-Commerce Solutions
Direct-To-Consumer Test Market
E-Commerce Solutions
Ambient Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
India E-Commerce Market
E-Commerce Solutions
Malaysia E-Commerce Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
ASEAN E-Commerce Logistics Market