
 New Zealand E-Commerce Market | 2026-2036
New Zealand E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand E-Commerce Market Foresight
Auckland-based third-party logistics providers is shifting warehouse capacity toward same-day fulfillment zones. Trade Me leverages its auction heritage and localized trust architecture to sustain dominant position in C2C transactions. The Warehouse anchors its omnichannel strategy through click-and-collect integration with its physical store network. Mighty Ape competes on specialist gaming and pop-culture merchandise, occupying a defensible niche against generalist platforms.
New Zealand E-Commerce encompasses digitally mediated transactions of goods and services conducted through web-based storefronts, mobile applications, and social commerce interfaces, relying on electronic payment rails and last-mile distribution networks to complete commercial exchange. The primary purpose centers on reducing transactional friction between sellers and buyers while expanding addressable market reach beyond physical retail boundaries. Consumer Electronics commands the largest product category revenue pool, though Beauty Products registers the fastest velocity as subscription and replenishment models gain traction among repeat purchasers. Online Marketplaces capture disproportionate transaction volume across the sales channel dimension, while mobile apps represent the emerging interface where younger demographics concentrate their purchasing activity.
The Commerce Commission enforces the Fair Trading Act and Consumer Guarantees Act, mandating accurate product descriptions and refund obligations that elevate compliance costs for cross-border sellers. The Privacy Act 2020, administered by the Office of the Privacy Commissioner, imposes data breach notification requirements that reshape how platforms collect and retain customer information. Payment service providers must navigate Reserve Bank oversight alongside anti-money laundering protocols administered by the Department of Internal Affairs. Stakeholders must weigh whether to build proprietary fulfillment infrastructure or deepen partnerships with existing logistics networks as delivery speed becomes the primary battleground for customer retention.
Market Dynamics
The Commerce Commission's disclosure mandates are forcing marketplace sellers to rebuild their digital storefronts with granular product specifications and transparent return policies. This regulatory compression is accelerating platform consolidation as smaller sellers absorb compliance costs or exit.
Growth Catalysts
- Consumer Guarantees Act enforcement:The Commerce Commission's tightened refund obligations are elevating buyer confidence in high-value transactions, particularly for electronics purchases where warranty clarity reduces perceived risk.
- Auckland logistics clustering:Third-party fulfillment providers are concentrating warehouse capacity in the metropolitan corridor, compressing delivery windows and enabling same-day service for urban consumers.
- Social commerce interfaces:Mobile-first purchasing behavior among younger demographics is expanding addressable reach beyond traditional web storefronts, creating new entry points for specialty retailers.
Market Restraints
- Cross-border compliance friction:The Privacy Act 2020's data breach notification requirements impose costly information governance burdens on international sellers accessing New Zealand consumers.
- Last-mile infrastructure gaps:Rural distribution networks outside Auckland, Wellington, and Christchurch suffer from sparse carrier coverage and extended transit times.
- Payment rail fragmentation:Reserve Bank oversight layered with anti-money laundering protocols administered by the Department of Internal Affairs creates multi-layered authorization delays for new market entrants.
Strategic Opportunities
- Subscription replenishment models:Beauty and personal care categories show underpenetrated recurring revenue potential as consumers shift from episodic to automated purchasing.
- Click-and-collect network expansion:Physical retail footprints in secondary cities can anchor hybrid fulfillment models that bypass pure-play delivery cost structures.
- Specialist vertical deepening:Gaming, pop-culture, and hobbyist merchandise segments retain pricing power through community curation that generalist platforms cannot replicate.
Industry Challenges
- Data governance capability scarcity:Mid-market sellers struggle to implement Privacy Act-compliant customer information architectures without dedicated compliance functions.
- Legacy system integration friction:Established retailers face technical debt when connecting inventory management systems to marketplace APIs and mobile commerce platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand E-Commerce Market |
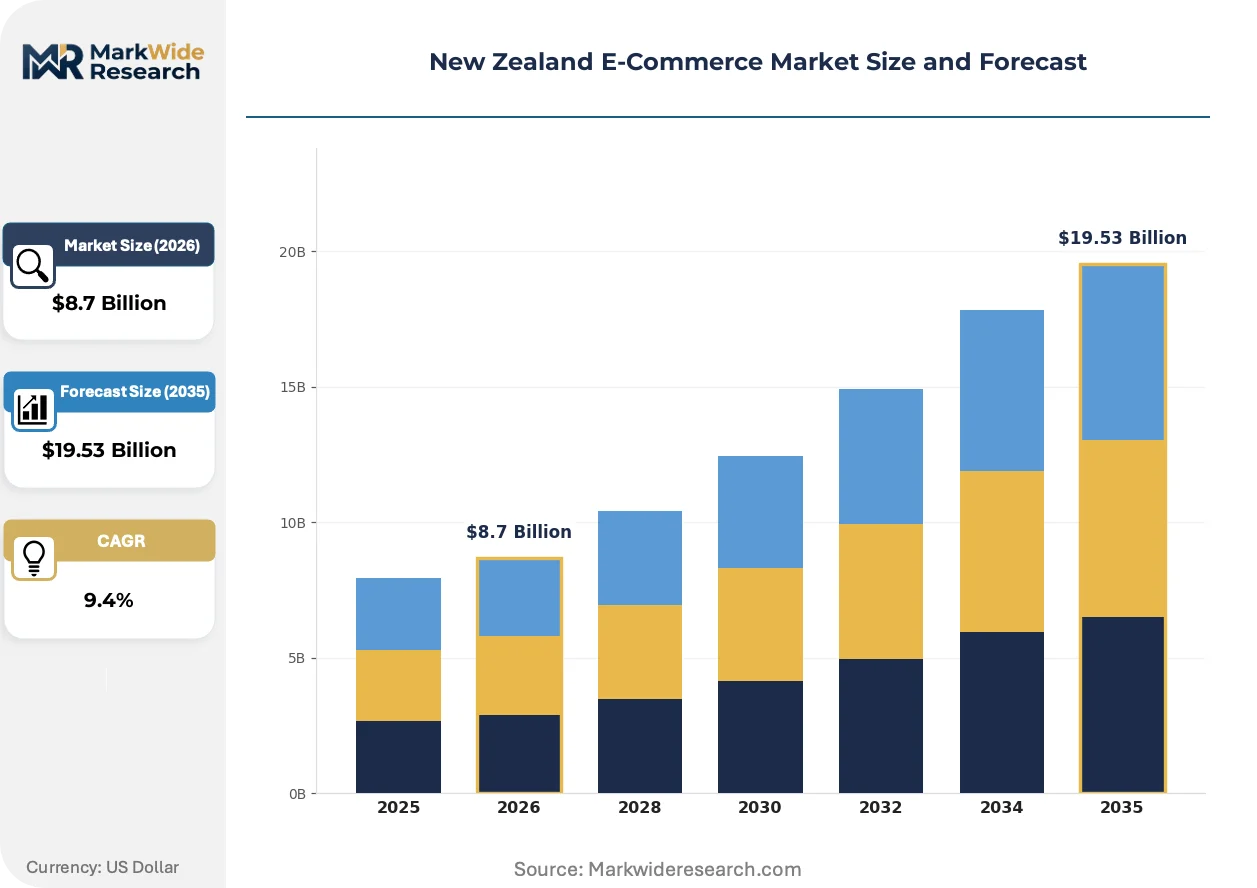
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Consumer Electronics, Apparel, Home Goods, Beauty Products Customer Type: B2C, B2B, C2C, Wholesale Payment Method: Credit Card, PayPal, Afterpay, Bank Transfer Sales Channel: Online Marketplaces, Brand Websites, Social Media, Mobile Apps |
| Companies Covered | Trade Me, The Warehouse, Mighty Ape, GrabOne, Kmart, Temu, Amazon, AliExpress, 1-day, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand E-Commerce Market Shifts & Advancements
Digital payment architectures and fulfillment automation are compressing transaction friction while regulatory transparency mandates reshape seller-platform relationships. Three developments merit particular attention.
Artificial intelligence-driven recommendation engines are integrating predictive inventory placement with individual browsing patterns. Mid-market retailers deploy these tools to reduce cart abandonment and optimize stock positioning across Auckland fulfillment nodes. The technology is integrating demand forecasting with real-time logistics coordination, narrowing the gap between purchase intent and delivery execution.
The Fair Trading Act's accuracy requirements are compelling marketplace operators to deploy automated description verification tools. Platforms now scan listings for misleading claims before publication, shifting liability exposure upstream. Consumer electronics and health-related categories face the most intensive scrutiny, with sellers investing in structured data feeds to preempt compliance flags.
Replenishment-driven purchasing patterns are displacing discretionary browsing as the dominant e-commerce behavior. Subscription services in beauty and household consumables capture recurring revenue through predictive reordering algorithms. Wellington and Christchurch metropolitan zones show the highest concentration of these automated purchase flows, reflecting urban consumer preferences for frictionless repeat transactions.
New Zealand E-Commerce Market Segmentation
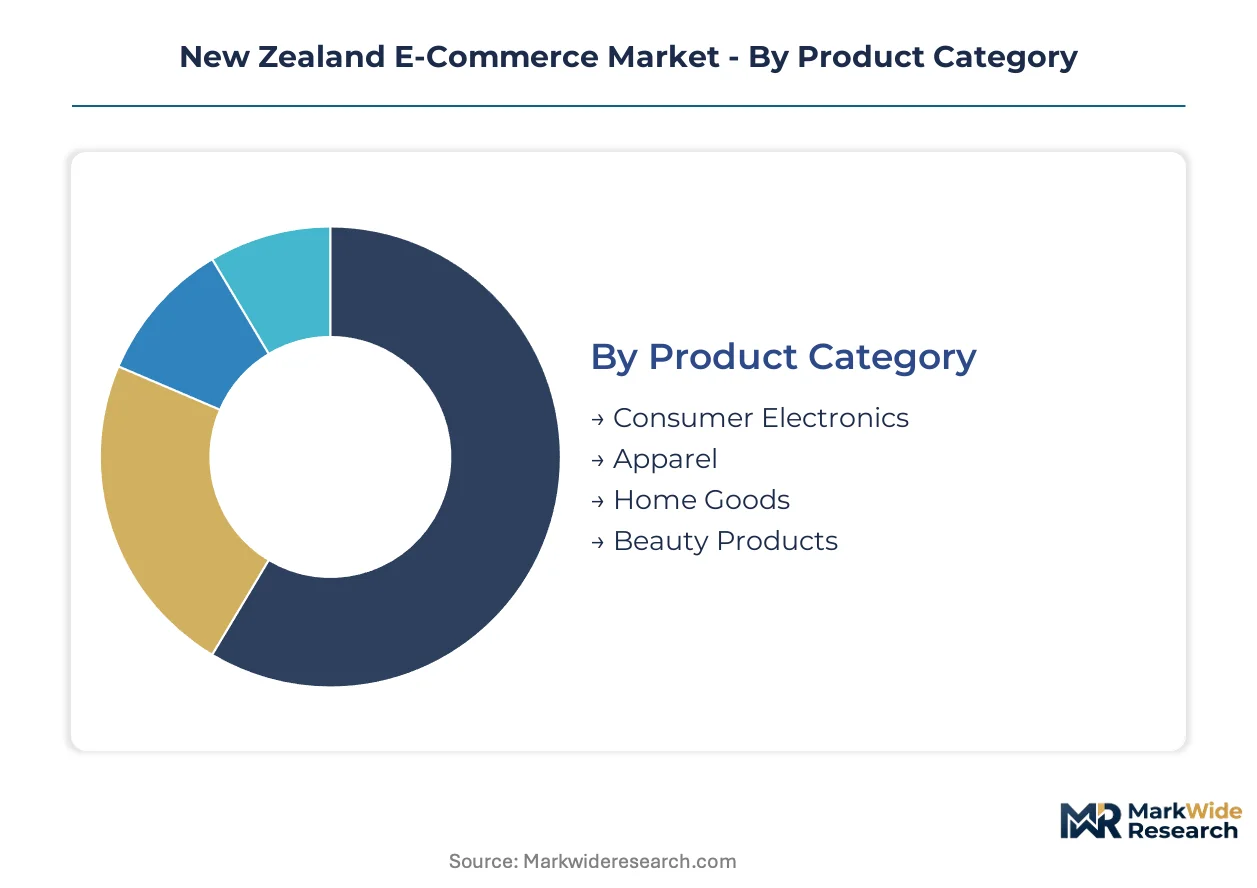
New Zealand's e-commerce segmentation reveals how digital purchasing behavior fragments across product categories, customer relationships, payment preferences, and interface technologies. Understanding these divisions enables targeted infrastructure investment and regulatory compliance planning across Auckland's logistics corridor and beyond.
Product Category:
Specification intensity and replenishment frequency define how product categories concentrate demand within New Zealand's metropolitan zones.
- Consumer Electronics:High-value transactions involving smartphones, laptops, and peripherals dominate revenue pools. Auckland households drive volume through warranty-sensitive purchases where Commerce Commission disclosure mandates reduce perceived transaction risk.
- Beauty Products:Subscription and automated replenishment models are gaining traction among repeat purchasers. Wellington and Christchurch metropolitan zones show concentrated adoption of predictive reordering algorithms for skincare and personal care consumables.
- Apparel:Seasonal purchasing cycles align with trans-Tasman fashion calendars, with click-and-collect integration reducing return friction.
- Home Goods:Bulky fulfillment requirements favor sellers with The Warehouse-style physical network anchoring last-mile delivery.
Mature deployment sits with Consumer Electronics. Newer deployment is concentrated in Beauty Products.
Customer Type:
Transaction scale and contractual complexity separate customer relationships across New Zealand's digital commerce landscape.
- B2C:Individual consumers executing discretionary and replenishment purchases through mobile-first interfaces. Auckland's same-day fulfillment infrastructure supports impulse-driven transaction velocity in this segment.
- C2C:Peer-to-peer exchanges leverage localized trust architectures and auction heritage. Trade Me's platform dominance sustains transaction liquidity for secondhand goods and collectibles.
- B2B:Procurement workflows integrate with enterprise inventory systems, requiring API connectivity that legacy retailers struggle to implement.
- Wholesale:Volume-based pricing and consolidated shipping contracts favor sellers with dedicated account management functions.
Volume concentration favors B2C. Margin expansion potential sits with B2B.
Payment Method:
Authorization speed and regulatory compliance burden differentiate payment rails available to New Zealand digital merchants.
- Credit Card:Dominant transaction volume through Visa and Mastercard networks with established chargeback protections. Reserve Bank oversight ensures settlement reliability across all merchant tiers.
- Afterpay:Buy-now-pay-later integration captures younger demographics through installment structuring. Department of Internal Affairs anti-money laundering protocols create onboarding friction for new market entrants deploying this method.
- PayPal:Cross-border seller preference due to integrated currency conversion and buyer protection frameworks.
- Bank Transfer:B2B and high-value B2C transactions favor this method for reduced merchant discount rates, though settlement delays extend fulfillment timelines.
Established infrastructure supports Credit Card. Fastest adoption velocity belongs to Afterpay.
Sales Channel:
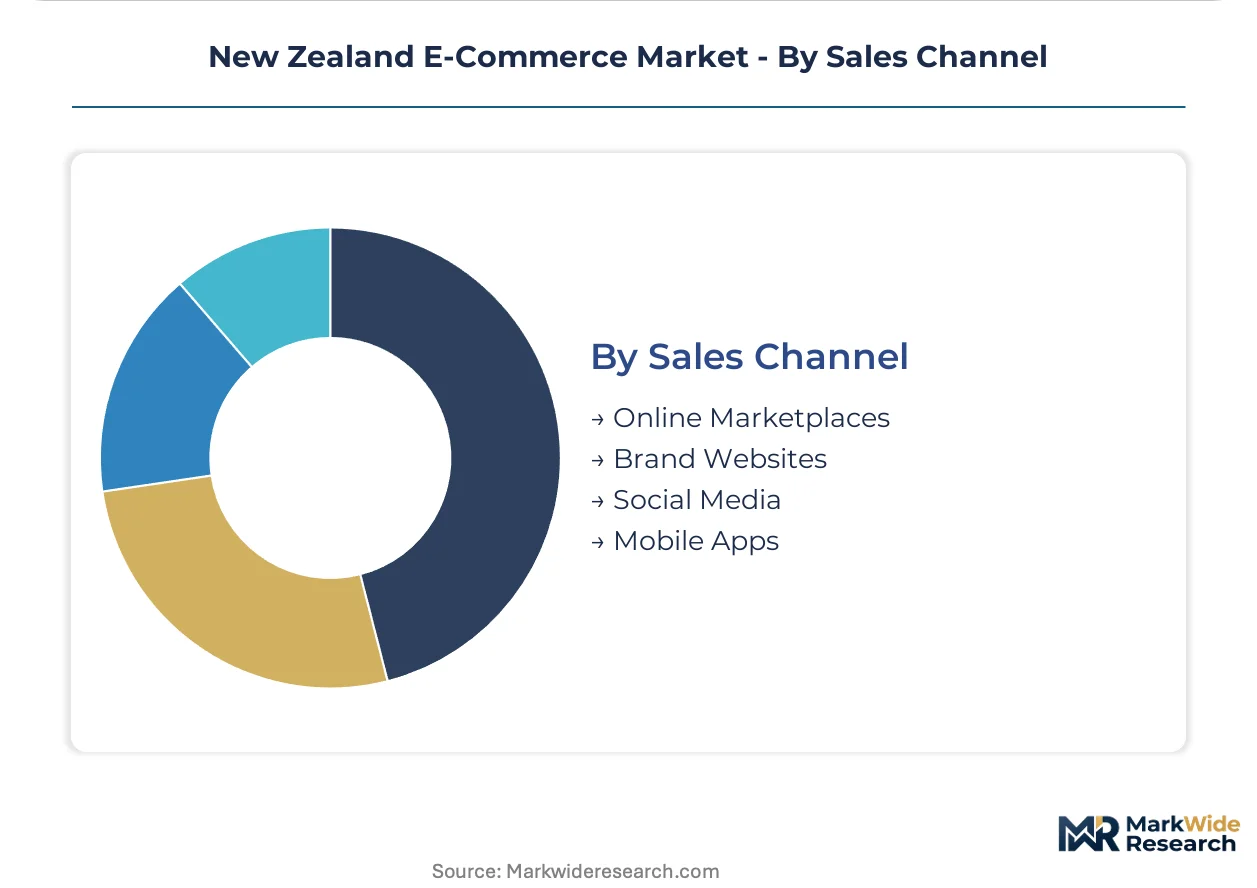
Interface technology and seller-platform power dynamics determine how transactions route through New Zealand's e-commerce architecture.
- Online Marketplaces:Aggregated seller bases with centralized traffic acquisition and fulfillment coordination. The Commerce Commission's tightened disclosure requirements are forcing marketplace sellers to rebuild digital storefronts with granular product specifications.
- Mobile Apps:Native purchasing interfaces concentrate younger demographic activity and enable push-notification-driven replenishment triggers. Mighty Ape's specialist gaming merchandise competes through community curation that generalist platforms cannot replicate.
- Brand Websites:Proprietary storefronts capture margin through direct consumer relationships, though traffic acquisition costs challenge independent operators.
- Social Media:Influencer-mediated discovery and in-feed purchasing expand addressable reach beyond traditional search-based entry points.
Transaction volume aggregates through Online Marketplaces. Steepest expansion trajectory belongs to Mobile Apps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Auckland's metropolitan corridor anchors New Zealand's e-commerce logistics density, with warehouse clustering and fulfillment velocity concentrating where population and infrastructure intersect. The Commerce Commission's consumer protection framework operates nationwide, yet compliance burdens and delivery economics create stark regional performance gradients.
Auckland Metropolitan Zone
Same-day fulfillment infrastructure and third-party logistics clustering drive transaction velocity in New Zealand's largest urban market. The Commerce Commission's Fair Trading Act enforcement elevates disclosure costs for marketplace sellers operating across the region. South Auckland industrial precincts concentrate automated warehousing investment as carriers compete on delivery window compression.
Wellington Capital Region
Government procurement digitization and professional services density sustain B2B e-commerce flows through specialized platforms. The Privacy Act 2020's data breach notification requirements reshape how public sector vendors manage customer information architectures. The Hutt Valley logistics corridor channels fulfillment traffic between port infrastructure and suburban distribution nodes.
Christchurch Canterbury
Post-earthquake infrastructure rebuilding embedded fiber-optic connectivity and automated sorting capacity into the regional distribution network. Consumer Guarantees Act refund obligations apply uniformly, yet rural Canterbury sellers face higher compliance friction relative to urban counterparts. Rolleston and Belfast industrial zones attract fulfillment center investment bypassing Christchurch congestion.
Hamilton-Waikato
Agricultural supply chain digitization and rural delivery network gaps create divergent e-commerce experiences across this mixed urban-rural territory. Reserve Bank payment oversight and anti-money laundering protocols administered by the Department of Internal Affairs delay new entrant authorization. Te Rapa industrial precinct hosts regional distribution hubs serving upper North Island catchments.
New Zealand E-Commerce Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialist verticals and cross-border marketplace penetration. The New Zealand e-commerce structure concentrates around domestic incumbents with auction heritage and physical network anchoring, while international platforms compete on price and selection breadth. Three archetypes dominate: localized trust-based marketplaces, omnichannel retailers with store-integrated fulfillment, and specialist community-curated platforms. Competitive moves center on click-and-collect network expansion and same-day fulfillment infrastructure partnerships.
Among domestic incumbents, Trade Me exemplifies the localized trust-based marketplace archetype through its auction heritage and C2C transaction liquidity. The Warehouse occupies the omnichannel tier with physical store anchoring for click-and-collect fulfillment. Mighty Ape represents specialist vertical deepening, concentrating community-curated merchandise in gaming and pop-culture segments where pricing power resists generalist platform competition.
| Leading Market Players |
|---|
| Trade Me |
| The Warehouse |
| Mighty Ape |
| GrabOne |
| Kmart |
| Temu |
| Amazon |
| AliExpress |
| 1-day |
| Others |
Supply & Pricing Matrix
Auckland's same-day fulfillment infrastructure anchors premium pricing tiers, while rural buyers absorb delivery-cost premiums that compress margins for cross-border sellers. Commerce Commission disclosure mandates elevate compliance spend, forcing smaller marketplace operators toward unbundled service models or exit.
Pricing Analysis
Warranty bundling separates Consumer Electronics pricing tiers, with extended coverage commanding premium positioning against bare-unit alternatives. Price differentiation rests on fulfillment velocity and return-policy transparency, not brand heritage alone. Cost compression in rural delivery tiers is intensifying because sparse carrier coverage extends transit windows. B2C individual consumers show highest price sensitivity, while B2B procurement workflows tolerate premium positioning for API-integrated inventory systems.
Supply Chain Analysis
Dual-sourcing requirements from major marketplace operators mandate multi-carrier qualification across Australia-based freight forwarders and domestic third-party logistics networks. Raw material flows draw from Chinese manufacturing hubs for Consumer Electronics, Australian beauty ingredient suppliers, and Southeast Asian textile producers. Supply chain risk centers on single-source vulnerability where Auckland warehouse clustering concentrates fulfillment capacity. Distribution runs through click-and-collect nodes at The Warehouse physical stores and direct-to-door courier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-capable operators as Commerce Commission disclosure mandates force weaker sellers toward platform exit or acquisition.
For Market Incumbents: Hedge regulatory exposure by deepening proprietary fulfillment infrastructure in South Auckland industrial precincts. Acquire smaller marketplace sellers struggling with Privacy Act compliance costs. Channel control through click-and-collect network expansion defends against Temu and AliExpress price aggression. For New Entrants and Emerging Players: Mobile-app-native purchasing interfaces offer lowest customer-acquisition friction among Wellington and Christchurch metropolitan zones. Target Beauty Products subscription replenishment as the most penetrable segment, where predictive reordering algorithms retain pricing power. Go-to-market through influencer-mediated social commerce bypasses established search-based traffic costs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market logistics specialists with Auckland warehouse footprints and existing carrier partnerships. Five-to-ten-year viability hinges on same-day fulfillment infrastructure ownership, not platform aggregation alone. Watch Commerce Commission enforcement intensity as inflection indicator for seller consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Same-Day Fulfillment Infrastructure Partnership | Third-party logistics clustering in Auckland compresses delivery windows against generalist platform competition. |
| Subscription Replenishment Model Launch | Beauty Products automated reordering captures recurring revenue through Wellington and Christchurch urban concentration. |
| Click-and-Collect Network Expansion | The Warehouse physical footprint integration reduces last-mile cost exposure in secondary cities. |
| Privacy Act Compliance Technology Investment | Automated description verification shifts liability upstream before Commerce Commission enforcement action. |
| Specialist Vertical Community Curation | Mighty Ape-style gaming and pop-culture merchandising resists generalist platform price erosion. |
Research Methodology
Multi-period observation of Auckland logistics capacity deployment, Commerce Commission enforcement actions, and marketplace seller exit rates anchored the trend analysis, supplemented by interviews with third-party logistics operators, e-commerce platform category managers, Privacy Act compliance consultants, and rural carrier network coordinators. Secondary validation drew from Reserve Bank payment system reports, Department of Internal Affairs anti-money laundering filings, Office of the Privacy Commissioner breach notifications, and Trade Me transaction volume disclosures. Bottom-up seller-level revenue modeling and top-down metropolitan consumption estimates were triangulated.
Input-output matrix framing connected Consumer Electronics warranty bundling, Beauty Products replenishment frequency, and Apparel return-rate assumptions to fulfillment cost structures across the projection horizon. Segmentation dimensions modeled include product category, customer type, payment method, and sales channel interface. CAGRs were derived from logistic diffusion curves fitted to mobile-app adoption patterns and same-day fulfillment penetration rates. Forecast inputs incorporated Auckland warehouse vacancy rates and Privacy Act complaint filing trajectories.
The model holds under stable Commerce Commission enforcement intensity and Reserve Bank payment authorization timelines; deviation in regulatory compression severity or cross-border data governance agreements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
India Digital Gift Card Market
E-Commerce Solutions
3D Interactive Ticketing Solutions Market
E-Commerce Solutions
Oman E-Commerce Market
E-Commerce Solutions
Latin America E-Commerce Logistics Market
E-Commerce Solutions
Pharma E-Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
Europe Dropshipping Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
Pharmaceutical E-Commerce Market
E-Commerce Solutions
Mobile Commerce Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
Ambient Commerce Enablement Infrastructure Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
Global Subscription E Commerce Market