
 Japan E-Commerce Market | 2026-2036
Japan E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Japan E-Commerce Market Outlook
Market Context with Strategic Players
Headless commerce architecture is fragmenting traditional monolithic platform stacks across Japan's online retail sector. Rakuten Ichiba leverages its super-app ecosystem to sustain merchant lock-in through integrated loyalty and financial services. Amazon Japan anchors fulfillment density with same-day delivery networks radiating from Kanto and Kansai distribution nodes. Mercari competes in C2C resale by specializing in frictionless mobile listing tools and AI-powered pricing suggestions.
Technical Definition and Structural Segments
Japan E-Commerce denotes digitally mediated commercial transactions where goods and services exchange through web-based storefronts, native applications, or API-connected procurement systems, typically processing payments via encrypted tokenization protocols and settling through domestic banking rails or licensed e-money instruments. The primary purpose is to reduce transaction friction, expand seller addressable markets beyond physical retail catchments, and capture consumption data for demand forecasting and inventory optimization. Marketplace channels dominate transaction volume by aggregating fragmented seller bases under unified discovery layers, while Social Commerce represents the fastest-expanding sales channel as LINE and Instagram integrate native checkout flows. B2B Platforms retain concentrated margin pools in industrial procurement, where contract pricing and volume tiering resist the transparency pressures affecting consumer-facing segments.
Regulatory Frame and Forward-Looking Close
METI enforces platform transparency rules under the Act on Improvement of Transparency and Fairness in Trading on Specified Digital Platforms, while the Consumer Affairs Agency applies the Specified Commercial Transactions Act to cooling-off rights and disclosure obligations for remote sales. The Payments Services Act, administered by the Financial Services Agency, governs digital wallet issuance and escrow functions that underpin most checkout flows. PMDA oversight intersects where beauty products and health-related items trigger pharmaceutical classification thresholds. Stakeholders must monitor whether METI expands designated platform obligations to mid-tier marketplaces currently below revenue thresholds, as this would force compliance investments across Qoo10 Japan and au PAY Market operations.
Market Dynamics
Headless commerce architecture is fragmenting Japan's platform stack, decoupling front-end presentation layers from back-end transaction engines and forcing incumbents to rebuild around API-first infrastructure.
Growth Catalysts
- Super-app convergence:LINE's native checkout integration binds messaging, payments, and discovery into unified purchase journeys, reducing friction for repeat transactions.
- Rural logistics extension:Cold-chain networks now reach Hokkaido dairy cooperatives and Kyushu citrus producers, unlocking fresh grocery e-commerce outside Kanto density zones.
- Payments Services Act revisions:FSA licensing clarity for escrow and e-money instruments enables cross-border sellers to deploy compliant checkout flows without domestic banking partnerships.
Market Restraints
- Platform compliance burden:METI's transparency obligations impose fixed-cost audit structures that disproportionately strain mid-tier marketplace operators below designated platform thresholds.
- Last-mile labor scarcity:Same-day delivery density in Greater Tokyo depends on contracted driver pools facing demographic contraction and wage pressure.
- Data localization requirements:Cross-border transaction records must reside on domestic servers, raising infrastructure costs for foreign entrants serving Japanese consumers.
Strategic Opportunities
- Tohoku and Shikoku penetration:Aging populations in Sendai and Matsuyama exhibit low online grocery adoption relative to infrastructure availability, creating first-mover windows for specialized fulfillment.
- B2B procurement digitization:Industrial buyers in Osaka's manufacturing belt are replacing fax-based ordering with API-connected procurement systems.
- Social commerce integration:Instagram Shopping and TikTok Shop are embedding native checkout within content feeds, capturing discovery-to-purchase moments outside traditional search.
Industry Challenges
- Legacy system integration:Established retailers operating on monolithic ERP architectures face multi-year migration timelines to adopt headless commerce stacks.
- PMDA classification complexity:Beauty and wellness products crossing pharmaceutical thresholds trigger extended review cycles that delay listing approvals.
- Talent scarcity in API development:Domestic engineering pipelines produce insufficient specialists in microservices architecture and cloud-native deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan E-Commerce Market |
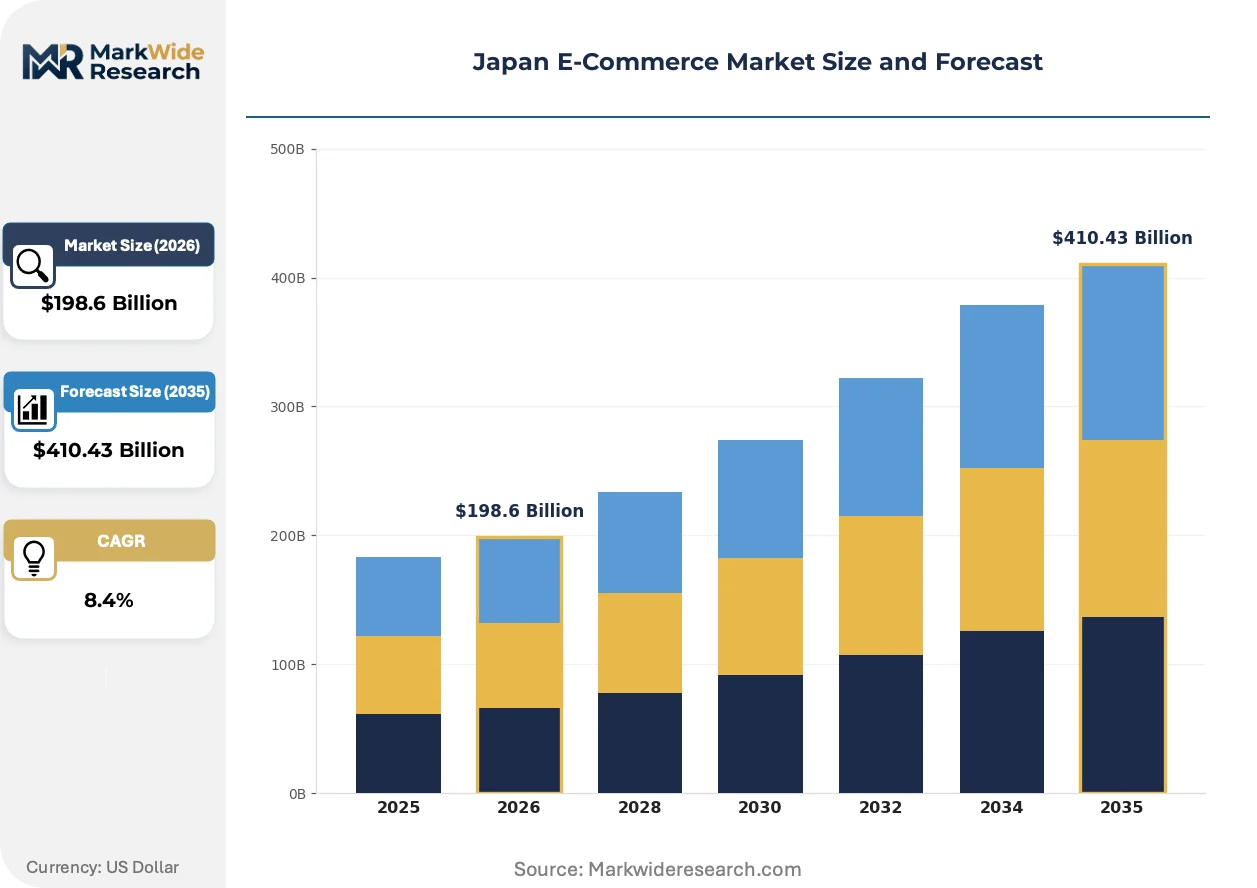
| Market Size in 2026 | $198.6 Billion |
| Market Size in 2035 | $410.43 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apparel, Electronics, Beauty Products, Home Goods Sales Channel: Direct Sales, Marketplace, Social Commerce, B2B Platforms Customer Type: Retail Consumers, SMEs, Corporates, E-Grocery Shoppers Payment Method: Credit Card, Digital Wallet, Bank Transfer, Cash on Delivery |
| Companies Covered | Amazon Japan, Rakuten Ichiba, Yahoo! Shopping Japan, Mercari, DMM.com, ZOZOTOWN, Rakuten Group, Qoo10 Japan, au PAY Market, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan E-Commerce Market Strategic Shifts
Commerce infrastructure in Japan is undergoing platform decoupling, regulatory recalibration, and behavioral channel migration simultaneously. These forces are compressing traditional competitive moats while opening entry paths for specialized operators.
Composable commerce stacks are migrating from monolithic legacy architectures toward modular API-assembled storefronts. Mid-market fashion and home goods retailers in Fukuoka and Nagoya are adopting headless frameworks to customize mobile experiences without replatforming core transaction engines. This migration from unified systems to component-based infrastructure enables faster A/B testing and reduces vendor lock-in.
METI's Act on Improvement of Transparency and Fairness in Trading on Specified Digital Platforms is mandating disclosure of search ranking parameters and contract terms for designated marketplace operators. The regulation forces Rakuten Ichiba and Amazon Japan to publish dispute resolution frameworks and fee structures. Smaller sellers gain leverage in platform negotiations, while compliance teams absorb new documentation burdens.
Subscription-based replenishment models are displacing one-time purchase behavior in household consumables and pet supplies. Younger cohorts in Tokyo and Osaka prefer automated delivery schedules over manual reordering, compressing customer acquisition costs for retention-focused operators. Rural prefectures lag this shift, maintaining higher per-transaction basket sizes with lower frequency.
Japan E-Commerce Market Segmentation
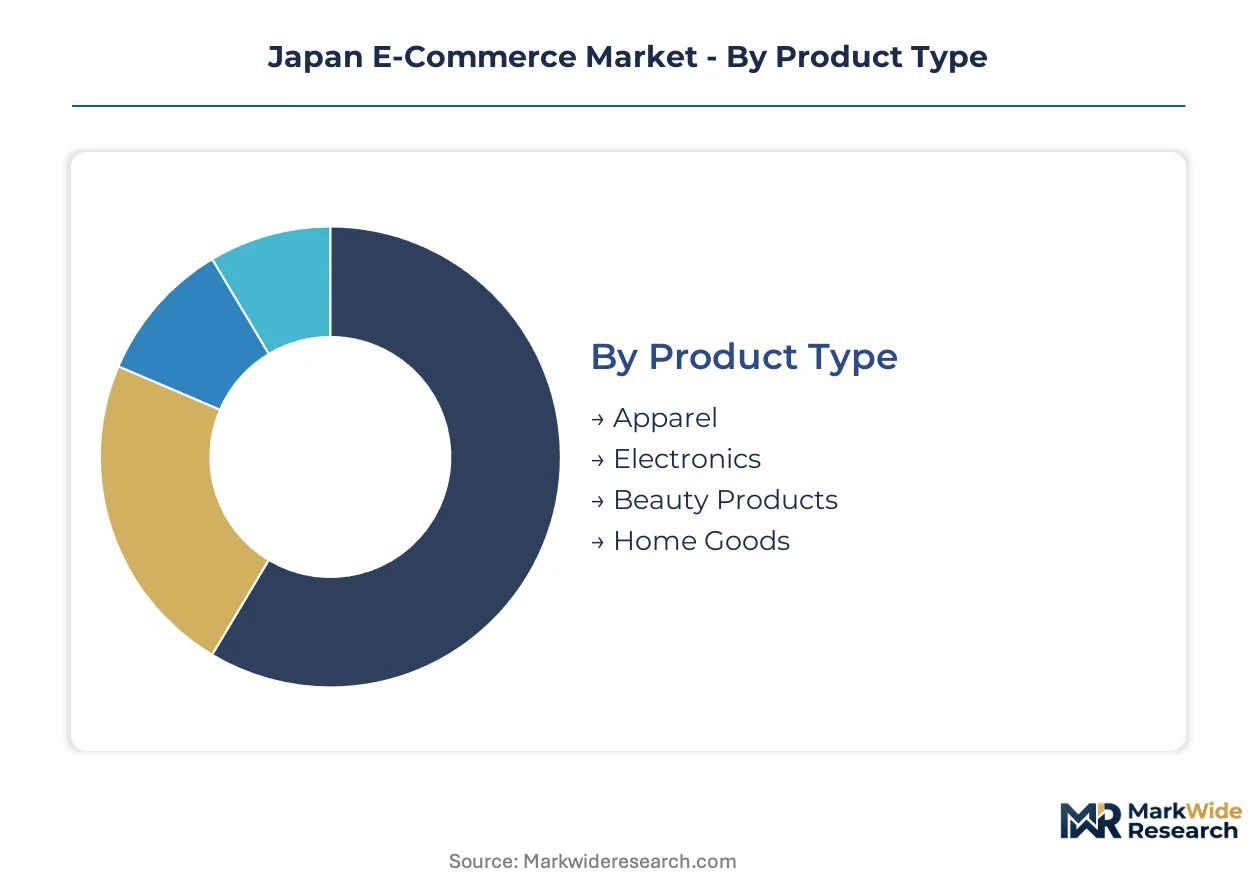
Segmentation reveals how purchase velocity, payment preferences, and fulfillment requirements fragment Japan's online retail landscape. Understanding these divisions exposes where infrastructure investments yield highest returns and which customer cohorts resist digital migration.
Product Type:
Cycle times vary dramatically: apparel refreshes quarterly while home goods turn annually, creating divergent inventory risk profiles across merchant portfolios.
- Electronics:High-consideration purchases with extended research phases and warranty dependency. Demand clusters around Tokyo and Osaka metro areas where same-day delivery density supports impulse upgrades of smartphones and peripherals.
- Apparel:Seasonal SKUs with high return rates due to sizing uncertainty. Repeat purchase frequency peaks among younger demographics in Fukuoka and Sapporo, where mobile-first discovery drives transaction velocity.
- Beauty Products:Subscription replenishment models capture recurring revenue in skincare and cosmetics, though PMDA classification thresholds delay launches for functional claims.
- Home Goods:Bulky fulfillment requirements favor merchants with dedicated large-item logistics partnerships across Kyushu and Tohoku distribution networks.
Electronics dominates installed base. Apparel is where expansion concentrates.
Sales Channel:
Channel economics split on customer acquisition cost versus margin retention, with direct operators sacrificing reach for profitability.
- Marketplace:Aggregated discovery layers with standardized fulfillment APIs. Rakuten Ichiba and Amazon Japan absorb majority transaction volume, though METI transparency rules now force search algorithm disclosures.
- Social Commerce:Native checkout embedded within LINE and Instagram feeds collapses discovery-to-purchase friction. Younger cohorts in urban corridors exhibit highest conversion rates from influencer-driven content.
- Direct Sales:Brand-controlled storefronts with full margin capture but elevated customer acquisition spend. Mid-market fashion retailers in Nagoya increasingly adopt headless architectures to customize experiences.
- B2B Platforms:Contract pricing and volume tiering resist transparency pressures affecting consumer segments. Osaka manufacturing belt buyers replace fax-based ordering with API-connected procurement systems.
Marketplace channels dominate installed base. Social commerce is climbing the fastest.
Customer Type:
Behavioral patterns diverge sharply between individual convenience-seekers and institutional procurement workflows with compliance layers.
- E-Grocery Shoppers:Aging demographics in Hokkaido, Kyushu, and Tohoku lock in repeat purchase behavior through subscription schedules. Cold-chain logistics extensions into rural prefectures now support fresh dairy and produce delivery.
- Corporates:Centralized procurement with negotiated terms and invoice-based settlement. Volume concentration in Tokyo headquarters drives platform customization requirements.
- Retail Consumers:Fragmented demand across age cohorts with payment method preferences varying by geography—cash on delivery persists in rural Shikoku.
- SMEs:Price-sensitive purchasing with limited technical integration capacity, favoring marketplace channels with standardized onboarding.
E-grocery shoppers dominate installed base. Corporate procurement digitization is where expansion concentrates.
Payment Method:
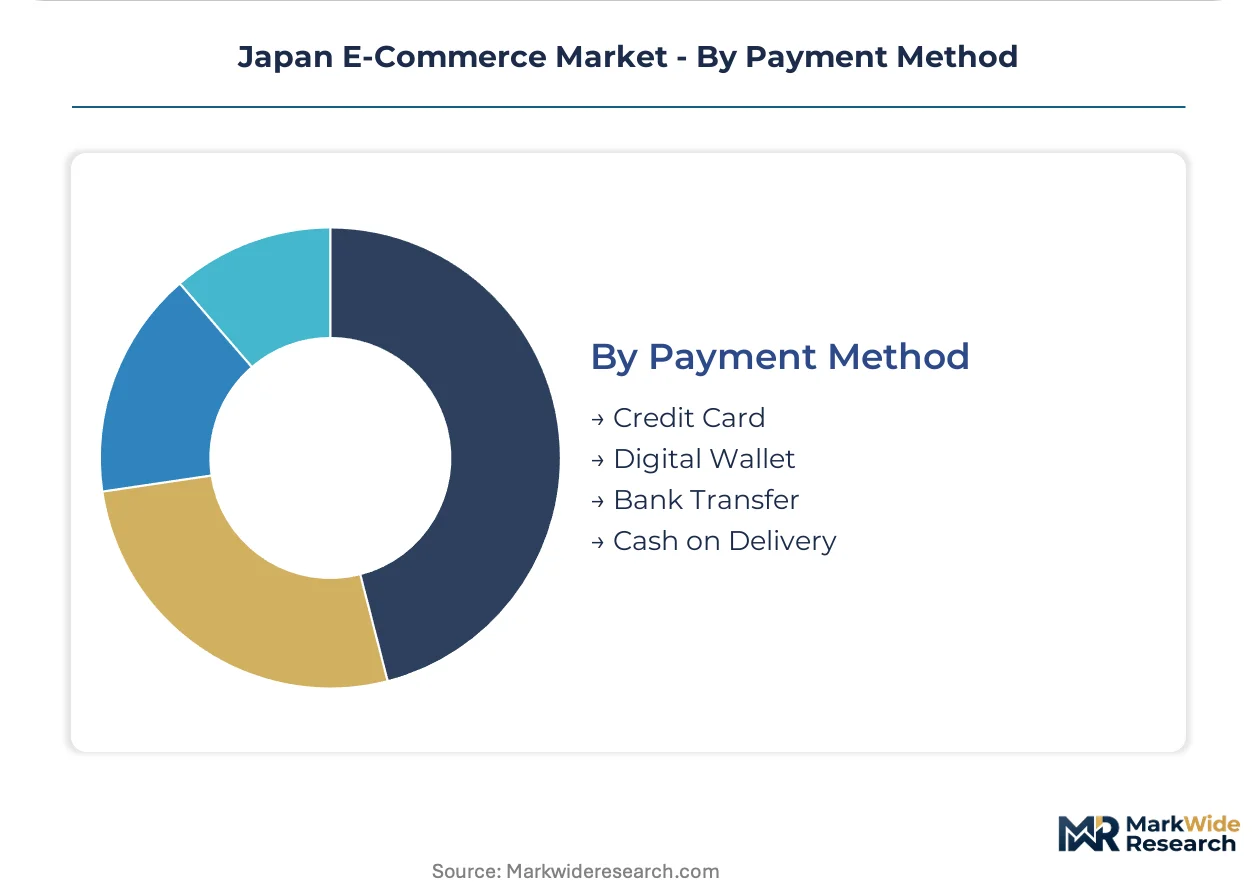
Settlement infrastructure maturity determines cross-border seller entry feasibility and checkout abandonment rates.
- Digital Wallet:LINE Pay and PayPay embedded within super-app ecosystems capture repeat transaction loyalty. FSA licensing clarity under Payments Services Act revisions enables compliant escrow without domestic banking partnerships.
- Credit Card:Dominant for high-value electronics and cross-border purchases, though interchange fees compress merchant margins.
- Cash on Delivery:Persistent preference among aging rural demographics in Tohoku and Shikoku, elevating logistics costs through collection reconciliation.
- Bank Transfer:Corporate and B2B standard with delayed settlement cycles, requiring working capital buffers from marketplace operators.
Credit card infrastructure dominates installed base. Digital wallet adoption is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-grocery shoppers in aging prefectures outside Tokyo-Osaka corridors drive fresh adoption as logistics networks extend into rural catchments. Regional variation concentrates in fulfillment density, payment infrastructure maturity, and demographic composition across Japan's island geography.
Kanto/Tokyo
Same-day delivery density peaks in Greater Tokyo where contracted driver pools support impulse electronics upgrades and subscription replenishment models. METI platform transparency rules force Rakuten Ichiba and Amazon Japan to publish search ranking parameters. The Shibuya and Shinjuku commercial clusters anchor super-app convergence with LINE Pay embedded in native checkout flows.
Kansai/Osaka
Industrial procurement digitization accelerates as manufacturing belt buyers replace fax-based ordering with API-connected systems. The Consumer Affairs Agency applies Specified Commercial Transactions Act cooling-off rights to B2B volume contracts. Osaka's Namba and Umeda districts concentrate fashion marketplace activity with mobile-first discovery driving apparel transaction velocity.
Kyushu
Cold-chain networks now reach citrus producers and dairy cooperatives, unlocking fresh grocery e-commerce outside Kanto density zones. FSA licensing clarity under Payments Services Act revisions enables compliant escrow for cross-border sellers. Fukuoka's Hakata district hosts mid-market retailers adopting headless commerce architectures for customized mobile experiences.
Hokkaido
Aging demographics lock in repeat purchase behavior through subscription schedules for household consumables and pet supplies. Data localization requirements raise infrastructure costs for foreign entrants serving Japanese consumers. Sapporo's retail corridor exhibits highest mobile-first apparel discovery rates among younger demographics in northern prefectures.
Tohoku
Low online grocery adoption relative to infrastructure availability creates first-mover windows for specialized fulfillment operators. PMDA classification complexity delays beauty product launches crossing pharmaceutical thresholds. Sendai's logistics hub serves as the distribution node for cold-chain extension into Matsuyama and rural Shikoku catchments.
Japan E-Commerce Market Competitive Environment
Channel-controlling players compete with product-specialist players across marketplace, social commerce, and direct sales vectors. The vendor base organizes around three strategic archetypes: super-app ecosystems bundling payments and loyalty, vertical fashion specialists owning discovery-to-delivery workflows, and C2C platforms monetizing frictionless mobile listing tools. Consolidation pressure concentrates in fulfillment infrastructure and payment licensing. Competitive moves emphasize API-first infrastructure rebuilds and geographic expansion into underpenetrated prefectures.
Within the super-app ecosystem tier, Rakuten Group exemplifies merchant lock-in through integrated financial services and loyalty point circulation. Among C2C specialists, Mercari occupies a position representing mobile-native resale architecture with AI-assisted pricing tools. At the cross-border marketplace vector, Qoo10 Japan sits within the compliance-sensitive tier where METI transparency obligations may expand to capture mid-tier operators below current revenue thresholds.
| Leading Market Players |
|---|
| Amazon Japan |
| Rakuten Ichiba |
| Yahoo! Shopping Japan |
| Mercari |
| DMM.com |
| ZOZOTOWN |
| Rakuten Group |
| Qoo10 Japan |
| au PAY Market |
| Others |
Value Chain & Pricing Dynamics
The Tokyo-Osaka freight corridor anchors cost dynamics across Japan's e-commerce landscape, where same-day delivery density in Greater Tokyo enables premium pricing for impulse electronics while rural logistics extensions compress margins on fresh grocery subscriptions. Supply concentration around Kanto and Kansai distribution nodes creates tiered fulfillment economics, with downstream price differentiation reflecting last-mile labor scarcity and cold-chain infrastructure availability.
Pricing Analysis
Cost-plus contracts with fuel indexation dominate third-party logistics arrangements, with surcharges adjusting to diesel price movements and driver wage inflation. Pricing stratifies across premium same-day tiers, standard next-day service, and economy multi-day windows, with brand premium and geographic delivery cost as primary differentiation drivers. Cost compression in rural fulfillment is intensifying because contracted driver pools face demographic contraction. SME marketplace sellers exhibit highest price sensitivity, while corporate procurement buyers prioritize API integration over unit cost.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment limit flows of advanced lithography systems from Netherlands and Japan, constraining domestic cloud infrastructure expansion. Supply concentration centers on China for consumer electronics assembly, South Korea for memory components, and domestic Kanto facilities for last-mile sortation. Raw material dependencies span lithium-ion cells, corrugated packaging, and refrigerants for cold-chain fleets. Single-source vulnerability runs through specialized automated sorting equipment. Distribution runs through hub-and-spoke networks radiating from Kanto and Kansai nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineering talent scarcity in microservices architecture and cloud-native deployment constrains platform modernization timelines, creating asymmetric advantage for operators with captive technical capacity. The gap between legacy ERP migration needs and domestic pipeline output defines competitive mobility across the forecast horizon.
For Market Incumbents: Insulate fulfillment density advantages by securing contracted driver pools through wage-premium structures in Greater Tokyo and Osaka corridors. Acquire headless commerce specialists to accelerate API-first infrastructure rebuilds before mid-tier competitors close capability gaps. METI transparency rule expansions threaten margin structures—preempt compliance investments to maintain platform economics.
For New Entrants and Emerging Players: Tohoku and Shikoku e-grocery corridors represent the most penetrable entry point, where aging demographics and low online adoption relative to cold-chain availability create first-mover windows. Specialized fulfillment for subscription household consumables in Sendai and Matsuyama bypasses incumbent density advantages. Partner with regional agricultural cooperatives for sourcing differentiation.
For Investors and Strategic Acquirers: API-first logistics technology providers with established Fukuoka or Sapporo footprints offer prime acquisition positioning, as platform decoupling accelerates demand for modular fulfillment infrastructure. Long-term viability hinges on regulatory clarity around data localization and cross-border escrow licensing. The signal to watch is METI expansion of designated platform obligations to mid-tier marketplaces.
| Strategic Initiative | Industry Significance |
|---|---|
| Headless Commerce Migration | Mid-market retailers in Nagoya and Fukuoka adopt API-assembled storefronts to reduce vendor lock-in. |
| Rural Cold-Chain Extension | Hokkaido dairy cooperatives and Kyushu citrus producers gain direct-to-consumer channel access. |
| Super-App Payment Integration | LINE Pay embedded checkout captures repeat transaction loyalty in Shibuya commercial clusters. |
| B2B Procurement Digitization | Osaka manufacturing belt buyers replace fax-based ordering with API-connected systems. |
| Subscription Replenishment Models | Automated delivery schedules for household consumables compress customer acquisition costs in Tokyo. |
Study Parameters
A standing panel of e-commerce platform engineers, logistics operations directors, merchant category managers, and FSA compliance officers provided ongoing calibration across the study period. Primary interviews with Rakuten Ichiba sellers, Amazon Japan fulfillment partners, and METI policy staff combined with secondary validation from METI platform governance disclosures, FSA Payments Services Act revisions, and cold-chain infrastructure investment filings. Bottom-up transaction volume modeling and top-down GDP-attribution approaches triangulated market sizing.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, sales channel, customer archetype, and payment method. Deployment model, organization size, and regional fulfillment density provided additional industry-specific granularity. CAGRs derived from logistic curve fitting against infrastructure penetration rates and demographic adoption curves. Forecast inputs incorporated rural logistics extension timelines and super-app payment adoption velocity.
Macroeconomic conditions sit as an overlay; deviation in yen exchange rates and domestic consumption tax policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and logistics labor availability. Material shifts in METI platform designation thresholds or Payments Services Act escrow requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Global Healthcare E-Commerce Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
E-Commerce Fulfillment Services Market
E-Commerce Solutions
ASEAN E-Commerce Logistics Market
E-Commerce Solutions
Global Ecommerce Platform Market
E-Commerce Solutions
Online on-Demand Laundry Service Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
Conversational Commerce Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
Retail E-Commerce Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
Global Subscription E-Commerce Platform Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
C2C E-Commerce Market
E-Commerce Solutions
Asia Pacific Same Day Delivery Market