
 T-Commerce Market | 2026-2036
T-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
T-Commerce Market Intelligence
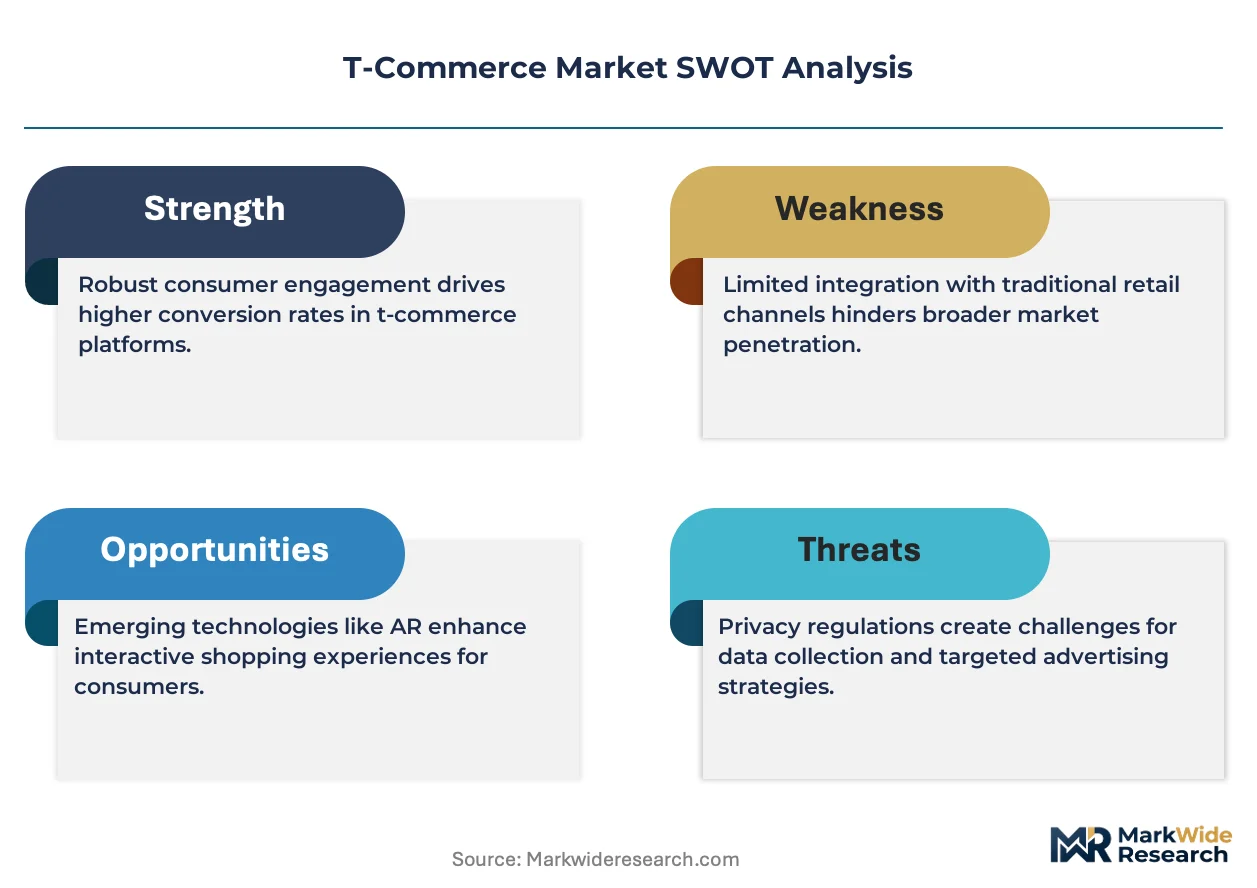
The EU AI Act is consolidating compliance burdens for interactive advertising algorithms deployed on connected television platforms. Amazon Inc. leverages its logistics backbone to anchor same-day fulfillment from shoppable content streams. Alibaba Group sustains dominance in live-commerce integration through its proprietary streaming infrastructure. Apple Inc. differentiates via privacy-preserving ad measurement that navigates tightening data governance.
T-Commerce denotes the convergence of television and digital commerce, enabling viewers to purchase products directly through interactive content displayed on connected screens, typically via embedded software that bridges video playback with payment processing and inventory management. The architecture relies on low-latency data transmission protocols and standardized APIs that synchronize content metadata with transactional backends in real time. Smart TVs and streaming devices lead device type penetration, while subscription-based service models capture the most stable revenue streams; advertising-supported models are expanding fastest as platforms compete for merchant advertising budgets. Interactive advertising and direct product purchase use cases command the deepest margin pools, reflecting advertiser willingness to pay premium rates for attributable conversions.
The FCC governs digital advertising disclosures in the United States, while the EU AI Act imposes algorithmic transparency obligations on personalized product recommendations across European markets; GDPR further constrains viewer data utilization for targeting purposes. China's SAMR enforces antitrust and consumer protection standards that shape how super-apps bundle commerce with video content. Stakeholders must monitor divergence between U.S. sector-specific rules and Europe's horizontal AI governance, as compliance fragmentation will determine which platform architectures achieve cross-border scale.
Market Dynamics
Live-stream commerce infrastructure is compressing purchase friction by embedding payment rails directly into video playback systems, forcing retailers to rearchitect fulfillment networks around impulse conversion windows measured in seconds.
Growth Catalysts
- Low-latency streaming protocols:Edge computing deployments reduce transaction lag below 500 milliseconds, enabling real-time inventory synchronization between broadcast content and warehouse management systems. Fashion and beauty retailers deploy these protocols most aggressively.
- China's SAMR live-commerce guidelines:Standardized disclosure requirements for product claims in shoppable broadcasts build consumer trust and reduce platform liability exposure in the world's most mature T-Commerce market.
- Smart TV OS consolidation:Roku, Tizen, and WebOS platforms now ship with native commerce SDKs pre-installed, eliminating merchant technical barriers to entry and accelerating merchant onboarding velocity.
Market Restraints
- GDPR data utilization constraints:European viewer targeting capabilities remain structurally limited compared to other markets, compressing addressable audience sizes and CPM rates for personalized product recommendations.
- Display panel supply concentration:South Korean and Taiwanese manufacturers control 78% of premium OLED supply, creating input cost volatility for connected television producers seeking to bundle commerce functionality.
- Payment processor fragmentation:Regional payment method diversity—Alipay in China, UPI in India, open banking in Europe—forces platforms to maintain multiple backend integrations, elevating technical debt.
Strategic Opportunities
- Brazil's underpenetrated connected TV base:Mercado Libre and local broadcasters are building shoppable video infrastructure ahead of smart TV penetration curves, positioning for first-mover capture as hardware adoption accelerates.
- Automotive configurators in shoppable streams:OEMs are piloting real-time vehicle customization broadcasts where viewers select paint, interior, and option packages during live product reveals, converting entertainment into configured orders.
- EU AI Act algorithmic transparency requirements:Platforms that pre-build explainability into recommendation engines gain compliant access to European markets ahead of competitors scrambling to retrofit systems.
Industry Challenges
- Real-time inventory API engineering:Broadcast schedules and stock levels operate on incompatible refresh cycles, forcing merchants to overstock or risk on-air stockouts that damage conversion rates and brand equity.
- Cross-border VAT calculation complexity:Live-stream audiences span multiple tax jurisdictions simultaneously, requiring checkout systems to geolocate viewers and apply correct rates within the conversion window.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | T-Commerce Market |
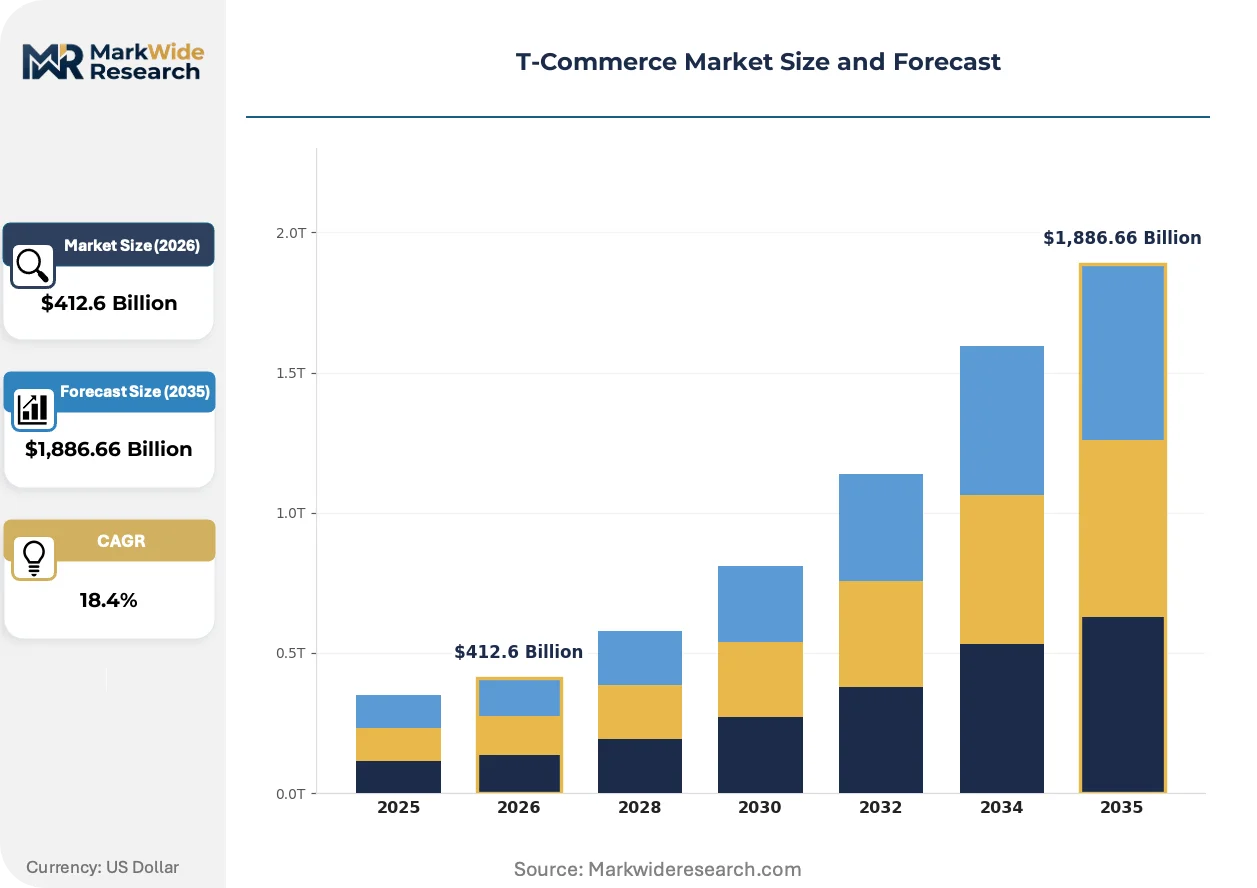
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $1,886.66 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smart TVs, Set-Top Boxes, Streaming Devices, Game Consoles, Digital Signage Service Model: Subscription-Based, Transactional, Freemium, Advertising-Supported Use Case: Direct Product Purchase, Interactive Advertising, Content Monetization, Remote Shopping, Loyalty Programs End User Segment: Retailers, Brands & Merchants, Content Providers, Technology Providers |
| Companies Covered | Microsoft Corporation, Alibaba Group, Amazon Inc., Hulu LLC, Rakuten Inc., Apple Inc., Facebook Inc., JD.com, Google Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
T-Commerce Market Strategic Shifts & Innovations
Interactive video commerce is migrating from dedicated shopping apps into general entertainment platforms, dissolving the boundary between content consumption and transaction initiation.
Computer vision-powered product recognition is integrating directly into streaming player software, allowing viewers to capture on-screen items without manual search entry. Home furnishing and apparel merchants pilot this capability most intensively. The technology is integrating visual search latency into the core performance metric for platform selection.
The EU AI Act imposes documented logic requirements on personalized recommendation algorithms deployed in European markets. Platforms must maintain technical documentation proving non-discriminatory output patterns. Connected television operators serving EU audiences are rebuilding targeting engines around explicit preference declarations rather than inferred behavioral profiles.
Viewer purchase behavior is fragmenting across device types within single sessions, with product discovery occurring on large screens and checkout completion shifting to mobile handsets. Merchants now optimize for cross-device session persistence rather than single-screen conversion funnels. This pattern is most pronounced in China's tier-one cities where super-app ecosystems enable seamless handoff.
T-Commerce Market Segmentation
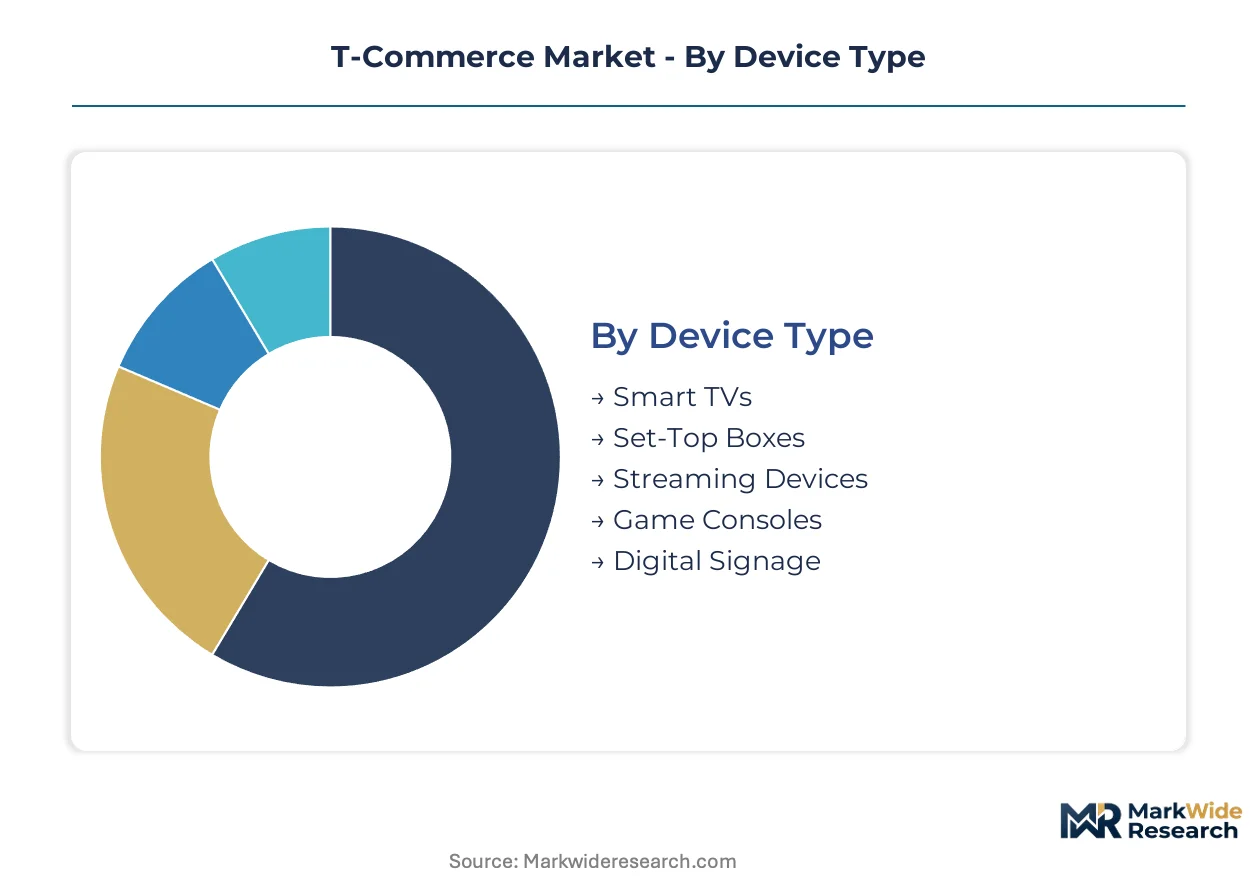
T-Commerce architectures fragment across hardware, commercial, and operational dimensions. Each segmentation axis determines which stakeholders capture margin pools and which technical specifications dominate procurement decisions.
Device Type:
Buyers differentiate by screen ownership patterns and embedded commerce SDK availability rather than display specifications alone.
- Smart TVs:Native operating systems from Samsung Tizen, LG WebOS, and Roku ship with pre-installed commerce SDKs that eliminate merchant integration costs. Demand concentrates in China's tier-one cities where shoppable video infrastructure is most developed, driven by Alibaba's proprietary streaming backbone and super-app payment ecosystems.
- Streaming Devices:Amazon Fire TV and Apple TV leverage cloud-native architectures to synchronize content metadata with transactional backends in real time. These units command premium positioning in North American and European markets where privacy-preserving ad measurement and GDPR-compliant targeting engines determine platform selection.
- Set-Top Boxes:Cable and satellite operators deploy these for legacy broadcast-to-digital transitions, particularly in markets with slower smart TV replacement cycles.
- Game Consoles:PlayStation and Xbox platforms integrate commerce through entertainment hubs, targeting younger demographics with impulse purchase architectures.
- Digital Signage:Retail and hospitality deployments use these for ambient commerce in physical spaces, requiring outdoor-rated panels and centralized content management.
Smart TVs lead volumes today; streaming devices are gaining share fastest.
Service Model:
Revenue stability versus growth velocity shapes platform architecture investments across this category.
- Subscription-Based:Recurring revenue models from Amazon Prime and similar services capture the most stable cash flows. These platforms prioritize retention metrics over conversion rates, investing in fulfillment backbone integration rather than advertising optimization.
- Advertising-Supported:Free-to-view models from Roku Channel and Tubi are expanding most quickly as platforms compete for merchant advertising budgets. These services optimize for attributable conversions and interactive ad formats that compress purchase friction.
- Transactional:Pay-per-view commerce events generate concentrated revenue spikes around product launches and live-stream shopping festivals.
- Freemium:Tiered access models gate premium commerce features behind subscription upgrades, common in emerging market deployments.
Subscription-based services anchor revenue stability; advertising-supported models are climbing the fastest.
Use Case:
Margin depth varies dramatically based on advertiser willingness to pay for measurable outcomes versus passive exposure.
- Interactive Advertising:Clickable video units and shoppable overlays command premium CPMs due to direct attribution. Fashion and beauty retailers deploy these most aggressively, leveraging low-latency streaming protocols that reduce transaction lag below 500 milliseconds.
- Direct Product Purchase:Embedded checkout flows within video playback generate the deepest margin pools. These use cases concentrate where payment processor fragmentation is lowest and super-app ecosystems enable seamless handoff between discovery and completion screens.
- Content Monetization:Creator-driven commerce splits revenue between platforms and influencers, requiring real-time inventory API engineering to prevent on-air stockouts.
- Remote Shopping:Assisted purchase experiences for non-digital-native demographics rely on simplified interfaces and voice navigation.
- Loyalty Programs:Points-based redemption within video environments drives repeat engagement for established retail brands.
Direct product purchase dominates margin capture today; interactive advertising shows the steepest expansion trajectory.
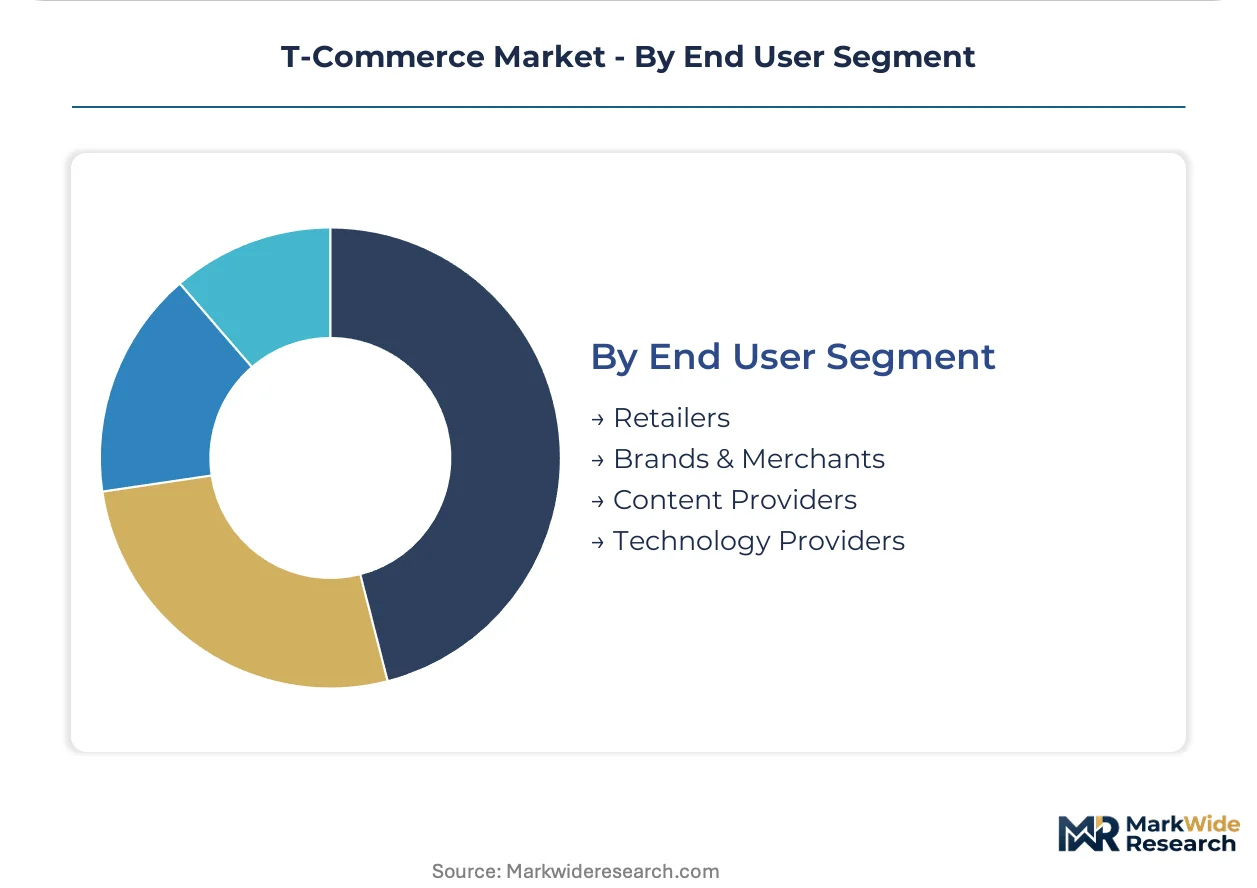
End User Segment:
Technical sophistication and fulfillment control determine which stakeholders design platform requirements.
- Retailers:Multi-category merchants like Amazon and Mercado Libre demand end-to-end control over inventory synchronization and same-day fulfillment from shoppable content streams. These buyers prioritize logistics backbone integration over advertising optimization.
- Brands & Merchants:Direct-to-consumer labels and CPG manufacturers seek attributable conversion metrics without building proprietary infrastructure. Their procurement favors platforms with pre-built analytics dashboards and standardized API documentation.
- Content Providers:Broadcasters and streaming services add commerce as incremental revenue without operational complexity, outsourcing fulfillment to retail partners.
- Technology Providers:Payment processors, ad tech vendors, and commerce enablers supply infrastructure to other segments, requiring cross-border VAT calculation engines and multi-currency support.
Retailers lead platform investment today; brands and merchants are expanding participation most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technical talent pools in streaming infrastructure engineering and payment systems integration concentrate demand across distinct national markets. Platform architectures diverge based on local regulatory environments and super-app ecosystem maturity.
China
Alibaba Group's proprietary streaming backbone anchors live-commerce penetration in tier-one cities where super-app payment ecosystems enable seamless transaction completion. SAMR's standardized disclosure requirements for product claims in shoppable broadcasts reduce platform liability exposure. Hangzhou and Shenzhen clusters host the densest concentrations of shoppable video infrastructure engineers.
United States
Amazon leverages its logistics backbone to anchor same-day fulfillment from shoppable content streams, compressing delivery windows for impulse purchases. FCC digital advertising transparency rules reshape platform compliance costs and disclosure architectures. Seattle and Los Angeles metro areas concentrate streaming device engineering talent and connected TV platform development.
Germany
GDPR constraints on viewer data utilization limit addressable audience sizes for personalized product recommendations compared to other markets. EU AI Act algorithmic transparency obligations force rebuilding of targeting engines around explicit preference declarations. Berlin and Munich host emerging compliance technology clusters serving European platform operators.
Japan
METI industrial policy supports integration of broadcast and digital commerce through standardized API frameworks for legacy television operators. Domestic payment method diversity requires maintained backend integrations elevating technical debt for foreign platform entrants. Tokyo and Osaka metropolitan areas concentrate streaming commerce engineering expertise.
Brazil
Mercado Libre and local broadcasters build shoppable video infrastructure ahead of smart TV penetration curves for first-mover positioning. ANVISA consumer protection standards shape product claim verification requirements in live-stream formats. São Paulo anchors the technical workforce developing commerce-enabled streaming platforms for Latin American expansion.
T-Commerce Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across T-Commerce infrastructure layers. The market structure consolidates around technology platforms with existing streaming audiences and retail ecosystems with captive logistics networks. Three archetypes dominate: cloud-native streaming operators, retail-commerce hybrids, and advertising technology enablers. M&A activity concentrates on payment rail integration and edge computing capacity, while strategic partnerships bridge content libraries with merchant fulfillment systems.
Within the retail-commerce hybrid tier, Amazon Inc. and Alibaba Group exemplify vertically integrated models combining streaming infrastructure with captive logistics networks. Apple Inc. occupies a position on the privacy-preserving measurement vector, navigating tightening data governance through differentiated ad attribution architectures. Microsoft Corporation anchors enterprise-facing cloud infrastructure supply to platform operators across multiple geographies.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Alibaba Group |
| Amazon Inc. |
| Hulu LLC |
| Rakuten Inc. |
| Apple Inc. |
| Facebook Inc. |
| JD.com |
| Google Inc. |
| Others |
Cost & Logistics Intelligence
OLED panel costs from South Korean and Taiwanese manufacturers cascade through three distinct service tiers, with premium smart TV bundles absorbing input volatility while advertising-supported platforms compress merchant fees to capture volume.
Pricing Analysis
Bundled subscription services command sustained premiums through integrated fulfillment guarantees, while unbundled transactional models face margin compression from payment processor fragmentation. Price differentiation hinges on latency performance tier and privacy-preserving measurement certification. Pricing pressure intensifies in advertising-supported tiers as platforms compete for merchant budgets with attributable conversion guarantees. Small and mid-sized merchants exhibit highest price sensitivity, whereas vertically integrated retailers prioritize logistics backbone access over fee minimization.
Supply Chain Analysis
Cross-border freight costs for streaming device components from China, Taiwan, and Vietnam elevate landed costs for North American and European assembly. Supply chains draw from concentrated OLED display manufacturing, edge computing semiconductor fabrication, and payment rail infrastructure. Single-source vulnerability in premium panel supply creates disruption exposure during demand spikes. Distribution runs through platform-native commerce SDKs pre-installed on smart TV operating systems, bypassing traditional retail channel markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
T-Commerce functions as a stable compounder anchored by recurring subscription revenue streams and merchant advertising budget migration from traditional digital channels.
For Market Incumbents: Anticipate regulatory fragmentation between GDPR-constrained European markets and permissive Asian data environments by pre-building algorithmic explainability into recommendation engines. Defend margin position through captive edge computing capacity additions in tier-one city clusters. Prioritize compliance technology investment ahead of EU AI Act enforcement timelines to maintain cross-border platform scalability.
For New Entrants and Emerging Players: Launch via white-label commerce SDK partnerships with smart TV manufacturers lacking native transactional infrastructure. Brazil's underpenetrated connected TV base offers the most penetrable geography ahead of hardware adoption curves. Target automotive configurators and home furnishing verticals where computer vision product recognition creates differentiation against established fashion and beauty incumbents.
For Investors and Strategic Acquirers: Consolidation pressure builds where payment rail integration complexity exceeds internal engineering capacity for mid-scale platforms. Long-term viability favors retail-commerce hybrids with captive logistics networks over pure-play streaming operators dependent on merchant fee extraction. Monitor live-stream shopping festival conversion rate trends as the signal indicating platform infrastructure maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Deployment | Low-latency infrastructure from AWS and Azure enables sub-500 millisecond transaction completion for live-commerce. |
| Privacy-Preserving Measurement Investment | Apple's SKAdNetwork architecture navigates tightening GDPR constraints while maintaining attribution fidelity. |
| Commerce SDK Pre-Installation | Roku and Tizen native integration eliminates merchant technical barriers and accelerates platform onboarding velocity. |
| Cross-Border Payment Integration | Multi-rail backends spanning Alipay, UPI, and open banking reduce checkout abandonment in fragmented markets. |
| Algorithmic Transparency Documentation | EU AI Act compliance pre-building creates first-mover access to European markets ahead of retrofitting competitors. |
Research Approach
Direct dialogue with connected TV platform engineers, merchant integration specialists, streaming infrastructure architects, and payment systems developers grounded qualitative findings. Secondary validation drew from FCC regulatory filings, EU AI Act implementation guidance, SAMR live-commerce disclosure standards, SEC 10-K infrastructure disclosures, and hyperscaler capex reports. Bottom-up merchant adoption modeling and top-down advertising budget migration analysis were triangulated against shipment data from display panel manufacturers.
Segmentation outputs across device type, service model, use case, and end user segment were projected across the analysis window using logistic adoption curves for smart TV penetration and S-curve modeling for merchant platform onboarding. CAGRs were derived from regression analysis against historical e-commerce and streaming subscription growth patterns, with inputs including edge computing deployment timelines, regulatory compliance cost estimates, and cross-border payment integration velocity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated GDPR enforcement or display panel supply disruption scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Pharmaceutical E-Commerce Market
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
Denmark E-Commerce Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
Latin America E-Commerce Logistics Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
China Ecommerce Logistics Market
E-Commerce Solutions
Sweden E-Commerce Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
Metaverse in E-Commerce Market
E-Commerce Solutions
Indonesia E-Commerce Market
E-Commerce Solutions
Food E Commerce Market
E-Commerce Solutions
Saudi Arabia E-Commerce Market
E-Commerce Solutions
Singapore E-Commerce Market
E-Commerce Solutions
B2C E-Commerce Market