
 Southeast Asia Cross-Border E-Commerce Market | 2026-2036
Southeast Asia Cross-Border E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Cross-Border E-Commerce Market Analytics
The price-performance gap between premium direct-ship electronics and commodity apparel drop-shipped from China is hardening across Southeast Asian platforms. Shopee leverages its integrated SeaMoney payments stack to sustain checkout conversion in tier-two Indonesian cities. Lazada Group anchors cross-border fulfillment through Alibaba's Cainiao network, while Bukalapak specializes in micro-SME onboarding with localized Bahasa interfaces.
Cross-border e-commerce denotes online retail transactions where buyers and sellers reside in different jurisdictions, requiring multi-currency pricing, customs clearance protocols, and last-mile handoffs across sovereign borders. Its commercial purpose centers on expanding merchant addressable markets beyond domestic inventory constraints while offering consumers access to SKUs unavailable through local distribution. Electronics commands the highest average order value and return complexity, while digital wallets displace cash-on-delivery as the fastest-growing payment rail due to real-time settlement and buyer protection features. Fulfillment centers in Johor Bahru and Bangkok generate superior margin pools compared to direct shipping by aggregating customs clearance and enabling next-day delivery promises.
Indonesia's trade ministry enforces product certification through its national standards body, while Thailand's central bank supervises e-payment licensing under the Payment Systems Act. Vietnam's e-commerce decree mandates foreign platform registration with local tax authorities, tightening market access for unincorporated sellers. Stakeholders must monitor divergent customs de minimis thresholds and emerging digital tax frameworks as ASEAN members advance unilateral rather than bloc-wide enforcement.
Market Dynamics
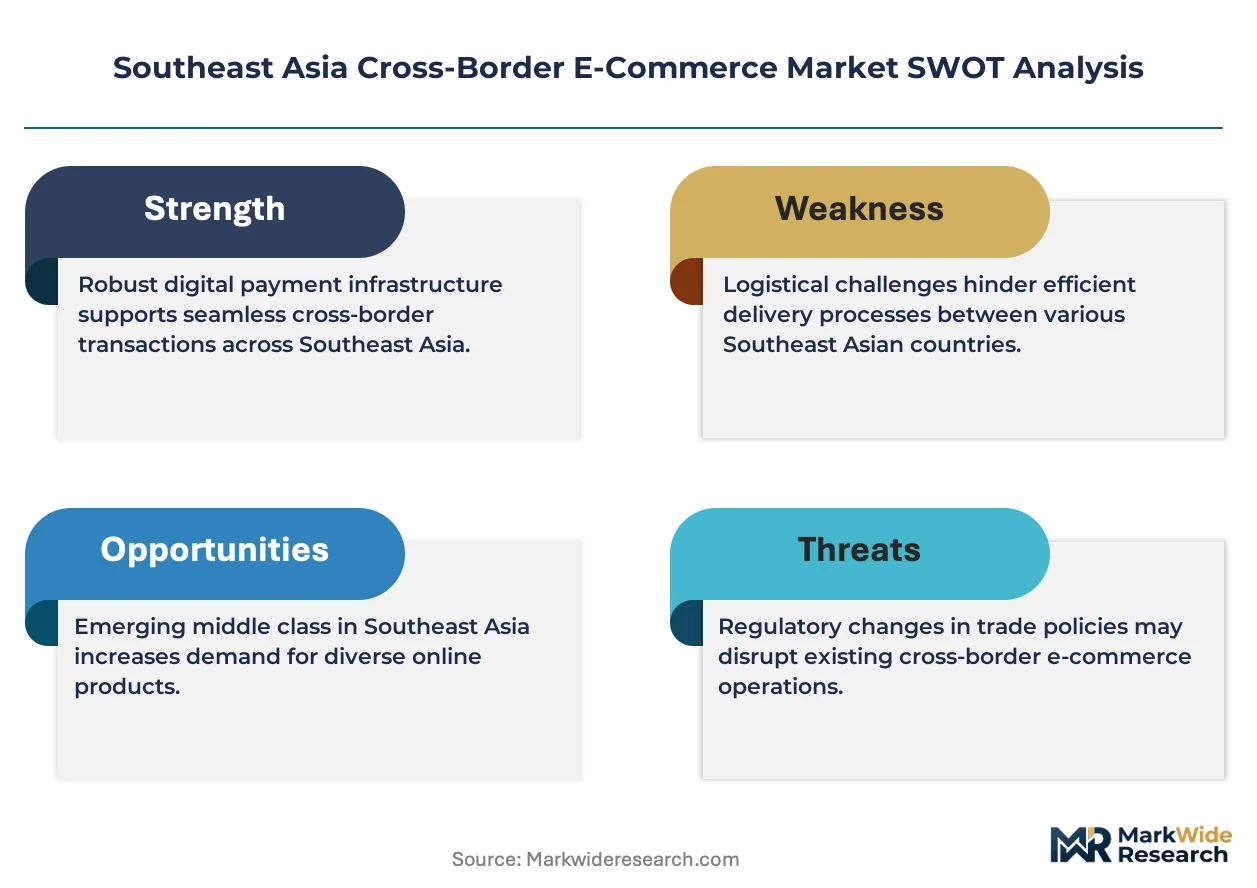
ASEAN's regulatory harmonization under the ASEAN Agreement on Electronic Commerce is compressing cross-border friction while digital wallet infrastructure scales unevenly across tier-one versus tier-two urban corridors.
Growth Catalysts
- Digital wallet penetration:Real-time settlement protocols through SeaMoney, Dana, and GrabPay are displacing cash-on-delivery in Indonesian and Vietnamese metropolitan zones.
- ASEAN Agreement on Electronic Commerce:Mutual recognition frameworks for electronic signatures and cross-border data flows reduce legal uncertainty for platform operators.
- Micro-SME onboarding:Localized Bahasa and Thai-language seller interfaces expand merchant supply pools beyond English-fluent urban centers.
Market Restraints
- Customs de minimis divergence:Indonesia's USD 3 threshold versus Thailand's USD 45 ceiling creates arbitrage complexity and compliance fragmentation.
- Last-mile concentration:Johor Bahru and Bangkok fulfillment clusters dominate margin-efficient cross-border logistics, leaving peripheral provinces dependent on slower direct-ship models.
- Product certification heterogeneity:Indonesia's SNI marks, Thailand's TISI requirements, and Vietnam's QCVN standards impose non-tariff barriers on electronics imports.
Strategic Opportunities
- Tier-two Indonesian cities:Surabaya, Bandung, and Medan exhibit wallet adoption velocity without proportional fulfillment infrastructure deployment.
- Live commerce integration:Shopee Live and TikTok Shop convergence with checkout flows compresses discovery-to-purchase latency for apparel and beauty categories.
- Vietnam's e-commerce decree amendments:Foreign platform registration mandates create first-mover advantages for compliant cross-border operators establishing local tax presence.
Industry Challenges
- Customs clearance talent scarcity:Licensed customs brokers with ASEAN-wide tariff classification expertise command premium wages in Ho Chi Minh City and Jakarta.
- Returns infrastructure capex:Electronics average order values justify dedicated reverse logistics networks, but apparel drop-ship margins cannot absorb equivalent facility investment.
- Cross-border payment reconciliation:Multi-currency settlement across Indonesian rupiah, Thai baht, and Vietnamese dong introduces FX hedging complexity for unhedged SME sellers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Cross-Border E-Commerce Market |
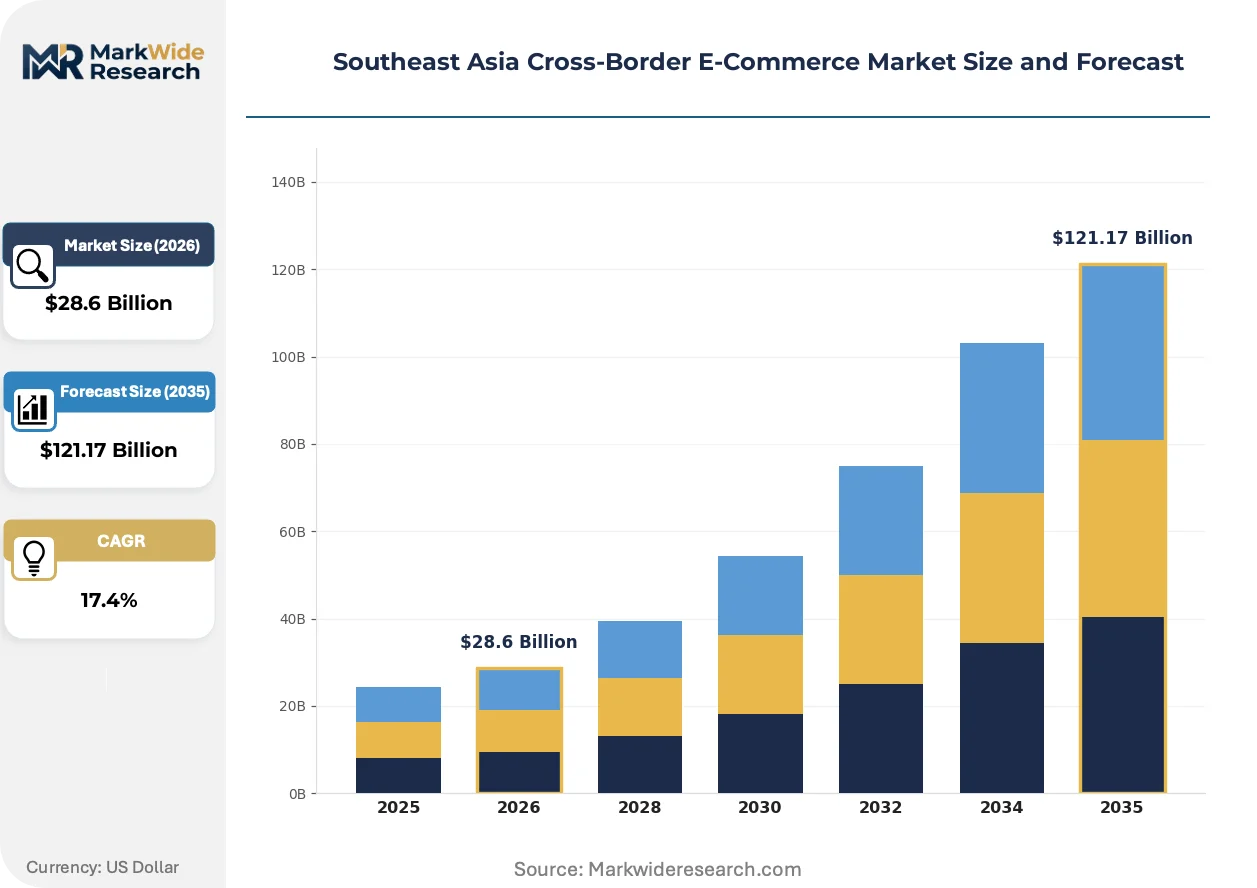
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $121.17 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Apparel, Beauty Products, Home Goods Payment Method: Credit Card, Digital Wallets, Bank Transfer, Cash on Delivery Customer Segment: Millennials, Professionals, Students, Families Shipping Model: Direct Shipping, Fulfillment Centers, Drop Shipping, Local Pick-Up |
| Companies Covered | Bukalapak, Tiki Corp, Shopee (Sea Ltd), Zalora (Global Fashion Group), Blibli, Lazada Group (Alibaba), Qoo10 Pte Ltd, JD.com Inc (JD.ID), Tokopedia (GoTo), Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Cross-Border E-Commerce Market Evolving Landscape
Platform economics in Southeast Asia are pivoting from traffic acquisition toward fulfillment density and payment stack integration as primary defensibility mechanisms.
AI-powered demand forecasting is rewriting inventory positioning algorithms for cross-border sellers. Tier-two city merchants in Indonesia and Vietnam now receive automated replenishment signals based on social commerce engagement metrics rather than historical sell-through data. This compression of planning cycles is enabling next-day delivery promises previously restricted to metropolitan warehouses.
Thailand's Payment Systems Act amendments are tightening e-money licensing scrutiny for foreign wallet operators. The Bank of Thailand now mandates local data residency and capital adequacy thresholds that favor incumbent SeaMoney and TrueMoney over newer entrants. Electronics and high-value beauty categories face elevated compliance documentation requirements under the revised supervision framework.
Social commerce discovery patterns are fragmenting buyer journeys across multiple touchpoints. Indonesian consumers increasingly initiate product search within TikTok and Instagram interfaces before completing checkout on native Shopee or Lazada apps. This channel arbitrage concentrates advertising spend on short-video platforms while commoditizing traditional search-based marketplace traffic in Jakarta and Bangkok.
Southeast Asia Cross-Border E-Commerce Market Segmentation
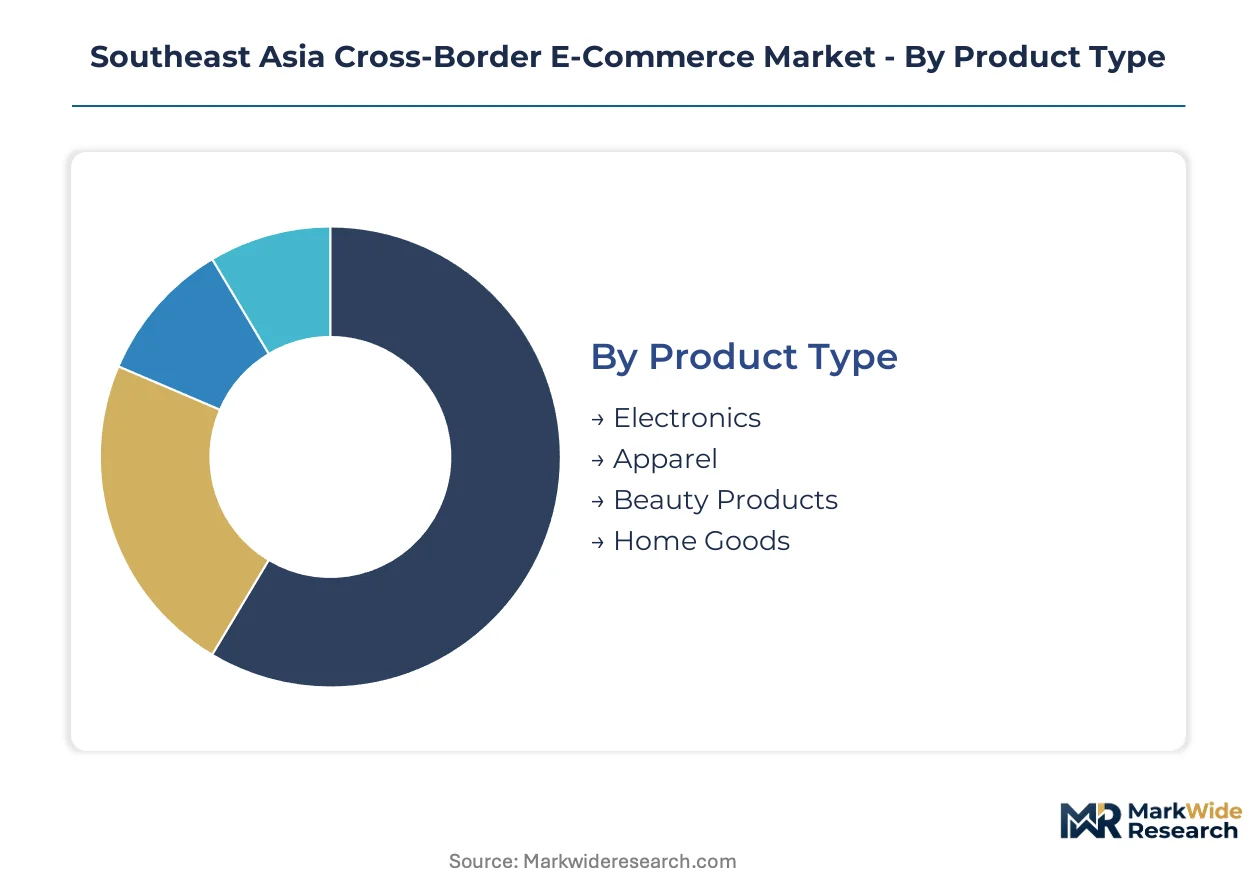
Cross-border e-commerce segmentation in Southeast Asia reveals how fulfillment economics, payment infrastructure maturity, and customs clearance complexity fragment addressable markets. Product certification requirements and wallet penetration rates vary sharply across these dimensions, forcing platform operators to configure localized service stacks rather than deploy uniform regional templates.
Product Type:
Standalone high-value categories demand integrated logistics and payment protection systems, while embedded consumable segments ride on platform traffic density without dedicated infrastructure.
- Electronics:Smartphones, laptops, and accessories carry the highest average order values and trigger Indonesia's SNI certification mandates. Demand clusters in Jakarta and Ho Chi Minh City where licensed customs brokers aggregate clearance for bulk shipments. Real-time settlement through SeaMoney and Dana displaces cash-on-delivery for these high-ticket purchases.
- Apparel:Fast-fashion SKUs from Guangdong factories dominate volume through drop-ship models with 7-14 day delivery windows. Thai consumers drive disproportionate per-capita spend on Korean beauty-adjacent clothing imports, while Indonesian tier-two cities exhibit rising order frequency without proportional fulfillment infrastructure.
- Beauty Products:K-beauty and C-beauty imports face Thailand's FDA registration requirements and Vietnam's ingredient disclosure rules. Cross-border sellers cluster SKUs in Johor Bahru fulfillment centers to compress delivery timelines.
- Home Goods:Furniture and kitchenware shipments incur dimensional weight penalties that favor sea freight over air cargo. Malaysian consumers show highest adoption of consolidated container shipping for bulky purchases.
Volume placements concentrate in Electronics; the faster expansion belongs to Beauty Products.
Payment Method:
Cost-tier stratification separates premium frictionless checkout experiences from cash-handling overhead that erodes margin on low-value orders.
- Digital Wallets:SeaMoney, Dana, and GrabPay enable real-time settlement with buyer protection features that reduce return disputes. Indonesian metropolitan zones exhibit wallet penetration above 60 percent, while Thai consumers favor TrueMoney's bank-linked top-up infrastructure. Transaction fees compress merchant margins but sustain conversion rates in competitive categories.
- Credit Card:Visa and Mastercard networks dominate Singapore and Malaysian cross-border purchases where issuing banks offer FX-hedged travel cards. Chargeback rights protect consumers on electronics purchases exceeding USD 200 equivalent.
- Bank Transfer:Virtual account systems through Indonesian state banks and Vietnamese techcombank channels serve underbanked professionals without credit histories. Settlement latency of 24-48 hours delays order confirmation.
- Cash on Delivery:Remains prevalent in Philippine provinces and rural Vietnamese districts where digital wallet onboarding lags. Courier collection costs add 8-12 percent to landed order economics and elevate return risks.
Transaction density clusters on Digital Wallets; steepest expansion trajectory runs through Bank Transfer as rural onboarding accelerates.
Customer Segment:
Maturity-based segmentation distinguishes digitally native cohorts from family units requiring trust-building mechanisms and installment financing options.
- Millennials:Urban Indonesian and Vietnamese consumers aged 28-38 drive Shopee Live commerce engagement and TikTok Shop discovery-to-purchase compression. Social proof and influencer endorsements override brand loyalty in apparel and beauty categories.
- Professionals:Bangkok and Singapore white-collar workers prioritize electronics and premium home goods with express delivery promises. Credit card-linked wallets dominate their payment mix.
- Students:Price-sensitive cohort in Malaysian university towns and Indonesian secondary cities. Group-buy mechanics and flash sale timing drive purchase decisions on accessories and study electronics.
- Families:Multi-generational households in Philippine and Vietnamese provincial centers favor cash-on-delivery for household replenishment. Bulk sizing and subscription discounts capture recurring orders.
Order frequency concentrates with Millennials; wallet adoption velocity is climbing fastest among Families as remittance-linked financial services expand.
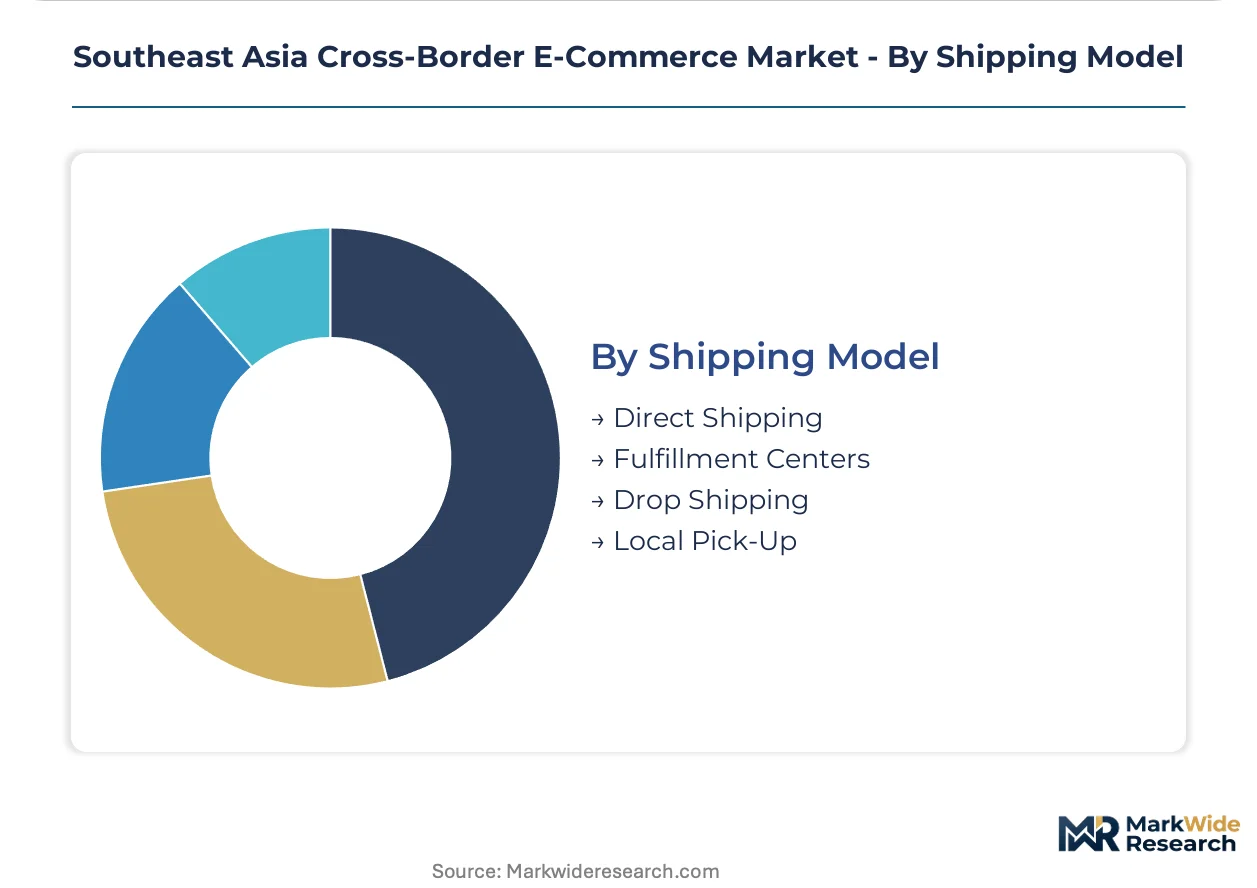
Shipping Model:
Geographic concentration of supply determines which fulfillment architecture can sustain next-day delivery promises against cost-competitive direct-ship alternatives.
- Fulfillment Centers:Johor Bahru and Bangkok clusters aggregate customs clearance and enable next-day delivery to Singapore and metropolitan Thailand. SeaMoney-integrated merchants achieve 15-20 percent higher conversion on electronics through inventory proximity.
- Direct Shipping:China-origin parcels through Cainiao and postal networks serve price-sensitive apparel buyers accepting 10-14 day timelines. Indonesian customs de minimis thresholds below USD 4 trigger frequent duty complications.
- Drop Shipping:Guangdong-based sellers list inventory without Southeast Asian stockholding, transferring fulfillment risk to consumers. Returns processing remains unsolved for this segment.
- Local Pick-Up:Alfamart and Indomaret partnerships in Indonesia, plus 7-Eleven integration in Thailand, serve unbanked customers without residential delivery addresses. Counter collection adds friction but reduces last-mile failure rates.
Margin efficiency concentrates in Fulfillment Centers; infrastructure deployment is gaining share fastest in Local Pick-Up as convenience store networks digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta anchors cross-border e-commerce volume through its concentration of licensed customs brokers and digital wallet infrastructure. The metropolitan corridor generates the highest average order values for electronics imports while serving as the primary node for tier-two city distribution.
Indonesia
Young professionals in Surabaya, Bandung, and Medan drive wallet adoption velocity through SeaMoney and Dana transactions. The country's trade ministry enforces SNI certification mandates through its national standards body, creating compliance bottlenecks for electronics imports. Fulfillment infrastructure concentrates in Greater Jakarta, leaving tier-two cities dependent on slower direct-ship models with extended delivery windows.
Vietnam
Ho Chi Minh City and Hanoi white-collar workers power demand for K-beauty imports and mid-tier electronics through credit card-linked wallets. The government's e-commerce decree mandates foreign platform registration with local tax authorities, tightening market access for unincorporated cross-border sellers. Licensed customs brokers with ASEAN-wide tariff classification expertise command premium wages in Ho Chi Minh City due to clearance talent scarcity.
Thailand
Bangkok metropolitan consumers sustain the region's highest per-capita spend on Korean beauty-adjacent apparel imports through TrueMoney's bank-linked infrastructure. The Bank of Thailand supervises e-payment licensing under the Payment Systems Act, mandating local data residency and capital adequacy thresholds. Fulfillment clusters in Bangkok enable next-day delivery promises to Singapore and metropolitan Thailand through aggregated customs clearance.
Singapore
The city-state functions as the regional headquarters node for platform operators managing multi-country fulfillment networks. Visa and Mastercard networks dominate cross-border purchases where issuing banks offer FX-hedged travel cards. Johor Bahru fulfillment centers across the border generate superior margin pools compared to direct shipping by aggregating customs clearance for the Singapore market.
Philippines
Multi-generational households in provincial centers favor cash-on-delivery for household replenishment, sustaining courier collection costs that add 8-12 percent to landed order economics. The central bank's digital payment transformation roadmap accelerates wallet onboarding in Metro Manila while rural districts lag. Alfamart and Indomaret partnerships serve unbanked customers without residential delivery addresses through counter collection networks.
Southeast Asia Cross-Border E-Commerce Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fulfillment infrastructure ownership and payment stack integration. The market structure fragments between integrated platform operators with captive logistics networks and marketplace aggregators reliant on third-party shipping. Three archetypes dominate: vertically integrated e-commerce groups controlling end-to-end supply chains, social commerce platforms leveraging short-video discovery, and specialized vertical marketplaces focused on single categories. Competitive moves center on fulfillment center expansion into tier-two corridors and payment licensing acquisitions to lock in checkout conversion.
Within the integrated platform tier, Shopee and Lazada exemplify divergent strategic postures. Shopee anchors its position through SeaMoney payment stack integration and live commerce convergence. Lazada occupies a position leveraging Alibaba's Cainiao network for cross-border fulfillment density. Bukalapak represents the specialized vertical archetype through micro-SME onboarding with localized Bahasa interfaces.
| Leading Market Players |
|---|
| Bukalapak |
| Tiki Corp |
| Shopee (Sea Ltd) |
| Zalora (Global Fashion Group) |
| Blibli |
| Lazada Group (Alibaba) |
| Qoo10 Pte Ltd |
| JD.com Inc (JD.ID) |
| Tokopedia (GoTo) |
| Others |
Value Network & Pricing Analysis
Captive logistics networks through Cainiao and SeaMoney infrastructure anchor both supply positioning and checkout pricing power across Indonesian and Thai corridors. Platform operators with integrated fulfillment stacks extract premium conversion rates while drop-ship merchants absorb margin compression from extended delivery windows and customs duty exposure.
Pricing Analysis
Value-based pricing anchored to delivery speed and buyer protection features dominates electronics transactions through SeaMoney and Dana integration. Three-tier pricing structure across premium express, standard fulfillment, and economy direct-ship segments separates merchants by inventory proximity and customs clearance capability. Pricing pressure stems from China-origin drop-ship commoditization in apparel categories where 7-14 day timelines erode willingness-to-pay. Students in Malaysian university towns exhibit highest price sensitivity; Bangkok professionals accept premiums for next-day electronics delivery.
Supply Chain Analysis
Indonesia's SNI certification mandates and Thailand's TISI requirements reshape sourcing toward pre-certified component suppliers in Vietnam and Malaysia. Cross-border inventory draws from Guangdong manufacturing clusters, Johor Bahru aggregation hubs, and Bangkok fulfillment centers. Single-source vulnerability concentrates in China-origin electronics components subject to customs clearance bottlenecks. Distribution runs through platform-operated fulfillment networks rather than merchant-direct postal channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics favor consolidation as fulfillment infrastructure capex requirements and payment licensing barriers force unintegrated merchants toward exit. Regulatory harmonization pressures compound this dynamic by raising compliance fixed costs.
For Market Incumbents: Deploy payment stack licensing acquisitions to lock in checkout conversion before Thailand's Payment Systems Act amendments tighten capital adequacy thresholds. Reinforce fulfillment density in Surabaya and Bandung through Johor Bahru hub expansion, countering TikTok Shop's social commerce discovery threat with inventory proximity advantages. For New Entrants and Emerging Players: Enter via Vietnam's e-commerce decree compliance pathway by establishing local tax presence ahead of foreign platform registration mandates. Target tier-two Indonesian cities where wallet adoption velocity outpaces fulfillment infrastructure deployment, leveraging Alfamart counter collection networks to bypass last-mile concentration. For Investors and Strategic Acquirers: Exit pathways concentrate in platform rollup transactions as SeaMoney-integrated operators absorb micro-SME specialists lacking captive logistics. Long-term viability favors vertically integrated e-commerce groups with ASEAN-wide customs broker relationships. Monitor Indonesia's customs de minimis threshold adjustments as inflection signal for drop-ship margin viability.| Strategic Initiative | Industry Significance |
|---|---|
| Fulfillment Center Expansion | Johor Bahru and Bangkok clusters enable next-day delivery promises through aggregated customs clearance. |
| Payment Licensing Acquisition | SeaMoney and TrueMoney integrations sustain checkout conversion rates above unintegrated wallet alternatives. |
| Live Commerce Platform Integration | Shopee Live convergence with checkout flows compresses discovery-to-purchase latency for beauty categories. |
| Micro-SME Onboarding Localization | Bahasa and Thai-language seller interfaces expand merchant supply pools beyond English-fluent urban centers. |
| Regulatory Compliance Pre-Positioning | Vietnam foreign platform registration mandates create first-mover advantages for tax-compliant operators. |
Research Methodology
Multi-period observation of digital wallet transaction velocity, fulfillment center utilization rates, and customs clearance throughput anchored the trend analysis, supplemented by interviews with platform operations executives, licensed customs brokers, e-payment licensing officers, and tier-two city merchant representatives. Secondary validation drew from ASEAN trade statistics, Bank of Thailand Payment Systems Act filings, Indonesian trade ministry SNI certification records, and Vietnam e-commerce decree implementation notices. Bottom-up merchant supply estimates triangulated against top-down platform GMV disclosures.
Input-output matrices modeled transaction flows across product type, payment method, customer segment, and shipping model dimensions over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated digital wallet penetration curves by metropolitan zone and fulfillment infrastructure deployment timelines in tier-two corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unilateral customs de minimis adjustments and digital tax framework fragmentation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
ASEAN E-Commerce Logistics Market
E-Commerce Solutions
Indonesia E-Services Market
E-Commerce Solutions
Italy Dropshipping Market
E-Commerce Solutions
North America Automotive E-Commerce Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Market
E-Commerce Solutions
Business to Business E Commerce Market
E-Commerce Solutions
Bahrain E-Commerce Market
E-Commerce Solutions
Vietnam E-Commerce Market
E-Commerce Solutions
Europe E-Commerce Watch Market
E-Commerce Solutions
Indonesia E-Commerce Market
E-Commerce Solutions
E-Commerce Software Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market
E-Commerce Solutions
North America B2B E-Commerce Market