
 Europe FMCG B2B E-Commerce Market | 2026-2036
Europe FMCG B2B E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Europe FMCG B2B E-Commerce Market Insights
Single-source procurement reliance on legacy distributors is decoupling as buyers diversify across digital channels. BigBuy anchors Spain and Portugal with specialized dropshipping infrastructure for independent retailers. Ankorstore competes through curated brand discovery tools that connect emerging European FMCG producers with boutique stockists. Alibaba extends its reach via cross-border fulfillment nodes serving price-sensitive Southern European wholesalers.
Europe FMCG B2B E-Commerce denotes digitally intermediated wholesale transactions where fast-moving consumer goods flow from manufacturers or authorized distributors to business buyers through online platforms, typically integrating real-time inventory synchronization, dynamic pricing algorithms, and API-connected procurement systems. The primary commercial purpose centers on reducing order cycle latency, consolidating fragmented supplier bases, and enabling data-driven replenishment for downstream retail and hospitality operators. Beverages and personal care categories dominate transaction volumes due to high replenishment frequency and standardized logistics requirements, while subscription services represent the fastest-growing distribution channel as recurring revenue models reduce customer acquisition costs. Online marketplaces capture the deepest margin pools through commission stacking on payment processing, logistics, and advertising layers.
The EU Digital Services Act, GDPR, and national e-invoicing mandates from tax authorities in Italy and France shape platform architecture requirements and data handling protocols for cross-border transactions. REACH compliance for chemical-containing personal care products adds product verification layers before marketplace listing eligibility. Stakeholders must monitor divergence between EU-wide digital regulation and member-state enforcement timelines to calibrate platform rollout sequencing.
Market Dynamics
Platform consolidation is compressing procurement cycle times as independent retailers abandon phone-and-fax ordering for API-connected inventory systems. The shift is decoupling buyer loyalty from traditional distributor relationships across Southern and Central Europe.
Growth Catalysts
- EU Digital Services Act:Mandated transparency in algorithmic ranking and complaint-handling systems is forcing marketplace operators to standardize seller verification protocols. This reduces buyer risk perception and accelerates platform onboarding for fragmented retail bases.
- Replenishment automation:Machine-learning demand forecasting tools embedded in procurement platforms are absorbing historical sales volatility. Independent grocers in Spain and Italy deploy these systems to reduce safety stock holdings.
- Polish retail fragmentation:The country's dispersed network of small-format stores lacks direct distributor coverage, creating natural aggregation demand for digital wholesale intermediaries with last-mile fulfillment capabilities.
Market Restraints
- Input cost volatility:Fuel and packaging material price swings compress platform commission margins, forcing operators to absorb logistics cost spikes or risk seller attrition.
- Cross-border VAT complexity:Divergent e-invoicing mandates between France's Chorus Pro system and Italy's SDI platform create compliance friction for pan-European marketplace operators.
- Legacy ERP integration:Proprietary data formats in incumbent distributor systems resist standard API connectivity, delaying buyer migration to digital procurement channels.
Strategic Opportunities
- Romanian market underpenetration:The country's independent retail sector remains underserved by digital wholesale platforms, offering first-mover expansion potential for operators with localized payment and logistics infrastructure.
- Subscription replenishment models:Recurring-order frameworks for high-velocity categories like beverages reduce customer acquisition costs and improve inventory predictability for platform operators.
- REACH compliance automation:Automated product verification workflows for chemical-containing personal care goods streamline marketplace listing processes and reduce seller onboarding friction.
Industry Challenges
- API interoperability talent scarcity:Shortages of developers skilled in legacy ERP-to-cloud platform integration slow buyer migration timelines and increase implementation costs.
- GDPR data residency requirements:Constraints on cross-border personal data flows complicate centralized platform architecture for operators serving multiple EU member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe FMCG B2B E-Commerce Market |
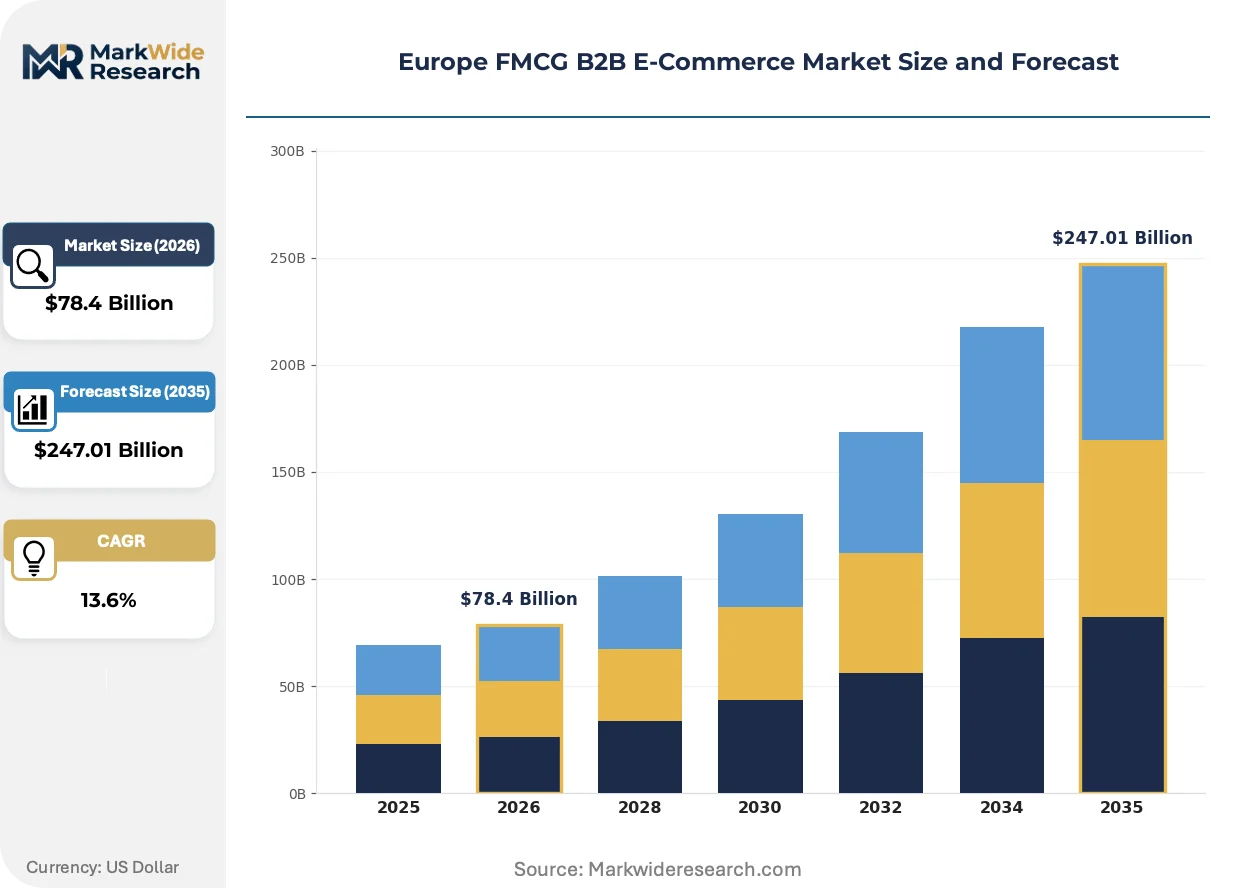
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beverages, Snacks, Dairy Products, Personal Care Distribution Channel: Online Marketplaces, Direct Sales, Wholesalers, Subscription Services Customer Type: Retailers, Grocery Stores, Restaurants, Hotels Service Model: Drop Shipping, Fulfillment Services, Purchase Order Management, Inventory Management |
| Companies Covered | BigBuy, Cdiscount, Allegro, eWorldTrade, Alibaba, Ankorstore, Vegshelf, Europages, eBay, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe FMCG B2B E-Commerce Market Trends and Innovations
Real-time inventory synchronization is collapsing the information asymmetry that historically protected regional distributors from price competition. Three developments are compressing the competitive timeline for platform operators.
Dynamic pricing algorithms are absorbing demand volatility across beverage and personal care categories. These systems adjust wholesale quotations in response to manufacturer promotional calendars and seasonal consumption patterns. Mid-sized independent retailers in Portugal and Greece adopt these tools fastest, using them to optimize cash flow around constrained working capital.
France's e-invoicing mandate through the Chorus Pro platform is forcing cross-border sellers to restructure billing workflows. The requirement accelerates digitization for suppliers previously reliant on paper-based documentation. German and Belgian FMCG exporters to French retail buyers face the steepest compliance adaptation costs.
Buyer aggregation through cooperative purchasing groups is displacing individual store procurement autonomy. These collectives consolidate order volumes to extract tiered pricing concessions from platform operators. The model concentrates most visibly in Italy's fragmented grocery sector, where family-owned retailers pool demand through digitally organized buying consortia.
Europe FMCG B2B E-Commerce Market Segmentation
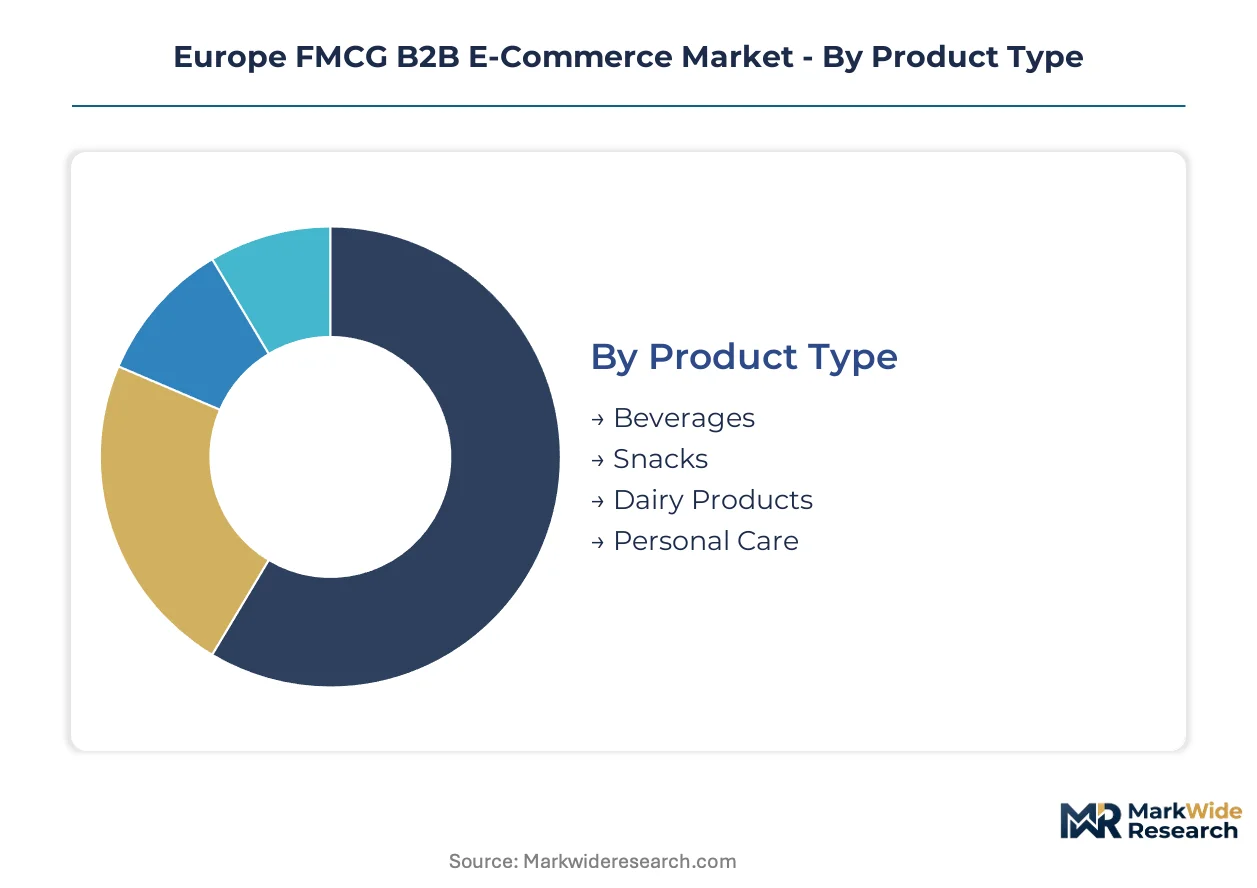
Segmentation in Europe FMCG B2B E-Commerce reveals how regulatory burdens and procurement workflows vary across product categories and service models. Platform operators calibrate compliance architectures and margin structures differently for each slice of the wholesale stack.
Product Type:
REACH registration requirements from ECHA differentiate chemical-containing segments from food-grade categories, with personal care facing the heaviest documentation burden before marketplace listing eligibility.
- Beverages:High-replenishment-frequency category with standardized pallet configurations and temperature-controlled logistics protocols. Demand concentrates in Spain and Portugal where independent grocers optimize cash flow around seasonal promotional calendars from Coca-Cola Europacific and Heineken.
- Personal Care:SKU-intensive segment requiring ingredient disclosure compliance under EU Cosmetics Regulation. Italian and French boutique stockists drive demand through Ankorstore's curated discovery tools, though REACH verification delays seller onboarding.
- Snacks:Shelf-stable logistics with lower compliance overhead than regulated categories. Polish independent retailers aggregate demand through cooperative purchasing groups.
- Dairy Products:Cold-chain dependency limits platform participation to operators with temperature-controlled fulfillment nodes. German grocery cooperatives prioritize direct distributor relationships for freshness guarantees.
Beverages sits at the top of the volume ranking, with Personal Care climbing the fastest.
Distribution Channel:
Commission stack depth varies dramatically across channel architectures, with marketplace operators capturing payment processing, logistics, and advertising layers while direct sales preserve margin for manufacturers.
- Online Marketplaces:Aggregation platforms integrating real-time inventory synchronization and dynamic pricing algorithms. BigBuy anchors Iberian penetration while Alibaba's cross-border nodes serve price-sensitive Southern European wholesalers.
- Subscription Services:Recurring-order frameworks reducing customer acquisition costs for high-velocity categories. Mid-sized Portuguese retailers deploy these for beverage replenishment to optimize working capital constraints.
- Direct Sales:Manufacturer-controlled channels bypassing platform commissions. German FMCG producers favor this model for established retail relationships.
- Wholesalers:Legacy distributors digitizing phone-and-fax ordering through API-connected procurement systems. French e-invoicing mandates through Chorus Pro accelerate their workflow restructuring.
Online Marketplaces command the deepest margin pools, while Subscription Services are expanding most quickly.
Customer Type:
Procurement autonomy varies by buyer scale, with fragmented independent operators embracing platform aggregation while consolidated chains negotiate direct terms.
- Grocery Stores:Dispersed independent networks across Poland and Italy driving natural aggregation demand. Machine-learning forecasting tools reduce their safety stock holdings.
- Restaurants:High-frequency, low-volume ordering patterns favoring dropshipping infrastructure. Spanish hospitality operators source through BigBuy's specialized fulfillment.
- Retailers:Cooperative purchasing groups in Italy consolidating volumes for tiered pricing concessions from platform operators.
- Hotels:Brand-standardized procurement with centralized decision-making. French hotel chains integrate directly with manufacturer portals.
Grocery Stores generate the highest transaction frequency, with Restaurants gaining share fastest.
Service Model:
Technical integration requirements scale with inventory visibility depth, from lightweight dropshipping to ERP-connected replenishment automation.
- Inventory Management:API-connected systems absorbing historical sales volatility through demand forecasting. Independent Italian grocers deploy these to compress order cycle latency.
- Fulfillment Services:Last-mile logistics capabilities determining platform viability in underserved regions. Romanian market entry depends on localized infrastructure.
- Drop Shipping:Low-capital model for boutique stockists curating emerging European FMCG brands. BigBuy specializes in Iberian coverage.
- Purchase Order Management:Workflow digitization for legacy distributor migration. GDPR data residency constraints complicate centralized architecture.
Inventory Management anchors platform differentiation, with Fulfillment Services showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between member states is accelerating platform migration toward jurisdictions with streamlined e-invoicing protocols and lighter VAT compliance burdens. The EU Digital Services Act harmonizes transparency requirements, yet national implementation timelines create operational gaps that agile operators exploit.
France
Independent grocers in Île-de-France and Auvergne-Rhône-Alpes are abandoning phone-based procurement for API-connected systems. The Chorus Pro e-invoicing mandate forces cross-border sellers to restructure billing workflows, accelerating digitization among legacy distributors. Paris anchors the deepest marketplace penetration, with boutique stockists driving curated brand discovery demand.
Germany
Food cooperatives in Bavaria and North Rhine-Westphalia prioritize direct manufacturer relationships for freshness guarantees, resisting platform intermediation. GDPR data residency constraints complicate centralized architecture for operators serving German buyers from non-EU cloud infrastructure. Berlin's hospitality sector experiments with subscription replenishment for beverage categories.
Poland
Dispersed small-format stores across Mazovia and Silesia lack direct distributor coverage, creating natural aggregation demand for digital wholesale intermediaries. The fragmented retail base favors marketplace models with last-mile fulfillment capabilities. Warsaw-based buying consortia consolidate volumes to extract tiered pricing concessions.
Italy
Family-owned retailers in Lombardy and Emilia-Romagna pool demand through digitally organized purchasing cooperatives. The SDI e-invoicing platform diverges from French Chorus Pro standards, creating compliance friction for pan-European operators. Milan's boutique stockists drive personal care category growth through curated discovery tools.
Spain
Independent grocers in Catalonia and Andalusia optimize cash flow around seasonal promotional calendars using dynamic pricing algorithms. Dropshipping infrastructure specializes in serving hospitality operators with high-frequency, low-volume ordering patterns. Barcelona anchors Iberian platform penetration for cross-border fulfillment nodes.
Europe FMCG B2B E-Commerce Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue curated discovery and dropshipping specialization. The vendor base stratifies across three tiers: pan-European marketplaces with cross-border fulfillment infrastructure, regional specialists with localized payment and logistics capabilities, and niche operators focused on single categories or buyer segments. Two strategic archetypes dominate: aggregation platforms capturing commission stacks across payment, logistics, and advertising layers; and vertical specialists embedding deeply in replenishment automation for high-velocity categories. Competitive moves concentrate on API interoperability investments and cooperative purchasing group partnerships.
Among platform operators, BigBuy anchors Iberian coverage with dropshipping infrastructure, Ankorstore exemplifies the curated discovery archetype connecting emerging producers with boutique stockists, and Alibaba occupies the cross-border price-sensitive wholesale position through fulfillment nodes serving Southern European buyers. These three represent distinct strategic vectors: geographic specialization, brand curation, and scale-driven cost leadership. Each sits within a defendable niche shaped by buyer procurement autonomy and working capital constraints.
| Leading Market Players |
|---|
| BigBuy |
| Cdiscount |
| Allegro |
| eWorldTrade |
| Alibaba |
| Ankorstore |
| Vegshelf |
| Europages |
| eBay |
| Others |
Pricing and Supply Chain Analysis
Independent grocers in Poland and Italy anchor procurement volume concentration, locking in subscription-based replenishment models that compress per-unit margins while securing volume commitments. Their cooperative purchasing structures extract tiered concessions from platform operators, reshaping how commission stacks distribute across payment, logistics, and advertising layers.
Pricing Analysis
Retailer markup compression dominates channel-margin dynamics as cooperative buying consortia consolidate fragmented order flows. Three-tier pricing structure across premium, standard, and economy levels stratifies by fulfillment speed and API integration depth, with boutique stockists in Milan and Paris absorbing premium tiers for curated brand access. Pricing pressure stems from fuel and packaging input volatility that operators must absorb to prevent seller attrition. Polish independent retailers exhibit highest price sensitivity due to working capital constraints, while French hotel chains demonstrate lowest sensitivity through centralized brand-standardized procurement.
Supply Chain Analysis
Fulfillment infrastructure rests on German cold-chain nodes, Spanish dropshipping hubs, and Chinese cross-border fulfillment centers serving Southern European wholesalers. Palletized beverage logistics, temperature-controlled dairy transport, and REACH-verified personal care documentation constitute critical input dependencies. Single-source vulnerability concentrates in last-mile capabilities for Romanian market entry, where localized infrastructure remains underdeveloped. Distribution feeds from manufacturer portals through API-connected procurement systems to fragmented retail endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe FMCG B2B E-Commerce functions as a stable compounder anchored by regulatory-mandated digitization that permanently shifts procurement workflows away from legacy phone-and-fax systems.
For Market Incumbents: Hedge against cooperative purchasing group consolidation by embedding deeper in replenishment automation workflows. Prioritize API interoperability investments that accelerate buyer migration from proprietary distributor ERP systems. Defensive positioning requires absorbing logistics cost spikes to maintain seller retention against Alibaba's cross-border price pressure.
For New Entrants and Emerging Players: Capture Romanian market whitespace through localized payment and fulfillment infrastructure deployment. Target underserved independent retail networks in secondary Spanish and Italian cities where cooperative buying consortia have not yet consolidated demand. Go-to-market execution should lead with subscription replenishment models for high-velocity beverage categories.
For Investors and Strategic Acquirers: Pan-European logistics operators are the most active acquirer in this space, seeking last-mile capabilities to complete geographic coverage. Long-term viability centers on platform operators with embedded demand forecasting tools and REACH compliance automation. Watch cooperative purchasing group formation velocity as the inflection signal for margin compression intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Investment | Accelerates migration from legacy distributor ERP systems in France and Germany. |
| Subscription Replenishment Launch | Reduces customer acquisition costs for Portuguese beverage wholesalers. |
| REACH Compliance Automation | Streamlines personal care seller onboarding through ECHA verification workflows. |
| Cooperative Purchasing Partnership | Locks in volume commitments from Italian family-owned retail consortia. |
| Romanian Infrastructure Buildout | Captures first-mover advantage in underserved independent retail corridors. |
Research Methodology
Bottom-up independent grocer demand modeling reconciled against top-down platform transaction tracking forms the analytical core of this study. Primary interviews with category buyers at cooperative purchasing groups, procurement directors at hospitality chains, platform operations leads, and logistics coordinators at cross-border fulfillment nodes combined with secondary validation from EU Digital Services Act implementation timelines, national e-invoicing mandate documentation, ECHA REACH registration databases, and customs trade flow records. Triangulation between buyer-reported procurement volumes and seller-reported platform commission structures ensures data integrity.
Historical trendline analysis of digital procurement adoption rates across Southern and Central European retail networks established baseline trajectory parameters. Segmentation dimensions modeled include product category compliance burden, distribution channel commission architecture, customer type procurement autonomy, and service model technical integration depth. CAGRs derive from curve-fitting observed platform transaction growth against machine-learning forecasting tool deployment rates. Forecast inputs incorporate EU member state e-invoicing rollout schedules and cooperative purchasing group formation patterns.
Regulatory implementation delays, fuel price volatility spikes, and cooperative purchasing group consolidation velocity are the dominant revision risks to modeled outcomes. Forecasts embed assumptions around API adoption timelines and seller onboarding friction coefficients. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
New Zealand E-Commerce Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
Indonesia E-Commerce Market
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
E-Commerce Search Software Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market
E-Commerce Solutions
Moldova E-Commerce Market
E-Commerce Solutions
Romania E-Commerce Market
E-Commerce Solutions
ASEAN E-Commerce Logistics Market
E-Commerce Solutions
India Digital Gift Card Market
E-Commerce Solutions
Argentina E-Commerce Market
E-Commerce Solutions
Europe Food Platform-To-Consumer Delivery Market
E-Commerce Solutions
Agricultural E-Commerce Market
E-Commerce Solutions
China Alcohol E-Commerce Market