
 North America B2B E-Commerce Market | 2026-2036
North America B2B E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
North America B2B E-Commerce Market Analytics
Subscription-based replenishment services are broadening what distributors sell beyond one-time transactions. W.W. Grainger Inc. leverages its KeepStock vending and inventory management programs to lock in recurring industrial supply relationships. Amazon Business sustains aggressive private-label expansion across MRO categories to capture share from incumbent distributors. Fastenal Company anchors its growth through onsite embedded inventory programs that tighten customer switching costs.
North America B2B e-commerce denotes commercial transactions between businesses conducted through digital platforms, encompassing electronic procurement systems, marketplace exchanges, and direct supplier portals that integrate with ERP software via API protocols and punchout catalogs. These systems automate purchase orders, invoice reconciliation, and supplier qualification to reduce procurement cycle times and administrative overhead. Manufacturing verticals dominate transaction volume given their complex bill-of-materials requirements and multi-tier supplier bases, while marketplace platforms capture the fastest expansion as buyers consolidate spend through unified search and comparison interfaces. Small enterprises remain the most underpenetrated customer type, creating a margin pool for platforms that can onboard them with simplified credit terms and guided buying workflows.
The US Federal Trade Commission scrutinizes platform pricing transparency and search ranking practices, while Canada's Competition Bureau monitors digital marketplace conduct under updated competitor collaboration guidelines. NIST cybersecurity frameworks shape supplier onboarding requirements as buyers mandate multi-factor authentication and data encryption standards. State-level sales tax nexus rules in the United States continue complicating cross-border platform compliance. Stakeholders must weigh platform consolidation against vertical specialization as procurement software vendors embed AI-driven spend analytics that could displace standalone marketplace relationships.
Market Dynamics
Cloud-based procurement platforms are unifying fragmented supplier networks across the Great Lakes manufacturing corridor, compressing transaction cycles that legacy EDI systems stretched across weeks.
Growth Catalysts
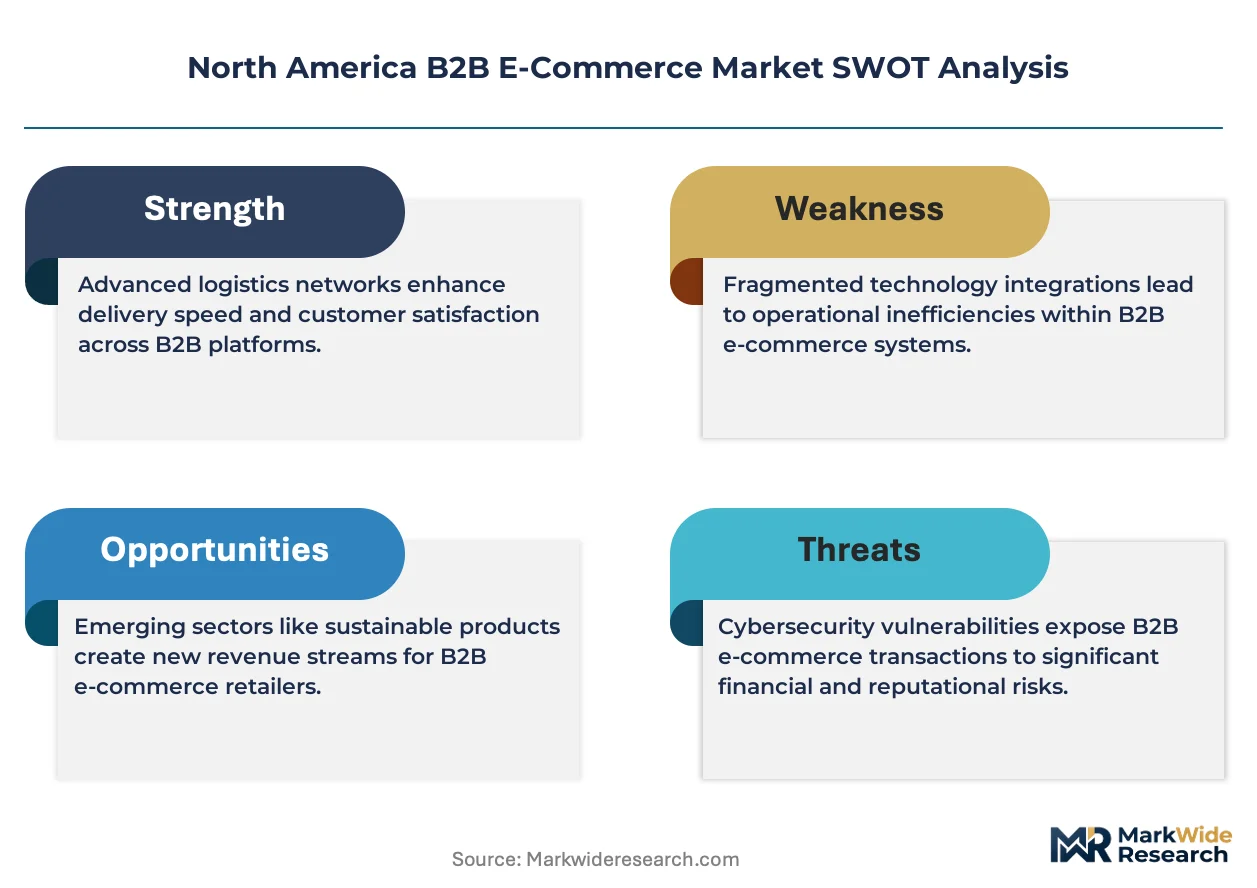
- FTC Digital Platform Transparency Rules:Tighter disclosure mandates on search rankings and pricing algorithms are accelerating buyer migration toward verified marketplace platforms with audit-ready transaction logs.
- API-First ERP Integration:Punchout catalog protocols are eliminating manual purchase order re-entry, cutting procurement administrative overhead by half for multi-tier manufacturing supply chains.
- Great Lakes Industrial Concentration:Dense clusters of automotive and heavy equipment manufacturers in Michigan, Ohio, and Ontario are creating network effects that pull adjacent suppliers onto unified platforms.
Market Restraints
- State Sales Tax Nexus Complexity:Divergent nexus thresholds across US states impose compliance burdens that disproportionately burden small marketplace vendors with limited accounting infrastructure.
- Cybersecurity Certification Costs:NIST framework mandates for multi-factor authentication and end-to-end encryption are raising onboarding barriers for legacy distributors with dated IT architectures.
- Supplier Concentration Risk:Dependence on a narrow tier of cloud infrastructure providers for marketplace hosting creates systemic vulnerability to regional outages or pricing power consolidation.
Strategic Opportunities
- Small Enterprise Credit Innovation:Simplified trade credit workflows and automated underwriting for businesses below 50 employees remain undeveloped across Canadian provincial markets.
- AI-Driven Spend Analytics Convergence:Procurement software vendors embedding predictive demand forecasting are creating openings for platforms that unify transactional marketplaces with strategic sourcing intelligence.
- Embedded Inventory Programs:Onsite vending and vendor-managed inventory systems are tightening switching costs in MRO categories where spot-buying still dominates.
Industry Challenges
- Legacy System Integration Friction:SAP and Oracle ERP environments with decades of customization require expensive middleware development to achieve real-time API connectivity with modern marketplaces.
- Supplier Data Standardization Gaps:Inconsistent product classification schemas between industrial distributors and manufacturer portals are forcing manual mapping workarounds that delay catalog launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America B2B E-Commerce Market |
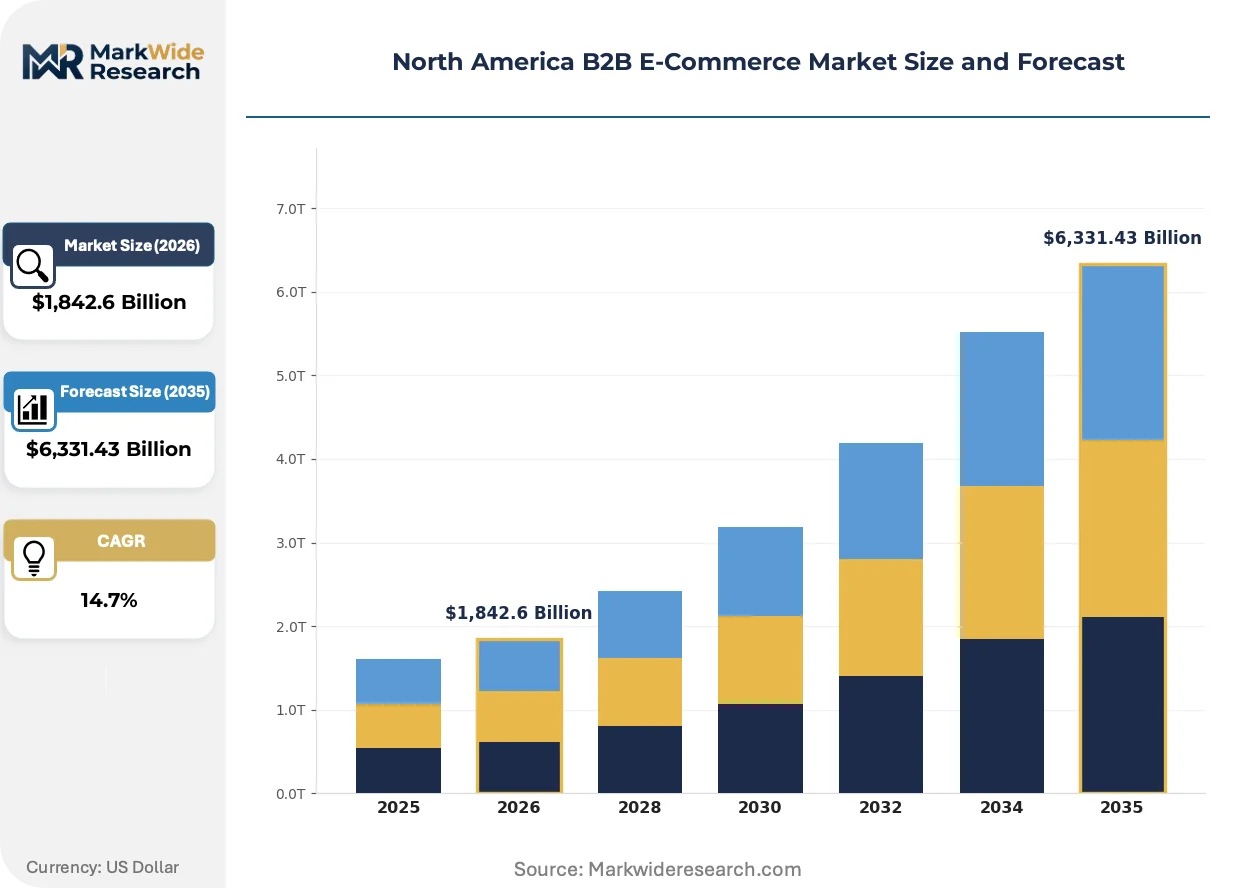
| Market Size in 2026 | $1,842.6 Billion |
| Market Size in 2035 | $6,331.43 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Industry Vertical: Manufacturing, Wholesale Trade, Retail, Healthcare Customer Type: Small Enterprises, Medium Businesses, Large Corporations, Distributors Product Type: Raw Materials, Office Supplies, Machinery, Finished Goods Sales Channel: Direct Sales, Marketplace Platforms, Distributor Networks, E-Procurement Systems |
| Companies Covered | Amazon.com Inc. (Amazon Business), W.W. Grainger Inc., Fastenal Company, MSC Industrial Supply Co., Ferguson plc, Costco Wholesale Corp, eBay Inc, Thomasnet.com, Alibaba.com, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America B2B E-Commerce Market Evolving Landscape
Artificial intelligence is compressing procurement decision cycles from days to hours, while regulatory pressure on platform transparency is reshaping how buyers evaluate vendor relationships.
Headless commerce architectures are unifying backend inventory systems with frontend purchasing interfaces across fragmented supplier networks. Large manufacturing enterprises in automotive and aerospace verticals are adopting these modular systems fastest, replacing monolithic ERP procurement modules. The technology is unifying previously siloed direct and indirect spend channels into single search and comparison interfaces.
The US Federal Trade Commission's updated guidance on digital platform pricing transparency is forcing marketplace operators to disclose algorithmic ranking factors and fee structures. Industrial buyers now demand audit trails for search result ordering and commission calculations before committing to multi-year contracts. Manufacturing procurement teams in the Great Lakes corridor are responding by requiring contractual guarantees of neutral search algorithms.
Self-service purchasing workflows are displacing traditional sales-rep-mediated ordering in maintenance, repair, and operations categories. Plant engineers and floor supervisors now expect mobile-optimized interfaces with guided buying paths that bypass procurement department gatekeeping. This behavioral shift is most visible among mid-sized manufacturers in Ontario and Illinois, where staffing constraints in procurement departments have accelerated delegation to operational end-users.
North America B2B E-Commerce Market Segmentation
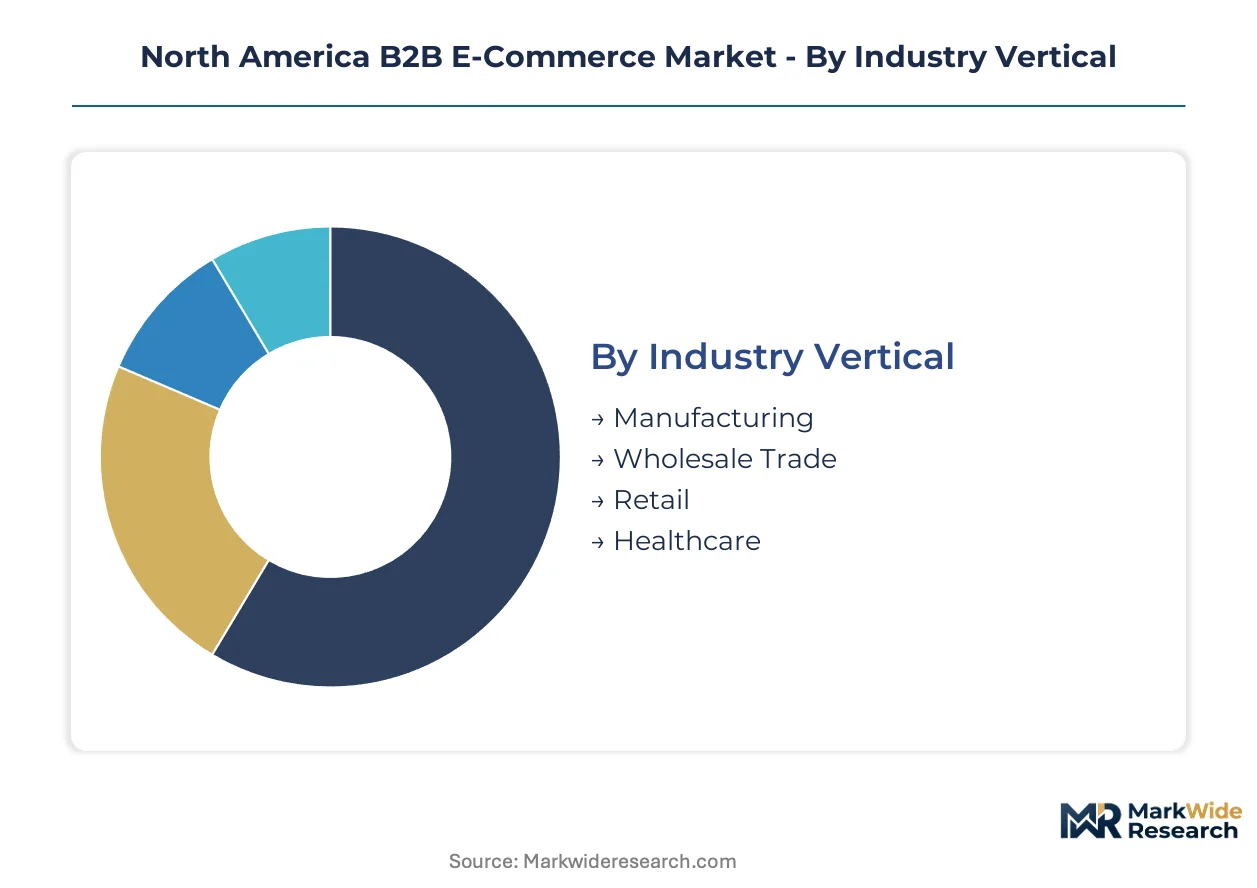
Segmentation in North America B2B e-commerce reveals how procurement complexity varies across buyer scale, supply chain position, and integration maturity. Understanding these axes exposes where platform investments concentrate and where friction persists.
Industry Vertical:
Technology intensity and supplier tier density separate verticals by platform integration depth.
- Manufacturing:Multi-tier supplier bases and complex bill-of-materials requirements drive the deepest ERP integration. Automotive and heavy equipment producers in Michigan and Ohio anchor demand for punchout catalog protocols and real-time inventory visibility.
- Wholesale Trade:Inventory velocity and margin compression push distributors toward unified search interfaces that consolidate fragmented supplier networks. Buyers here prioritize lot-size flexibility and cross-dock efficiency over customization depth.
- Retail:Seasonal demand spikes and private-label sourcing create procurement workflows balancing speed with quality assurance. Food and apparel retailers dominate transaction volume in this vertical.
- Healthcare:NIST cybersecurity mandates and FDA traceability requirements impose steeper onboarding barriers. Group purchasing organizations filter supplier access, concentrating platform relationships through intermediaries.
Mature deployment sits with Manufacturing. Newer deployment is concentrated in Healthcare.
Customer Type:
Procurement staff sophistication and credit infrastructure access determine platform engagement models.
- Large Corporations:Dedicated procurement teams with SAP or Oracle ERP environments demand API-first architectures and spend analytics dashboards. These buyers negotiate custom terms and require audit trails for FTC compliance.
- Small Enterprises:Owner-operators with limited accounting staff need guided buying workflows and simplified trade credit. Canadian provincial markets remain particularly underpenetrated for automated underwriting solutions.
- Medium Businesses:Hybrid structures blending procurement departments with operational buying authority. Self-service mobile interfaces gain traction here as staffing constraints delegate purchasing to plant engineers.
- Distributors:Inventory-heavy balance sheets drive demand for vendor-managed stock programs and consignment arrangements. Fastenal and W.W. Grainger embed vending systems that tighten switching costs in this segment.
Platform sophistication peaks with Large Corporations. Volume expansion is climbing the fastest among Small Enterprises.
Product Type:
Specification complexity and sourcing frequency shape catalog structure and search interface design.
- Raw Materials:Commodity pricing volatility and lot-traceability requirements dominate procurement criteria. Steel and polymer buyers in the Great Lakes corridor prioritize supplier qualification databases over comparison shopping.
- Machinery:Capital expenditure cycles and maintenance contracts create long evaluation horizons. Specifications require engineering validation, slowing migration from sales-rep-mediated ordering.
- Office Supplies:Standardized SKUs and predictable consumption patterns suit subscription replenishment models. Amazon Business private-label expansion targets this category aggressively.
- Finished Goods:Brand reputation and warranty terms filter supplier selection. Retailers here demand unified portals integrating direct and indirect spend channels.
Digital catalog maturity concentrates in Office Supplies. Specification-driven complexity anchors Machinery in legacy workflows.
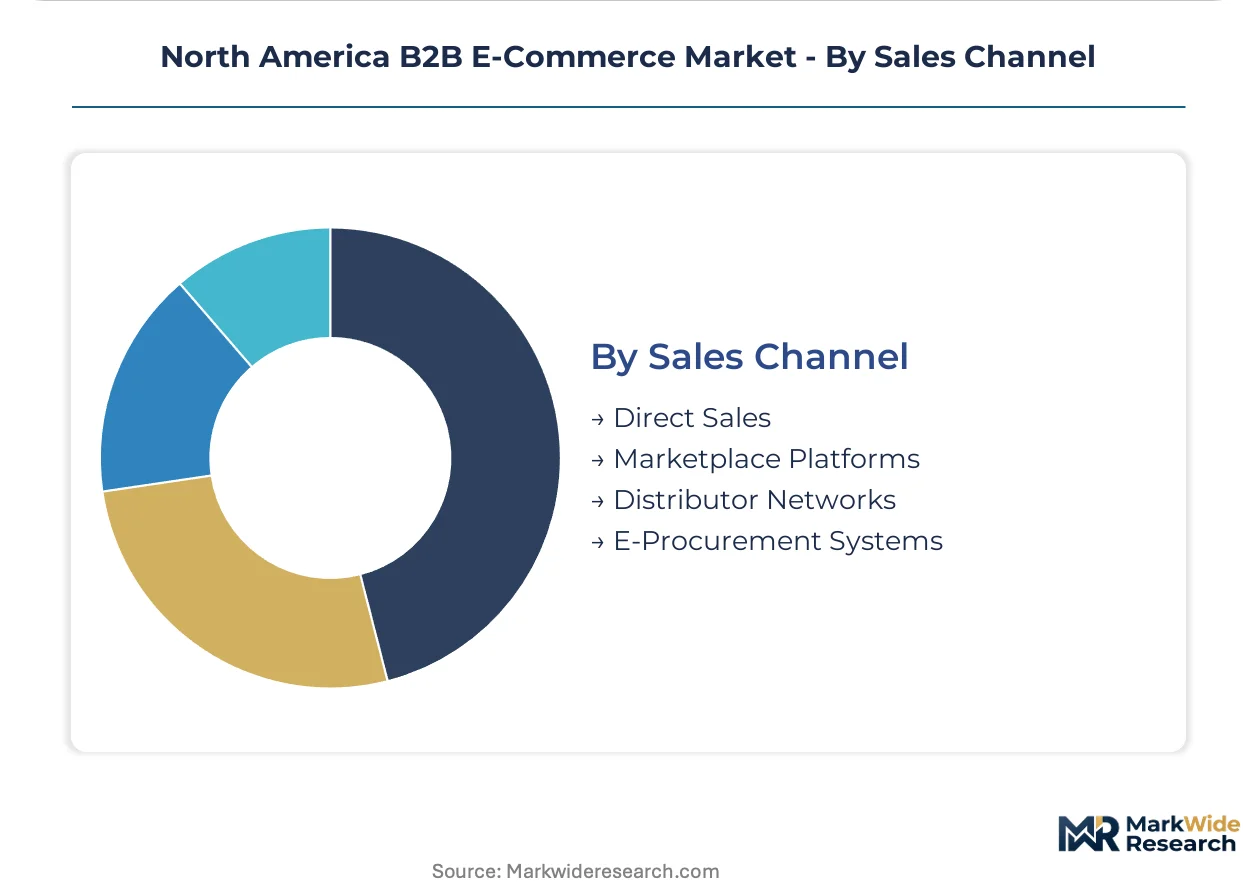
Sales Channel:
Integration architecture and fee transparency separate channels by buyer trust and switching cost.
- Marketplace Platforms:Unified search and comparison interfaces capture the steepest expansion trajectory as buyers consolidate spend. FTC transparency rules now require disclosed algorithmic ranking factors before multi-year contract commitment.
- E-Procurement Systems:Punchout catalog protocols eliminate manual purchase order re-entry, cutting administrative overhead by half. These systems anchor procurement for manufacturing enterprises with customized SAP environments.
- Direct Sales:Relationship-based negotiation persists for complex specifications and volume commitments. Machinery and raw materials buyers retain this channel for strategic sourcing.
- Distributor Networks:Embedded inventory programs and local logistics infrastructure defend position in maintenance and repair categories. Onsite vending systems create physical switching costs that pure digital platforms cannot replicate.
Transaction volume concentrates in E-Procurement Systems. Buyer migration is gaining share fastest through Marketplace Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates disproportionate platform transaction volume against Canada and Mexico, though cross-border supplier integration is compressing procurement cycle times across all three markets. Production concentration in the Great Lakes corridor pulls adjacent Canadian and Mexican suppliers onto unified cloud platforms.
United States
Automotive and heavy equipment manufacturers in Michigan and Ohio drive demand for punchout catalog protocols and real-time inventory visibility. FTC transparency mandates on search rankings and pricing algorithms are accelerating buyer migration toward verified marketplace platforms with audit-ready transaction logs. The Great Lakes industrial corridor anchors network effects that pull tier-two and tier-three suppliers onto unified procurement systems.
Canada
Ontario-based automotive parts producers and Quebec aerospace suppliers are adopting API-first ERP integration fastest among Canadian manufacturers. The Competition Bureau monitors digital marketplace conduct under updated competitor collaboration guidelines, shaping platform compliance requirements. Toronto and Montreal procurement teams are consolidating spend through unified search interfaces that compress supplier qualification timelines.
Mexico
Nuevo León and Baja California manufacturing clusters are integrating with US-based marketplace platforms to maintain just-in-time supply chain coordination. Mexico's federal economic competition authority enforces digital platform transparency standards aligned with USMCA procurement provisions. Maquiladora operations along the northern border are driving cross-border punchout catalog adoption to eliminate manual purchase order re-entry.
North America B2B E-Commerce Market Competitive Landscape
Top-tier vendors anchor cloud-based marketplace platforms with embedded inventory programs, while mid-tier distributors defend position through specialized MRO categories and regional logistics density. The vendor base stratifies across three functional tiers: integrated industrial supply platforms, distributor-led marketplace hybrids, and pure-play digital marketplaces. Two strategic archetypes dominate competitive positioning: subscription-based replenishment services that lock in recurring relationships, and onsite embedded inventory systems that tighten customer switching costs. M&A activity concentrates on vertical software capabilities, while strategic partnerships with ERP vendors are accelerating API-first integration deployment.
Within the integrated industrial supply tier, W.W. Grainger Inc. and Fastenal Company exemplify platform operators that have built captive demand through vending and vendor-managed inventory systems. Amazon.com Inc. (Amazon Business) occupies a distinct position as a scale-driven marketplace with aggressive private-label expansion across standardized procurement categories. These three anchors represent divergent competitive vectors: embedded physical infrastructure, digital-native scale, and hybrid distribution-network platforms.
| Leading Market Players |
|---|
| Amazon.com Inc. (Amazon Business) |
| W.W. Grainger Inc. |
| Fastenal Company |
| MSC Industrial Supply Co. |
| Ferguson plc |
| Costco Wholesale Corp |
| eBay Inc |
| Thomasnet.com |
| Alibaba.com |
| Others |
Value Network & Pricing Analysis
Cloud platform engineering talent concentration in Seattle and San Francisco generates labor-cost differentials that widen pricing-tier spreads between premium API-first procurement suites and economy-tier marketplace subscriptions.
Pricing Analysis
Margin tightening in economy-tier marketplace subscriptions reflects aggressive private-label expansion by digital-native operators. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in NIST cybersecurity certification grade and ERP integration depth. Cost compression in standard tiers intensifies because Amazon Business and W.W. Grainger deploy automated underwriting to capture small-enterprise volume. Large corporations with dedicated procurement teams exhibit lowest price sensitivity, while owner-operated manufacturers below fifty employees drive hardest bargain hunting.
Supply Chain Analysis
Returns and refurbishment flows for industrial vending equipment create secondary supply channels that extend asset lifecycles and compress new-equipment pricing. Manufacturing concentrates in the United States, Mexico, and Canada, with Nuevo León and Michigan anchoring automotive component production. Semiconductor chips, steel alloys, and lithium-ion cells constitute critical input dependencies. Single-source vulnerability in cloud infrastructure hosting poses systemic risk to marketplace uptime guarantees. Distribution runs through embedded inventory programs at customer facilities, tightening switching costs beyond pure digital reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud infrastructure capacity constraints among hyperscalers prop pricing power for platforms with captive data center investments, creating supply-constrained conditions that favor incumbent consolidation.
For Market Incumbents: Cement switching-cost advantages by expanding onsite vending footprints in the Great Lakes corridor before Fastenal saturates automotive plant adjacencies. Deepen backward integration into private-label MRO manufacturing to defend margin position against Amazon Business undercutting. Prioritize NIST framework pre-certification to accelerate supplier onboarding velocity. For New Entrants and Emerging Players: The price-point gap between premium API-first suites and economy marketplace subscriptions offers white-space entry for mid-tier hybrid platforms. Target Canadian provincial markets where automated trade-credit underwriting remains undeveloped. Pursue AI-driven spend analytics convergence as the go-to-market wedge, unifying transactional marketplaces with strategic sourcing intelligence. For Investors and Strategic Acquirers: Re-rating potential sits with vertical software vendors embedding procurement modules given FTC transparency mandates forcing audit-ready platform migration. Long-term viability favors operators combining marketplace liquidity with embedded physical infrastructure. Monitor API-first ERP integration adoption rates among mid-sized manufacturers as inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Inventory Program Expansion | Onsite vending systems at Michigan automotive plants tighten customer switching costs against digital-only competitors. |
| API-First ERP Integration Partnership | Punchout catalog protocols with SAP eliminate manual purchase order re-entry for multi-tier manufacturing supply chains. |
| Private-Label MRO Manufacturing Scale-Up | In-house production of maintenance supplies defends margin position against Amazon Business aggressive undercutting. |
| AI-Driven Spend Analytics Development | Predictive demand forecasting embedded in procurement software displaces standalone marketplace relationships. |
| Canadian Trade Credit Automation Launch | Automated underwriting for businesses below fifty employees captures underpenetrated provincial market volume. |
Research Methodology
Independent corroboration across procurement executives at Great Lakes automotive manufacturers, platform product managers at cloud marketplace operators, and ERP integration specialists underwrites the qualitative findings. Primary interviews with maintenance directors, plant engineers, and distributor channel partners combined with secondary validation from SEC 10-K filings, customs trade data, and FTC enforcement disclosures. Bottom-up transaction volume estimates and top-down market sizing triangulate to anchor projections.
Comparable-period anchoring to historical ERP adoption curves and EDI displacement timelines shaped the forecast window construction. Segmentation modeling spans industry vertical, customer type, product category, and sales channel dimensions across the projection horizon. CAGRs derive from logistic diffusion curves fitted to platform penetration rates, with inputs including punchout catalog deployment velocity and NIST framework compliance adoption.
Inputs from procurement software vendors and industrial distributor executives were available through the study window; gaps in small-enterprise credit-performance data introduce uncertainty bands around automated underwriting expansion forecasts. Practitioners should monitor FTC algorithmic transparency enforcement intensity and cloud infrastructure pricing volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
China Online Trading Platform Market
E-Commerce Solutions
Russia Alcohol E-Commerce Market
E-Commerce Solutions
Finland E-Commerce Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Panama E-Commerce Market
E-Commerce Solutions
Hong Kong E-Commerce Market
E-Commerce Solutions
Moldova E-Commerce Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
FMCG B2B E-Commerce Market
E-Commerce Solutions
United Kingdom E-Commerce Logistics Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Apparel Market
E-Commerce Solutions
Clothing E-Commerce Platform Market
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
United States E-Commerce Logistics Market