
 E-Commerce Lockers Market | 2026-2036
E-Commerce Lockers Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce Lockers Market Analysis
Aluminum is expanding its share in locker housing as manufacturers seek weight reduction and corrosion resistance against legacy steel enclosures. InPost S.A. leverages Europe's dense parcel network to sustain high utilization rates across its automated terminal base. KEBA AG anchors its position through electromechanical lock expertise and industrial-grade control systems. Amazon competes via proprietary locker ecosystems integrated with its fulfillment architecture.
E-commerce lockers are self-service, electronically controlled storage units designed for secure parcel deposit and retrieval, typically featuring PIN codes, QR scanning, or mobile-app authentication with compartment dimensions ranging from envelope slots to bulk cargo bays. Their primary purpose is to decouple delivery and collection timing, reducing failed delivery costs and consumer inconvenience. Smart lockers lead the type category due to embedded IoT sensors and real-time inventory tracking that command premium positioning. Logistics providers dominate end-user deployment as they seek to control last-mile infrastructure and reduce dependency on residential door delivery. Indoor installations retain the largest footprint, though outdoor units with weatherproofing and thermal management represent the fastest-growing installation sub-segment.
FCC guidelines on wireless device certification shape connectivity module selection for Wi-Fi and cellular-enabled units in the United States. The EU AI Act and GDPR impose data governance requirements on facial recognition and consumer tracking features embedded in locker interfaces. OSHA workplace safety standards influence maintenance access design and electrical enclosure ratings for indoor deployments. Stakeholders must weigh modular hardware architectures against integrated software stacks as connectivity protocols fragment across regional telecom infrastructures.
Market Dynamics
Last-mile delivery economics are forcing logistics operators toward automated pickup infrastructure as labor costs and failed delivery rates erode margins on residential drop-offs. Dense urban networks favor locker consolidation over individual home delivery.
Growth Catalysts
- EU Green Deal:Emissions reduction mandates push parcel carriers toward consolidated delivery points that cut per-package transport mileage and vehicle counts.
- Online grocery fulfillment:Temperature-controlled locker compartments enable fresh food retailers to offer flexible pickup without cold-chain breakage.
- Aluminum housing adoption:Corrosion-resistant, lightweight enclosures reduce installation complexity and extend outdoor unit service life in coastal and high-humidity environments.
Market Restraints
- Steel price volatility:Legacy locker manufacturers face margin compression when commodity steel spikes, slowing capacity expansion timelines.
- Real estate access costs:Prime urban locations for locker placement command premium lease rates that strain operator unit economics.
- GDPR facial recognition friction:Biometric authentication features face deployment hurdles across EU member states due to strict data processing consent requirements.
Strategic Opportunities
- Rural and suburban penetration:Lower locker density in exurban zones creates first-mover advantage for operators willing to subsidize initial placement.
- IoT sensor convergence:Integration of environmental monitoring, occupancy detection, and predictive maintenance analytics transforms lockers into data collection nodes.
- OSHA indoor safety standards:Compliance-driven retrofit cycles create replacement demand for aging locker installations in warehouse and retail backroom environments.
Industry Challenges
- Cyber-physical security expertise:Electromechanical lock engineering and embedded systems firmware development require talent pools concentrated in Central European industrial zones.
- Legacy WMS integration:Warehouse management system connectivity protocols fragment across regional logistics software vendors, complicating deployment standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce Lockers Market |
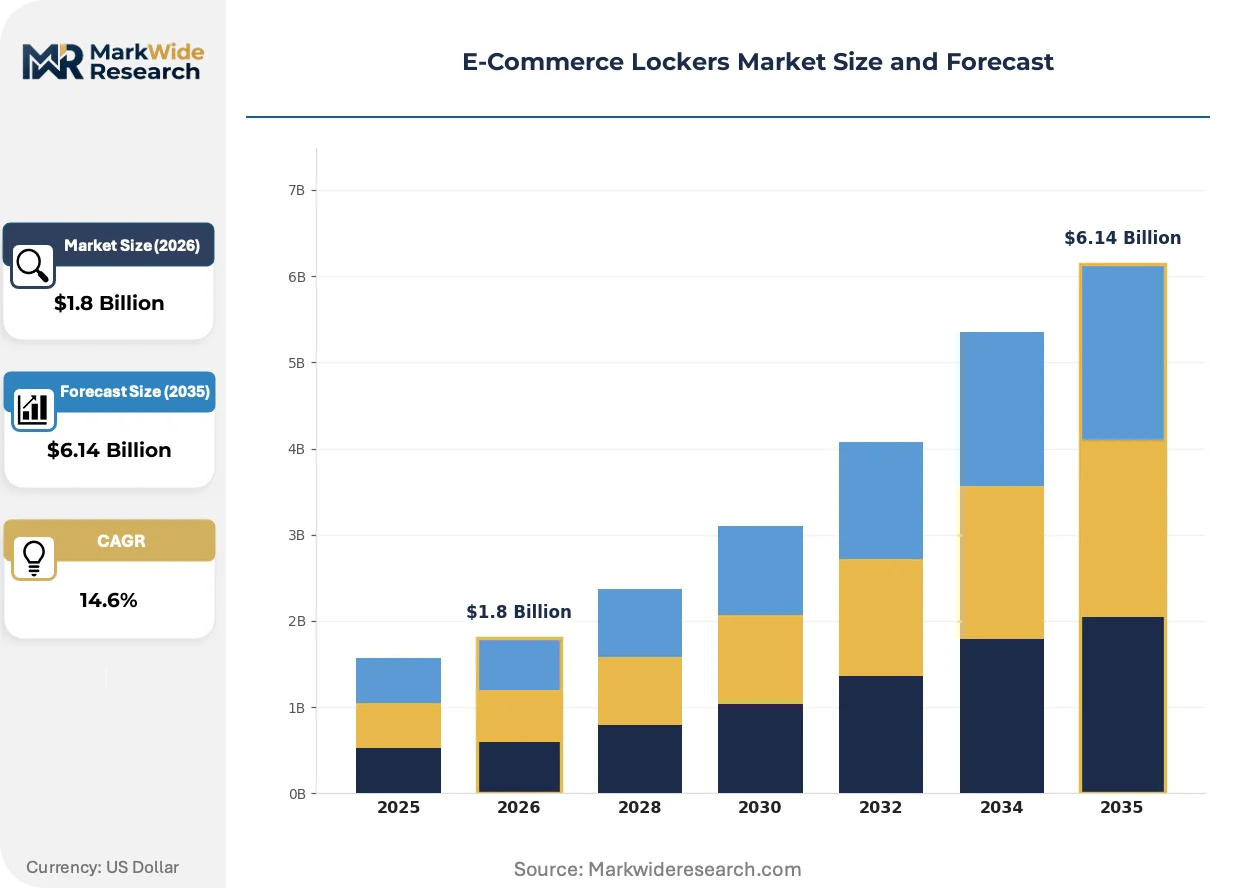
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Smart Lockers, Modular Lockers, Wall-Mounted Lockers, Delivery Lockers End User: Retailers, Logistics Providers, Urban Venues, Educational Institutions Installation: Indoor, Outdoor, Automated, Manual Connectivity: Wi-Fi, Cellular, Bluetooth, Ethernet |
| Companies Covered | InPost S.A., Quadient S.A., KEBA AG, Cleveron AS, ASSA ABLOY, Pitney Bowes, Inc., Amazon, Ricoh, Luxer Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce Lockers Market Emerging Trajectories
Hardware-software integration is deepening as locker systems evolve from passive storage to active nodes in real-time supply chain orchestration. Operators now treat locker networks as programmable infrastructure rather than fixed assets.
Embedded IoT sensor arrays are consolidating control over locker fleet operations. Electromechanical locks now incorporate vibration, temperature, and door-position telemetry that feeds predictive maintenance algorithms. Logistics providers with dense terminal networks leverage this data to optimize technician dispatch and reduce field failure rates. The technology is consolidating operational visibility previously scattered across separate building management and parcel tracking systems.
FCC wireless device certification requirements are reshaping connectivity module procurement for North American deployments. Wi-Fi and cellular radio configurations must undergo extensive electromagnetic compatibility testing before locker firmware updates reach production. Manufacturers serving US markets maintain separate hardware SKUs to isolate certified configurations from European variants. This regulatory fragmentation adds inventory complexity but creates compliance moats against unvetted import competition.
Buyer procurement patterns are compressing vendor selection cycles as logistics operators consolidate supplier relationships. Large parcel networks now favor framework agreements covering hardware, software, and maintenance across multi-year horizons. This shift displaces transactional purchasing of individual locker units. Germany and the Netherlands exhibit the most advanced procurement consolidation, with operators bundling locker deployment into broader last-mile infrastructure tenders.
E-Commerce Lockers Market Segmentation
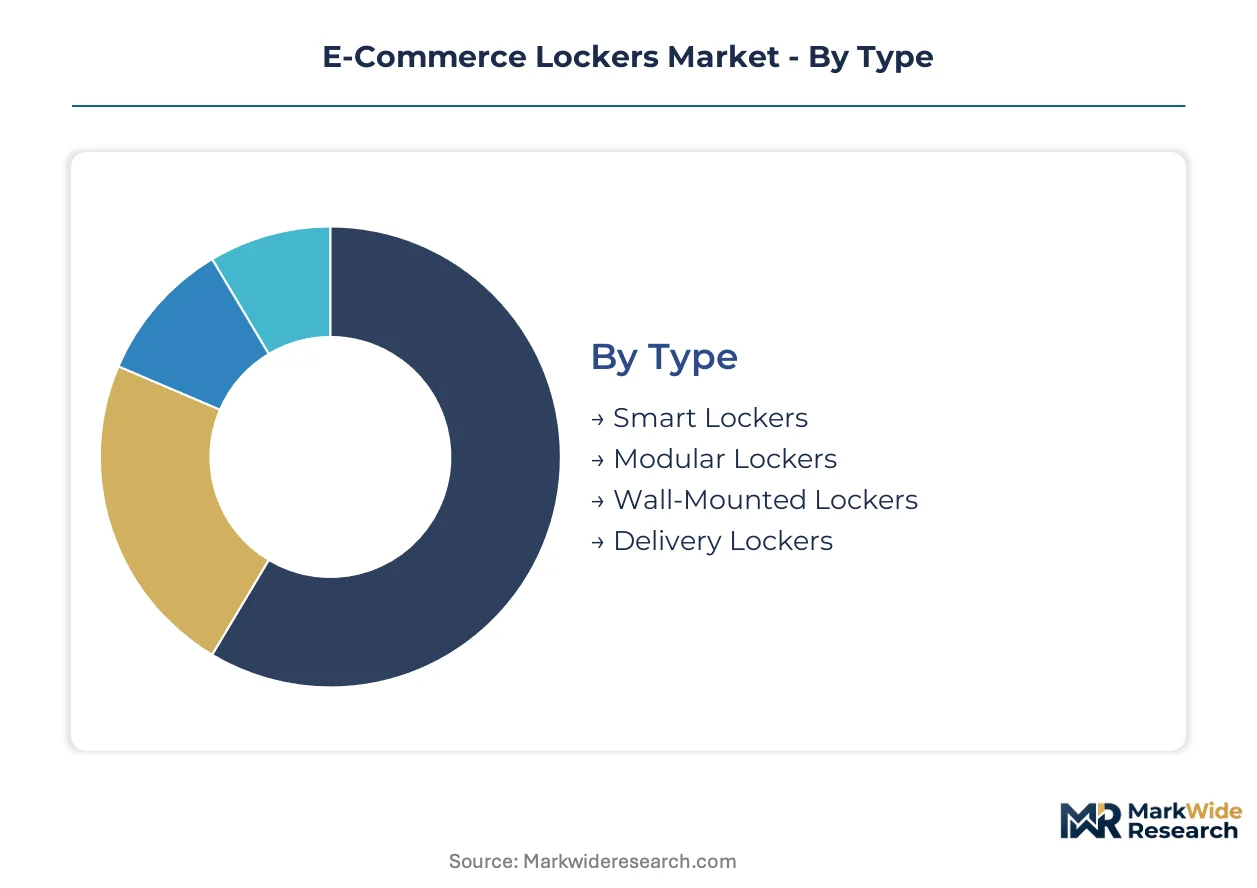
Locker deployment varies sharply by operational environment and connectivity requirements. Segment selection determines capital intensity, maintenance burden, and integration complexity with existing fulfillment systems.
Type:
Technology architecture defines functional capability and price positioning across the locker hardware spectrum.
- Smart Lockers:Embedded IoT sensors enable real-time inventory tracking, environmental monitoring, and predictive maintenance alerts. Demand concentrates among logistics providers operating dense urban networks in Germany, driven by pressure to minimize failed delivery costs and optimize technician dispatch.
- Modular Lockers:Configurable compartment arrays allow operators to resize units based on seasonal volume fluctuations or location-specific parcel mix. Retailers in the Netherlands favor these for phased rollout across store networks, balancing initial capital outlay against expansion flexibility.
- Wall-Mounted Lockers:Space-constrained installations in retail backrooms and apartment lobbies.
- Delivery Lockers:Basic deposit-only units without integrated authentication or tracking systems.
Mature deployment sits with Delivery Lockers. Newer deployment is concentrated in Smart Lockers.
End User:
Procurement authority and utilization patterns diverge across buyer categories with distinct operational priorities.
- Logistics Providers:These operators treat locker networks as owned infrastructure to control last-mile economics and reduce residential delivery failure rates. Dense terminal deployment in German urban corridors supports high utilization through consolidated pickup points.
- Retailers:Grocery and general merchandise chains deploy temperature-controlled and ambient units to enable click-and-collect fulfillment without store congestion. Fresh food retailers in France drive demand for compartments with thermal management capabilities.
- Urban Venues:Transit hubs, shopping centers, and municipal facilities offering locker placement for foot traffic monetization.
- Educational Institutions:Campus-based installations serving student residential and administrative mail needs.
Mature deployment sits with Logistics Providers. Newer deployment is concentrated in Urban Venues.
Installation:
Physical siting determines weatherproofing requirements, security protocols, and real estate access costs.
- Indoor:Climate-controlled environments eliminate thermal management hardware and reduce corrosion exposure. Warehouse backrooms and retail service areas in Belgium and Luxembourg host the bulk of existing installed base.
- Outdoor:Weatherproofed enclosures with heating, cooling, and moisture sealing enable street-facing and parking-lot placement. Coastal municipalities in Spain and Portugal specify aluminum housings for salt-air corrosion resistance.
- Automated:Robotic retrieval systems for high-throughput distribution centers.
- Manual:Staff-assisted parcel handling without self-service authentication.
Mature deployment sits with Indoor. Newer deployment is concentrated in Outdoor.
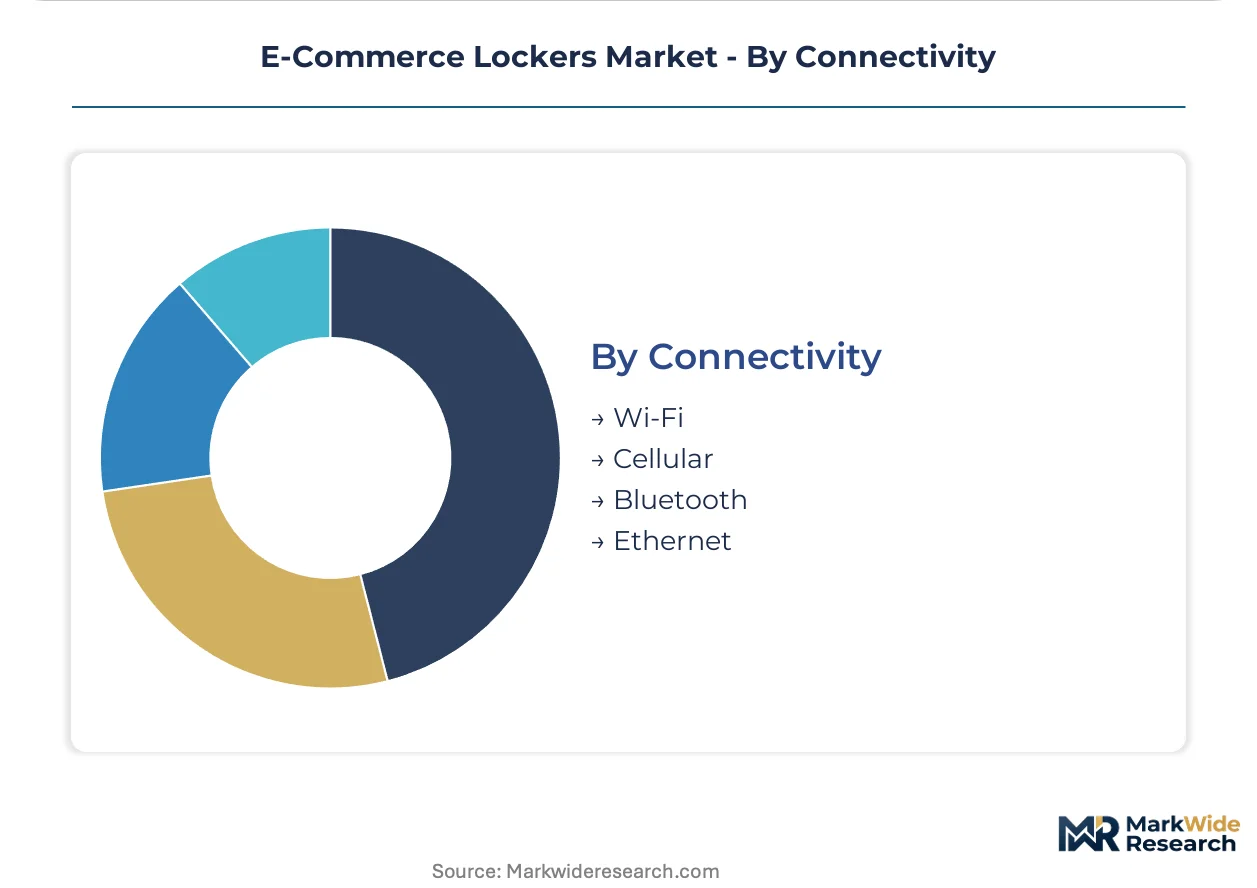
Connectivity:
Communication protocol selection shapes hardware certification requirements and ongoing data costs.
- Cellular:LTE and 5G modules enable deployment in locations lacking fixed infrastructure, with subscription fees embedded in operational budgets. Rural and suburban expansions in Poland and Czech Republic rely on cellular backhaul where fiber penetration remains uneven.
- Wi-Fi:Lower recurring costs suit indoor installations with reliable enterprise network coverage. German logistics hubs with existing warehouse Wi-Fi infrastructure favor this protocol to minimize telemetry expenses.
- Bluetooth:Short-range authentication for mobile-app-driven retrieval without continuous cloud connection.
- Ethernet:Wired reliability for high-security indoor deployments with permanent network infrastructure.
Mature deployment sits with Wi-Fi. Newer deployment is concentrated in Cellular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German logistics operators deploy the densest locker networks in Europe, while Polish and Czech carriers expand cellular-connected units into underserved suburban corridors. Urban consolidation mandates and emissions regulations reshape infrastructure investment across continental markets.
Germany
Dense parcel terminal networks in Berlin, Hamburg, and the Rhine-Ruhr corridor sustain high utilization rates for logistics providers. The EU Green Deal drives carrier consolidation of last-mile delivery points to reduce per-package vehicle mileage. Bavaria hosts industrial clusters developing electromechanical lock systems and predictive maintenance firmware for smart locker fleets.
Poland
Rural and suburban expansion creates demand for cellular-enabled lockers where fiber infrastructure remains uneven. The country's national telecommunications regulator shapes connectivity module certification requirements for LTE and 5G deployments. Warsaw and Krakow anchor logistics hub development, with operators subsidizing initial locker placement to capture first-mover advantage in exurban zones.
France
Fresh food retailers in Paris and Lyon drive temperature-controlled compartment installations for click-and-collect grocery fulfillment. GDPR and the EU AI Act impose strict consent requirements on biometric authentication features, slowing facial recognition deployment. The Île-de-France region concentrates smart locker manufacturing partnerships between logistics operators and industrial automation specialists.
Spain
Coastal municipalities specify aluminum locker housings for salt-air corrosion resistance in Barcelona, Valencia, and Málaga installations. Outdoor weatherproofing with thermal management represents the fastest-growing installation sub-segment. Andalusia and Catalonia lead street-facing placement negotiations with municipal authorities for parking-lot and transit-adjacent locker networks.
Netherlands
Retailers favor modular locker configurations for phased rollout across store networks, balancing capital outlay against expansion flexibility. The Randstad conurbation exhibits the most advanced procurement consolidation, with operators bundling locker deployment into broader last-mile infrastructure tenders. Rotterdam and Amsterdam host pilot programs integrating predictive maintenance analytics with existing warehouse management systems.
E-Commerce Lockers Market Vendor Landscape
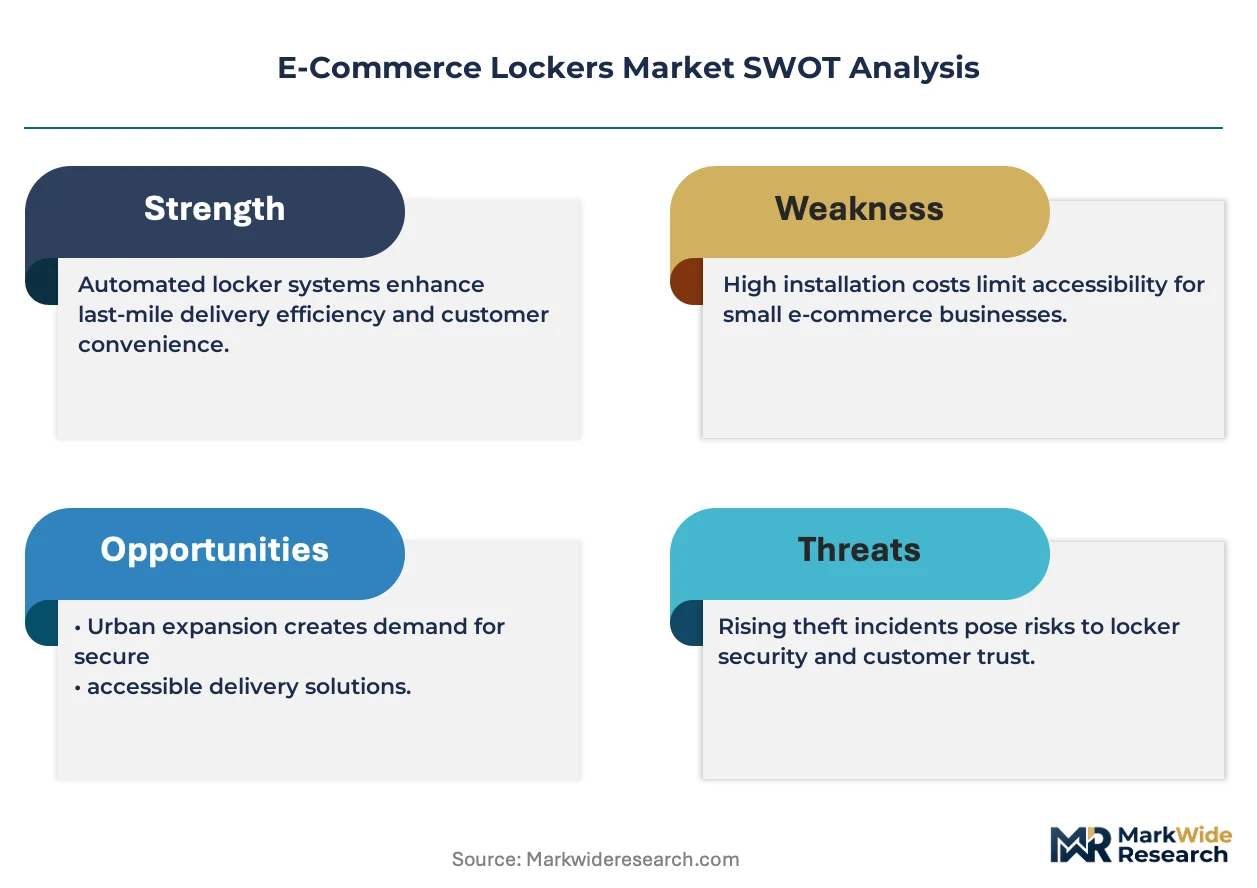
Branded specialists and contract manufacturers split share differently across segments, with logistics operators favoring framework agreements covering hardware, software, and maintenance over transactional unit purchases. Market structure tilts toward consolidation among parcel network operators with captive terminal infrastructure, while component suppliers compete on electromechanical reliability and firmware integration. Three archetypes dominate: dense-network parcel carriers, industrial automation specialists, and proprietary ecosystem operators. Competitive moves center on multi-year infrastructure tenders and modular hardware architectures that accommodate regional connectivity fragmentation.
Among European parcel network operators, InPost S.A. and Quadient S.A. occupy positions exemplifying the dense-terminal archetype, leveraging high-utilization automated bases across urban corridors. KEBA AG anchors the industrial automation tier through electromechanical lock expertise and control system integration. These three represent distinct competitive vectors—network scale, component specialization, and system integration—that shape procurement decisions across German, Polish, and Benelux logistics markets.
| Leading Market Players |
|---|
| InPost S.A. |
| Quadient S.A. |
| KEBA AG |
| Cleveron AS |
| ASSA ABLOY |
| Pitney Bowes, Inc. |
| Amazon |
| Ricoh |
| Luxer Corporation |
| Others |
Supply Flow & Price Mechanics
Framework agreements bundling hardware, software, and maintenance across multi-year horizons are displacing transactional unit purchases, forcing manufacturers to absorb inventory complexity from regional connectivity fragmentation and FCC certification isolation. This procurement consolidation in Germany and the Netherlands compresses vendor margins while rewarding suppliers with modular architectures that accommodate electromechanical lock customization and IoT sensor integration.
Pricing Analysis
Volume commitments against margin preservation splits the market between hyperscale logistics operators capturing scale discounts and mid-tier retailers facing cost compression from steel price volatility. Three-tier pricing structure across premium smart lockers, standard modular units, and economy delivery-only models differentiates on IoT sensor density and predictive maintenance bundling. Price erosion runs through the economy tier as Chinese contract manufacturers expand aluminum housing production. Logistics providers with dense terminal networks exhibit lowest price sensitivity; independent urban venue operators show highest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from InPost and Quadient, while distribution runs through industrial automation distributors for mid-market logistics operators in Poland and Czech Republic. Electromechanical lock production concentrates in Germany and Austria; aluminum extrusion and PCB assembly draw from China and Taiwan. Legacy steel enclosure supply rests on commodity spot markets vulnerable to volatility. Single-source vulnerability sits with embedded firmware development talent pools concentrated in Bavaria and Baden-Württemberg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where procurement bundling and framework agreement dominance force sub-scale hardware vendors toward exit or acquisition by dense-network operators seeking captive supply.
For Market Incumbents: Lock in multi-year maintenance contracts with logistics providers before cellular connectivity standardization erodes service revenue differentiation. Backward integration into aluminum housing extrusion mitigates commodity exposure from steel volatility. Prioritize electromechanical lock firmware development in Bavarian industrial clusters to defend against Chinese contract manufacturer encroachment on standard locker units. For New Entrants and Emerging Players: Municipal transit authorities in Spain and Portugal represent underpenetrated placement channels with lower competitive density than German logistics corridors. Target coastal municipalities specifying corrosion-resistant aluminum housings for salt-air environments. Lead with outdoor weatherproofing expertise and thermal management capabilities rather than competing on indoor unit cost. For Investors and Strategic Acquirers: Re-rating potential sits with industrial automation specialists possessing electromechanical lock IP and predictive maintenance firmware capabilities given IoT sensor convergence transforming lockers into data collection nodes. Five-to-ten year viability favors vendors with modular hardware architectures accommodating regional telecom infrastructure fragmentation. Watch for cellular connectivity standardization across EU member states as inflection signal compressing connectivity module inventory complexity.| Strategic Initiative | Industry Significance |
|---|---|
| Framework Agreement Consolidation | Bundled hardware-software-maintenance tenders in Germany displace transactional purchasing and compress vendor margins. |
| Aluminum Housing Transition | Corrosion-resistant enclosures extend outdoor unit service life in Spanish coastal municipalities and high-humidity environments. |
| Predictive Maintenance Integration | IoT sensor telemetry feeding technician dispatch optimization reduces field failure rates for dense-network operators. |
| Cellular Connectivity Expansion | LTE and 5G modules enable Polish and Czech suburban penetration where fiber infrastructure remains uneven. |
| Temperature-Controlled Compartment Development | Thermal management capabilities capture French fresh food retailer demand for click-and-collect grocery fulfillment. |
Methodological Framework
Multi-period observation of locker deployment density, utilization rates, and procurement pattern shifts anchored the trend analysis, supplemented by interviews with logistics network planners, electromechanical lock engineers, retail fulfillment directors, municipal transit procurement officers, and IoT sensor integration specialists. Secondary validation drew from EU Green Deal implementation tracking, FCC wireless device certification databases, GDPR enforcement actions on biometric authentication, and customs records of aluminum and steel enclosure imports. Bottom-up unit economics modeling triangulated against top-down market sizing from parcel volume growth projections.
Input-output matrices mapped connectivity protocol selection, installation environment requirements, and end-user procurement authority across segmentation dimensions including locker technology architecture, deployment location, and buyer category. CAGRs were derived from logistic curve fitting to adoption saturation thresholds, with cross-validation against historical penetration patterns in comparable automated infrastructure markets. Industry-specific forecast inputs incorporated EU emissions reduction mandate timelines and last-mile delivery cost elasticity estimates from German carrier financial disclosures.
Caveats apply where GDPR facial recognition enforcement actions, steel commodity price spikes, or real estate access cost inflation could materially shift the outlook for outdoor deployment economics and authentication feature roadmaps. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Alcohol E-Commerce Market
E-Commerce Solutions
3D Interactive Ticketing Solutions Market
E-Commerce Solutions
Philippines E-Commerce Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
Albania E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Logistics Market
E-Commerce Solutions
Turkey E-Commerce Market
E-Commerce Solutions
Italy E-Commerce Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
North America FMCG B2B E-Commerce Market
E-Commerce Solutions
Greece E-Commerce Market
E-Commerce Solutions
Global Live E-Commerce Market
E-Commerce Solutions
Saudi Arabia E-Commerce Market
E-Commerce Solutions
Direct-To-Consumer Test Market