
 Italy Electric Vehicles Battery Anode Market | 2026-2036
Italy Electric Vehicles Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Electric Vehicles Battery Anode Market Insights
Aftermarket service revenue for anode diagnostics and cell refurbishment is fragmenting as OEMs internalize lifecycle management. Umicore SA leverages its European metallurgical base to sustain closed-loop graphite recovery operations. SGL Carbon anchors German-Italian supply corridors with specialized carbon precursor manufacturing. POSCO Future M competes through Korean-Japanese process licensing adapted to EU material compliance frameworks.
Italy electric vehicles battery anode denotes the negative electrode material, typically synthetic or natural graphite with particle sizes of 5–20 microns and specific capacities near 350–370 mAh/g, engineered to intercalate lithium ions during charge cycles in rechargeable cells. Silicon-doped composites and lithium titanate variants are gaining traction among Tier-1 suppliers seeking higher energy density for premium passenger vehicle platforms. Graphite retains manufacturing scale advantages and dominates current procurement volumes from OEMs, though solid-state battery chemistry roadmaps are redirecting R&D funding toward silicon-carbon architectures.
EU Green Deal emission benchmarks, REACH chemical registration protocols, and CE marking under the EU Battery Regulation govern anode material composition, carbon footprint disclosure, and second-life traceability across Italian production lines. The F-Gas Regulation restricts fluorinated solvent use in electrode coating, compelling reformulation of slurry binders and drying processes. Stakeholders must monitor how delegated acts under the EU Battery Regulation reshape due diligence obligations for imported synthetic graphite and silicon feedstocks.
Market Dynamics
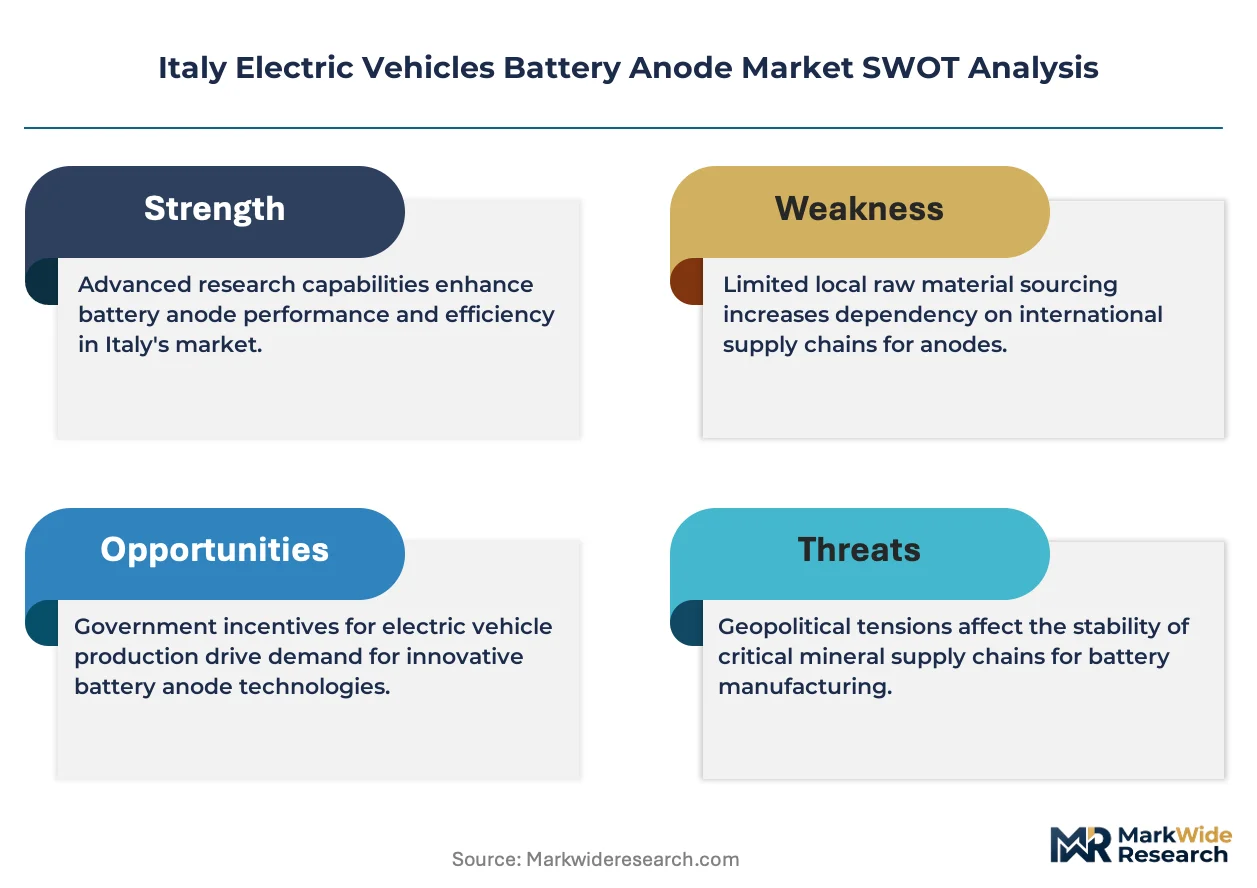
EU Green Deal decarbonization mandates and the EU Battery Regulation are compressing certification timelines for anode suppliers while redirecting capital toward closed-loop material recovery systems across Italy's northern industrial corridor.
Growth Catalysts
- Domestic passenger EV production:Accelerating OEM assembly volumes in Turin and Milan are pulling anode procurement toward localized supply agreements.
- REACH chemical registration protocols:Standardized material disclosure requirements are reducing supplier qualification friction for Italian cell manufacturers.
- Silicon-carbon composite architectures:Higher energy density formulations are penetrating premium passenger platforms as solid-state roadmaps mature.
Market Restraints
- Synthetic graphite feedstock concentration:Dependence on Asian precursor suppliers exposes Italian anode producers to shipping cost volatility and carbon border adjustment exposure.
- F-Gas Regulation coating restrictions:Fluorinated solvent bans are forcing slurry reformulation and capital-intensive drying process retrofits.
- Lithium titanate energy density ceiling:Lower specific capacity versus graphite limits adoption to heavy-duty commercial segments with extreme cycle-life requirements.
Strategic Opportunities
- Southern Italy cell manufacturing:Underdeveloped anode supply infrastructure in Sicily and Apulia creates first-mover positioning for integrated precursor-to-coating facilities.
- Second-life traceability mandates:EU Battery Regulation due diligence obligations are opening revenue streams for diagnostic and refurbishment service providers.
- Solid-state electrolyte convergence:Sulfide and oxide ceramic interfaces are driving silicon anode interface engineering partnerships between material suppliers and cell designers.
Industry Challenges
- Electrochemical engineering talent scarcity:Specialized lithium-ion intercalation expertise concentrates in German and Korean research clusters, complicating Italian pilot line staffing.
- CE marking timeline compression:Accelerated EU Battery Regulation delegated acts are squeezing certification windows for imported synthetic graphite batches.
- Slurry coating equipment capex intensity:Double-sided electrode coating lines require eight-figure euro investments, constraining mid-tier supplier scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Electric Vehicles Battery Anode Market |
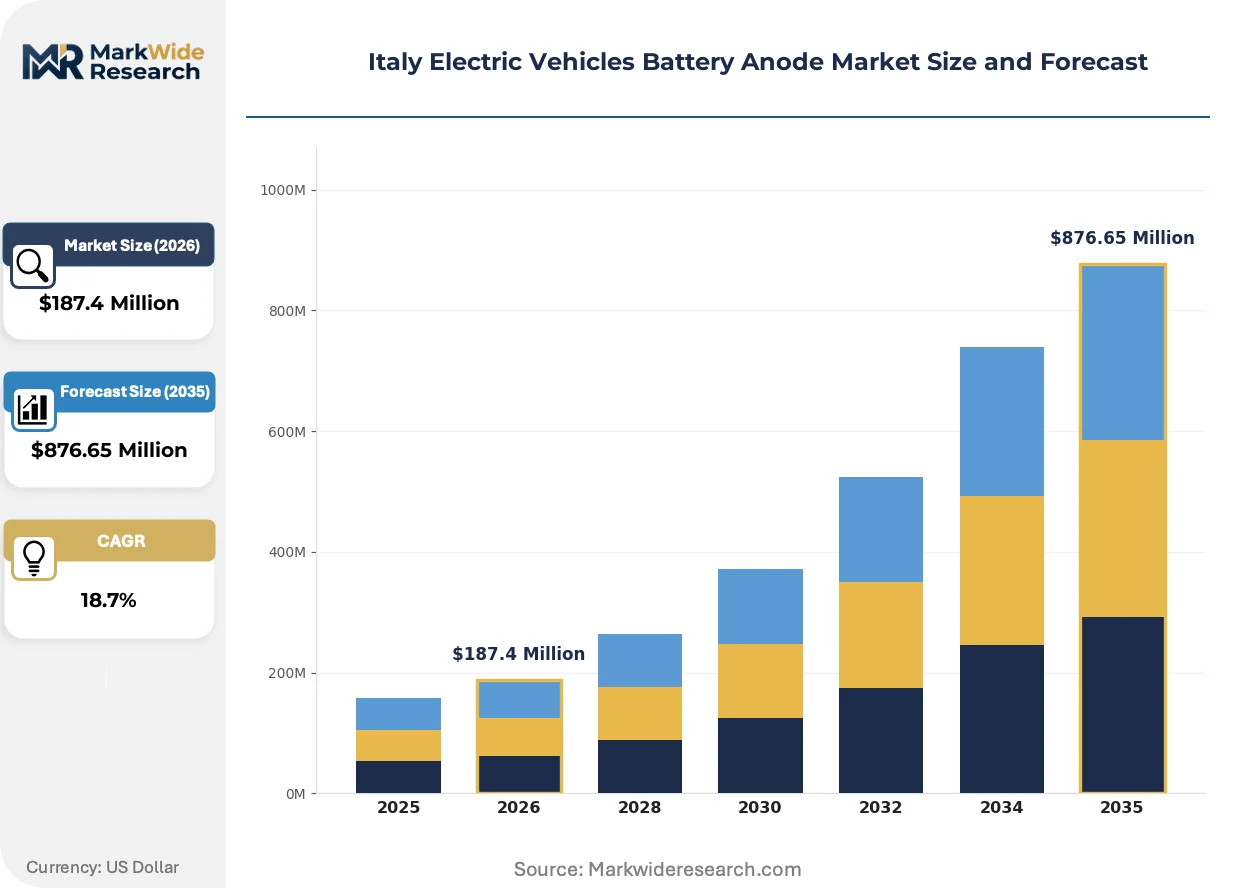
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Graphite, Silicon, Lithium Titanate, Composite Materials End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Battery Chemistry: Lithium-Ion, Solid-State, Nickel-Manganese-Cobalt, Lithium Iron Phosphate Geotechnical Use: Passenger Vehicles, Commercial Vehicles, Industrial Applications, Others |
| Companies Covered | BASF SE, Umicore SA, Solvay SA, Arkema SA, Sumitomo Chemical Co., Ltd, SGL Carbon, Resonac, Mitsubishi Chemical Group, POSCO Future M, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Electric Vehicles Battery Anode Market Trends and Innovations
Anode material architectures are fragmenting across performance tiers as OEMs diverge on solid-state commercialization timelines and silicon doping ratios. This divergence is compressing R&D cycles while expanding the supplier base for specialized carbon precursors.
Silicon-doped graphite composites are migrating from laboratory validation to volume procurement contracts among premium European passenger EV platforms. BMW and Mercedes-Benz cell engineering teams have qualified 10-15% silicon loadings for 2026 model year battery packs. This migration is compressing pricing premiums for conventional synthetic graphite and forcing incumbent suppliers to accelerate composite coating investments.
The EU Battery Regulation's carbon footprint disclosure rules are tightening material provenance documentation across Italian production lines. Cell manufacturers must now submit lifecycle emissions data for anode active materials to receive CE marking approval. Northern Italian engineering clusters are responding by integrating blockchain traceability tools into supplier qualification workflows.
Fleet operators and energy storage integrators are unbundling after-sales service contracts from initial equipment procurement. Third-party cell refurbishment providers in Emilia-Romagna are capturing diagnostic revenue previously internalized by OEM captive service networks. This unbundling is most visible in commercial vehicle segments where battery residual value guarantees dominate financing structures.
Italy Electric Vehicles Battery Anode Market Segmentation
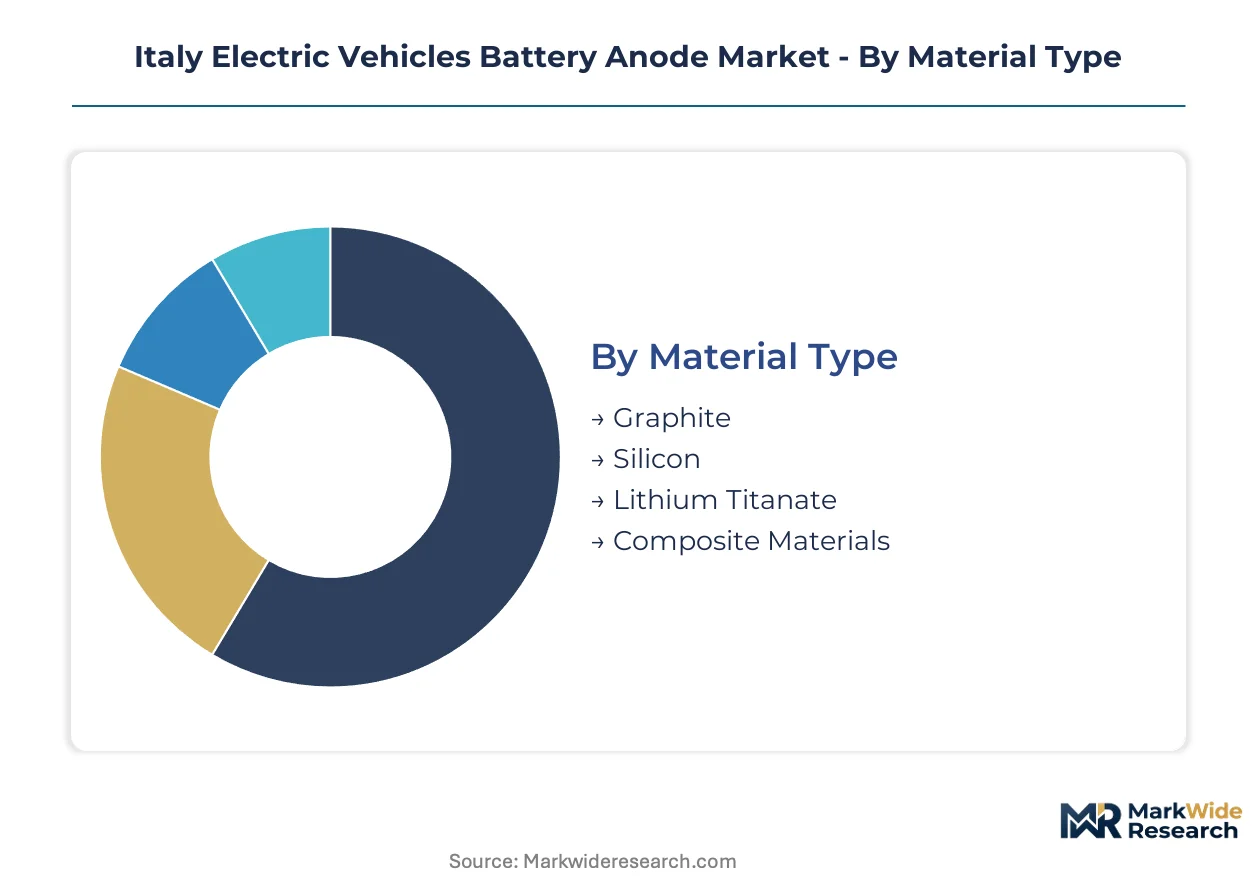
Anode procurement patterns in Italy diverge sharply across material grades and end-user tiers. Cell manufacturers qualify suppliers against distinct cycle-life and energy density thresholds, creating segmented demand pools with minimal supplier overlap.
Material Type:
Cycle times vary from six-month qualification windows for graphite to multi-year validation for silicon composites. Procurement velocity concentrates in materials with established coating infrastructure.
- Graphite:Synthetic and natural variants with 5–20 micron particle sizes dominate current procurement volumes. Northern Italian cell pilot lines in Turin and Milan source primarily from German-Italian supply corridors due to REACH registration maturity and established carbon footprint documentation.
- Silicon:Doped composites achieving 400+ mAh/g specific capacity are penetrating premium passenger platforms. BMW and Mercedes-Benz engineering teams have qualified 10-15% silicon loadings, pulling Italian suppliers toward composite coating investments despite longer qualification cycles.
- Lithium Titanate:Lower energy density limits deployment to heavy-duty commercial segments requiring extreme cycle life.
- Composite Materials:Silicon-carbon architectures and hybrid formulations bridge performance tiers for mid-range EV platforms.
Graphite anchors the volume base while silicon gains share at the steepest rate.
End User:
Procurement concentration maps directly to captive versus merchant cell supply strategies. OEMs internalizing lifecycle management are compressing aftermarket service margins.
- OEMs:Stellantis and Ferrari captive engineering teams specify anode architectures directly, qualifying suppliers against proprietary cell designs. Direct procurement contracts bypass traditional Tier-1 intermediaries for high-volume platforms.
- Tier-1 Suppliers:Cell manufacturers serving multiple OEMs aggregate anode demand across vehicle programs. Samsung SDI and CATL Italian operations source through qualified material suppliers with CE marking under EU Battery Regulation protocols.
- Aftermarket Providers:Diagnostic and refurbishment specialists capture residual value from commercial vehicle fleets.
- Vehicle Assemblers:Contract manufacturers without captive cell engineering rely on Tier-1 cell supply with limited anode specification influence.
OEMs concentrate procurement authority while Tier-1 suppliers retain the broadest supplier portfolios.
Battery Chemistry:
Electrode formulation requirements diverge across cathode-anode pairing strategies. Solid-state roadmaps are redirecting silicon anode interface engineering priorities.
- Lithium-Ion:Graphite anodes paired with NMC or LFP cathodes constitute the installed manufacturing base. Italian production lines optimize slurry coating for liquid electrolyte cell architectures with mature process controls.
- Solid-State:Sulfide and oxide ceramic electrolytes demand silicon-carbon anodes with engineered interface stability. Research partnerships between Milan-based engineering clusters and Korean-Japanese licensors are accelerating qualification timelines.
- Nickel-Manganese-Cobalt:High-voltage cathode pairings stress anode material purity thresholds.
- Lithium Iron Phosphate:Cost-optimized cell designs accept lower energy density anode specifications for commercial vehicle duty cycles.
Lithium-ion retains manufacturing scale advantages while solid-state chemistry expands most quickly in R&D allocation.
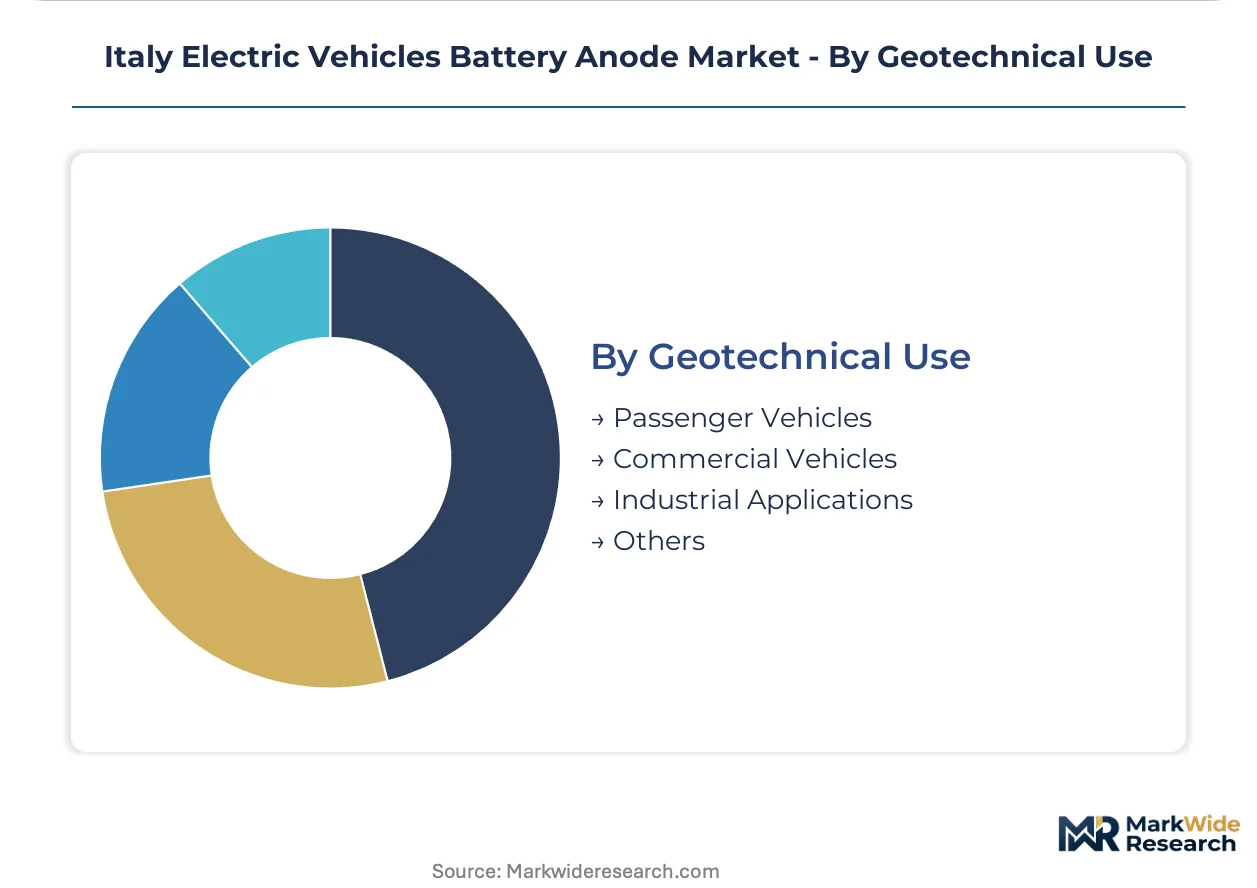
Geotechnical Use:
Application-specific duty cycles dictate anode material selection and supplier qualification intensity. Passenger vehicle platforms drive procurement volume concentration.
- Passenger Vehicles:Premium European OEM platforms specify silicon-doped graphite for 700+ km range targets. Stellantis Turin-Mirafiori operations and Ferrari Modena engineering centers anchor Italian demand concentration.
- Commercial Vehicles:Heavy-duty cycle-life requirements favor lithium titanate or high-purity graphite for bus and truck electrification programs.
- Industrial Applications:Forklift and stationary storage systems prioritize cost-optimized LFP-graphite cell configurations.
- Others:Marine and aviation battery systems constitute emerging qualification pipelines with extended certification timelines.
Passenger vehicles concentrate procurement volume while commercial vehicle segments show the steepest expansion trajectory in aftermarket service attachment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity across European anode procurement varies sharply. Premium passenger OEMs in Germany absorb silicon-doped graphite premiums with minimal volume sensitivity. Italian and Spanish assemblers face tighter margin compression, forcing qualified supplier lists toward REACH-registered, lower-cost synthetic graphite corridors.
Germany
BMW and Mercedes-Benz cell engineering teams specify 10-15% silicon loadings for 2026 model year platforms. The EU Battery Regulation's carbon footprint disclosure rules compress CE marking timelines for imported precursors. Bavarian and Baden-Württemberg engineering clusters anchor qualification partnerships with Korean-Japanese licensors.
France
Renault's ElectriCity manufacturing complex in northern France pulls anode procurement toward localized supply agreements. ECHA REACH protocols standardize material disclosure requirements for French cell manufacturers. Paris-Saclay research clusters accelerate solid-state electrolyte interface engineering with silicon-carbon anode developers.
Spain
SEAT-Volkswagen Martorell operations and emerging Basque Country cell pilot lines concentrate procurement authority. Spain's alignment with EU Green Deal decarbonization mandates tightens carbon border adjustment exposure for Asian graphite feedstock. Catalan automotive engineering clusters densify around Barcelona-Tarragona battery material corridors.
Netherlands
Northvolt's planned Delfzijl gigafactory redirects anode demand toward North Sea supply corridors. Dutch implementation of EU Battery Regulation delegated acts accelerates due diligence obligations for imported synthetic graphite. Brainport Eindhoven's high-tech systems sector converges with automotive electrification clusters in Randstad logistics hubs.
Belgium
Umicore's European metallurgical base sustains closed-loop graphite recovery operations serving adjacent markets. Belgium's central position in EU chemical regulation enforcement shapes REACH compliance workflows for anode suppliers. Flanders' materials technology ecosystem in Leuven-Antwerp corridors supports precursor refinement scale-up.
Italy Electric Vehicles Battery Anode Market Competitive Landscape
Integrated chemical conglomerates and specialized carbon precursor manufacturers split the market across distinct capability tiers. The vendor base concentrates among European metallurgical specialists, German-Italian supply corridor anchors, and Korean-Japanese process licensors adapting to EU compliance frameworks. Three archetypes dominate: diversified chemical majors with battery material divisions, dedicated carbon and graphite specialists, and Asian technology licensors with European localization strategies. Competitive intensity centers on M&A-driven portfolio expansion into silicon-carbon composites and strategic partnerships for solid-state electrolyte interface engineering.
Among diversified chemical majors, BASF SE and Solvay SA exemplify the integrated materials conglomerate archetype with European manufacturing footprints. Umicore SA anchors the metallurgical recovery and closed-loop material specialist tier. SGL Carbon represents the carbon precursor manufacturing specialist with German-Italian supply corridor positioning. POSCO Future M occupies the technology licensor archetype, adapting Korean-Japanese process expertise to EU material compliance requirements.
| Leading Market Players |
|---|
| BASF SE |
| Umicore SA |
| Solvay SA |
| Arkema SA |
| Sumitomo Chemical Co., Ltd |
| SGL Carbon |
| Resonac |
| Mitsubishi Chemical Group |
| POSCO Future M |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Asian synthetic graphite precursor manufacturing is compressing input costs for Italian anode coaters while simultaneously eroding pricing power across standard-grade material tiers. This utilization imbalance forces European suppliers to differentiate through REACH-registered, carbon-documented product lines that command modest premiums from OEMs facing EU Battery Regulation compliance deadlines.
Pricing Analysis
Aftermarket service contracts for cell diagnostics and refurbishment now drive lifetime value capture beyond initial material sales. Three-tier pricing structure across premium silicon-carbon composites, standard synthetic graphite, and economy natural graphite separates qualification-intensive formulations from commodity feedstocks. Cost compression in standard-grade synthetic graphite is intensifying because Asian precursor oversupply is flooding European spot markets. Fleet operators and commercial vehicle assemblers exhibit the highest price sensitivity, while premium passenger OEMs absorb silicon-doped premiums with minimal volume pushback.
Supply Chain Analysis
Export-control restrictions on advanced coating equipment and silicon precursor purification technology are fragmenting equipment procurement timelines for Italian producers. Raw material flows draw from China for spherical graphite, South Korea for anode coating machinery, and Germany for carbon precursor intermediates. Feedstock dependence on Asian spherical graphite concentrates exposes Turin-Milan corridor coaters to carbon border adjustment mechanism exposure and maritime logistics volatility. Distribution runs through qualified Tier-1 cell manufacturers rather than direct OEM supply, with Samsung SDI and CATL Italian operations anchoring downstream offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in battery cell manufacturing are inflecting toward closed-loop material ecosystems, with EU Battery Regulation traceability mandates forcing interoperability between anode suppliers and OEM lifecycle management systems.
For Market Incumbents: Entrench position through captive precursor refinement capacity in the German-Italian corridor and accelerated CE marking pre-certification for silicon-carbon composite architectures. Defensive consolidation should prioritize backward integration into synthetic graphite precursor production to offset Asian feedstock volatility. Umicore SA's metallurgical recovery model offers a template for margin defense against commodity price swings. For New Entrants and Emerging Players: Pursue white-space positioning in southern Italy's underdeveloped cell manufacturing belt, specifically Sicily and Apulia, where integrated precursor-to-coating facilities face minimal incumbent competition. The most penetrable segment lies in second-life diagnostic services for commercial vehicle fleets, where residual value guarantees create sticky service contracts. A go-to-market angle anchored to EU Battery Regulation due diligence compliance offers regulatory tailwinds against established suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon-carbon composite coating lines, favoring scaled operators with eight-figure euro equipment access over capital-constrained mid-tier entrants. Long-term viability across the analysis window hinges on positioning within solid-state electrolyte interface engineering partnerships. Acquisition targets should display Korean-Japanese process licensing relationships adapted to EU material compliance frameworks. The signal to monitor is delegated act acceleration under EU Battery Regulation carbon footprint disclosure rules, which would compress qualification windows for importers.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbon Composite Scale-Up | BMW and Mercedes-Benz qualification timelines pull Italian suppliers toward 10-15% silicon loading capacity. |
| Backward Integration into Precursor Refinement | Captive synthetic graphite production insulates Turin-Milan coaters from Asian feedstock volatility. |
| Second-Life Diagnostic Service Buildout | EU Battery Regulation traceability mandates open revenue streams in commercial fleet refurbishment. |
| Solid-State Electrolyte Interface Partnership | Milan-based engineering clusters accelerate qualification with Korean-Japanese sulfide ceramic licensors. |
| Southern Italy Manufacturing Footprint | Sicily and Apulia offer first-mover positioning for integrated precursor-to-coating facilities. |
Research Methodology
Desk research of EU regulatory filings, customs trade data, and SEC disclosures from listed chemical conglomerates preceded structured interviews with anode coating line engineers, OEM platform battery specialists, Tier-1 cell procurement managers, and aftermarket diagnostic service operators. Primary fieldwork combined with secondary validation from ECHA REACH registration databases and EU Battery Regulation delegated act drafts. Bottom-up volume modeling triangulated against top-down OEM production forecasts across the Italian passenger and commercial vehicle electrification pipeline.
Assumptions held fixed include EU Green Deal decarbonization mandate adherence, F-Gas Regulation coating solvent restrictions, and CE marking timeline compression under delegated acts. Variables included silicon doping penetration rates across premium passenger platforms, solid-state battery chemistry commercialization pacing, and carbon border adjustment mechanism implementation scope. Segmentation dimensions spanned material grade tier, end-user procurement authority, battery chemistry pairing, and geotechnical application duty cycle. CAGRs derived from logistic curve fitting to OEM platform rollout schedules and cell manufacturing capacity buildout trajectories. Forecast inputs incorporated REACH registration maturity timelines and Korean-Japanese process licensing adaptation rates.
Macroeconomic conditions sit as an overlay; deviation in euro-denominated energy costs, maritime freight rates, or lithium carbonate spot pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and OEM platform electrification commitments. Material shifts in EU Battery Regulation carbon footprint disclosure thresholds or solid-state electrolyte interface engineering breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
France Electric Vehicle Battery Anode Market
Lithium-ion Battery
India Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Global Next Generation Batteries Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Iodide Market