
 Metal Ore Mining Market | 2026-2036
Metal Ore Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Ore Mining Market Intelligence
Clean energy manufacturers are gaining share against traditional construction buyers as the metal ore mining demand base is bifurcating. Rio Tinto Group leverages its Pilbara iron ore infrastructure to sustain cost leadership in seaborne markets. BHP Group Limited anchors its portfolio through copper and nickel assets tied to electrification supply chains. Vale S.A. competes on deep integration between Brazilian iron ore mines and Asian steel mill customers.
Metal ore mining encompasses the extraction of rock and mineral deposits containing economically recoverable metals, typically requiring ore grades above cut-off thresholds measured in weight percent metal content and processed through crushing, grinding, and concentration circuits to produce smelter-ready feedstock for downstream refining. Iron ore dominates extraction volumes globally due to steelmaking dependency, while copper ore commands premium margins tied to electrification and renewable energy infrastructure buildouts. Underground mining methods are expanding their share in mature jurisdictions where surface deposits deplete, whereas open-pit mining retains cost advantages for bulk commodities in greenfield basins.
Australia's environmental protection frameworks, Chile's mining royalty reforms, and Indonesia's downstream processing mandates are reshaping capital allocation and offtake structures across major producing regions. The EU Critical Raw Materials Act and corresponding domestic content thresholds are tightening market access for unprocessed ore shipments into European manufacturing supply chains. Stakeholders must monitor regulatory divergence between ore-exporting jurisdictions and processing-demand centers to anticipate where extraction investments will secure long-term offtake commitments.
Market Dynamics
Electrification supply chains are pulling high-grade copper and nickel concentrates away from traditional steelmaking offtake, forcing miners to reconfigure extraction priorities and processing investments toward battery cathode specifications.
Growth Catalysts
- EU Critical Raw Materials Act:Domestic content thresholds for processed ores entering European manufacturing are redirecting capital toward EU-adjacent extraction projects and smelter partnerships.
- Indonesia's downstream processing mandates:Banned raw nickel ore exports are accelerating integrated mine-to-refinery investments along the Sulawesi processing corridor.
- Electric vehicle cathode chemistry:Nickel-rich NCM and NCA formulations are concentrating demand pull on Class 1 nickel deposits with sub-0.02% iron impurity profiles.
Market Restraints
- Chilean mining royalty reforms:Progressive tax scales on copper production are compressing project IRRs and delaying greenfield approvals in the Atacama copper belt.
- Indonesian nickel supply concentration:Over 40% of global refined nickel output flows through Indonesian processing facilities, creating single-jurisdiction disruption exposure.
- Underground mining cost escalation:Labor intensity and ventilation requirements for deep ore bodies are widening cost gaps against open-pit alternatives in greenfield basins.
Strategic Opportunities
- Australian critical minerals infrastructure:Underdeveloped lithium, rare earth, and cobalt processing capacity offers first-mover positions for integrated extraction-refining plays.
- Direct shipping ore bypass:High-grade hematite deposits in West Africa enable mine-to-steel-mill shipments without beneficiation, collapsing cost structures for seaborne iron ore.
- Carbon border adjustment mechanisms:EU CBAM phase-in creates premium pricing windows for low-carbon-intensity concentrate producers with verified Scope 1-3 emissions data.
Industry Challenges
- Geometallurgical modeling complexity:Ore body variability in copper-gold porphyry systems is forcing multi-year drilling campaigns before feasibility commitments.
- Autonomous haulage integration:Retrofitting legacy open-pit fleets with driverless truck systems requires parallel workforce reskilling and control room infrastructure rebuilds.
- Tailings storage facility compliance:Global Industry Standard on Tailings Management certification timelines are extending project permitting by 18-36 months in jurisdictions with active civil society monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Ore Mining Market |
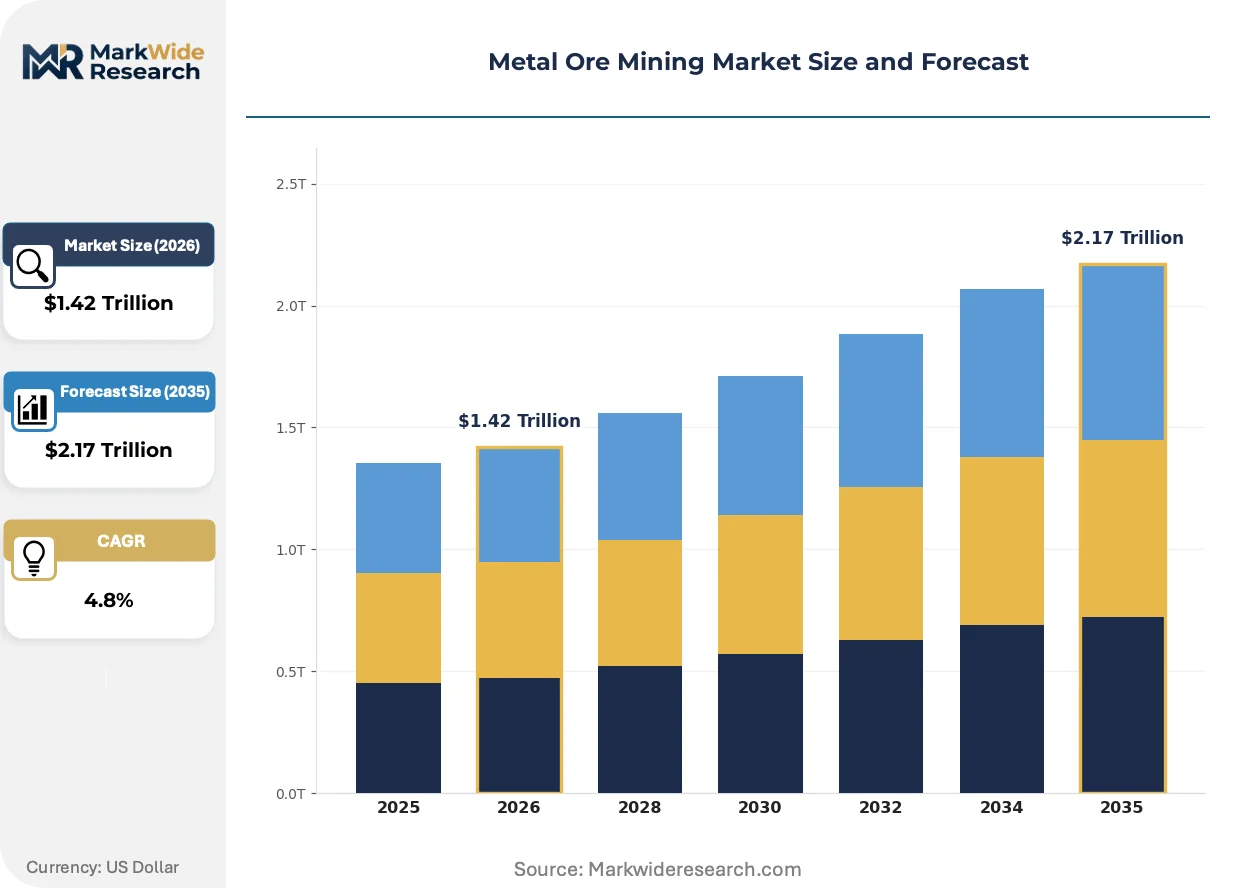
| Market Size in 2026 | $1.42 Trillion |
| Market Size in 2035 | $2.17 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Iron Ore, Bauxite, Copper Ore, Zinc Ore Extraction Method: Open-Pit Mining, Underground Mining, Placer Mining, Mountaintop Removal Industry Application: Construction, Manufacturing, Automotive, Aerospace End User: Steel Mills, Foundries, Fabricators, Electronics Manufacturers |
| Companies Covered | Vale S.A., Rio Tinto Group, BHP Group Limited, Fortescue Metals Group, Freeport-McMoRan, Newmont Corporation, Zijin Mining, Southern Copper, NMDC Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Ore Mining Market Strategic Shifts & Innovations
In-situ recovery methods and sensor-based ore sorting are compressing capital intensity thresholds, while regulatory pressure on Scope 3 emissions is forcing downstream integration decisions that reshape traditional merchant concentrate markets.
Sensor-based ore sorting is fragmenting the economics of marginal deposits. X-ray transmission and laser-induced breakdown spectroscopy systems now enable real-time grade control at the primary crusher, allowing sub-economic ore bodies to achieve cut-off grade thresholds previously requiring dense media separation circuits. Junior developers in the Pilbara and Carajás are adopting these units to extend mine life without mill expansion capex.
REACH authorization requirements for processing chemicals are tightening concentrate import conditions into EU smelters. Sulfuric acid and cyanide reagents face escalating substitution mandates, pushing miners toward chloride leach flowsheets or bioleaching alternatives. Chilean copper producers are responding with seawater desalination and sulfuric acid capture from smelter off-gas to close reagent loops.
Long-term offtake contracting is compressing toward shorter tenors with price reopeners. Battery cathode manufacturers are refusing decade-fixed commitments, instead favoring 3-5 year agreements with floor-ceiling structures tied to LME and Fastmarkets indices. This liquidity preference is most visible in Indonesian nickel and DRC cobalt negotiations, where traders and merchants are regaining intermediary roles that integrated miners had sought to displace.
Metal Ore Mining Market Segmentation
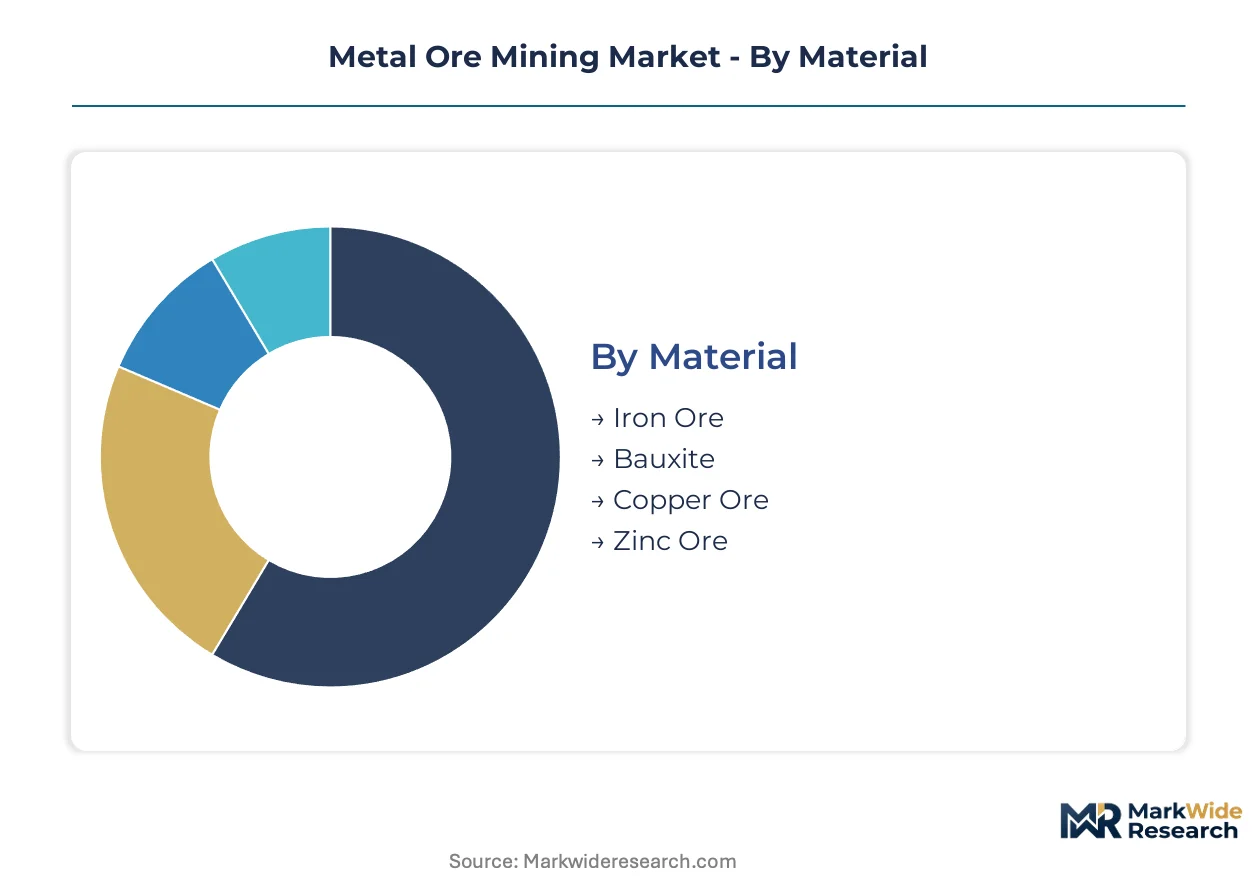
Segmentation in metal ore mining reveals how extraction economics, processing specifications, and end-use requirements fragment capital allocation across materially different value pools. Each dimension exposes distinct vulnerability to substitute materials, regulatory exposure, and margin compression.
Material:
Substitution pressure varies sharply across metal ores, with some segments facing imminent displacement by synthetic or recycled alternatives while others enjoy structural demand protection.
- Iron Ore:Hematite and magnetite deposits supply blast furnace and direct reduction feedstock with grades typically ranging 58-65% Fe. Steel mills in China and India absorb the dominant volume share, though scrap-based electric arc furnace expansion in Europe and North America is eroding virgin ore dependency in flat-rolled product segments.
- Copper Ore:Porphyry and sediment-hosted deposits yield concentrates grading 20-30% Cu after beneficiation, with cathode chemistry specifications from battery manufacturers now overriding traditional wire rod and tube demand. Chile's Escondida and Indonesia's Grasberg deposits anchor supply concentration for electrification supply chains.
- Bauxite:Lateritic deposits processed through Bayer refining into alumina face limited near-term substitution for primary aluminum production, though inert anode smelting technology could eventually displace carbon-intensive Hall-Héroult processes.
- Zinc Ore:Sphalerite concentrates from Mississippi Valley-type and volcanic-hosted massive sulfide deposits supply galvanizing and die-casting applications, with aluminum and magnesium alloys pressuring automotive corrosion protection and structural casting segments.
Iron ore anchors the volume base while copper ore gains share at the steepest rate.
Extraction Method:
Cost tier stratification separates capital-light placer operations from infrastructure-heavy underground developments, with method selection increasingly driven by ore body depth and jurisdictional permitting constraints.
- Open-Pit Mining:Bulk extraction of near-surface ore bodies using truck-and-shovel or dragline systems achieves economies of scale unmatched by other methods. Australia's Pilbara iron ore operations and Chile's Chuquicamata copper pit demonstrate how grade decline and strip ratio escalation eventually force transition to underground alternatives.
- Underground Mining:Block caving, sublevel stoping, and cut-and-fill methods access deeper ore bodies with higher grades but require vertical shafts, hoisting infrastructure, and ventilation systems that triple capital intensity. Labor shortages and diesel particulate exposure are accelerating automation investments in Canadian and Swedish base metal operations.
- Placer Mining:Alluvial deposits of gold, tin, and rare earth minerals are recovered through dredging or sluicing without blasting or crushing, though environmental restrictions on water use and tailings discharge have collapsed operating margins outside artisanal jurisdictions.
- Mountaintop Removal:Contour mining of coal-associated metal deposits in the Appalachian basin faces regulatory extinction under EPA Clean Water Act enforcement, with remaining permits concentrated in legacy thermal coal operations rather than primary metal extraction.
Open-pit mining dominates capital deployment while underground methods expand most quickly in mature extraction jurisdictions.
Industry Application:
Application-based demand concentration exposes miners to diverging cyclicality, with construction volatility contrasting against automotive contract stability and aerospace qualification barriers.
- Construction:Structural steel, rebar, and galvanized sheet consumption tracks infrastructure stimulus and residential building cycles, with Chinese property sector deleveraging compressing seaborne iron ore premiums.
- Manufacturing:Industrial machinery, appliances, and capital equipment demand favors long-term offtake contracts with price reopeners, though reshoring initiatives in the US and EU are shortening supply chains and favoring regional concentrate sources.
- Automotive:Battery electric vehicle production is redirecting copper and nickel flows from traditional powertrain castings toward motor windings and cathode active materials, with OEMs now qualifying mines directly for responsible sourcing compliance.
- Aerospace:Titanium and aluminum alloy specifications require traceable primary metal with tight impurity controls, locking suppliers into decade-long qualification protocols that exclude new market entrants.
Construction absorbs the largest volume share while automotive applications climb the fastest on electrification metal intensity.
End User:
Customer type determines pricing power and contract structure, with integrated steel mills extracting volume discounts that fragmenters cannot match while electronics manufacturers impose sustainability audit requirements.
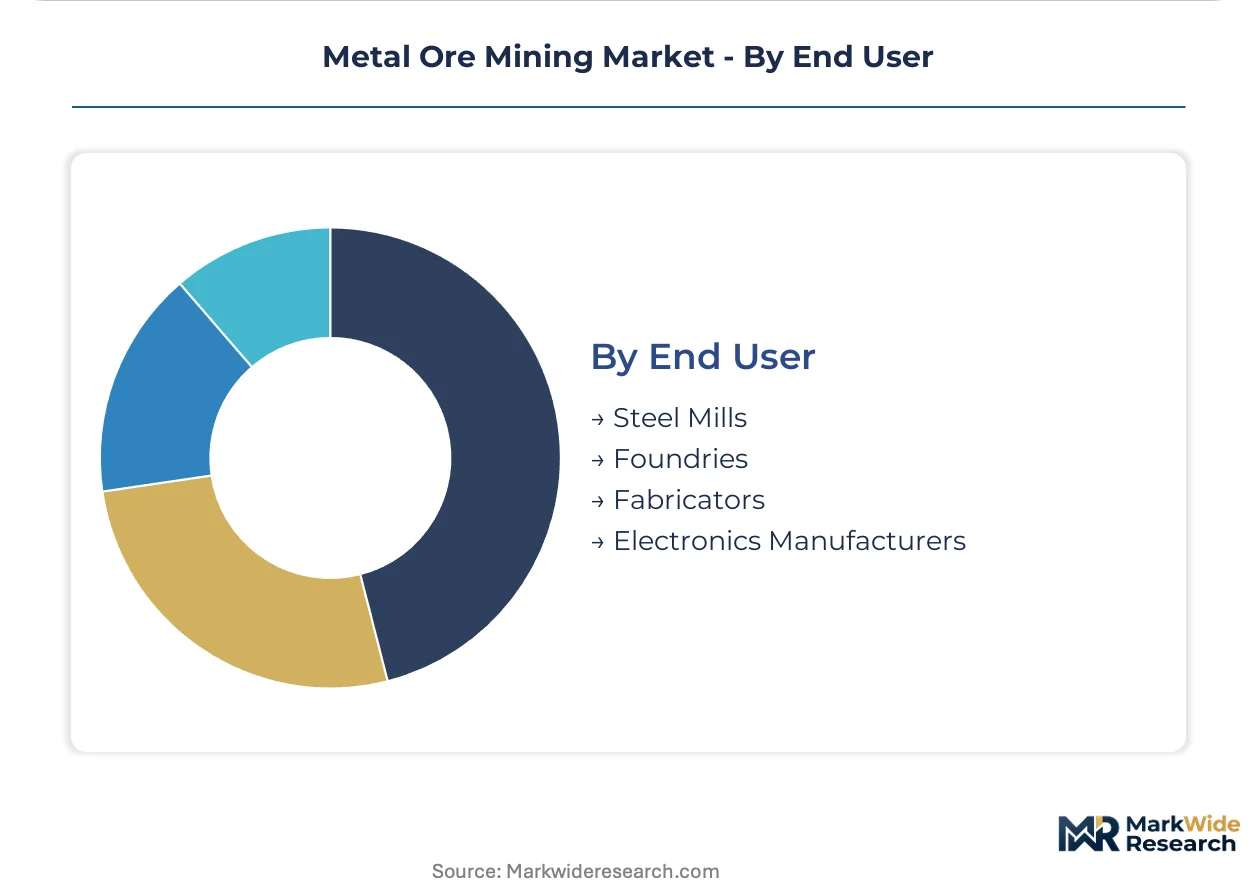
- Steel Mills:Blast furnace operators in China, Japan, and South Korea negotiate annual benchmark pricing for seaborne iron ore, while electric arc furnace mills in the US and Turkey favor scrap and direct reduced iron flexibility over long-term concentrate commitments.
- Foundries:Ferrous and non-ferrous casting operations purchase customized scrap blends and virgin metal units in spot markets, with aluminum die-casters particularly exposed to LME price volatility and energy surcharge pass-through disputes.
- Fabricators:Rolled product and extrusion specialists source from merchant metal distributors rather than mines directly, insulating them from concentrate supply disruptions but compressing margin capture in the value chain.
- Electronics Manufacturers:Semiconductor and battery cell producers are bypassing traders to secure direct offtake from certified mines, with cobalt and lithium contracts now incorporating child labor verification and carbon intensity thresholds.
Steel mills anchor procurement volume while electronics manufacturers are restructuring contract terms most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blast furnace operators in China and electric arc furnace mills in India concentrate seaborne iron ore procurement, while battery cathode manufacturers in South Korea and Japan pull high-grade nickel and copper concentrates toward electrification supply chains. This buyer concentration reshapes extraction investment and processing infrastructure location decisions.
Australia
Pilbara iron ore operations supply Chinese steel mills through long-term offtake agreements tied to annual benchmark pricing. The country's environmental protection frameworks enforce progressive rehabilitation bonds and biodiversity offsets for new mine approvals. Western Australia's lithium and rare earth processing corridor attracts capital for integrated extraction-refining plays targeting battery supply chains.
Chile
Escondida and Chuquicamata copper deposits anchor global concentrate supply for electrification infrastructure and EV motor windings. Mining royalty reforms impose progressive tax scales that compress project IRRs and delay greenfield approvals in the Atacama copper belt. Antofagasta and Calama processing clusters face seawater desalination mandates to reduce freshwater consumption.
Indonesia
Class 1 nickel deposits in Sulawesi and Halmahera feed integrated mine-to-refinery investments for NCM and NCA cathode chemistry specifications. Downstream processing mandates banned raw nickel ore exports and accelerated smelter construction along the Sulawesi processing corridor. Morowali Industrial Park concentrates over 40% of global refined nickel output, creating single-jurisdiction disruption exposure.
Brazil
Carajás iron ore deposits sustain Vale's cost leadership in seaborne markets through deep integration with Asian steel mill customers. ANVISA and IBAMA regulations enforce tailings storage facility compliance under the Global Industry Standard on Tailings Management. Pará state's northern mining corridor attracts sensor-based ore sorting investments to extend mine life without mill expansion capex.
China
Domestic iron ore production supplements seaborne imports for steelmaking, though low-grade deposits require beneficiation before blast furnace feedstock preparation. MIIT dual carbon goals and MEE emissions standards tighten concentrate import conditions and favor low-carbon-intensity suppliers with verified Scope 1-3 data. Sichuan and Inner Mongolia rare earth processing clusters face REACH-aligned chemical substitution mandates for sulfuric acid reagents.
Metal Ore Mining Market Key Industry Players
Player mix skews toward diversified mining conglomerates with integrated logistics infrastructure and single-commodity specialists with deep regional extraction expertise. Tier-one operators control Pilbara iron ore corridors and Chilean copper porphyry systems through decades-long concession holdings. Strategic archetypes include seaborne cost leaders, battery metals integrators, and deep-tier underground specialists. Competitive moves center on autonomous haulage retrofit programs and downstream smelter partnerships to secure offtake under EU Critical Raw Materials Act thresholds.
Within the diversified conglomerate tier, Rio Tinto Group and BHP Group Limited exemplify seaborne iron ore cost leadership through Pilbara infrastructure scale and Asian steel mill integration. Vale S.A. occupies a parallel position anchoring Brazilian iron ore supply chains. Among copper-nickel specialists, Freeport-McMoRan represents the porphyry extraction archetype with Indonesian and Americas assets tied to electrification demand.
| Leading Market Players |
|---|
| Vale S.A. |
| Rio Tinto Group |
| BHP Group Limited |
| Fortescue Metals Group |
| Freeport-McMoRan |
| Newmont Corporation |
| Zijin Mining |
| Southern Copper |
| NMDC Limited |
| Others |
Cost & Logistics Intelligence
Scrap-based electric arc furnace feedstock substitution for virgin iron ore simultaneously redraws procurement geography around coastal scrap yards and compresses long-term contract premiums for seaborne concentrate producers. This displacement forces Pilbara operators to defend volume through Asian steel mill integration while Indonesian nickel smelters capture battery cathode price premiums.
Pricing Analysis
Cost-plus contracts with LME indexation dominate copper and nickel concentrate offtake, with floor-ceiling structures replacing decade-fixed commitments. Price differentiation rests on carbon intensity certification and cathode chemistry compliance, with Class 1 nickel commanding premiums over ferronickel. Pricing pressure stems from Chilean royalty compression of project returns. Steel mills exhibit highest price sensitivity; battery manufacturers accept premium tiers for verified low-carbon supply.
Supply Chain Analysis
Strait of Malacca transit underwrites Indonesian nickel concentrate flows to South Korean and Japanese cathode plants, creating chokepoint exposure for electrification supply chains. Extraction concentrates in Indonesia, Chile, and Australia; processing draws from sulfuric acid and reagent chemical networks. Single-jurisdiction concentration risk pervades Morowali Industrial Park output. Distribution runs through integrated mine-to-refinery partnerships and annual benchmark seaborne contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal ore mining sits at an inflection where EU Critical Raw Materials Act domestic content thresholds restructure offtake access, turning regulatory compliance into a competitive moat for integrated operators.
For Market Incumbents: Fortify cost leadership through autonomous haulage retrofit programs in Pilbara and Carajás corridors. Deepen Asian steel mill integration to defend volume against scrap substitution. Secure EU-adjacent smelter partnerships to meet domestic content thresholds and protect European market access. For New Entrants and Emerging Players: Anchor in Australian lithium and rare earth processing infrastructure gaps, where underdeveloped refining capacity offers first-mover positions. Target West African direct shipping hematite deposits that bypass beneficiation costs. Pursue carbon intensity certification as primary go-to-market credential for EU battery supply chain qualification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Australian critical minerals developers holding extraction permits but lacking downstream integration. Five-to-ten year viability favors operators with secured offtake under EU threshold structures and verified Scope 1-3 emissions data. Watch Indonesian export policy shifts as inflection signal for nickel supply concentration risk.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Haulage Deployment | Rio Tinto and BHP retrofit Pilbara fleets to compress labor costs and close productivity gaps. |
| EU Smelter Partnership Formation | Indonesian nickel operators secure Antwerp and Hamburg processing access for CRM Act compliance. |
| Carbon Intensity Certification | Chilean copper producers capture EU CBAM premium windows with verified emissions data. |
| Direct Shipping Ore Development | West African juniors collapse cost structures through mine-to-steel-mill hematite shipments. |
| Sensor-Based Ore Sorting Adoption | Brazilian operators extend Carajás mine life without mill expansion capital deployment. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade databases, and national mining ministry production statistics. Mine operations executives, steel mill procurement directors, and battery cathode supply chain managers provided operational perspective. Bottom-up reserve and production estimates triangulate against top-down trade flow analysis.
Segmentation dimensions modeled span material type, extraction method, and end-use application across the projection horizon. CAGRs derive from production capacity buildout schedules, offtake contract tenors, and substitution elasticity parameters. Forecast inputs incorporate Chilean royalty regime scenarios and Indonesian downstream processing compliance trajectories.
Underlying assumptions cover sustained electrification metal intensity, EU regulatory enforcement timelines, and Chinese steel output stabilization, with deviation risk concentrated in single-jurisdiction supply disruptions and scrap substitution acceleration. Practitioners should keep alternative scenarios live as carbon border adjustment phase-in schedules and battery chemistry shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Learning Analytics Market
Others
High Voltage Measuring Equipment Market
Others
Enterprise Video Content Management Market
Others
Versatile Video Coding Market
Others
China Smart Home Market
Others
Aircraft Cameras Market
Others
Global Flexible PVC Films Market
Others
India Smart Home Market
Others
Ammeters Market
Others
Semiconductor Gas Filters Market
Others
Turbo Mills Market
Others
Middle East Location-Based Services Market
Others
Dry-Cleaning and Laundry Services Market
Others
Bio-Imaging Technologies Market
Others
Hot Air System Market
Others
Short Video Applications Market