
 DIY Haircut Kits Market | 2026-2036
DIY Haircut Kits Market Size, Share, and Industry Trends Forecast 2026-2036
DIY Haircut Kits Market Analysis
Lithium-ion cordless motor architecture is reconfiguring how DIY haircut kits deliver power and portability. Wahl Clipper Corporation leverages its century-old manufacturing scale to dominate professional-grade home clippers. Koninklijke Philips N.V. anchors its position through integrated blade systems and multi-region distribution networks. Panasonic Corporation differentiates via precision ceramic blade technology developed for Asian hair textures.
DIY haircut kits comprise motorized or manual cutting instruments bundled with combs, guards, and maintenance accessories designed for non-professional hair trimming. Electric clippers typically operate at 3,000 to 7,500 revolutions per minute with stainless steel or carbon-coated blades to handle varying hair densities. Electric clippers command the largest product type share due to repeat blade replacement cycles and attachment ecosystems. Subscription packs represent the fastest-growing packaging format as direct-to-consumer brands lock in recurring revenue. Online retail channels capture expanding volume as platform algorithms surface grooming tutorials alongside product listings.
FDA oversight of electric grooming devices ensures blade safety and electromagnetic compliance for products entering the United States. CE marking requirements under EU MDR and REACH chemical standards govern blade coatings and motor materials for European distribution. Japan's METI enforces PSE certification for lithium-ion battery systems in cordless models. Stakeholders must monitor evolving battery transport regulations and state-level e-waste directives as cordless adoption accelerates.
Market Dynamics
Cordless lithium-ion motor architecture is compressing replacement cycles and redistributing power across the value chain as suburban households abandon corded systems for untethered grooming flexibility.
Growth Catalysts
- Suburban household density:Post-pandemic remote work permanence in United States exurbs and German secondary cities sustains demand for home-based grooming infrastructure.
- FDA electromagnetic compliance:Streamlined device safety pathways for electric grooming instruments accelerate United States market entry for cordless lithium-ion models.
- Ceramic blade precision engineering:Japanese-developed coatings adapted for Asian hair textures expand addressable user segments beyond traditional stainless steel limitations.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing relies on concentrated East Asian cell manufacturers, exposing brands to transport regulation volatility and raw material allocation constraints.
- CE marking friction under EU MDR:Blade coating substance approvals and motor material declarations extend European commercialization timelines by 8-14 months for new entrants.
- Manual clipper residual demand:Low-cost stainless steel scissors and non-motorized trimmers retain price-sensitive segments in emerging markets, compressing electric kit penetration ceilings.
Strategic Opportunities
- Subscription pack packaging:Direct-to-consumer blade replacement subscriptions lock recurring revenue and reduce customer acquisition costs through automated replenishment cycles.
- Platform algorithm surfacing:Grooming tutorial content paired with product listings on major e-commerce platforms converts viewership into purchase intent without traditional advertising spend.
- Japan PSE certification pathway:METI battery safety standards, once satisfied, enable premium positioning across Asian markets with harmonized electrical safety recognition.
Industry Challenges
- Blade alignment technician scarcity:Precision grinding and ceramic bonding skills concentrate in legacy manufacturing regions, constraining quality-scaled production expansion.
- State-level e-waste directive fragmentation:United States cordless kit brands face 23 distinct battery disposal compliance regimes, complicating reverse logistics design and cost allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DIY Haircut Kits Market |
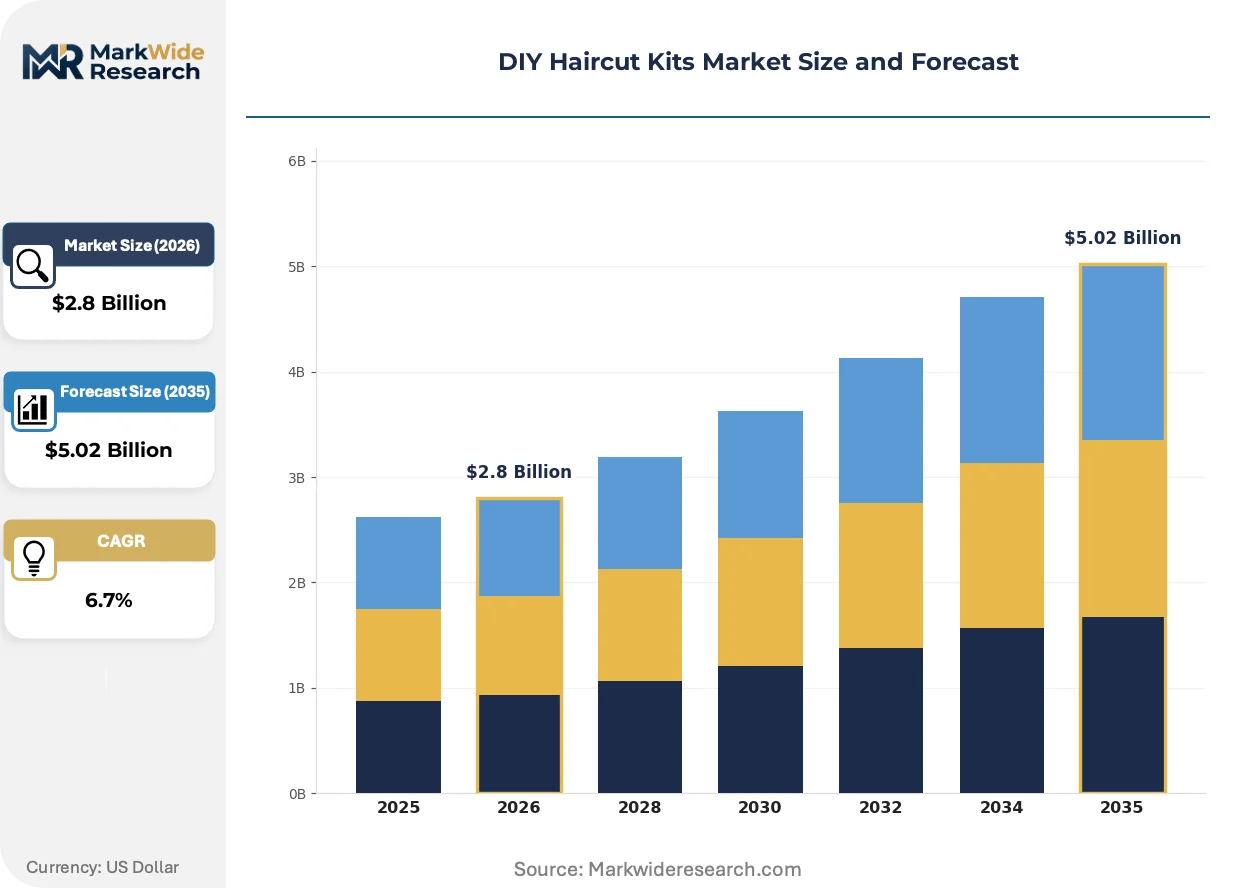
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Clippers, Scissors, Comb Sets, Razor Kits Packaging Type: Retail Boxes, Carry Cases, Subscription Packs, Travel Kits End User: Individuals, Families, Salons, Barbers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Wahl Clipper Corporation, Koninklijke Philips N.V., Panasonic Corporation, Conair Corporation, Procter & Gamble, VEGA, Andis Company, Remington, Braun GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DIY Haircut Kits Market Emerging Trajectories
Power delivery architectures and distribution mechanics are simultaneously compressing product lifecycles and unbundling traditional retail relationships in home grooming equipment.
Brushless DC motor systems paired with high-density lithium-polymer cells are rendering obsolete nickel-cadmium and basic brushed motor platforms across mid-tier and premium kit segments. German and Japanese households are adopting these configurations at replacement rates exceeding corded system obsolescence curves. The technology shift is collapsing the historical 5-7 year replacement cycle toward 3-4 year intervals driven by battery degradation rather than mechanical failure.
EU REACH chemical standards governing blade coatings and motor housing materials are compelling reformulation of carbon-coated edge treatments and lubricant compositions. Manufacturers serving European distribution channels must resubmit substance dossiers for existing product lines, absorbing 12-18 month compliance windows. Japanese exporters with established substance testing protocols are capturing shelf space as European brands navigate re-registration delays.
Algorithmic product surfacing on video-commerce platforms is displacing traditional retail discovery for first-time DIY clipper purchasers. United States suburban buyers encounter bundled tutorial-content recommendations that reduce perceived skill barriers and accelerate purchase conversion. This behavioral shift concentrates volume capture among brands investing in native content production rather than legacy retail slotting fees.
DIY Haircut Kits Market Segmentation
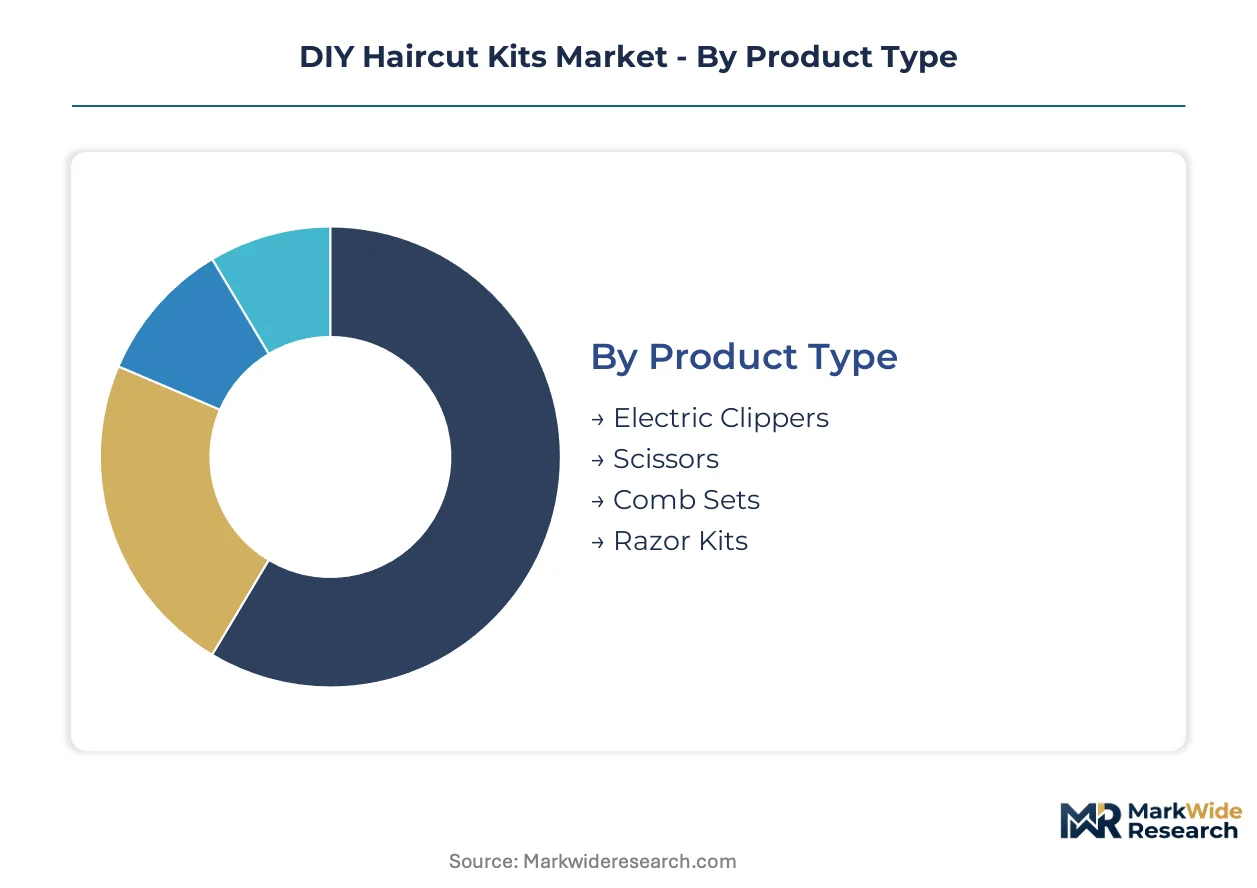
DIY haircut kit manufacturers engineer distinct product configurations to match divergent replacement cycles, skill levels, and purchase contexts across home grooming scenarios. Segment boundaries blur as cordless electric platforms absorb manual tool functions and subscription models restructure how households acquire blade replacements.
Product Type:
After-sales-service intensity varies sharply across product types, with motorized systems demanding blade sharpening, battery replacement, and motor maintenance that manual alternatives never require.
- Electric Clippers:Cordless lithium-ion motor systems operating at 3,000 to 7,500 RPM with stainless steel or carbon-coated blades dominate suburban United States households seeking repeatable home grooming outcomes. Corded system obsolescence accelerates replacement cycles toward 3-4 year intervals as battery degradation outpaces mechanical failure.
- Scissors:Manual stainless steel cutting instruments with precision-ground edges retain residual demand among price-sensitive segments and traditional grooming practitioners in emerging markets. Low replacement frequency and minimal maintenance compress recurring revenue potential for manufacturers.
- Comb Sets:Polymer attachment guards calibrated to specific clipper blade widths enable length-graded cutting without technical skill.
- Razor Kits:Straight-edge and safety razor configurations serve precision detailing and neckline cleanup tasks beyond clipper capabilities.
By volume, Electric Clippers leads. By growth pace, Razor Kits is ahead as precision grooming tutorials expand their addressable user base.
Packaging Type:
Packaging cost tiers stratify sharply between single-purchase retail configurations and recurring-revenue subscription mechanics that lock in customer lifetime value.
- Retail Boxes:Standard cardboard packaging with blister-inserted components dominates supermarket and specialty store channels across German secondary cities. Shelf presence and price transparency drive impulse purchases among first-time DIY groomers.
- Subscription Packs:Automated blade replacement cycles paired with lubricant refills and cleaning accessories capture direct-to-consumer brands seeking recurring revenue without customer reacquisition costs. United States platform algorithms surface these offerings alongside tutorial content to convert viewership into purchase intent.
- Carry Cases:Hard-shell or reinforced fabric storage solutions protect clipper investments during transport and extend perceived product longevity.
- Travel Kits:Compact, battery-operated configurations with dual-voltage compatibility serve mobile grooming needs and international travelers.
Subscription Packs is climbing the fastest as brands prioritize recurring revenue over transactional margin.
End User:
End-user application contexts determine blade durability specifications, motor power requirements, and accessory bundle complexity across purchase decisions.
- Individuals:Single-person households in United States exurbs and Japanese urban apartments drive cordless lithium-ion adoption for personal maintenance without professional dependency. Remote work permanence sustains demand for home-based grooming infrastructure.
- Families:Multi-user households require adjustable guard systems and durable blade coatings to accommodate varying hair densities and cutting frequencies across household members.
- Salons:Professional establishments seeking backup equipment or auxiliary services purchase commercial-grade home kits for overflow capacity.
- Barbers:Traditional practitioners integrate DIY-grade tools into mobile or secondary service offerings.
Families generates the highest absolute volume. Individuals is expanding most quickly as single-person household formation accelerates.
Distribution Channel:
Channel margin structures and customer acquisition mechanics diverge between algorithmic surfacing platforms and physical retail discovery environments.
- Online Retail:Major e-commerce platforms convert grooming tutorial viewership into purchase intent through bundled content-product recommendations without traditional advertising spend. United States suburban buyers encounter these surfacing mechanisms at accelerating rates.
- Supermarkets:Mass-market retail channels in Germany and Japan stock entry-level electric and manual configurations for unplanned purchase occasions.
- Specialty Stores:Beauty supply and grooming-focused retailers offer hands-on product comparison and staff guidance for uncertain first-time buyers.
- Direct Sales:Manufacturer-owned channels bypass platform fees and capture full margin on premium ceramic-blade configurations.
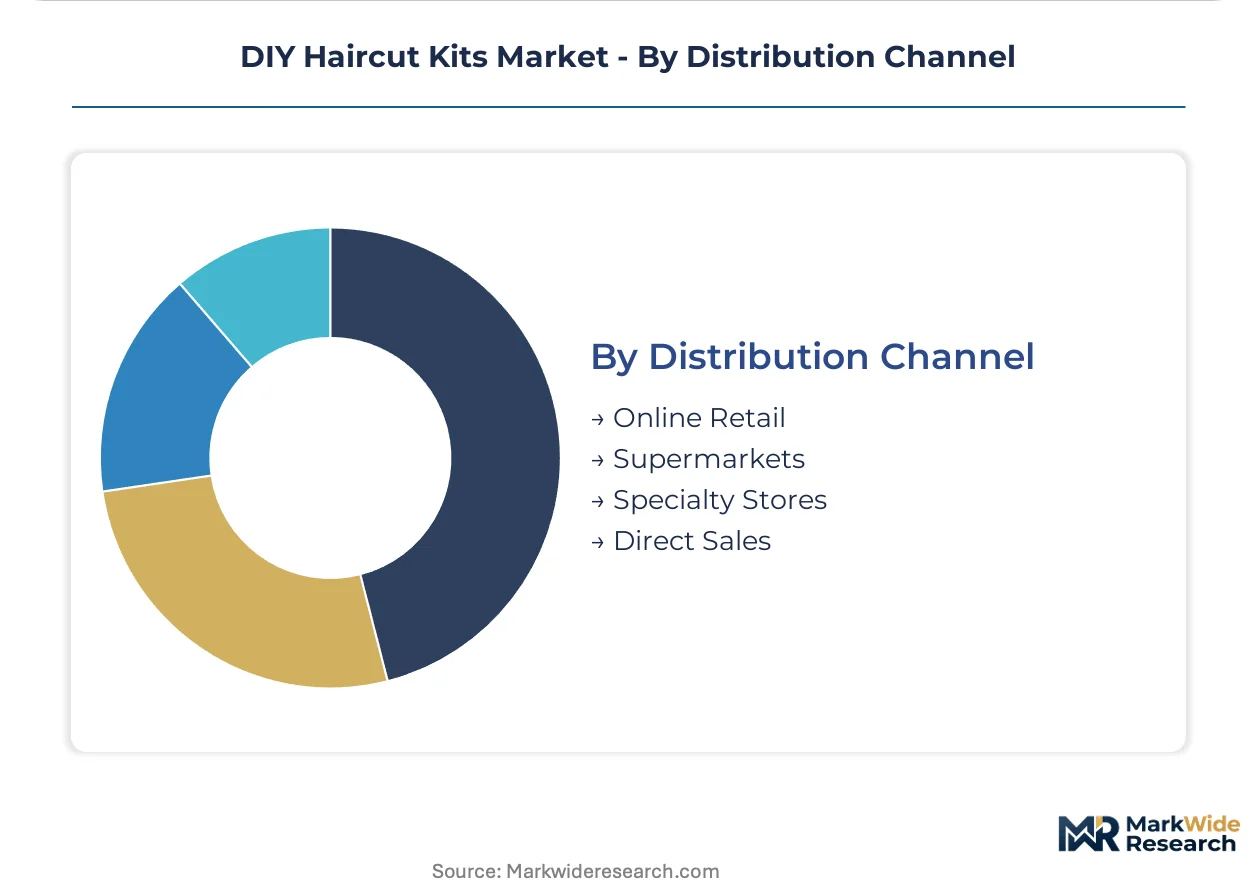
Online Retail leads by transaction volume. Direct Sales is gaining share fastest as brands seek margin protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered grooming systems to United States suburban markets, while Japanese ceramic blade technology flows into Asian premium segments. This trade configuration shapes demand patterns across three continents.
United States
Remote work permanence in Texas and Florida exurbs sustains demand for cordless lithium-ion grooming infrastructure. FDA electromagnetic compliance pathways accelerate market entry for battery-powered models. Greater Atlanta distributors stock premium ceramic-blade configurations for suburban household penetration.
Germany
Secondary cities in Bavaria and North Rhine-Westphalia drive replacement of corded systems with brushless DC motor platforms. CE marking under EU MDR governs blade coating substance approvals for European distribution. Stuttgart industrial clusters engineer precision grinding equipment for ceramic bonding processes.
Japan
Tokyo and Osaka metropolitan households adopt high-density lithium-polymer configurations at accelerated replacement cycles. METI enforces PSE certification for battery systems in cordless models. Nagoya manufacturing corridors concentrate ceramic blade coating expertise for Asian hair texture applications.
United Kingdom
London and Southeast England groomers shift toward subscription-pack purchasing through direct-to-consumer channels. REACH chemical standards regulate carbon-coated edge treatments entering British ports. Midlands distribution hubs consolidate EU-originating inventory for post-Brexit customs processing.
China
Domestic manufacturers in Yangtze River Delta supply battery pack assemblies to international clipper brands. GB standards and MIIT regulations govern lithium-ion cell transport and dual carbon compliance for export-bound production. Shenzhen technology corridors concentrate brushless motor controller fabrication.
DIY Haircut Kits Market Vendor Landscape
On the supply side, the industry is consolidated around century-old grooming equipment specialists and diversified electronics conglomerates. Three strategic archetypes dominate: heritage clipper manufacturers with professional-grade lineage, integrated appliance multinationals with blade system R&D, and direct-to-consumer brands with subscription mechanics. Competitive moves center on vertical integration into battery cell sourcing and algorithmic content partnerships with video-commerce platforms.
Among heritage grooming specialists, Wahl Clipper Corporation and Andis Company represent the professional-grade home segment archetype with manufacturing scale accumulated over decades. Koninklijke Philips N.V. and Panasonic Corporation exemplify the diversified electronics multinational model, leveraging integrated blade systems and precision ceramic technology respectively. These four anchors occupy positions across premium and mid-tier price bands, with Japanese and Dutch entities capturing Asian market recognition and American firms dominating domestic suburban distribution.
| Leading Market Players |
|---|
| Wahl Clipper Corporation |
| Koninklijke Philips N.V. |
| Panasonic Corporation |
| Conair Corporation |
| Procter & Gamble |
| VEGA |
| Andis Company |
| Remington |
| Braun GmbH |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta battery pack assembly capacity governs downstream pricing power for cordless lithium-ion grooming systems, compressing margins for brands without captive cell sourcing or long-term offtake agreements with East Asian manufacturers.
Pricing Analysis
Brushless DC motor systems command premium positioning against nickel-cadmium legacy platforms and basic brushed alternatives. Three-tier pricing structure across premium, standard, and economy levels separates ceramic-blade precision configurations from stainless steel mid-tier offerings and entry-level corded alternatives. Cost compression in economy tiers intensifies because Shenzhen-based motor controller suppliers are absorbing volume discounts. Families with multi-user households exhibit lowest price sensitivity due to amortized per-use costs, while emerging market individuals retain highest sensitivity to upfront kit expenditure.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for cordless kit brands. Lithium-ion cell production concentrates in China, South Korea, and Japan. Brushless motor controllers, precision grinding equipment, and ceramic coating substrates draw from specialized manufacturing corridors. Single-source vulnerability concentrates in Nagoya ceramic blade bonding facilities. Distribution runs through platform algorithmic surfacing and direct-to-consumer subscription mechanics alongside traditional retail slotting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward algorithmic platforms that control discovery and subscription mechanics, fragmenting traditional brand loyalty as suburban households prioritize tutorial-integrated purchase journeys over heritage manufacturer recognition.
For Market Incumbents: Insulate proprietary blade system ecosystems through backward integration into precision grinding equipment and ceramic coating capacity. Lock in lithium-ion cell offtake with Yangtze River Delta suppliers before allocation constraints tighten. Defend against direct-to-consumer entrants by capturing grooming tutorial content partnerships with major video-commerce platforms. For New Entrants and Emerging Players: Establish a beachhead in subscription-pack packaging for blade replacement cycles, where automated replenishment mechanics reduce customer reacquisition costs. Target price-sensitive individuals in United States exurbs with entry-level cordless configurations paired with algorithmic tutorial surfacing. Bypass retail slotting fees through native content production that converts viewership into purchase intent. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription mechanics and replacement cycle compression transform transactional hardware into annuity-like cash flows. Target heritage grooming specialists with dormant ceramic blade technology or underutilized precision manufacturing assets. Watch for inflection when platform algorithm changes favor tutorial-integrated listings over traditional search ranking.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium-Ion Cell Sourcing | Captive battery supply from Yangtze River Delta manufacturers insulates brands from transport regulation volatility and raw material allocation constraints. |
| Ceramic Blade Coating Capacity Expansion | Nagoya corridor expertise for Asian hair texture applications commands premium positioning across Japanese and export markets. |
| Platform Algorithm Content Partnership | Native grooming tutorial production converts video-commerce viewership into purchase intent without traditional advertising expenditure. |
| Subscription Pack Infrastructure Buildout | Automated blade replacement cycles lock recurring revenue and reduce customer lifetime value acquisition costs. |
| Precision Grinding Equipment Acquisition | Stuttgart industrial cluster tooling for ceramic bonding processes addresses technician scarcity constraining quality-scaled production. |
Methodological Framework
Operator-level perspectives from brand managers at heritage grooming specialists, platform algorithm specialists at major e-commerce retailers, procurement leads at lithium-ion cell manufacturers, and maintenance directors at suburban household service providers anchored the qualitative base. Secondary validation drew from FDA electromagnetic compliance filings, METI PSE certification databases, EU MDR substance dossiers, and customs records tracking grooming equipment trade flows. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to converge on volume and value estimates.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, packaging format, end-user application, and distribution channel complexity alongside regional regulatory cluster differentiation. CAGRs were derived from replacement cycle compression dynamics, cordless adoption curves, and platform algorithm penetration rates. Industry-specific forecast inputs incorporated lithium-ion cell cost trajectories and grooming tutorial content production scaling patterns.
Sensitivities concentrate around lithium-ion transport regulation shifts, platform algorithm surfacing policy changes, and ceramic blade technician availability constraints. Forecasts reflect documented assumptions regarding remote work permanence sustaining home-based grooming infrastructure. Material shifts in battery chemistry substitution timelines or EU REACH substance restriction expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Global Cosmetic Products Market
Beauty & Personal Care
Nail Art Tools and Accessories Market
Beauty & Personal Care
Bio-Based Cosmetics Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
Germany Lip Care Products Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
DIY Face Mask Machine Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Hand Soap in Retail Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Digitalization of Beauty Industry Market
Beauty & Personal Care
Facial Care Market