
 Salon Products Market | 2026-2036
Salon Products Market Size, Share, and Industry Trends Forecast 2026-2036
Salon Products Market Analysis
Professional-grade formulation tiers is bifurcating the competitive landscape as stylists and salon owners demand higher-performance actives than mass-market alternatives offer. L'Oréal S.A. leverages its Redken and Kérastase divisions to dominate professional-only distribution through licensed salon channels. Estée Lauder Companies Inc. sustains prestige positioning in hair care through concentrated R&D on bond-repair technologies. Henkel AG & Co. KGaA competes aggressively in the mid-professional segment with Schwarzkopf Professional, anchoring its European manufacturing base for cost-controlled export.
Salon products encompass chemically formulated preparations designed for application by licensed cosmetologists or trained technicians, typically requiring controlled pH ranges, oxidative stability, and compatibility with thermal processing tools. These formulations serve to cleanse, condition, color, or restyle human hair while meeting stringent dermal safety thresholds for repeated professional exposure. Hair color and styling products command the deepest margin pools, as ammonia-free lighteners and heat-activated polymers justify premium price positioning. Shampoos and conditioners represent the highest absolute volume segment, though private-label and economy-tier competition compresses profitability. Professional salons remain the decisive end-user channel, with product loyalty tied to stylist education programs and back-bar exclusivity agreements.
Regulatory oversight from the FDA governs cosmetic safety labeling and adverse event reporting in the United States, while EU REACH and the MDR framework impose stricter substance restrictions and documentation burdens on formulations entering European professional channels. California's Proposition 65 and forthcoming state-level fragrance disclosure mandates are forcing reformulation investments for brands serving the North American salon trade. Stakeholders must monitor evolving chemical ban lists and professional licensing reciprocity rules as determinants of market access and product liability exposure.
Market Dynamics
Clean beauty mandates and bond-building chemistry advances are forcing simultaneous reformulation across professional-only and prestige retail tiers, compressing development cycles while elevating raw material specifications.
Growth Catalysts
- EU REACH substance restrictions:Professional brands investing in pre-registered alternatives gain accelerated market access across European salon channels.
- Scalp treatment service expansion:North American salons adding trichology-adjacent protocols drive demand for pH-stabilized pre-shampoos and post-color scalp soothers.
- Ammonia-free lightener chemistry:MEA and oil-based lift systems are displacing traditional alkaline formulations in premium color services.
Market Restraints
- Isopropyl alcohol supply volatility:Sanitization-grade alcohol diversion during health emergencies creates intermittent shortages for aerosol styling product manufacturers.
- Professional licensing reciprocity fragmentation:Cross-border stylist mobility restrictions limit standardized training program rollout for brands dependent on educator networks.
- At-home color kit performance convergence:Mass-market bond-building additives narrow the efficacy gap with salon-only oxidative color systems.
Strategic Opportunities
- South Korean salon density expansion:Seoul's scalp-focused service culture creates template markets for specialized treatment protocols exportable to Chinese tier-one cities.
- California fragrance disclosure mandates:Early compliance investments position brands for probable federal extension of ingredient transparency requirements.
- Salon-to-consumer subscription bridging:Back-bar exclusivity agreements are loosening to allow stylist-curated home maintenance product replenishment.
Industry Challenges
- Trichology certification scarcity:Advanced scalp health credentialing programs remain concentrated in Western Europe, limiting service menu expansion in emerging markets.
- Thermal tool compatibility testing:Heat-activated polymer validation requires capital-intensive flat-iron and blow-dryer protocol standardization across multiple device manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salon Products Market |
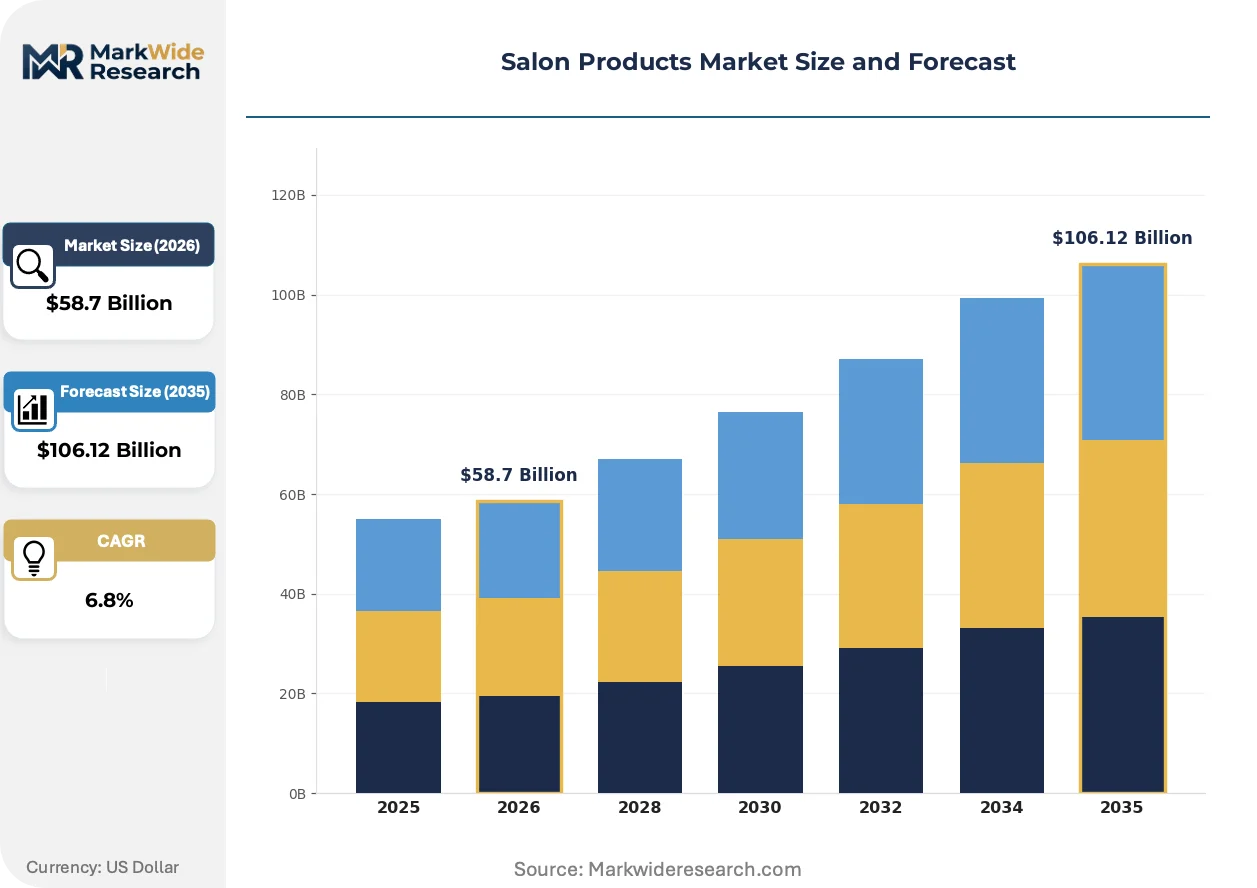
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Color, Styling Products End User: Professional Salons, Home Users, Beauty Schools, Spas Distribution Channel: Online Retail, Supermarkets, Beauty Supply Stores, Direct Sales Price Tier: Premium, Mid-Range, Economy, Value |
| Companies Covered | Estée Lauder Companies Inc., Amorepacific Corporation, L’Oréal S.A., Shiseido Company Limited, Kao Corporation, Unilever PLC, Coty Inc., Henkel AG & Co. KGaA, Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salon Products Market Emerging Trajectories
Bond-repair molecular engineering and predictive color-matching algorithms are compressing the performance gap between professional-only and adjacent retail tiers.
Olaplex-style bis-aminopropyl diglycol dimaleate chemistry is displacing traditional protein reconstructor treatments in damage-recovery service protocols. High-volume salon chains in the United States and United Kingdom are standardizing these protocols across color correction appointments. This displacement is compressing margins on legacy keratin-based back-bar treatments while elevating stylist technical training requirements.
EU REACH Annex XIV substance restriction expansions are forcing reformulation of oxidative color developers containing toluene-2,5-diamine sulfate alternatives. Professional brands serving European salon channels face 18-month registration timelines for new colorant precursors. Color manufacturers with captive raw material synthesis capabilities are internalizing compliance costs while contract-dependent competitors face supply interruption risks.
Stylists are curating personalized home-care regimens through client-specific QR code scanning, bypassing traditional retail shelf selection. This behavior shift concentrates product recommendation authority with individual technicians rather than salon inventory managers. The pattern is most visible in Japanese and South Korean salon ecosystems where mobile payment integration enables seamless stylist-commissioned replenishment.
Salon Products Market Segmentation
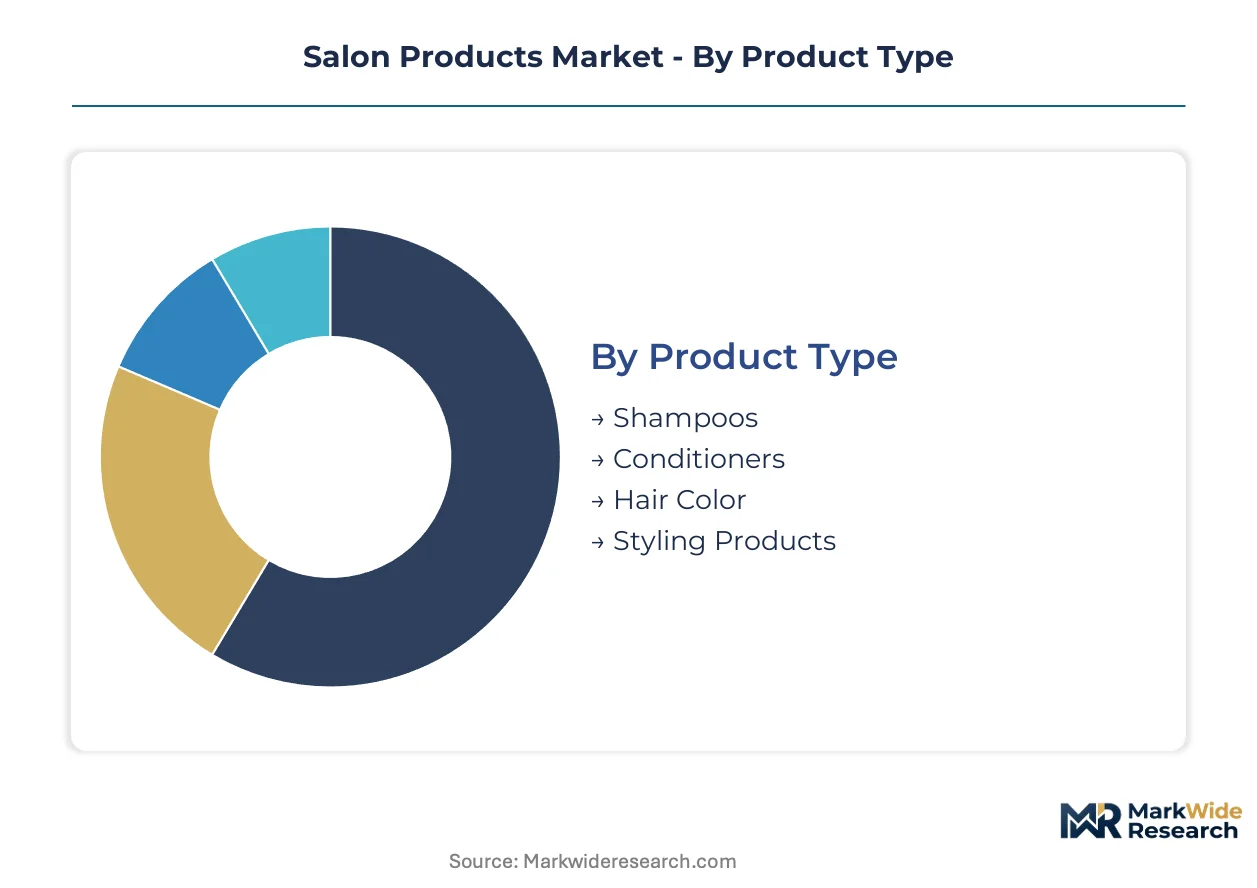
Salon product purchasing decisions bifurcate sharply between professional-only formulations and retail-accessible alternatives. Each segmentation dimension carries distinct margin profiles, regulatory exposure, and channel control requirements that shape competitive strategy.
Product Type:
Hair color and styling products face the most acute substitution pressure from mass-market bond-building additives and heat-activated polymer alternatives.
- Shampoos:pH-stabilized cleansing formulations designed for repeated professional application and compatibility with oxidative color systems. Demand concentrates in high-frequency salon service markets including the United States and South Korea, where pre-color clarification protocols drive back-bar volume.
- Conditioners:Cationic emulsion systems delivering cuticle-sealing performance for chemically treated hair. Professional salons in Western Europe anchor demand, though EU REACH substance restrictions on certain quaternary ammonium compounds are forcing reformulation timelines.
- Hair Color:Oxidative and direct dye systems requiring controlled developer concentrations.
- Styling Products:Heat-activated polymers and aerosol formulations for thermal tool compatibility.
Shampoos anchor the volume base while hair color gains share at the steepest rate.
End User:
Customer type segmentation follows the divergence between licensed professional channels and unregulated home application environments.
- Professional Salons:Licensed cosmetology operations requiring OSHA-compliant labeling and stylist education program integration. United States salon chains drive concentrated demand for back-bar exclusivity agreements and protocol-standardized treatment systems.
- Home Users:Consumer-directed purchasers seeking maintenance formulations between professional appointments. Chinese e-commerce platforms are expanding this segment through live-streaming stylist recommendations.
- Beauty Schools:Institutional training programs requiring bulk-format, educational-labeled product supplies.
- Spas:Wellness-integrated facilities expanding scalp treatment service menus.
Professional salons dominate absolute revenue contribution while home users expand most quickly through digital channel migration.
Distribution Channel:
Channel structure determines margin capture and brand control intensity across the value chain.
- Online Retail:Direct-to-consumer and third-party marketplace platforms enabling stylist-curated subscription replenishment. South Korean mobile payment integration is compressing friction in technician-commissioned repeat purchases.
- Supermarkets:Mass-market retail placement for economy-tier maintenance formulations.
- Beauty Supply Stores:Professional-only distribution requiring license verification for purchase authorization.
- Direct Sales:Manufacturer-to-salon relationships with educator network support.
Beauty supply stores retain the highest margin structure while online retail captures the steepest expansion trajectory.
Price Tier:
Pricing stratification reflects raw material specification tiers and certification requirements rather than mere brand positioning.
- Premium:Captive-synthesis colorant precursors and bis-aminopropyl diglycol dimaleate bond-repair actives with EU REACH pre-registration status.
- Mid-Range:Reformulated sulfate-free and paraben-free alternatives meeting California disclosure mandates.
- Economy:Private-label and contract-manufactured basics with compressed R&D recovery.
- Value:Entry-tier positioning for price-sensitive emerging market penetration.
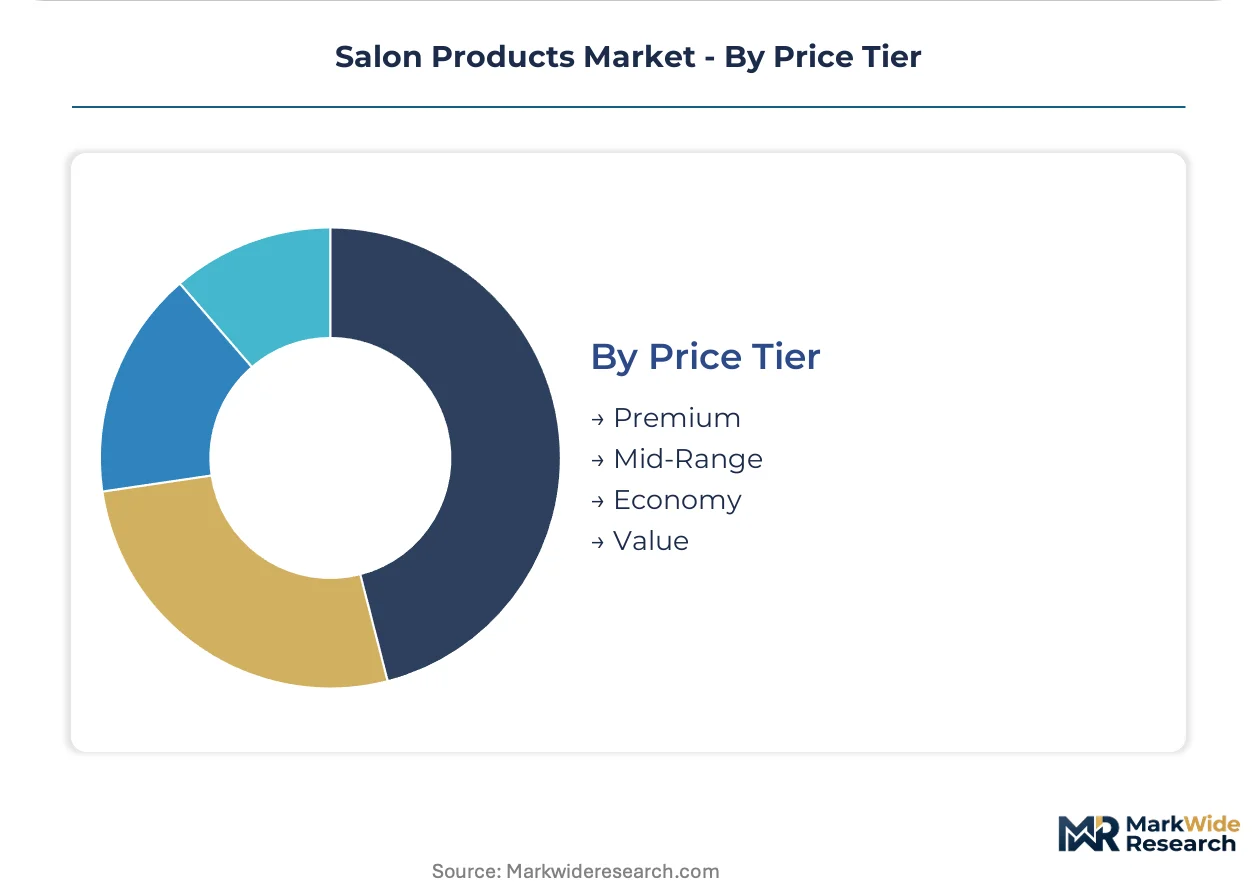
Economy tier anchors developing market volume while premium formulations climb the fastest on professional service menu expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for professional-grade salon formulations concentrates in Germany, the United States, Japan, South Korea, and France. These five countries anchor supply chains for oxidative color precursors, bond-repair actives, and pH-stabilized treatment systems serving licensed salon channels worldwide.
United States
California's Proposition 65 and emerging fragrance disclosure mandates are forcing reformulation investments across professional color lines. The FDA governs cosmetic safety labeling and adverse event reporting for salon products entering interstate commerce. Los Angeles and New York City host the densest salon ecosystems, with chain operators standardizing back-bar exclusivity agreements across multiple locations.
Germany
EU REACH Annex XIV substance restrictions on toluene-2,5-diamine sulfate alternatives are compressing registration timelines for colorant precursors. ECHA documentation burdens favor manufacturers with captive raw material synthesis capabilities. The Rhine-Ruhr industrial corridor anchors production of professional oxidative developers and MEA-based lightener systems for European export.
Japan
Scalp-focused service protocols in Tokyo and Osaka are driving demand for pH-stabilized pre-shampoos and post-color scalp soothers. METI oversees chemical substance reporting under the Act on the Evaluation of Chemical Substances. Yokohama-based formulators are integrating predictive color-matching algorithms into professional-only distribution systems.
South Korea
Seoul's salon density and mobile payment integration enable seamless stylist-commissioned product replenishment. MFDS regulates cosmetic safety and functional claims for professional scalp treatment formulations. The Gangnam district serves as a template market for specialized trichology protocols exportable to Chinese tier-one cities.
France
Prestige positioning in hair care sustains concentrated R&D investment on bond-repair technologies and ammonia-free lightener chemistry. ANSM enforces stricter substance documentation than baseline EU requirements for professional channel entry. Paris anchors the highest per-capita professional service spending in Western Europe, with independent salons maintaining tight educator network relationships.
Salon Products Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the professional salon products sector. Premium-tier specialists dominate bond-repair molecular engineering and captive-synthesis colorant precursors, while mid-professional competitors leverage scale manufacturing and regional distribution density. The market structure separates into three strategic archetypes: integrated beauty conglomerates with professional-only divisions, independent prestige houses focused on stylist education networks, and contract-manufactured private-label suppliers. Competitive moves concentrate on educator network expansion and back-bar exclusivity renegotiation rather than price-based confrontation.
Within the integrated conglomerate tier, L'Oréal S.A. and Estée Lauder Companies Inc. exemplify divergent positioning strategies. L'Oréal occupies a position anchored in licensed salon channel control through professional-only distribution arms. Estée Lauder sits within the prestige R&D-intensive segment, representing concentrated investment in damage-recovery service protocols. Henkel AG & Co. KGaA anchors the mid-professional European manufacturing base, exemplifying cost-controlled export positioning for Schwarzkopf Professional formulations.
| Leading Market Players |
|---|
| Estée Lauder Companies Inc. |
| Amorepacific Corporation |
| L'Oréal S.A. |
| Shiseido Company Limited |
| Kao Corporation |
| Unilever PLC |
| Coty Inc. |
| Henkel AG & Co. KGaA |
| Procter & Gamble |
| Others |
Supply Flow & Price Mechanics
Eighteen-month registration timelines for new colorant precursors under EU REACH compress pricing power for contract-dependent manufacturers while amplifying margin capture for captively integrated competitors. This lead-time differential shapes how supply chain configuration translates into tiered pricing authority across professional salon channels.
Pricing Analysis
EU REACH Annex XIV substance restrictions dictate the pricing tier structure across professional color lines, separating captive-synthesis precursors at premium positioning from reformulated alternatives in mid-professional tiers. Price differentiation rests on certification grade for bond-repair actives and volume scale for back-bar exclusivity agreements. Cost compression in economy-tier shampoos is intensifying because private-label contract manufacturing expands capacity faster than branded R&D recovery. Home users through Chinese e-commerce platforms exhibit highest price sensitivity, while United States salon chains maintaining educator network relationships show lowest.
Supply Chain Analysis
Strategic stockpiling of oxidative color precursors dominates over just-in-time preferences given eighteen-month EU registration windows and intermittent isopropyl alcohol shortages. Manufacturing concentrates in Germany, the United States, and South Korea for professional-grade formulations. Raw material dependencies center on bis-aminopropyl diglycol dimaleate bond-repair actives, MEA-based lightener systems, and pH-stabilized quaternary ammonium compounds. Single-source vulnerability from toluene-2,5-diamine sulfate alternatives creates supply interruption exposure for non-integrated brands. Distribution runs through licensed beauty supply stores with verification protocols, though online retail channels accelerate fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional salon service menus are recovering cyclically as post-pandemic appointment density normalizes and scalp treatment protocols expand service revenue per visit.
For Market Incumbents: Consolidate educator network control through exclusive stylist certification programs in bond-repair application protocols, and deepen backward integration into captive synthesis of colorant precursors to neutralize EU REACH registration timeline risks from contract-dependent supply. For New Entrants and Emerging Players: Anchor in South Korean scalp-focused service culture for template protocol export to Chinese tier-one cities, and penetrate trichology-adjacent treatment systems where Western European certification scarcity limits incumbent coverage, deploying mobile payment-integrated stylist commission structures as go-to-market mechanism. For Investors and Strategic Acquirers: Long-term, this sits as a professional-channel control play because back-bar exclusivity agreements and educator network density create durable switching costs, with acquisition targets favoring mid-professional brands possessing captive raw material synthesis capabilities, and the signal to watch being California fragrance disclosure mandate progression toward probable federal extension.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Colorant Precursor Synthesis | EU REACH registration timelines favor manufacturers with captive raw material capabilities over contract-dependent competitors. |
| Educator Network Expansion | Stylist certification programs in bond-repair protocols lock in back-bar exclusivity across United States salon chains. |
| Scalp Treatment Protocol Development | Seoul's trichology service culture provides exportable templates for Chinese tier-one city salon expansion. |
| Mobile Payment Integration | South Korean stylist-commissioned replenishment models reduce friction in technician-curated home care regimens. |
| California Compliance Investment | Early fragrance disclosure adherence positions brands for probable federal extension of ingredient transparency mandates. |
Methodological Framework
The analysis maps oxidative color systems, bond-repair actives, pH-stabilized treatment protocols, and scalp-focused service menus, each validated through formulation chemists, salon chain procurement directors, licensed cosmetology educators, and professional distributor inventory managers. Primary interview findings triangulate against secondary sources including FDA cosmetic safety filings, ECHA REACH registration databases, California Proposition 65 enforcement actions, and South Korean MFDS functional claim approvals. Bottom-up volume modeling from individual product categories reconciles with top-down market sizing through cross-referencing manufacturer capacity disclosures and professional salon density estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product type, end user channel, distribution pathway, and price tier, with additional modeling across professional certification requirements and regulatory compliance status. CAGRs derive from category-level growth trajectory analysis incorporating service menu expansion rates, reformulation investment cycles, and channel migration patterns. Industry-specific forecast inputs include stylist education program rollout timelines and EU Annex XIV substance restriction implementation schedules.
Material uncertainties — regulatory ban list expansions, professional licensing reciprocity fragmentation, and at-home color kit performance convergence — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued salon service recovery and clean beauty mandate progression. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Switzerland Cosmetics Market
Beauty & Personal Care
Dry Shampoo Market
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
Face Oil Market
Beauty & Personal Care
Male Grooming Products Market
Beauty & Personal Care
Frizz Control Shampoo Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Japan Beauty Fridges Market
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
Depilatories Market
Beauty & Personal Care
Hairstyling Products Market
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
Spain Sustainable Personal Care Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Sunless Tanners Market