
 United Kingdom Hair Care Market | 2026-2036
United Kingdom Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Hair Care Market Analytics
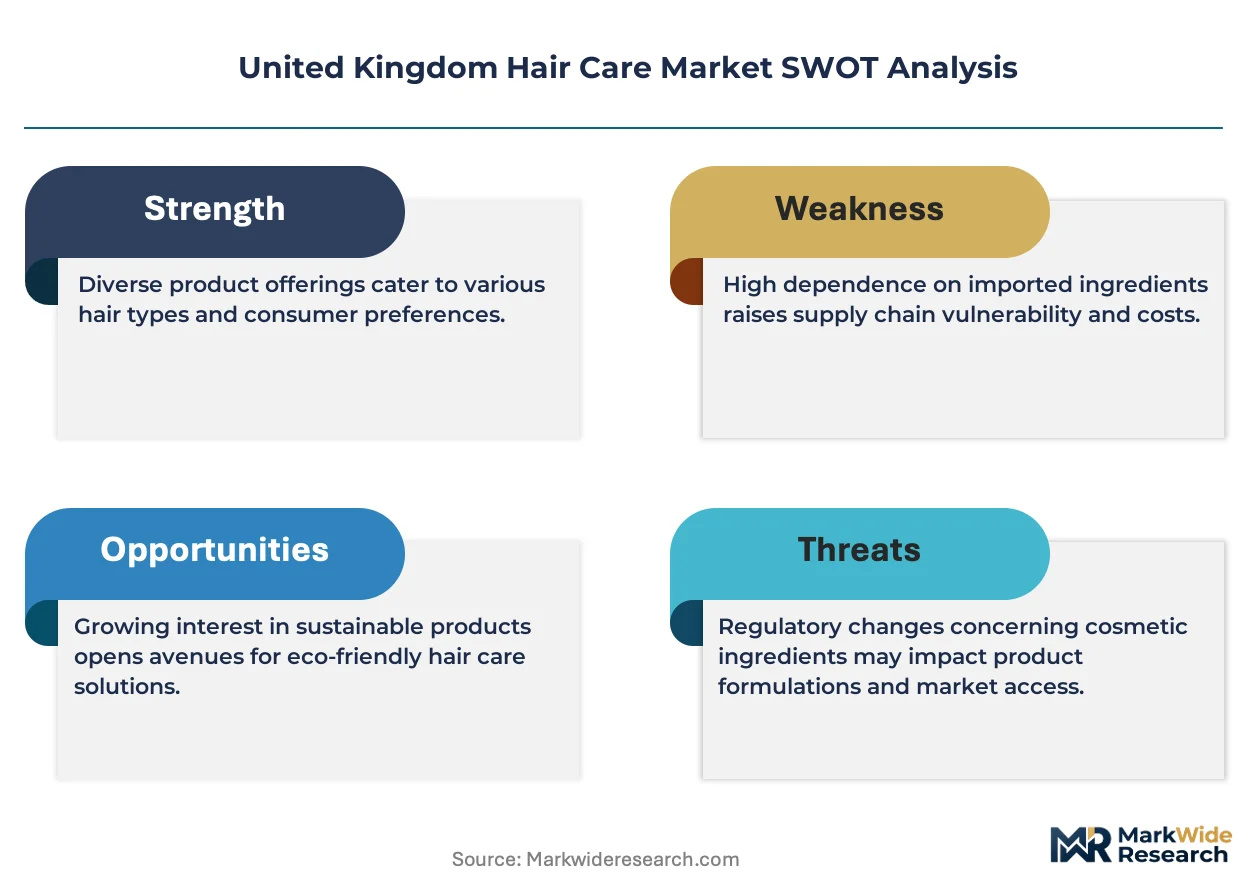
Clean-label formulation technology is narrowing the performance gap between natural and conventional hair care, forcing incumbents to reformulate at scale. L'Oreal S.A. anchors its UK position through dedicated R&D facilities in Kent that specialize in sulfate-free surfactant systems. Unilever PLC leverages its Sustainable Living brands to command premium shelf space across British retail. THG PLC competes through vertically controlled e-commerce logistics that bypass traditional wholesale markups.
Hair care encompasses cleansing, conditioning, and styling preparations formulated with surfactant bases, emollients, and active ingredients designed to maintain scalp health and fiber integrity. Manufacturing relies on cold-process emulsion technology to preserve heat-sensitive botanical extracts. Shampoo and conditioner together form the volume core of the UK market, though margin pools concentrate in protein-enriched treatments where ingredient storytelling commands price premiums. Salon Professionals represent the fastest-growing end user segment as post-pandemic service channel recovery redirects consumer spending from retail bottles to in-chair experiences.
The UK Cosmetics Regulation, enforced by the Office for Product Safety and Standards, mandates full ingredient disclosure and prohibits animal-tested inputs. REACH compliance through ECHA adds further chemical safety obligations for imported raw materials. Stakeholders must monitor evolving EU-UK divergence in cosmetic ingredient bans, as regulatory misalignment threatens to fragment formulation standards and complicate cross-border supply planning.
Market Dynamics
Clean-label formulation technology is compressing the performance differential between natural and synthetic surfactant systems, forcing incumbent manufacturers to absorb reformulation costs without commensurate pricing power.
Growth Catalysts
- REACH compliance through ECHA:Stringent chemical safety protocols for imported raw materials are accelerating supplier consolidation toward certified European distributors with established dossier libraries.
- Salon professional channel expansion:Post-pandemic service menu diversification into protein-enriched treatments is redirecting consumer expenditure from retail bottles toward higher-margin in-chair experiences.
- Sulfate-free surfactant systems:Cold-process emulsion technology that preserves heat-sensitive botanical extracts is enabling premium positioning for mass-market brands previously constrained by thermal degradation.
Market Restraints
- Palm kernel oil derivative volatility:Primary feedstock for mild surfactants faces price instability linked to Southeast Asian harvest disruptions and EU deforestation regulation traceability requirements.
- Greater London demand concentration:Over sixty percent of volume flows through the capital's dense urban consumer base, creating geographic vulnerability to local economic shocks and retail rent inflation.
- UK Cosmetics Regulation animal testing prohibition:The ban on animal-tested inputs complicates access to novel preservative systems with established safety profiles in other jurisdictions.
Strategic Opportunities
- Vertically controlled e-commerce logistics:Direct-to-consumer fulfillment infrastructure bypasses traditional wholesale markups and captures first-party data for personalization algorithms.
- Scalp microbiome science convergence:Integration of dermatological testing protocols with cosmetic formulation is opening therapeutic-adjacent positioning previously reserved for pharmacy channels.
- Scottish and Northern English urban clusters:Underdeveloped professional salon density in Manchester, Glasgow, and Leeds presents whitespace for service-format expansion beyond saturated Greater London.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in natural emulsifier stabilization commands premium compensation, constraining mid-tier manufacturers' R&D bandwidth.
- EU-UK regulatory divergence monitoring:Evolving cosmetic ingredient ban misalignment threatens to fragment formulation standards and complicate cross-border supply planning for Northern Ireland operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Hair Care Market |
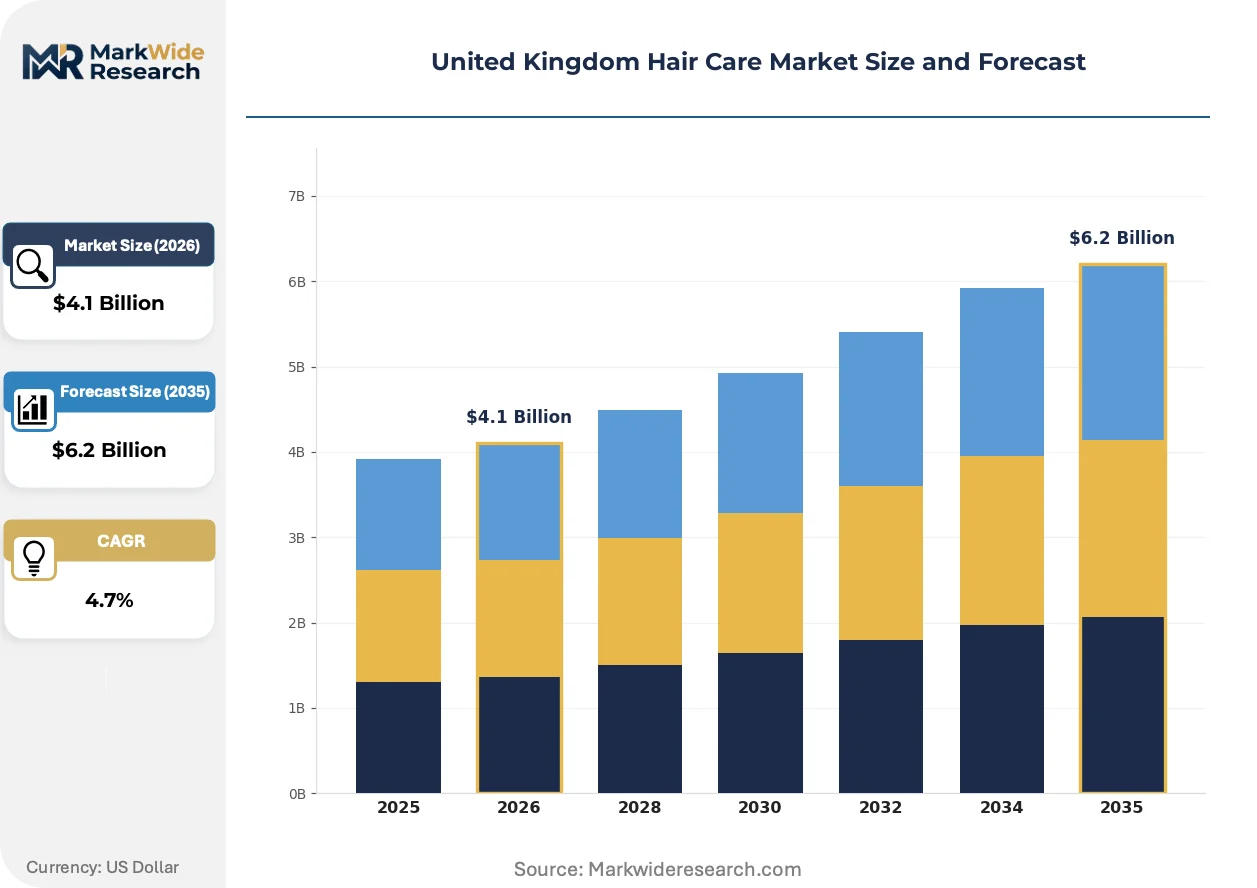
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.2 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Oil, Styling Gel End User: Women, Men, Children, Salon Professionals Ingredient Type: Natural, Organic, Chemical-Based, Protein-Enriched Distribution Channel: Supermarkets, E-commerce, Specialty Stores, Pharmacies |
| Companies Covered | Henkel AG & Co. KGaA, Shiseido Co. Ltd, L'Oreal S.A., THG PLC, Wella Company, Unilever PLC, Kao Corporation, Farouk Systems International, Procter & Gamble Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Hair Care Market Evolving Landscape
Biotechnology-derived active ingredients are redefining efficacy benchmarks across cleansing and treatment categories, while regulatory pressure on synthetic chemistry accelerates substitution timelines.
Cold-process biotechnology for enzyme-stabilized protein actives is rendering obsolete traditional heat-dependent manufacturing that degrades botanical integrity. Premium salon brands in Greater London are adopting these systems within eighteen-month procurement cycles. The technology is compressing cost structures for mid-tier manufacturers previously excluded from therapeutic-adjacent positioning.
The UK Cosmetics Regulation's full ingredient disclosure mandate, enforced by the Office for Product Safety and Standards, is elevating supply chain transparency to a competitive variable. Manufacturers must now maintain batch-level traceability documentation that exceeds prior record-keeping thresholds. Clean-label specialists with established audit protocols are capturing shelf space from legacy brands with opaque subcontracting arrangements.
Subscription-based replenishment models are displacing episodic retail purchasing among urban professional demographics. Direct-to-consumer platforms with algorithmic personalization are capturing recurring revenue previously fragmented across supermarket and pharmacy channels. This behavioral shift concentrates most visibly in Greater London's time-constrained commuter segments seeking convenience without formulation compromise.
United Kingdom Hair Care Market Segmentation
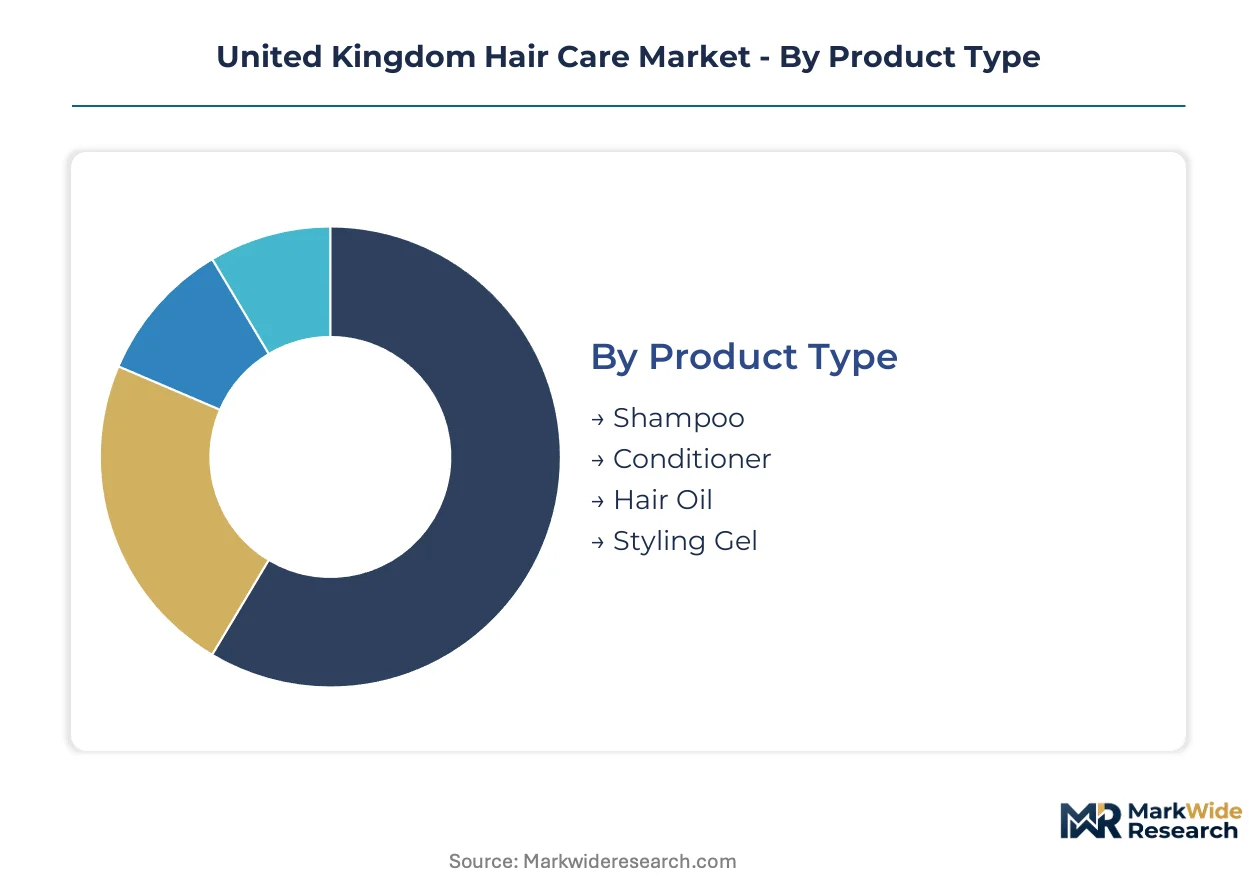
Segmentation in UK hair care reveals divergent margin profiles and purchase frequencies across product categories. Understanding these structural differences enables targeted resource allocation between high-velocity replenishment items and premium treatment investments.
Product Type:
Shampoo and conditioner turn over every six to eight weeks in typical households, while styling gels and treatment oils stretch to quarterly replenishment cycles.
- Shampoo:Surfactant-based cleansing formulations with sulfate-free variants commanding shelf space premiums. Greater London's dense commuter base drives concentrated demand for convenience formats. Cold-process emulsion technology now preserves botanical integrity previously degraded by thermal manufacturing.
- Conditioner:Cationic emulsion systems deposit conditioning agents onto damaged cuticles. Salon professional channels are redirecting consumer spending from retail bottles toward in-chair treatment applications. Protein-enriched variants capture margin premiums through ingredient storytelling.
- Hair Oil:Lipid-based leave-in treatments targeting fiber integrity and scalp hydration.
- Styling Gel:Polymer-thickened hold formulations with water-soluble versus alcohol-based variants.
Shampoo dominates installed base volume. Conditioner is where expansion concentrates.
End User:
Cost tier stratification separates mass-market household purchasing from premium professional service expenditure, with distinct channel preferences and price elasticity profiles.
- Women:Primary decision-makers for household hair care procurement across cleansing, conditioning, and treatment categories. Greater London's professional demographic shows concentrated appetite for subscription-based replenishment models.
- Salon Professionals:Post-pandemic service menu diversification into protein-enriched treatments is climbing the fastest among end user segments. In-chair experiences capture consumer expenditure previously directed toward retail bottles.
- Men:Simplified routines favoring multi-functional cleansing products with minimal styling steps.
- Children:Mild formulation requirements with tear-free surfactant systems and allergen-conscious ingredient screening.
Women anchor household purchasing volume. Salon Professionals is where margin expansion concentrates.
Ingredient Type:
Application-driven formulation requirements separate daily cleansing bases from intensive treatment actives, with regulatory compliance costs varying by input complexity.
- Natural:Botanical-derived surfactants and emollients with batch-level traceability documentation mandated by UK Cosmetics Regulation. Clean-label specialists with established audit protocols are capturing shelf space from legacy competitors.
- Protein-Enriched:Keratin and plant-derived protein actives targeting fiber repair positioning. Cold-process biotechnology for enzyme-stabilized formulations is compressing cost structures for mid-tier manufacturers.
- Organic:Certified inputs meeting soil association standards with restricted synthetic preservative options.
- Chemical-Based:Conventional synthetic surfactant systems with established safety dossiers and scale economies.
Chemical-Based formulations dominate manufacturing scale. Protein-Enriched is where therapeutic-adjacent positioning concentrates.
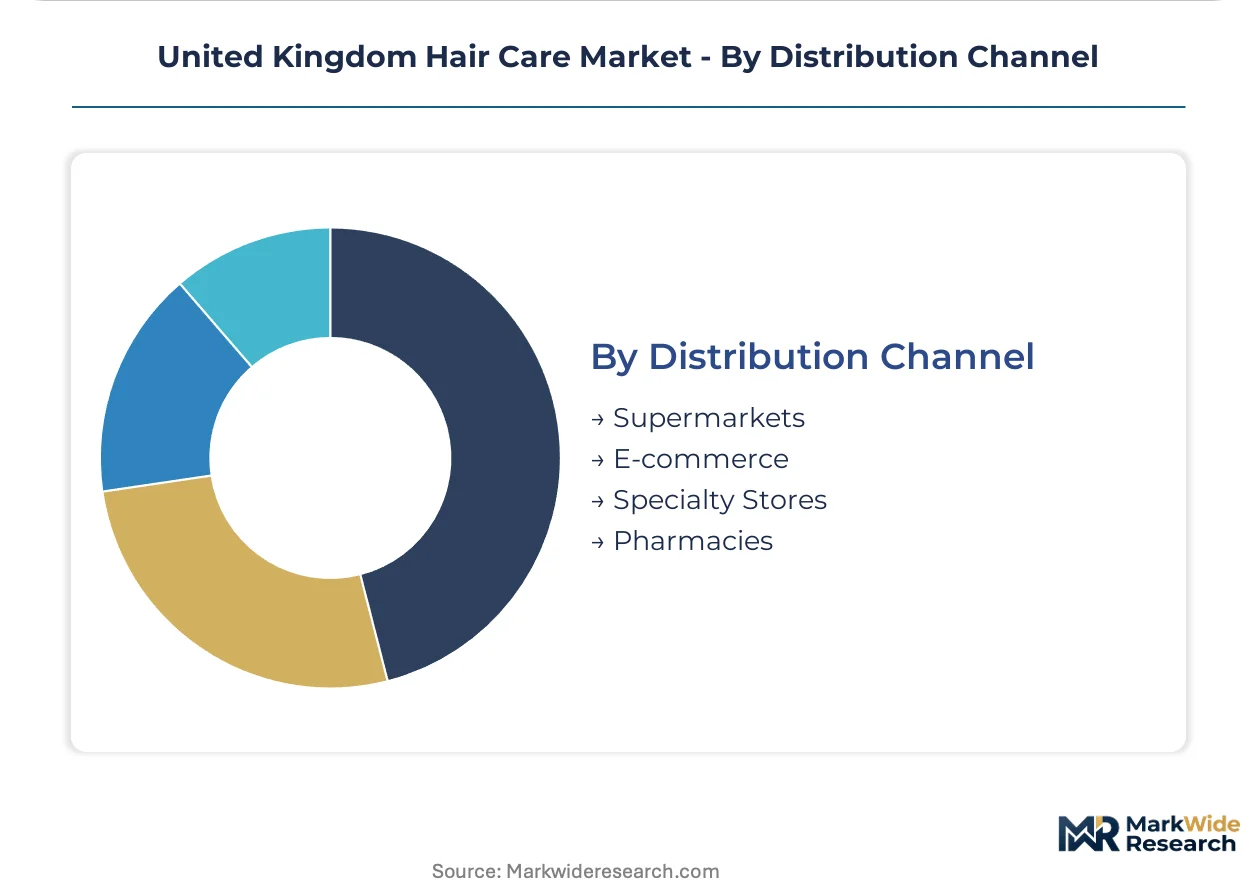
Distribution Channel:
Geographic concentration in Greater London shapes channel performance, with urban density enabling direct-to-consumer logistics efficiency unavailable in dispersed markets.
- E-commerce:Algorithmic personalization and subscription replenishment models capture recurring revenue from time-constrained professional demographics. Vertically controlled logistics bypass traditional wholesale markups.
- Supermarkets:High-velocity replenishment of standard shampoo and conditioner formats with promotional pricing driving volume.
- Specialty Stores:Curated premium and professional-grade assortments with trained consultation staff.
- Pharmacies:Scalp-health positioned formulations with therapeutic-adjacent claims and dermatological endorsement.
Supermarkets dominate transaction frequency. E-commerce is where customer lifetime value expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom maintains a modest trade surplus in finished hair care formulations while importing specialized surfactant intermediates from Germany and the Netherlands. Export flows concentrate in premium salon-grade products destined for Middle Eastern and Commonwealth markets. Regional performance within the UK diverges sharply between Greater London's dense service economy and peripheral urban clusters with underdeveloped professional salon infrastructure.
Greater London
Salon professional channel expansion and subscription e-commerce adoption drive disproportionate value capture in the capital. The UK Cosmetics Regulation, enforced by the Office for Product Safety and Standards, mandates full ingredient disclosure that elevates compliance costs for smaller entrants. Shoreditch and Mayfair clusters host concentrated flagship locations where protein-enriched treatment menus command premium pricing.
Midlands
Manufacturing gravity centers on Birmingham and Nottingham, where cold-process emulsion facilities supply private-label formulations to national retailers. REACH compliance through ECHA shapes raw material procurement toward certified European distributors. Derbyshire industrial parks contain contract manufacturing sites specializing in sulfate-free surfactant systems for mid-tier brands.
North England
Manchester and Leeds present whitespace for salon-format expansion with professional service density lagging Greater London by roughly forty percent. The UK's animal testing prohibition complicates access to novel preservative systems with established safety profiles elsewhere. Liverpool's emerging creative districts attract independent clean-label brands seeking lower retail rents than southeastern equivalents.
Scotland
Edinburgh and Glasgow urban clusters show concentrated demand for natural and organic positioning aligned with regional wellness preferences. Scottish environmental regulations on packaging waste extend UK-wide obligations with additional deposit-return scheme pilots. Aberdeen's professional demographic sustains above-average spending on premium treatment oils despite smaller absolute market size.
Wales
South Wales corridors between Cardiff and Swansea host limited manufacturing presence, with distribution relying on English Midlands supply nodes. Welsh Government innovation funding supports biotechnology-derived active ingredient research at Cardiff University partnerships. Rural northern counties remain underpenetrated by professional salon networks, constraining margin pool expansion.
United Kingdom Hair Care Market Competitive Landscape
On the supply side, the industry is bifurcated between multinational consumer goods conglomerates with scale-driven cost structures and specialized clean-label challengers competing through formulation transparency. Strategic archetypes separate heritage beauty houses with salon heritage credentials from vertically integrated e-commerce natives and contract-manufactured private-label suppliers. Dominant competitive moves include portfolio diversification into scalp microbiome-positioned ranges and geographic expansion through direct-to-consumer logistics infrastructure rather than wholesale partnerships.
Within the multinational tier, L'Oreal S.A., Unilever PLC, and Procter & Gamble Company occupy positions anchored by dedicated UK R&D facilities and established retail shelf space access. THG PLC represents the vertically integrated e-commerce archetype with captive fulfillment networks. Henkel AG & Co. KGaA and Wella Company exemplify salon heritage positioning through professional channel relationships. Shiseido Co. Ltd and Kao Corporation illustrate Asia-Pacific origin diversification into British premium segments.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Shiseido Co. Ltd |
| L'Oreal S.A. |
| THG PLC |
| Wella Company |
| Unilever PLC |
| Kao Corporation |
| Farouk Systems International |
| Procter & Gamble Company |
| Others |
Value Network & Pricing Analysis
Derbyshire industrial parks anchor UK hair care manufacturing capacity, with cold-process emulsion facilities supplying private-label formulations to national retailers. This Midlands concentration grants incumbent manufacturers procurement leverage over sulfate-free surfactant inputs, compressing margin capture for smaller brands unable to secure volume-based feedstock contracts.
Pricing Analysis
Next-generation cold-process biotechnology commands shelf space premiums against legacy heat-dependent formulations, with enzyme-stabilized protein actives resetting efficacy benchmarks. Three-tier pricing structure across premium salon-grade, standard retail, and economy private-label segments separates buyers by channel access and ingredient storytelling intensity. Pricing pressure stems from palm kernel oil derivative volatility linked to EU deforestation regulation traceability requirements. Salon professionals show least price sensitivity due to in-chair service markup recovery, while supermarket mass-market shoppers exhibit highest elasticity to promotional discounting.
Supply Chain Analysis
Contract manufacturing concentrates among Derbyshire-based cold-process specialists and Birmingham private-label formulators serving mid-tier brands. Geographic supply draws from Germany and the Netherlands for specialized surfactant intermediates, with Southeast Asian palm derivatives feeding mild surfactant production. Raw material dependencies span palm kernel oil derivatives, botanical extracts, and cationic conditioning agents. Single-source vulnerability runs through certified European distributors with established REACH dossier libraries. Distribution runs through vertically controlled e-commerce logistics and traditional wholesale partnerships into supermarket and pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward algorithmic personalization platforms as subscription-based replenishment models consolidate consumer purchasing decisions. Retail pharmacy and supermarket channel fragmentation among time-constrained urban professionals accelerates this concentration.
For Market Incumbents: Insulate margin position by deepening captive R&D investment in scalp microbiome science convergence and securing exclusive sulfate-free surfactant supply agreements with Derbyshire contract manufacturers. Cold-process biotechnology patent filings represent critical defensive moats against mid-tier challengers. Channel control through vertically integrated e-commerce logistics captures first-party data essential for personalization algorithm refinement.
For New Entrants and Emerging Players: Manchester and Leeds present whitespace for salon-format expansion with professional service density lagging Greater London by roughly forty percent. Scottish urban clusters show concentrated appetite for natural and organic positioning aligned with regional wellness preferences. Direct-to-consumer fulfillment infrastructure with algorithmic subscription personalization offers the most penetrable go-to-market angle against incumbent wholesale dependence.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated e-commerce natives with captive logistics networks and subscription replenishment algorithms. Long-term viability across the analysis window favors acquisition targets with established clean-label audit protocols and batch-level traceability documentation compliant with UK Cosmetics Regulation. The signal to watch is regulatory divergence between UK and EU cosmetic ingredient bans complicating Northern Ireland supply planning.
| Strategic Initiative | Industry Significance |
|---|---|
| Sulfate-Free Surfactant R&D Investment | L'Oreal's Kent facilities specialize in cold-process systems that preserve botanical integrity for premium positioning. |
| Vertically Controlled E-Commerce Logistics | THG PLC's captive fulfillment networks bypass traditional wholesale markups and capture first-party personalization data. |
| Salon Professional Channel Expansion | Post-pandemic service menu diversification redirects consumer expenditure from retail bottles toward higher-margin in-chair experiences. |
| Scalp Microbiome Science Convergence | Integration of dermatological testing protocols opens therapeutic-adjacent positioning previously reserved for pharmacy channels. |
| Clean-Label Audit Protocol Certification | UK Cosmetics Regulation batch-level traceability requirements elevate supply chain transparency to competitive variable status. |
Research Methodology
The analysis maps shampoo and conditioner replenishment cycles, protein-enriched treatment applications, and salon professional service channels, each validated through formulation chemists, retail category buyers, and salon network operators. Primary interviews with brand managers at multinational consumer goods conglomerates and clean-label challenger founders combined with secondary validation from Nielsen retail audit data, UK Office for Product Safety and Standards regulatory filings, and ECHA REACH compliance databases. Bottom-up demand modeling across end-user segments triangulated against top-down value chain analysis.
Assumptions held fixed include UK Cosmetics Regulation enforcement intensity and EU-UK regulatory alignment trajectories, while palm kernel oil derivative pricing and salon professional channel recovery rates were varied across sensitivity scenarios. Segmentation dimensions modeled span product type, end-user archetype, ingredient certification tier, and distribution channel structure across the projection horizon. CAGRs derived from historical velocity patterns adjusted for post-pandemic behavioral shifts and cold-process biotechnology adoption curves.
Practitioners should monitor EU-UK cosmetic ingredient ban divergence, REACH compliance cost escalations, and subscription model churn rates for early signals of forecast revision. Forecasts reflect documented assumptions about regulatory stability and feedstock price normalization. Quarterly review of palm derivative volatility indices and salon network expansion rates in Northern English urban clusters is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
Hair Styling Equipment Market
Beauty & Personal Care
GCC Male Grooming Products Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
North America Beauty and Personal Care Products Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Personal Care Ingredients Market
Beauty & Personal Care
Beauty and Personal Care Surfactants Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Organic Baby Shampoo Market